
 Disodium Inosinate Market | 2026-2036
Disodium Inosinate Market Size, Share, and Industry Trends Forecast 2026-2036
Disodium Inosinate Market Analysis
Ingredient-as-a-service contracting is pivoting how disodium inosinate suppliers monetize their output, shifting from bulk commodity sales to tailored flavor-system subscriptions with embedded technical support. Ajinomoto Co., Inc. leverages its century-long fermentation expertise to anchor premium positioning in nucleotide-based flavor enhancers. Fufeng Group Company Limited sustains cost leadership through captive starch-to-MSG verticality that feeds downstream inosinate synthesis. Vedan International (Holdings) Limited competes on Southeast Asian channel density, while Meihua Holdings Group Co., Ltd. dominates Chinese domestic volume through integrated bioreactor scale.
Disodium inosinate is the sodium salt of inosinic acid, typically manufactured via microbial fermentation of carbohydrate feedstocks followed by enzymatic phosphorylation and neutralization, yielding a white crystalline powder with E number E631 that potentiates glutamate-driven umami perception at concentrations below threshold detection. The ingredient serves primarily as a synergistic flavor intensifier in processed foods, enabling sodium reduction while preserving sensory satisfaction. Powder formulations lead volume due to handling efficiency in industrial seasoning blends, while liquid formats gain traction in beverage applications requiring homogeneous dispersion without dissolution steps. Food additive classifications command the largest application share, though nutraceuticals represent the fastest-expanding margin pool as functional food brands seek provenance-transparent excipients.
FDA GRAS status and EPA fermentation effluent guidelines govern US market access, while China's NMPA and SAMR enforce GB 1886.97 purity specifications that determine import eligibility. EFSA's re-evaluation of nucleotide additives under EU food improvement agent frameworks shapes reformulation timelines for European-exporting manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions on combined nucleotide limits in infant and follow-on formulas, as this threshold variation will determine where capacity investments achieve fastest payback.
Market Dynamics
Clean-label reformulation pressure from East Asian processed food manufacturers is compressing formulation cycles, forcing nucleotide suppliers to embed technical service capabilities directly into supply agreements rather than selling commodity powders alone.
Growth Catalysts
- GB 1886.97 compliance upgrades:China's SAMR enforcement of revised purity specifications for food additives is accelerating facility modernization among domestic manufacturers seeking export eligibility.
- Umami-forward cuisine proliferation:Southeast Asian instant noodle and seasoning manufacturers are expanding nucleotide inclusion rates to meet sensory benchmarks without sodium escalation.
- Fermentation yield optimization:Advances in CRISPR-edited Corynebacterium strains are reducing carbohydrate feedstock intensity per unit inosinate output.
Market Restraints
- Starch feedstock volatility:Corn and tapioca price swings in key producing regions directly compress fermentation economics for inosinate manufacturers without captive starch supply.
- Shandong-Hebei supply concentration:Over half of global disodium inosinate fermentation capacity sits within 300 kilometers in eastern China, creating single-point vulnerability to regional environmental enforcement actions.
- Yeast extract substitution:Natural autolyzed yeast extracts carrying inherent nucleotides are displacing pure inosinate in premium clean-label segments despite higher unit cost.
Strategic Opportunities
- Indian FSSAI additive approvals:Pending revisions to India's food additive positive lists could unlock formal nucleotide usage in processed foods currently restricted to natural sources only.
- Plant-based meat excipient demand:Alternative protein formulators are adopting nucleotide synergists to mask off-notes from legume and fungal protein bases without MSG dependency.
- EU Green Deal biomanufacturing incentives:Fermentation-based production routes qualify for subsidized capital under circular economy frameworks targeting reduced petrochemical dependency.
Industry Challenges
- Phosphorylation enzyme supply security:Specialist kinase procurement for downstream processing faces lead time extension from contract fermentation providers serving multiple nucleotide product lines.
- Infant formula nucleotide caps:Divergent maximum permitted levels between EU, US, and Chinese regulations force manufacturers to maintain separate inventory lots for export versus domestic sale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disodium Inosinate Market |
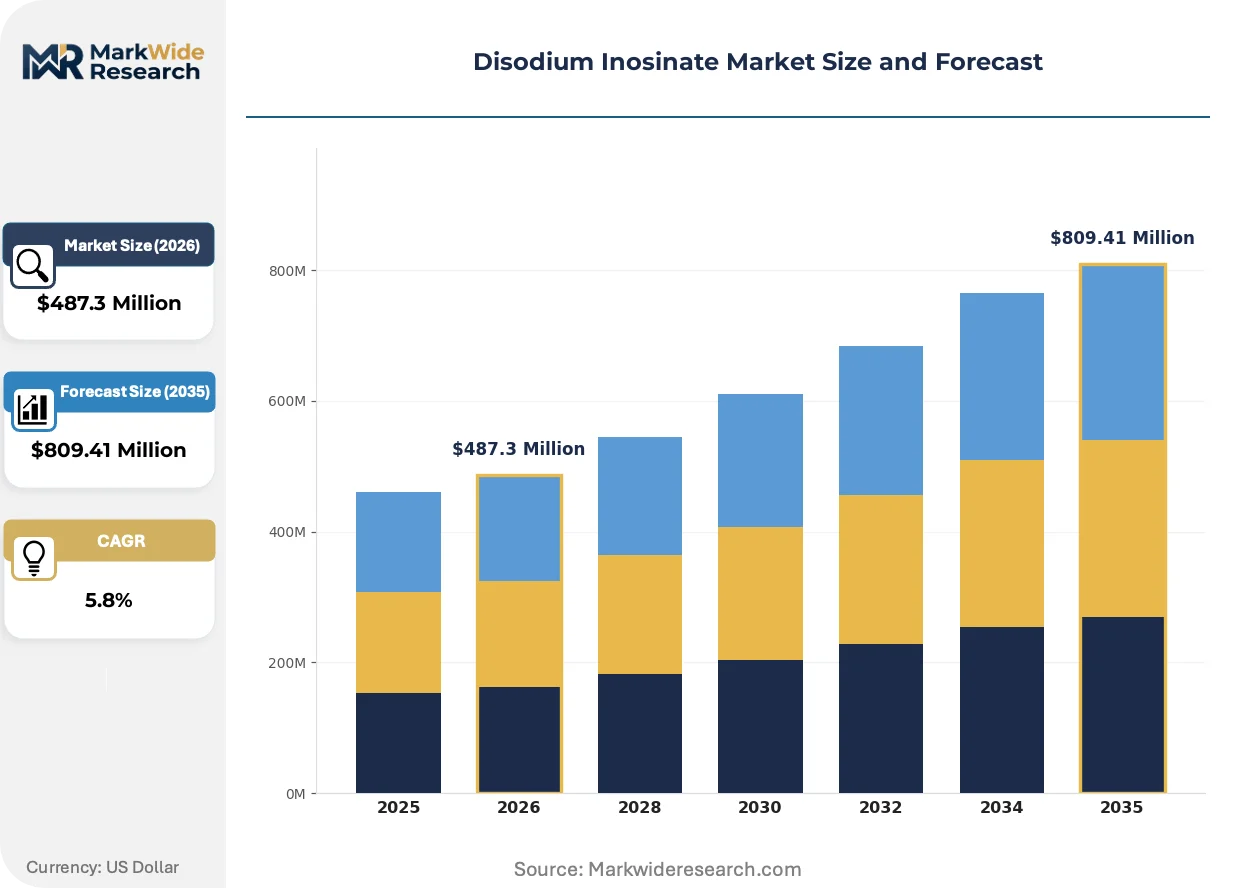
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Tablets, Liquid Application: Food Additive, Flavor Enhancer, Seasoning, Nutraceuticals End User: Food Processing, Beverage Industry, Pharmaceutical Companies, Restaurants Distribution Channel: Online Retail, Direct Sales, Distributor, Supermarkets |
| Companies Covered | Foodchem International Corporation, Huanghua Ouhai Biology Co., Ltd., Ajinomoto Co., Inc., Roquette Frères, Lian Company Limited, Fufeng Group Company Limited, Meihua Holdings Group Co., Ltd., Vedan International (Holdings) Limited, Cheil Jedang Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disodium Inosinate Market Emerging Trajectories
Bioprocess intensification and regulatory harmonization efforts are converging to reshape how nucleotide additives reach formulated food products, with implications for capital deployment and technical service structures.
Continuous fermentation systems with real-time metabolite monitoring are modularizing production economics for disodium inosinate manufacturers. Mid-scale processors in Jiangsu and Zhejiang provinces are retrofitting batch tanks with perfusion modules to reduce downtime between harvest cycles. This hardware transition is compressing minimum efficient scale thresholds and enabling distributed production closer to seasoning compounders.
EFSA's ongoing re-evaluation of nucleotide food improvement agents under consolidated additive frameworks is tightening toxicological data requirements for European market access. Manufacturers must submit renewed safety dossiers covering combined intake scenarios with glutamates and guanylates. Asian exporters to EU markets are front-loading chronic exposure studies to avoid formulation exclusion during transition periods.
Ingredient-as-a-service contracting is displacing spot purchasing for nucleotide supplies among multinational seasoning houses. Technical support subscriptions covering formulation optimization and regulatory documentation are bundling with volume commitments. This shift is most visible in Japanese and South Korean markets where processor technical teams prefer embedded supplier expertise over in-house nucleotide specialization.
Disodium Inosinate Market Segmentation
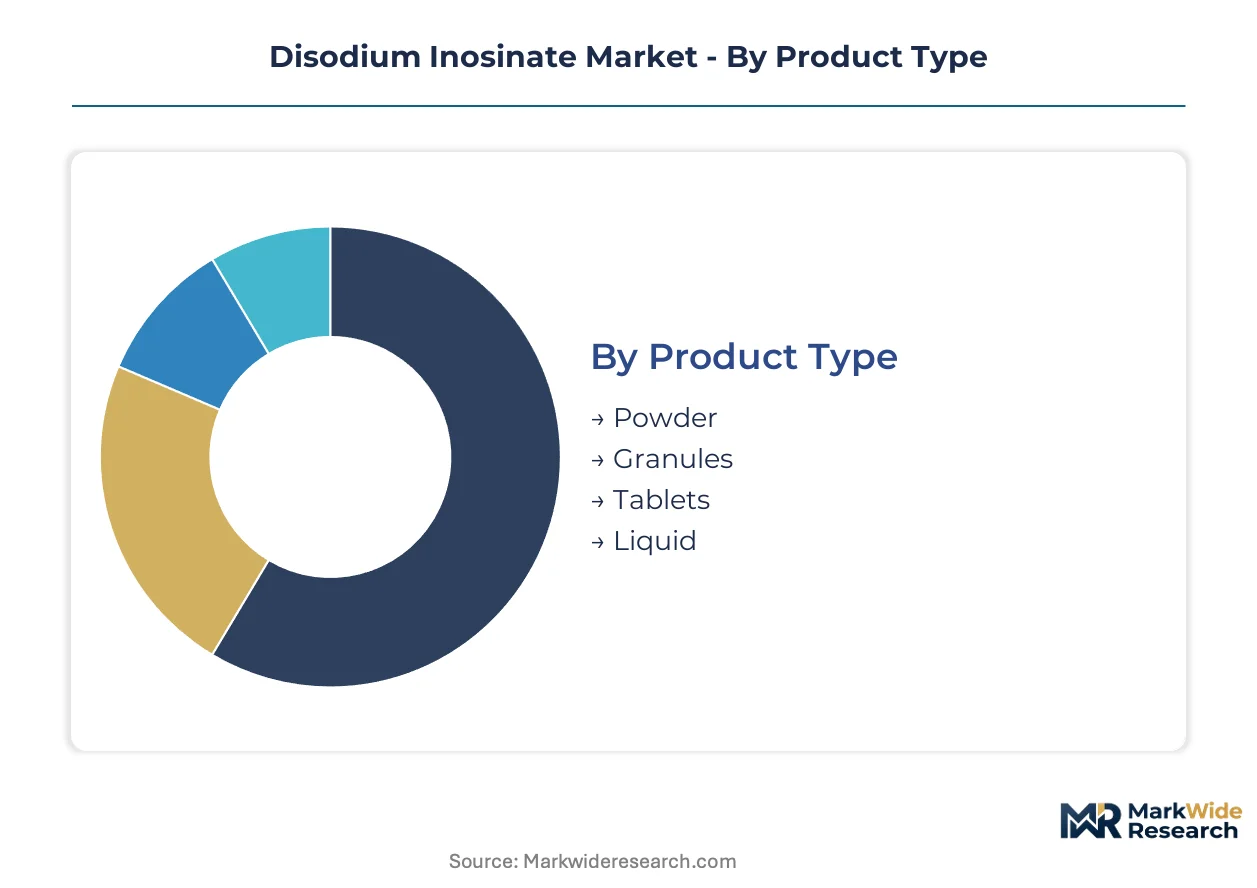
Disodium inosinate suppliers structure their portfolios around handling characteristics, regulatory classifications, and channel access requirements. Segmentation decisions determine which fermentation outputs receive downstream processing investment versus commodity sale.
Product Type:
Upgrade cycles in seasoning manufacturing are pushing format innovation as compounders seek dust-free handling and instant solubility without capital-intensive dissolution equipment.
- Powder:Fine crystalline form dominates industrial seasoning blends due to flowability and uniform dispersion in dry mixes. East Asian instant noodle manufacturers specify powder grades for their automated seasoning packet lines.
- Liquid:Aqueous solutions eliminate dissolution steps for beverage applications and wet marinades. Southeast Asian sauce compounders are adopting liquid nucleotide systems to reduce processing time in high-throughput facilities.
- Granules:Agglomerated particles reduce dust exposure during manual handling in smaller processing operations.
- Tablets:Compressed units serve laboratory and pharmaceutical excipient applications requiring precise dosing.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid.
Application:
Cost tier differentiation separates commodity-grade nucleotide sales from premium-positioned functional food ingredients requiring extended documentation packages.
- Food Additive:E631-classified ingredient serves processed food manufacturers seeking GRAS-equivalent status for export markets. China's GB 1886.97 compliance requirements determine which fermentation batches qualify for this classification.
- Flavor Enhancer:Synergistic pairing with glutamates enables sodium reduction in savory formulations. Japanese and South Korean seasoning houses specify nucleotide ratios for umami intensity targets without MSG dependency.
- Seasoning:Direct incorporation into compound blends for instant noodles, snacks, and prepared meals.
- Nutraceuticals:Purified grades function as excipients in functional food matrices requiring provenance transparency and allergen documentation.
Food Additive commands the largest shipment volumes; Nutraceuticals is climbing the fastest on margin expansion.
End User:
Customer-type fragmentation requires suppliers to maintain separate technical service teams for industrial compounders versus pharmaceutical quality systems.
- Food Processing:Large-scale manufacturers of savory snacks, ready meals, and processed meats drive bulk nucleotide consumption with formulation support contracts.
- Beverage Industry:Sports drink and savory beverage innovators adopt nucleotide synergists for flavor masking in protein-fortified formulations.
- Pharmaceutical Companies:Excipient-grade nucleotides require USP or EP compliance for tablet and capsule applications.
- Restaurants:Commercial kitchens and chain operators source through foodservice distributors for centralized sauce production.
Food Processing absorbs the majority of volume placements; Beverage Industry shows the steepest expansion trajectory.
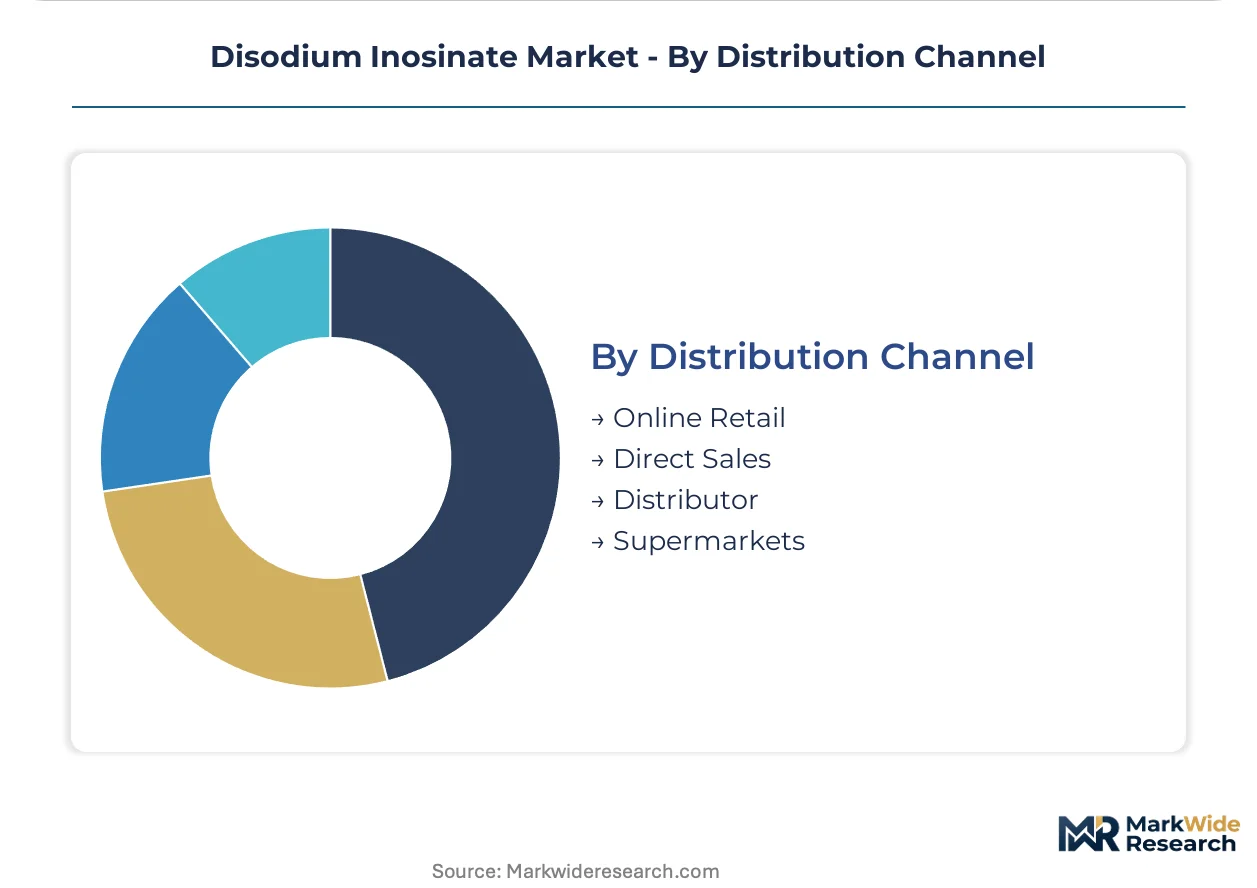
Distribution Channel:
Supply concentration in eastern China shapes how nucleotide outputs reach end users across different geographies and order scales.
- Direct Sales:Long-term supply agreements with multinational seasoning houses bundle technical service and regulatory documentation. Ajinomoto and Fufeng Group leverage direct relationships to anchor volume commitments.
- Distributor:Regional intermediaries serve mid-scale compounders lacking procurement specialization in nucleotide specifications. Southeast Asian channel density depends on distributor technical capabilities for local formulation support.
- Online Retail:E-commerce platforms serve small-batch purchasers and research institutions requiring kilogram-scale quantities.
- Supermarkets:Limited retail presence for consumer-facing seasoning blends containing declared nucleotide ingredients.
Direct Sales captures the dominant volume share; Online Retail is gaining share fastest among emerging formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China hosts the majority of fermentation capacity while Japan and South Korea absorb premium nucleotide volumes for seasoning manufacturing. This production-consumption asymmetry shapes trade flows and technical service investments across Asia-Pacific.
China
Shandong and Hebei provinces concentrate over half of global disodium inosinate fermentation capacity within a 300-kilometer radius. SAMR enforces GB 1886.97 purity specifications that determine which batches qualify for food additive classification versus technical grades. Zhejiang and Jiangsu processors are retrofitting batch tanks with perfusion modules to reduce harvest cycle downtime.
Japan
Instant noodle and seasoning manufacturers drive nucleotide demand for sodium-reduced umami formulations. METI oversees food additive safety assessments that align with international Codex standards for export compatibility. Kanto region compounders specify nucleotide-to-glutamate ratios for precise sensory targeting without MSG dependency.
South Korea
Savory snack and sauce producers expand nucleotide inclusion to meet clean-label reformulation benchmarks. MFDS regulates combined nucleotide limits in processed foods under food additive positive list frameworks. Seoul-based seasoning houses prefer ingredient-as-a-service contracts bundling technical support with volume commitments.
United States
Processed meat and savory beverage formulators adopt nucleotide synergists for flavor masking in protein-fortified applications. FDA GRAS status governs market access while EPA fermentation effluent guidelines shape production economics for domestic manufacturers. Midwest seasoning compounders source through direct supply agreements with Asian fermentation houses.
Germany
Plant-based meat innovators utilize nucleotide additives to mask off-notes from legume and fungal protein bases. EFSA re-evaluates nucleotide food improvement agents under consolidated additive frameworks requiring renewed toxicological dossiers. Bavarian food technology clusters front-load chronic exposure studies to maintain EU market access during regulatory transitions.
Disodium Inosinate Market Vendor Landscape
Capital-heavy fermentation operators compete with asset-light formulation specialists for downstream value capture. The vendor base splits between integrated starch-to-nucleotide producers and toll manufacturers serving multiple product lines. Three archetypes dominate: captive feedstock integrators, regional channel specialists, and premium-grade purity merchants. Capacity expansion and ingredient-as-a-service contracting represent the dominant competitive vectors as technical support bundling displaces spot commodity sales.
Within the integrated fermentation tier, Ajinomoto Co., Inc. and Fufeng Group Company Limited occupy positions anchored by century-long bioprocess expertise and captive starch verticality respectively. Vedan International (Holdings) Limited exemplifies the regional channel density archetype, while Meihua Holdings Group Co., Ltd. represents scale-driven domestic volume leadership. These three companies illustrate how geographic clustering and feedstock control determine competitive positioning in nucleotide additive supply.
| Leading Market Players |
|---|
| Foodchem International Corporation |
| Huanghua Ouhai Biology Co., Ltd. |
| Ajinomoto Co., Inc. |
| Roquette Frères |
| Lian Company Limited |
| Fufeng Group Company Limited |
| Meihua Holdings Group Co., Ltd. |
| Vedan International (Holdings) Limited |
| Cheil Jedang Corporation |
| Others |
Supply Flow & Price Mechanics
Captive starch-to-nucleotide integration anchors both supply security and pricing power for dominant fermentation operators in eastern China. Fufeng Group and Meihua Holdings leverage in-house corn processing to buffer margin compression when tapioca and maize prices swing, while toll-dependent manufacturers absorb feedstock volatility directly.
Pricing Analysis
Margin tightening in standard-grade powder reflects yeast extract substitution pressure from premium clean-label formulators. Three-tier pricing structure across pharmaceutical-grade, food-additive, and technical specifications separates batches by GB 1886.97 compliance and EFSA dossier completeness. Instant noodle manufacturers in Japan and South Korea show lowest price sensitivity due to embedded technical service contracts, while Southeast Asian sauce compounders drive hardest volume negotiations.
Supply Chain Analysis
China's evolving GB standards for domestic-content verification in food additive procurement are reshaping import sourcing strategies. Fermentation capacity concentrates in Shandong, Hebei, and Jiangsu provinces, drawing from corn starch, tapioca flour, and specialist kinase enzymes. Single-point vulnerability to regional environmental enforcement actions threatens continuity. Distribution runs through direct supply agreements with multinational seasoning houses rather than spot commodity markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous fermentation systems with real-time metabolite monitoring are displacing legacy batch tank operations, compressing minimum efficient scale thresholds and enabling distributed production economics.
For Market Incumbents: To counter yeast extract displacement in premium segments, deepen captive feedstock integration through Jiangsu and Zhejiang facility retrofits, and front-load EFSA chronic exposure studies to defend EU market access during regulatory transition periods. For New Entrants and Emerging Players: Launch via ingredient-as-a-service subscriptions bundling technical support with volume commitments, targeting Indian FSSAI approval timelines for nucleotide positive-list expansion, and prioritizing plant-based meat excipient partnerships over commodity seasoning sales. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale fermentation operators with perfusion module installations and pending regulatory dossiers. Long-term viability hinges on CRISPR-edited strain IP and regional channel density. Watch for Indian FSSAI additive list revisions as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starch Supply | Fufeng Group's captive corn processing insulates margins from Shandong-Hebei feedstock volatility. |
| Continuous Fermentation Retrofit | Jiangsu and Zhejiang processors reduce harvest cycle downtime through perfusion module adoption. |
| Regulatory Dossier Front-Loading | Asian exporters to EU markets submit renewed EFSA safety studies before framework transition deadlines. |
| Ingredient-as-a-Service Launch | Japanese and South Korean seasoning houses embed supplier technical expertise via subscription contracts. |
| Plant-Based Protein Partnership | Alternative protein formulators adopt nucleotide synergists to mask legume and fungal off-notes. |
Methodological Framework
Document review covered SAMR regulatory filings, GB standards documentation, EFSA additive re-evaluation records, and fermentation industry trade data, complemented by interviews with plant managers at Shandong and Hebei fermentation facilities, procurement leads at Japanese and South Korean seasoning manufacturers, technical R&D directors at nucleotide compounders, and regulatory affairs specialists navigating EU food improvement agent frameworks. Secondary validation drew from customs export records, NMPA food additive registrations, and SEC disclosures from listed fermentation operators. Bottom-up capacity assessments and top-down consumption estimates were triangulated against reported shipment volumes.
Segment-level outputs across the projection horizon reflect modeled interactions between product format, application grade, and end-user procurement structure. The analytical framework incorporated fermentation yield curves, GB 1886.97 compliance batch qualification rates, and ingredient-as-a-service contract penetration by geography. CAGRs were derived from weighted capacity expansion timelines and consumption intensity benchmarks in instant noodle, savory snack, and plant-based meat formulations.
Starch feedstock price volatility, unanticipated environmental enforcement actions in eastern China, and divergent nucleotide caps in infant formula regulations are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on regulatory harmonization timelines and CRISPR strain adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Feed Acidulants Market
Additives
Monocalcium Phosphate Market
Additives
Global Low-Profile Additive Market
Additives
1,4 Butanediol Derivatives Market
Additives
Polyols and Sorbitols Products Market
Additives
Foundry Additives Market
Additives
Carboxymethylcellulose (CMC) Market
Additives
Mycotoxin Binders Market
Additives
Printing Ink Additives Market
Additives
Anti-Wear Additives Market
Additives
Global Propyl Acetate Market
Additives
Polysorbate-80 Market
Additives
Cosmetic Grade Color Additives Market
Additives
Global Glass Additives Market
Additives
Global Performance Additives Market
Additives
Alginic Acid Market