
 Glycol Monostearate Market | 2026-2036
Glycol Monostearate Market Size, Share, and Industry Trends Forecast 2026-2036
Glycol Monostearate Market Foresight
Multi-source procurement from specialized ester manufacturers is restructuring how personal care and food compounders secure glycol monostearate supply. BASF SE leverages integrated oleochemical feedstock access to sustain cost-competitive cosmetic-grade production across European and Asian facilities. Croda International Plc differentiates through high-purity pharmaceutical-grade certification, while Kao Corporation anchors regional supply security for Japanese and Southeast Asian cosmetic manufacturers.
Glycol monostearate is an ethylene glycol ester of stearic acid, typically produced via direct esterification of stearic acid with ethylene glycol at temperatures between 180°C and 220°C, functioning primarily as a non-ionic surfactant, emulsifier, and opacifying agent across personal care and food systems. Cosmetic-grade formulations command premium positioning due to stringent heavy-metal and acid-value specifications required by skin-contact regulations, whereas food-grade material serves as a stabilizer in baked goods and confectionery with defined melting-point ranges. Powder and liquid forms split demand structurally: powders dominate high-volume food and coatings applications for handling efficiency, while liquid emulsions concentrate in personal care manufacturing lines optimized for continuous batch processing.
REACH registration requirements in Europe, FDA food additive and cosmetic ingredient oversight in the United States, and BIS quality certification protocols in India collectively elevate compliance costs for cross-border glycol monostearate suppliers. These frameworks push manufacturers toward documented supply-chain traceability and third-party purity testing to maintain market access across jurisdictions. Stakeholders must weigh regional certification investments against the margin compression from standardized industrial-grade competition when allocating capacity between pharmaceutical, cosmetic, and food-grade product streams.
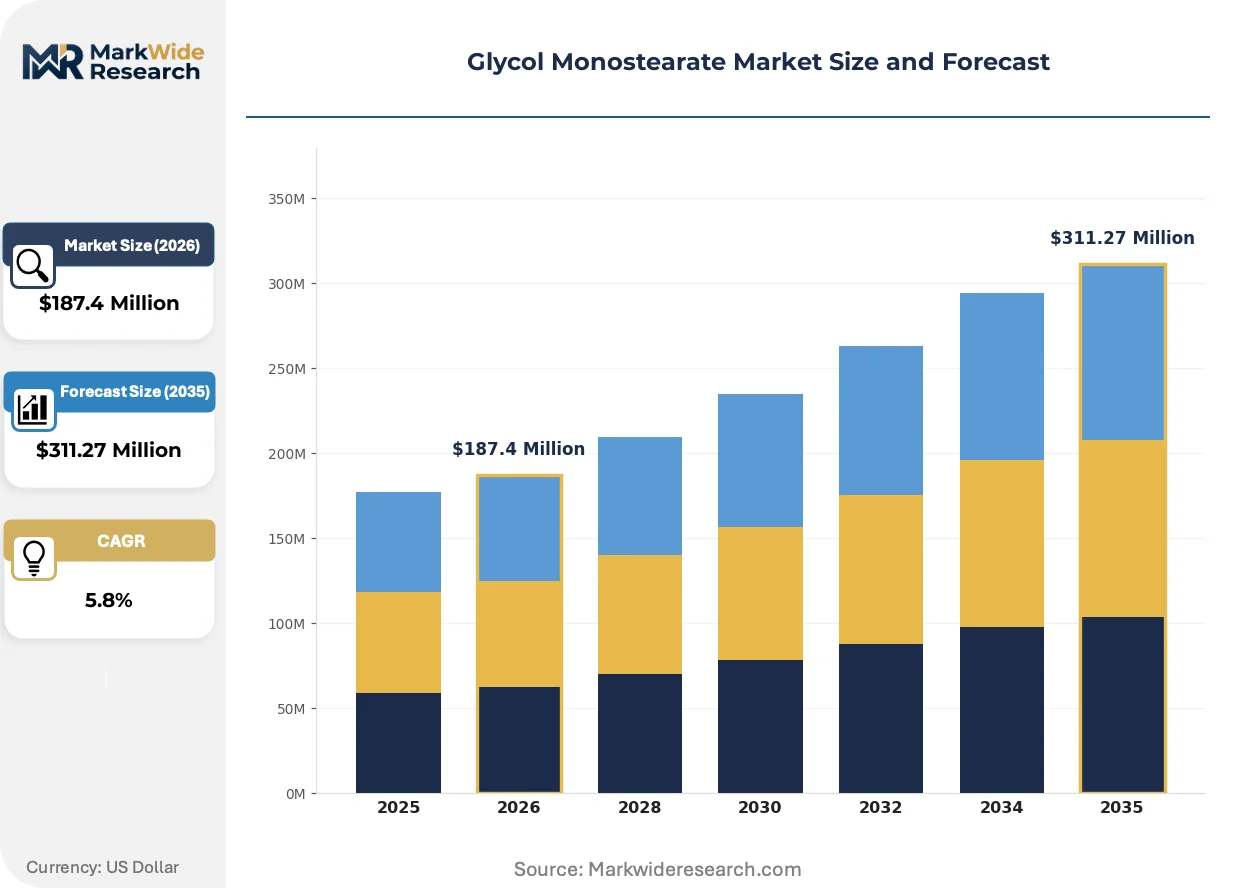
Market Dynamics
Personal care formulators are consolidating procurement around certified emulsifier-grade glycol monostearate as REACH purity benchmarks and FDA cosmetic ingredient reviews tighten simultaneously, forcing supply base rationalization toward documented traceability systems.
Growth Catalysts
- REACH compliance escalation:ECHA registration requirements for ethylene glycol esters are filtering out uncertified suppliers and concentrating volume with registered European producers capable of documented heavy-metal testing.
- China domestic beauty supply chains:Local surfactant manufacturers are scaling cosmetic-grade output to serve indigenous personal care brands, reducing import dependency for emulsion stabilizers.
- Hair conditioner emulsion stabilization:Formulators are expanding glycol monostearate loading rates in rinse-off conditioners to achieve superior viscosity control and pearlized aesthetics.
Market Restraints
- Stearic acid feedstock volatility:Oleochemical price swings tied to palm oil and tallow markets compress margin predictability for ester manufacturers without backward integration into fatty acid production.
- Supplier concentration in specialty esters:Limited qualified producers of pharmaceutical-grade material create single-source risk for cosmetic compounders requiring dual supply documentation.
- Glycerol monostearate substitution:Food-grade compounders in baked goods applications are partially substituting glycol esters with glycerol-based alternatives where melting-point specifications permit.
Strategic Opportunities
- Indian BIS certification gap:Domestic cosmetic manufacturers seeking export-ready formulations present volume opportunity for certified suppliers willing to navigate India's quality assurance protocols.
- Continuous batch processing liquid emulsions:Personal care manufacturing lines optimized for pumpable feedstocks favor liquid glycol monostearate over powder handling, shifting product-form strategy.
- EU Green Deal bio-based mandates:Renewable carbon-content specifications for surfactants are creating preference for oleochemical-derived esters over petrochemical alternatives in European formulations.
Industry Challenges
- Cross-jurisdiction certification timelines:Simultaneous FDA cosmetic ingredient review, REACH dossier maintenance, and BIS quality mark applications strain regulatory affairs capacity at mid-scale ester producers.
- Emulsion stability testing protocols:Accelerated aging validation for skin-cream applications requires capital investment in climatic chambers and rheometry equipment that smaller compounders lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycol Monostearate Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Cosmetic Grade, Pharmaceutical Grade Application: Baking, Personal Care, Pharmaceuticals, Coatings End User: Food Industry, Cosmetic Manufacturers, Drug Manufacturers, Paints Form: Powder, Liquid, Granules, Emulsions |
| Companies Covered | BASF SE, Croda International Plc, Wilmar International Limited, Stepan Company, Evonik Industries AG, Cargill, Incorporated, Kao Corporation, Lonza Group AG, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycol Monostearate Market Shifts & Advancements
Process intensification and regulatory digitization are restructuring how glycol monostearate purity is verified and documented across personal care supply chains, compressing traditional batch-release timelines.
Enzymatic esterification catalysts are decentralizing production economics for cosmetic-grade glycol monostearate. Mid-scale manufacturers in Southeast Asia are adopting lipase-mediated processes to achieve lower acid values without high-temperature equipment. This technology is decentralizing capacity expansion away from integrated petrochemical complexes toward regional oleochemical hubs.
REACH registration dossier updates for ethylene glycol esters are mandating enhanced toxicological endpoint data. ECHA's revised information requirements are extending compliance timelines for existing suppliers. Cosmetic-grade producers with pre-submitted dossiers are capturing volume from competitors facing registration gaps.
Beauty brand procurement teams are consolidating supplier panels around vertically integrated oleochemical producers capable of chain-of-custody documentation. Direct sourcing agreements are replacing distributor-mediated transactions for high-volume emulsifier requirements. This concentration is most visible among Japanese and South Korean cosmetic manufacturers seeking supply security.
Glycol Monostearate Market Segmentation
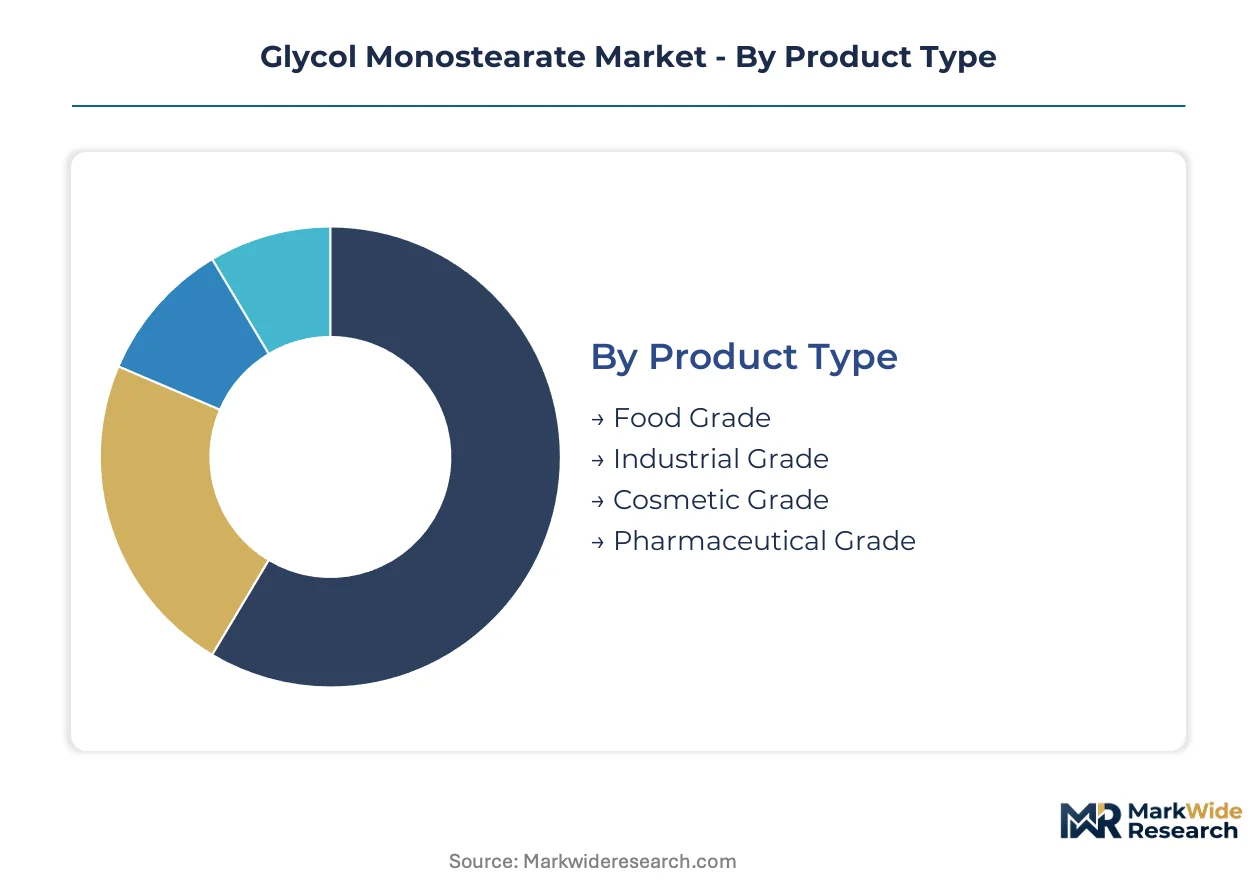
Grade certification and form factor specifications determine pricing power and regulatory compliance burden across glycol monostearate supply chains. Personal care compounders prioritize cosmetic-grade material with documented heavy-metal testing, while food manufacturers optimize for handling efficiency in powder formats.
Product Type:
Technical specifications around acid value, heavy-metal content, and melting-point ranges define procurement priorities for compounders across end-use sectors.
- Cosmetic Grade:Stringent acid-value specifications below 5 mg KOH/g and heavy-metal thresholds under 10 ppm distinguish skin-contact formulations. REACH-registered European suppliers command premium positioning as ECHA dossier requirements filter uncertified competitors.
- Food Grade:Defined melting-point ranges between 55°C and 60°C stabilize baked goods and confectionery emulsions. FDA food additive compliance and FSSAI quality protocols in India create documented supply-chain requirements for cross-border suppliers.
- Pharmaceutical Grade:USP-NF monograph compliance with enhanced purity documentation serves topical drug formulations.
- Industrial Grade:Standardized ester specifications for coatings and lubricant applications prioritize cost efficiency over traceability documentation.
Cosmetic grade leads on scale; pharmaceutical grade leads on momentum.
Application:
End-use performance requirements around emulsion stability, viscosity control, and aesthetic opacity shape formulation loading rates and supplier selection criteria.
- Personal Care:Hair conditioner formulators expand glycol monostearate loading rates to achieve pearlized aesthetics and superior viscosity control in rinse-off systems. Japanese and South Korean cosmetic manufacturers consolidate procurement around vertically integrated oleochemical producers with chain-of-custody documentation.
- Baking:Emulsion stabilization in cakes and pastries depends on precise melting-point behavior during oven temperature cycling. Glycerol monostearate substitution pressure intensifies where melting specifications permit reformulation.
- Pharmaceuticals:Topical cream and ointment bases require documented purity for skin-contact drug delivery systems.
- Coatings:Opacifying and flow-control functions in industrial finishes utilize industrial-grade material with less stringent traceability.
Personal care dominates volume concentration; pharmaceuticals shows the steepest expansion trajectory.
End User:
Customer scale and certification sophistication determine whether procurement runs through distributors or direct manufacturer agreements.
- Cosmetic Manufacturers:Large-scale compounders in Japan and South Korea bypass distributor networks for direct sourcing agreements with integrated oleochemical producers. Beauty brand procurement teams consolidate supplier panels around documented traceability systems.
- Food Industry:Bakery and confectionery compounders prioritize powder-form handling efficiency and standardized melting-point performance across high-volume production lines.
- Drug Manufacturers:Pharmaceutical compounders require dual-source documentation and USP-NF certification for topical formulation inputs.
- Paints:Industrial coatings producers utilize cost-optimized industrial-grade material with functional performance specifications.
Cosmetic manufacturers anchor premium-tier demand; drug manufacturers concentrate qualification requirements.
Form:
Physical state determines handling infrastructure, batch processing compatibility, and regional manufacturing line optimization.
- Powder:Dominates high-volume food and coatings applications where pneumatic conveying and bulk storage systems optimize handling efficiency. Chinese domestic surfactant producers scale powder output to serve local beauty brand supply chains.
- Liquid:Personal care manufacturing lines optimized for continuous batch processing favor pumpable feedstocks over powder handling. Liquid emulsions reduce dust exposure and accelerate batch cycle times in automated cosmetic production.
- Granules:Intermediate handling characteristics serve specialty applications requiring controlled dissolution rates.
- Emulsions:Pre-dispersed formats simplify formulation for mid-scale compounders lacking high-shear mixing equipment.
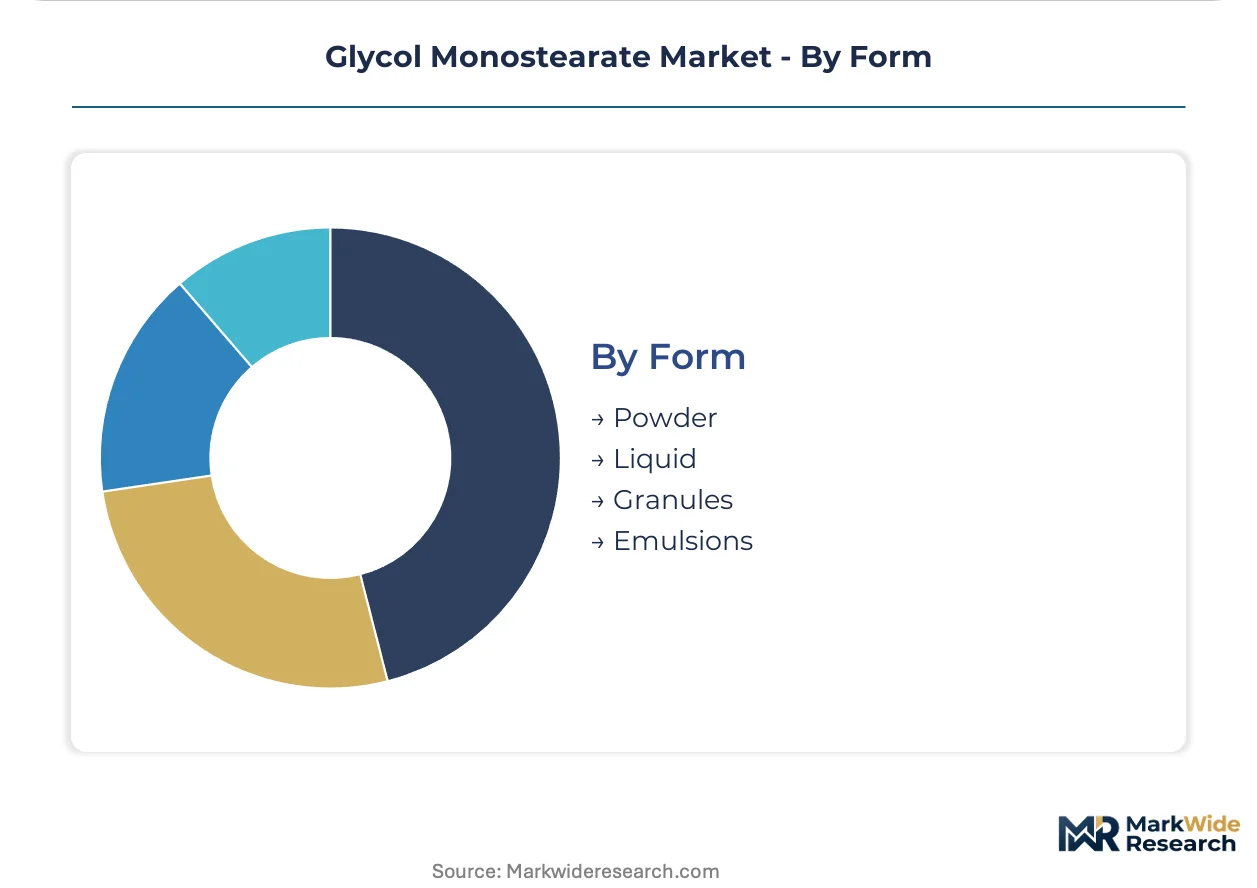
Powder leads on installed base scale; liquid gains share fastest in personal care conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors glycol monostearate manufacturing scale, with domestic surfactant producers scaling cosmetic-grade output to serve indigenous beauty brand supply chains.
China
Domestic surfactant manufacturers in Jiangsu and Zhejiang provinces are expanding cosmetic-grade capacity to supply local personal care brands reducing import dependency. SAMR's evolving cosmetic ingredient oversight tightens purity documentation requirements for cross-border suppliers. Shanghai-based compounders are consolidating procurement around regional producers with documented chain-of-custody systems.
United States
Personal care formulators in New Jersey and California are tightening emulsifier specifications as FDA cosmetic ingredient reviews intensify scrutiny of heavy-metal thresholds. EPA and FDA oversight of ethylene glycol derivatives elevates compliance costs for imported material. Chicago-area food compounders prioritize powder-form handling efficiency for high-volume bakery applications.
Germany
REACH registration requirements for ethylene glycol esters are filtering uncertified suppliers from the European market. ECHA dossier maintenance demands documented toxicological endpoint data extending compliance timelines. BASF SE's Ludwigshafen complex sustains cost-competitive cosmetic-grade production through integrated oleochemical feedstock access.
India
Domestic cosmetic manufacturers in Maharashtra and Gujarat are seeking export-ready formulations, creating volume opportunity for certified suppliers navigating BIS quality assurance protocols. FSSAI food additive standards and CDSCO pharmaceutical oversight create multi-jurisdiction certification requirements. Mumbai-based personal care compounders are rationalizing supplier panels toward documented traceability systems.
Japan
Cosmetic manufacturers in Osaka and Tokyo are consolidating procurement around vertically integrated oleochemical producers with chain-of-custody documentation. METI industrial standards and PMDA pharmaceutical oversight maintain stringent purity benchmarks for skin-contact applications. Kao Corporation anchors regional supply security for domestic and Southeast Asian cosmetic manufacturers.
Glycol Monostearate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue enzymatic process technology and regional certification gaps. The supplier base concentrates around integrated oleochemical conglomerates with backward integration into fatty acid production, mid-scale ester specialists with pharmaceutical-grade certification, and regional surfactant manufacturers scaling cosmetic-grade output. Competitive positioning depends on REACH dossier completeness, documented heavy-metal testing capacity, and chain-of-custody systems for beauty brand procurement. Primary competitive moves include capacity expansion in Chinese coastal provinces and strategic partnerships for BIS certification navigation in India.
Among European-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated archetype with captive oleochemical feedstock access. Croda International Plc occupies a position within the high-purity certification tier, representing pharmaceutical-grade specialists. Kao Corporation anchors the Asia-Pacific regional supply security archetype for Japanese and Southeast Asian cosmetic manufacturers. These three patterns—integrated feedstock control, purity-tier specialization, and regional supply anchoring—structure competitive differentiation across procurement consolidation trends.
| Leading Market Players |
|---|
| BASF SE |
| Croda International Plc |
| Wilmar International Limited |
| Stepan Company |
| Evonik Industries AG |
| Cargill, Incorporated |
| Kao Corporation |
| Lonza Group AG |
| Clariant AG |
| Others |
Supply & Pricing Matrix
Palm oil futures volatility on Bursa Malaysia Derivatives cascades through stearic acid markets into tiered glycol monostearate pricing. REACH-registered cosmetic-grade material commands substantial premiums over industrial-grade alternatives as ECHA dossier maintenance costs embed into supplier quotations.
Pricing Analysis
Input-cost pass-through from oleochemical feedstock markets structures glycol monostearate pricing across three certification tiers. Cosmetic-grade material with documented heavy-metal testing under 10 ppm and acid values below 5 mg KOH/g extracts premium positioning from personal care compounders in Japan and South Korea. Food-grade specifications with defined 55-60°C melting-point ranges occupy mid-tier positioning. Price compression intensifies in industrial-grade segments where glycerol monostearate substitution pressures standard ester offerings. Large-volume cosmetic manufacturers demonstrate lowest price sensitivity due to supply security priorities, while mid-scale food compounders exhibit highest elasticity to alternative emulsifiers.
Supply Chain Analysis
Reverse-logistics flows for glycol monostearate remain minimal given consumable end-use nature, though drum return programs for liquid emulsions operate between German chemical distributors and cosmetic compounders. Supply concentrates in China, Germany, and Japan, with Jiangsu province surfactant producers scaling cosmetic-grade powder output. Stearic acid feedstock draws from Malaysian and Indonesian palm oil complexes, with tallow alternatives sourced from North American rendering operations. Single-source vulnerability concentrates in pharmaceutical-grade certification where limited producers maintain USP-NF compliance. Distribution runs through integrated oleochemical producers for high-volume cosmetic accounts, with regional distributors serving mid-scale food and coatings compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glycol monostearate functions as a regulatory compounder where REACH dossier updates and FDA cosmetic ingredient reviews simultaneously elevate compliance burdens and filter competitor supply. ECHA's revised toxicological endpoint requirements for ethylene glycol esters represent the decisive regulatory milestone concentrating volume with pre-registered European producers.
For Market Incumbents: Acquire enzymatic esterification technology assets to defend against lipase-mediated process entrants in Southeast Asia. BASF SE and Croda International Plc should extend backward integration into Malaysian oleochemical feedstock through long-term offtake agreements with KLK Oleo and IOI Loders Croklaan. Certification investment in Indian BIS quality marks creates defensive moats as Maharashtra cosmetic manufacturers seek export-ready formulations.
For New Entrants and Emerging Players: Enzymatic process technology offers viable entry pathway for mid-scale manufacturers lacking high-temperature esterification infrastructure. White-space targets concentrate in liquid emulsion formats for personal care manufacturing lines optimized for continuous batch processing. Indian domestic cosmetic supply chains present most penetrable geography given BIS certification gaps and import substitution momentum. Go-to-market positioning should emphasize pumpable feedstock compatibility and reduced dust exposure versus incumbent powder offerings.
For Investors and Strategic Acquirers: Asymmetric upside sits with pharmaceutical-grade specialists possessing pre-submitted REACH dossiers and documented heavy-metal testing capacity. Long-term viability frames around regulatory consolidation rather than commodity scale, favoring acquisition targets with certification depth over volume leadership. The signal to watch is ECHA registration gap closures among European mid-scale ester producers, which would indicate competitive pressure normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Feedstock | BASF SE's Ludwigshafen complex sustains cost positioning through captive stearic acid supply. |
| Pharmaceutical-Grade Certification Investment | USP-NF monograph compliance opens topical drug formulation channels with premium pricing power. |
| Enzymatic Process Technology Adoption | Lipase-mediated production achieves lower acid values without 180-220°C thermal equipment. |
| Indian BIS Quality Mark Navigation | Certified suppliers capture volume from Maharashtra cosmetic manufacturers seeking export readiness. |
| Liquid Emulsion Format Expansion | Pumpable feedstocks align with Japanese and South Korean continuous batch processing lines. |
Research Methodology
Multiple input streams — technical discussions with ester plant managers, procurement leads at Japanese cosmetic OEMs, and distribution channel partners in German chemical logistics — were reconciled against secondary validation. Primary interviews engaged R&D directors at surfactant manufacturers, regulatory affairs specialists navigating ECHA dossier maintenance, and quality assurance officers at Indian personal care compounders. Secondary sources incorporated REACH registration databases, FDA food additive petitions, BIS certification records, customs trade flows for ethylene glycol esters, and SEC filings from integrated oleochemical conglomerates. Bottom-up capacity assessments and top-down demand modeling were triangulated to establish volume baselines.
Data-stream reconciliation across grade-tier segmentation, end-use industry classification, and regional production hub analysis structured the forecast framework. Modeled dimensions spanned cosmetic, food, pharmaceutical, and industrial grades; personal care, baking, pharmaceutical, and coatings applications; plus powder, liquid, granule, and pre-dispersed emulsion formats. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements across the analysis window. Industry-specific inputs incorporated palm oil price volatility indices, ECHA registration timeline assumptions, and substitution elasticity estimates for glycerol monostearate in baked goods.
The model holds under stable REACH dossier maintenance schedules and continued FDA cosmetic ingredient review intensity; deviation in ECHA information requirement timelines or feedstock supply disruptions would shift trajectory. Forecasts embed assumptions around enzymatic process adoption rates and Indian export-readiness certification demand. Practitioners should monitor ECHA registration gap closures and Malaysian palm oil production data for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Sodium Cumenesulfonate Market
Surfactants
Asia Pacific Biosurfactants Market
Surfactants
Fatty Methyl Ester Sulfonate Market
Surfactants
Naphthalene Sulfonate Market
Surfactants
Cationic Surfactants Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Global Methyl Ester Sulfonate Market
Surfactants
Oil-in-Water Anionic Emulsifier Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Global Rhamnolipid Market
Surfactants
Anionic Surfactants Market
Surfactants
Global Oilfield Surfactants Market
Surfactants
Microemulsions Market
Surfactants
Global Biosurfactant Market
Surfactants
MDEA Esterquats Market