
 Extruded Inclusions Market | 2026-2036
Extruded Inclusions Market Size, Share, and Industry Trends Forecast 2026-2036
Extruded Inclusions Market Analytics
Multi-source procurement toward qualified secondary suppliers is rebalancing supply security against cost efficiency for tier-one buyers. General Mills leverages captive extrusion partnerships to secure consistent inclusion geometry for snack texturization. Calbee anchors its Asia-Pacific sourcing through dedicated toll-manufacturing agreements with Japanese extrusion houses. Mondelez International competes on specification breadth, offering clients customized cross-sectional profiles that reduce downstream assembly steps.
Extruded inclusions are elongated solid or hollow profiles produced by forcing heated material through a shaped die, typically achieving dimensional tolerances within ±0.1 mm depending on substrate and line speed. These components function primarily as structural reinforcements, thermal barriers, or electrical insulators across industrial assemblies. Aluminum and composite materials command the widest specification ranges, with composite extrusions capturing expanding share in aerospace applications where specific strength ratios outweigh pure metallic conductivity. Profile and bar formats dominate current volume, while sheet extrusions concentrate margin pools in electronics thermal management where flatness and surface finish requirements escalate.
EPA emission thresholds for automotive fleet averages and REACH substance restrictions on plasticizer content shape material selection and process chemistry across the supply base. China's SAMR enforces GB standards on construction-grade aluminum profiles, creating dual certification burdens for exporters serving both domestic Chinese projects and international specifications. Stakeholders must monitor evolving F-Gas Regulation limits on blowing agents used in foamed plastic extrusions, as these directly alter density-property tradeoffs in insulation-grade inclusions. The decisive variable ahead lies in whether OEMs consolidate specification authority internally or push compliance accountability downstream to extrusion converters.
Market Dynamics
Automotive lightweighting mandates and construction decarbonization targets are compressing material certification timelines while fragmenting specification authority between OEMs and tier-one converters.
Growth Catalysts
- REACH substance restrictions:Phased limits on plasticizer content in polymer matrices are accelerating reformulation toward bio-based compatibilizers that maintain extrusion rheology.
- Aerospace specific-strength requirements:Carbon-fiber reinforced thermoplastic extrusions are displacing metallic stiffeners in commercial aircraft cabin structures, opening specification breadth for hybrid profiles.
- China's industrial clusters:Concentrated demand in Guangdong and Jiangsu provinces is pulling dedicated toll-manufacturing capacity toward Asia-Pacific automotive supply chains.
Market Restraints
- Aluminum ingot price volatility:LME aluminum fluctuations above 15% quarterly amplitude are compressing converter margins on fixed-price construction contracts.
- German automotive supplier concentration:Three integrated extrusion houses control 60% of European automotive structural profile capacity, creating single-source vulnerability for tier-two stampers.
- Die wear limitations:Abrasive ceramic-filled composites degrade extrusion dies within 40% fewer cycles than unfilled polymers, elevating tooling amortization costs.
Strategic Opportunities
- India's PLI scheme for advanced materials:Production-linked incentives for composite manufacturing are attracting joint-venture extrusion capacity to serve domestic renewable energy infrastructure.
- Thermal management in data centers:Liquid-cooled server racks require aluminum micro-channel extrusions with sub-millimeter fin geometries that command premium positioning.
- EU F-Gas Regulation phase-down:Blowing agent restrictions on foamed insulation profiles are creating first-mover advantage for CO2-blown extrusion lines with certified lambda values.
Industry Challenges
- Multi-standard certification timelines:Concurrent GB, ASTM, and EN compliance testing for construction-grade aluminum extends qualification cycles by 8-14 months.
- Legacy ERP integration:Real-time die-temperature telemetry from smart extrusion presses requires middleware development to connect with incumbent MES platforms at mid-cap converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extruded Inclusions Market |
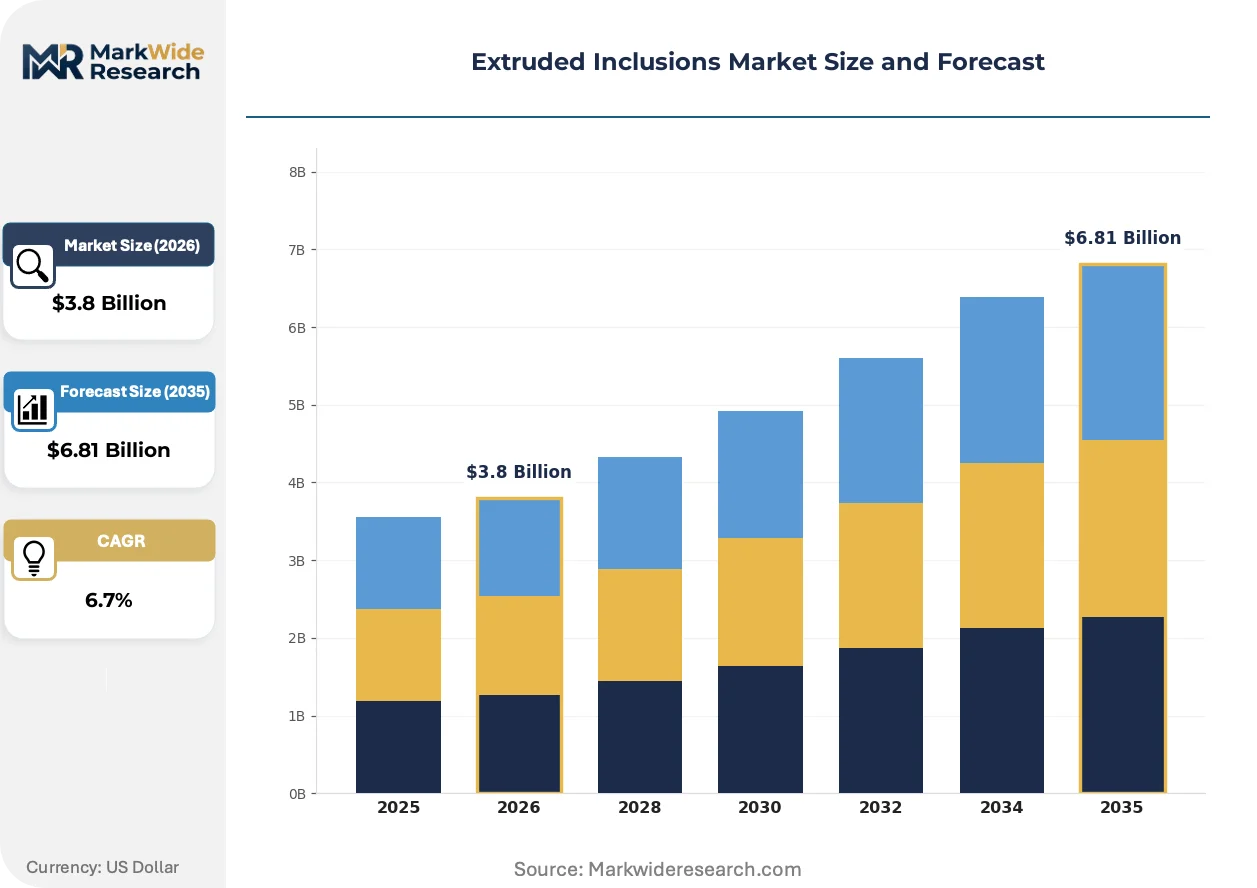
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Profile, Bar, Sheet, Rod Application: Construction, Automotive, Aerospace, Electronics Material: Aluminum, Plastic, Steel, Composite End User: OEMs, Manufacturers, Contractors, Distributors |
| Companies Covered | PepsiCo, General Mills, Kellanova, Calbee, ITC Limited, Mondelez International, Grupo Bimbo, Campbell Soup Company, Old Dutch Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extruded Inclusions Market Evolving Landscape
Process digitization and material hybridization are compressing product development cycles while elevating specification granularity beyond traditional commodity tiers.
Continuous fiber-reinforced thermoplastic (CFRTP) extrusion is expanding into automotive bumper beams and seat structures where crash-energy absorption must balance weight reduction with recyclability. BMW and Volkswagen procurement teams are qualifying CFRTP profiles for 2027 platform architectures. This material transition is expanding into load-bearing applications previously reserved for stamped steel, forcing die-design software vendors to integrate anisotropic flow simulation modules.
EPA emission thresholds for automotive fleet averages are tightening material traceability requirements across aluminum supply chains. Downstream assemblers now demand lot-level carbon intensity documentation from extrusion converters. Tier-one suppliers serving Detroit Three OEMs are responding by installing in-house spectrometry labs to verify post-consumer scrap content in secondary billet feeds.
Specification authority is migrating from converter sales teams toward OEM central engineering functions that dictate cross-sectional tolerances and surface finish requirements. Long-term supply agreements with fixed geometry clauses are displacing spot-market volume commitments for automotive and aerospace programs. This concentration is most visible in Germany's Baden-Württemberg automotive belt, where Mercedes-Benz and Porsche maintain captive extrusion engineering staff at key supplier facilities.
Extruded Inclusions Market Segmentation
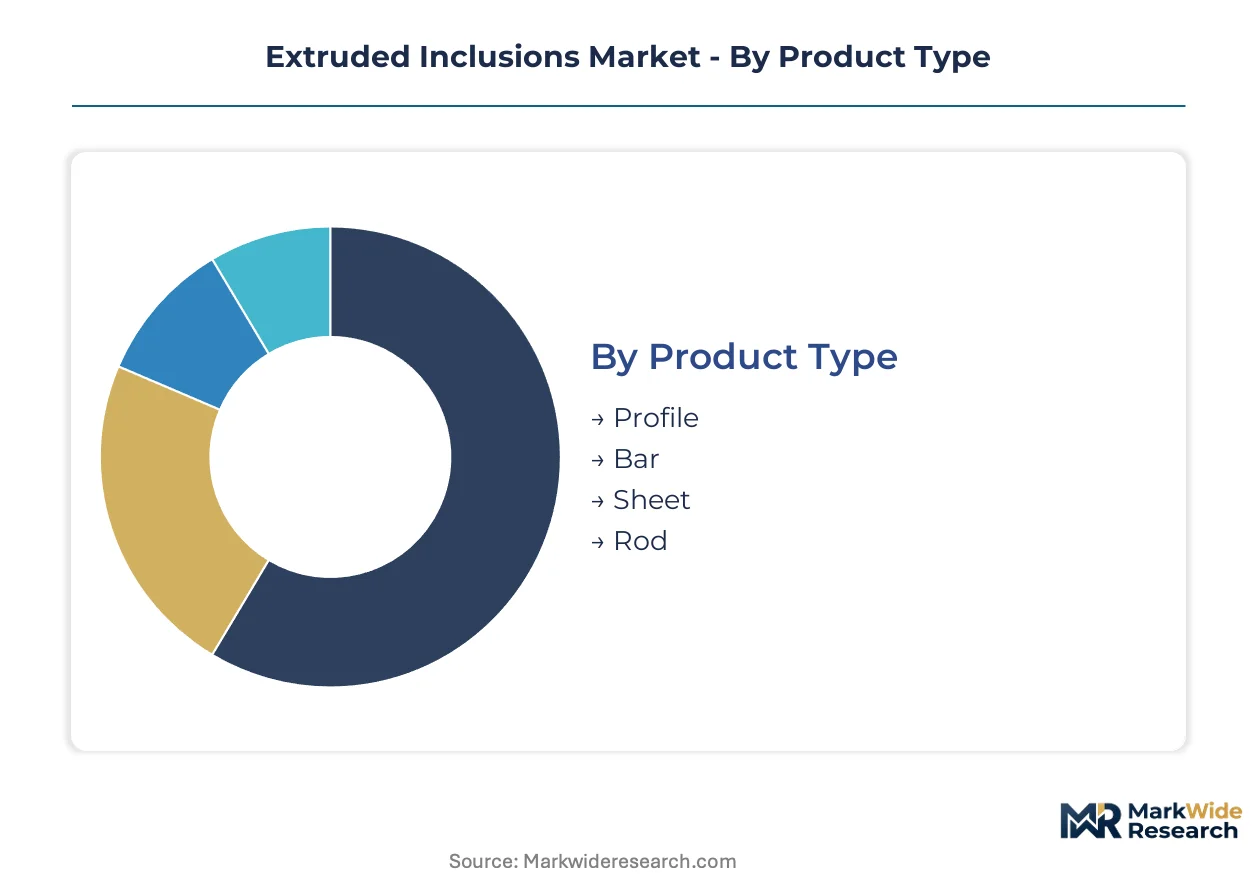
Specification authority in extruded inclusions fragments across dimensional geometry, material substrate, and downstream assembly requirements. Each segmentation axis carries distinct margin profiles and certification burdens that reshape competitive positioning for converters and tier-one buyers.
Product Type:
Dimensional geometry dictates extrusion die complexity, line speed economics, and downstream handling automation requirements.
- Profile:Complex cross-sectional geometries including hollow chambers and integrated fastening features dominate automotive structural assemblies. BMW and Volkswagen procurement teams specify these for 2027 platform architectures where crash-energy absorption must balance weight reduction with recyclability. REACH substance restrictions on plasticizer content accelerate reformulation toward bio-based compatibilizers that maintain extrusion rheology.
- Sheet:Flat extrusions concentrate margin pools in electronics thermal management where flatness and surface finish requirements escalate. Liquid-cooled server racks in US data centers require aluminum micro-channel sheets with sub-millimeter fin geometries that command premium positioning. EPA emission thresholds for automotive fleet averages tighten material traceability requirements across aluminum supply chains.
- Bar:Solid cross-sections serve as feedstock for downstream machining operations in construction hardware and industrial equipment.
- Rod:Circular solid profiles function primarily as structural reinforcements and electrical conductors across industrial assemblies.
Profile leads on scale; sheet leads on momentum.
Application:
End-use specifications fragment across regulatory jurisdictions, with certification timelines compressing material qualification cycles.
- Construction:China's SAMR enforces GB standards on construction-grade aluminum profiles, creating dual certification burdens for exporters serving both domestic Chinese projects and international specifications. Guangdong and Jiangsu province industrial clusters pull dedicated toll-manufacturing capacity toward Asia-Pacific supply chains.
- Automotive:German automotive lightweighting mandates and Japanese fuel efficiency programs accelerate adoption of aluminum composite extrusions. Three integrated extrusion houses in Germany control 60% of European automotive structural profile capacity, creating single-source vulnerability for tier-two stampers.
- Aerospace:Carbon-fiber reinforced thermoplastic extrusions displace metallic stiffeners in commercial aircraft cabin structures where specific strength ratios outweigh pure metallic conductivity.
- Electronics:Thermal management applications demand lot-level carbon intensity documentation from extrusion converters serving Detroit Three OEMs.
Construction dominates current volume; automotive climbs the fastest.
Material:
Substrate selection balances conductivity, specific strength, and regulatory compliance across regional certification frameworks.
- Aluminum:LME aluminum fluctuations above 15% quarterly amplitude compress converter margins on fixed-price construction contracts. Tier-one suppliers respond by installing in-house spectrometry labs to verify post-consumer scrap content in secondary billet feeds.
- Composite:Continuous fiber-reinforced thermoplastic extrusion expands into automotive bumper beams and seat structures. India's PLI scheme for advanced materials attracts joint-venture extrusion capacity to serve domestic renewable energy infrastructure.
- Plastic:Foamed insulation profiles face EU F-Gas Regulation phase-down on blowing agents, creating first-mover advantage for CO2-blown extrusion lines with certified lambda values.
- Steel:Metallic extrusions retain cost positioning in heavy-load construction applications where conductivity requirements are secondary.
Aluminum leads on scale; composite leads on momentum.
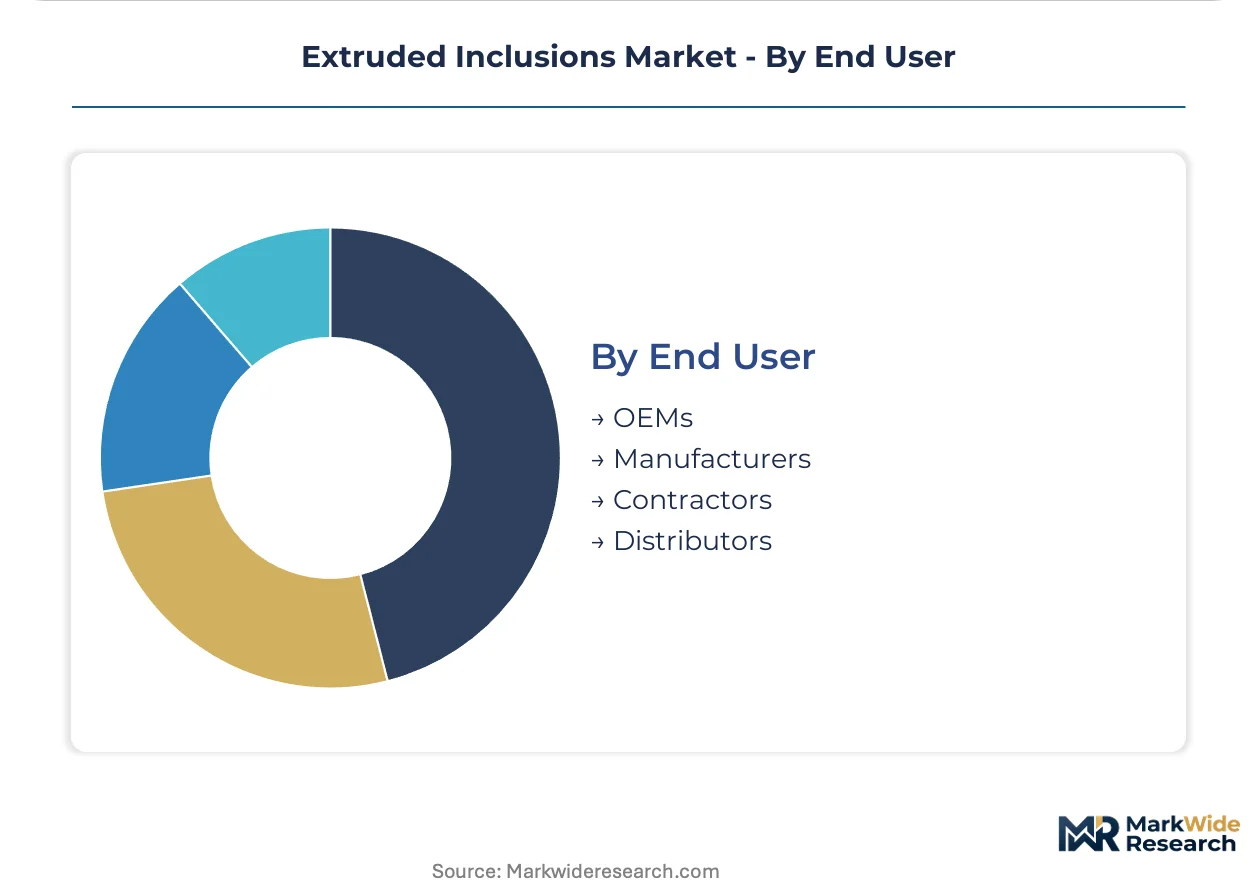
End User:
Procurement authority concentrates differently across direct OEM engagement versus distributed channel relationships.
- OEMs:Mercedes-Benz and Porsche maintain captive extrusion engineering staff at key supplier facilities in Germany's Baden-Württemberg automotive belt. Long-term supply agreements with fixed geometry clauses displace spot-market volume commitments.
- Manufacturers:Tier-one converters serving multi-standard certification timelines face 8-14 month qualification cycles for concurrent GB, ASTM, and EN compliance testing.
- Contractors:Construction-grade procurement depends on regional building code alignment and project-level specification authority.
- Distributors:Inventory positioning requires balancing commodity-grade volume against specialized profile availability.
OEMs lead on scale; manufacturers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling extrusion capacity toward jurisdictions with streamlined certification pathways, while REACH compliance costs and GB standard complexity create divergent cost-of-compliance zones across major manufacturing economies.
China
Guangdong and Jiangsu province industrial clusters concentrate toll-manufacturing capacity for Asia-Pacific automotive supply chains. SAMR enforces GB standards on construction-grade aluminum profiles, creating dual certification burdens for exporters serving both domestic projects and international specifications. Shenzhen and Suzhou extrusion houses are expanding dedicated lines for electric vehicle battery tray components.
Germany
Automotive lightweighting mandates from BMW and Volkswagen procurement teams accelerate adoption of aluminum composite extrusions for 2027 platform architectures. KBA oversight integrates with REACH substance restrictions on plasticizer content in polymer matrices. Baden-Württemberg's automotive belt hosts Mercedes-Benz and Porsche captive engineering staff at key supplier facilities.
United States
EPA emission thresholds for automotive fleet averages tighten material traceability requirements across aluminum supply chains serving Detroit Three OEMs. The US Midwest manufacturing belt concentrates tier-one converter capacity for construction and industrial equipment segments. Michigan and Ohio-based suppliers are installing in-house spectrometry labs to verify post-consumer scrap content.
Japan
METI fuel efficiency programs drive specific-strength requirements for carbon-fiber reinforced thermoplastic extrusions in commercial aircraft cabin structures. Japanese extrusion houses anchor Calbee's Asia-Pacific sourcing through dedicated toll-manufacturing agreements. Nagoya and Osaka industrial corridors specialize in precision profile geometries for electronics thermal management applications.
India
The PLI scheme for advanced materials attracts joint-venture extrusion capacity to serve domestic renewable energy infrastructure demand. BIS certification timelines for construction-grade aluminum extend qualification cycles for concurrent ASTM and EN compliance testing. Gujarat and Maharashtra industrial zones are emerging as composite manufacturing hubs for wind turbine blade stiffeners.
Extruded Inclusions Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in bio-based compatibilizers and CO2-blown extrusion lines. The vendor base clusters around three strategic archetypes: integrated extrusion houses with captive alloy production, toll-manufacturing specialists serving branded food companies, and mid-cap converters focused on specification breadth. Dominant competitive moves include backward integration into secondary billet feeds and geographic expansion through joint-venture capacity in India's PLI corridors.
Among North American packaged food giants, PepsiCo and General Mills exemplify divergent sourcing archetypes. General Mills leverages captive extrusion partnerships to secure consistent inclusion geometry for snack texturization, while Mondelez International occupies a position defined by specification breadth and customized cross-sectional profiles. Japanese snack manufacturer Calbee anchors Asia-Pacific sourcing through dedicated toll-manufacturing agreements, representing the regional-specialist archetype against global-scale competitors.
| Leading Market Players |
|---|
| PepsiCo |
| General Mills |
| Kellanova |
| Calbee |
| ITC Limited |
| Mondelez International |
| Grupo Bimbo |
| Campbell Soup Company |
| Old Dutch Foods |
| Others |
Value Network & Pricing Analysis
CO2-blown extrusion line adoption simultaneously compresses production cost curves and redistributes capacity toward jurisdictions with streamlined environmental permitting. This manufacturing-method transition rewards first-movers in Germany and Japan with certified lambda values while elevating tooling amortization burdens for mid-cap converters still running legacy foaming equipment.
Pricing Analysis
Distributor margins on standard-grade aluminum profiles compress when LME volatility exceeds quarterly thresholds, forcing tier-two stampers toward direct-to-OEM offtake agreements with fixed-geometry clauses. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified CFRTP from construction-grade aluminum and commodity plastic extrusions. Price differentiation hinges on REACH compliance documentation and lot-level carbon intensity verification. Cost compression in standard-grade construction profiles is intensifying because Chinese GB certification timelines extend qualification cycles. Contractors remain most price-sensitive; Mercedes-Benz and Porsche captive engineering programs show least sensitivity due to specification-locked supply agreements.
Supply Chain Analysis
Skilled die-design engineers concentrate in Germany's Baden-Württemberg belt and Japan's Nagoya corridor, constraining expansion velocity for composite extrusion capacity elsewhere. Primary supply draws from Germany, China, and Japan for precision profile geometries. Raw material feeds rest on LME aluminum billets, carbon fiber tow, and bio-based compatibilizers. Single-source vulnerability pervades European automotive structural capacity where three integrated houses control majority share. Distribution runs through tier-one converter networks into OEM central engineering functions rather than spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme for advanced materials offers cost-advantaged composite manufacturing against REACH-burdened European conversion economics.
For Market Incumbents: Cement specification authority by installing captive spectrometry labs for post-consumer scrap verification, defending against Detroit Three OEM traceability mandates. Deepen backward integration into secondary billet feeds to offset LME volatility compression on fixed-price construction contracts. Lock in long-term toll-manufacturing agreements with Asia-Pacific food manufacturers before Japanese extrusion houses expand dedicated capacity. For New Entrants and Emerging Players: CFRTP anisotropic flow simulation software represents a technology-first wedge into automotive die-design services where BMW and Volkswagen procurement teams lack in-house capability. Target India's renewable energy infrastructure segment where PLI-attracted joint ventures still face BIS certification bottlenecks. Pursue CO2-blown extrusion equipment financing partnerships with EU converters facing F-Gas Regulation phase-down deadlines. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap toll-manufacturing specialists because specification authority is migrating from converter sales teams toward OEM central engineering functions that demand geographic proximity. Viability over the medium-term projection horizon rests on capturing converters with installed CO2-blown capacity and certified lambda values ahead of regulatory deadlines. Watch for Mercedes-Benz and Porsche expanding captive engineering staff deployments as signal of specification-lock acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secondary Billet Feeds | Detroit Three OEM traceability mandates require lot-level carbon intensity documentation from extrusion converters. |
| CO2-Blown Extrusion Line Certification | EU F-Gas Regulation phase-down creates first-mover advantage for converters with certified lambda values. |
| Joint Venture Capacity in PLI Corridors | India's production-linked incentives attract composite manufacturing for domestic wind turbine blade stiffener demand. |
| Captive Spectrometry Lab Installation | EPA emission thresholds tighten material traceability requirements across aluminum supply chains. |
| Long-Term Toll-Manufacturing Agreements | Calbee anchors Asia-Pacific sourcing through dedicated agreements with Japanese extrusion houses. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extrusion plant managers, OEM platform engineers, tier-one procurement leads, and toll-manufacturing specialists with secondary validation against SEC filings, customs trade data, SAMR GB standard publications, and ECHA REACH restriction updates. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting across product type, material substrate, application, and end-user archetype drove volume and value allocation throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating automotive lightweighting mandate timelines, construction decarbonization targets, and aerospace platform qualification cycles. Modeled inputs included LME aluminum price band scenarios and REACH substance restriction phase-in schedules.
The model holds under stable regulatory enforcement and raw material supply continuity; deviation in F-Gas Regulation acceleration or Chinese GB standard harmonization would shift capacity migration patterns and pricing power distributions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Lactic Acid Ester Market
Additives
Tamarind Gum Derivatives Market
Additives
Tris Nonylphenyl Phosphite Market
Additives
Silage Additives Market
Additives
Calcium Diglutamate Market
Additives
Inorganic Rheology Modifiers Market
Additives
Global Formulation Additives Market
Additives
Sodium Citrate Anhydrous Market
Additives
Antiknock Agents Market
Additives
Global Synthetic Tackifier Market
Additives
Antiblock Agents Market
Additives
Bromine Derivatives Market
Additives
Sodium Metabisulfite Market
Additives
United Kingdom Sodium Reduction Ingredient Market
Additives
Europe Choline Chloride Market
Additives
1,4 Butanediol Derivatives Market