
 Laminating Adhesives Market | 2026-2036
Laminating Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Laminating Adhesives Market Intelligence
Technical service subscriptions for adhesive application equipment is rebalancing how laminating adhesives are sold, bundling chemistry with performance guarantees rather than standalone resin volumes. Dow Inc. leverages its polyurethane portfolio to anchor large flexible packaging accounts in North America. Henkel AG & Co. KGaA sustains R&D intensity across reactive hot melt platforms for automotive interior lamination. DIC Corporation competes through specialized solventless systems targeting Asian electronics substrate producers.
Laminating adhesives are multi-component bonding systems, typically comprising polyols, isocyanates, or acrylic monomers cured through thermal, moisture, or UV activation to achieve peel strengths exceeding 5 N/cm for film-to-film or film-to-foil substrates. Their primary industrial purpose is creating durable multi-layer composites that combine barrier, aesthetic, and structural properties impossible in single-material constructions. Polyurethane formulations command the deepest margin pools due to their versatility across packaging and automotive applications, while water-based systems are gaining fastest on regulatory pressure. Packaging applications dominate volume, though electronics lamination for flexible printed circuit boards offers premium pricing tiers.
EPA regulations in the United States restrict hazardous air pollutant emissions from adhesive coating operations, compelling facility upgrades or formulation switches. REACH and the EU Green Deal in Europe mandate substance registration and carbon footprint disclosure across chemical supply chains. EMA and EFSA frameworks indirectly shape demand by requiring migration testing for food-contact laminates. Stakeholders must monitor how evolving per- and polyfluoroalkyl substance restrictions will force reformulation of high-barrier packaging adhesives previously dependent on fluorinated chemistries.
Market Dynamics
Water-based and solventless adhesive systems are compressing the market share of conventional solvent-borne formulations as REACH and EPA emission ceilings tighten procurement specifications across flexible packaging converters.
Growth Catalysts
- EU Green Deal VOC limits:REACH substance restrictions on volatile organic compounds are compelling European flexible packaging converters to qualify water-based laminating adhesives for food-contact applications.
- Multi-layer barrier film demand:Food and beverage brands are specifying adhesives with peel strengths exceeding 5 N/cm for oxygen and moisture barrier laminates in shelf-stable packaging.
- Düsseldorf-Cologne machinery cluster:German packaging OEM concentration creates captive demand for high-performance polyurethane laminating systems with integrated application equipment.
Market Restraints
- Isocyanate feedstock volatility:Polyol and aromatic isocyanate price swings compress margin pools for two-component polyurethane adhesive formulators.
- Fluorinated chemistry phase-out:Per- and polyfluoroalkyl substance restrictions under ECHA evaluation are forcing reformulation of high-barrier packaging adhesives previously dependent on fluorinated chemistries.
- Cure speed limitations:Water-based systems require longer thermal dwell times than solventless alternatives, constraining throughput on high-speed lamination lines.
Strategic Opportunities
- India packaging expansion:FSSAI food-contact compliance requirements and PLI scheme incentives for domestic manufacturing are creating first-mover advantages for adhesive suppliers establishing local technical service.
- Flexible electronics substrates:UV-curable acrylic laminating adhesives for flexible printed circuit boards command premium pricing tiers above commodity packaging applications.
- Technical service bundling:Subscription-based performance guarantees combining adhesive chemistry with application equipment monitoring are displacing standalone resin volume contracts.
Industry Challenges
- Migration testing bottlenecks:EFSA framework compliance for food-contact laminates extends certification timelines, delaying new product commercialization.
- Equipment retrofit capex:Converting solvent-borne coating lines to handle water-based or solventless adhesives requires substantial capital outlay for drying system modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminating Adhesives Market |
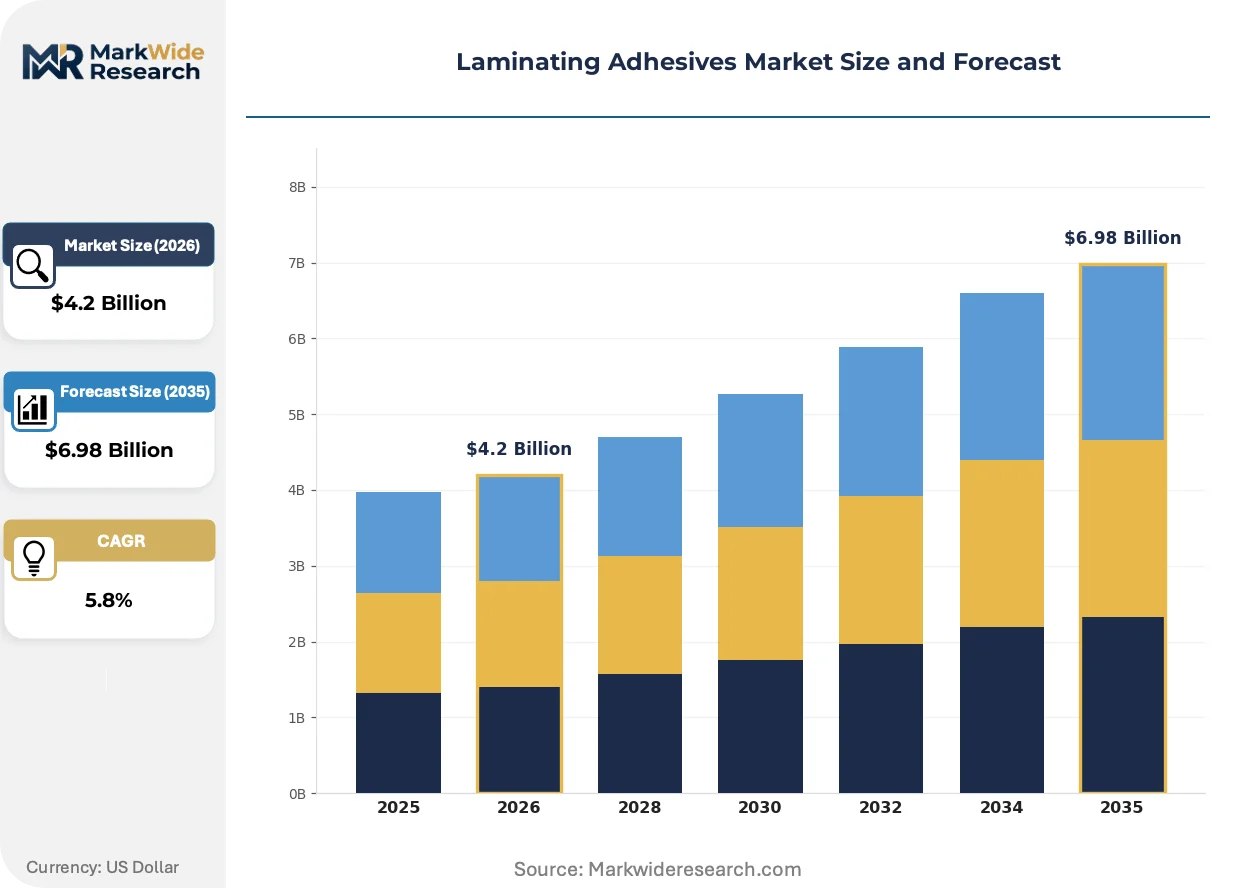
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.98 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone Application: Packaging, Automotive, Electronics, Construction Formulation: Solvent-Based, Water-Based, Hot Melt, Reactive End User: Manufacturers, Contractors, Retailers, Distributors |
| Companies Covered | Dow Inc., Sika AG, Henkel AG & Co. KGaA, DIC Corporation, Ashland Global Specialty Chemicals Inc., 3M Company, Arkema S.A., Coim Group, H.B. Fuller Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminating Adhesives Market Strategic Shifts & Innovations
Reactive hot melt and UV-curable platforms are reshaping competitive positioning by decoupling adhesive performance from thermal energy intensity, enabling lamination of temperature-sensitive substrates.
Electron-beam curable laminating adhesives are electrifying the high-speed packaging segment by eliminating solvent handling and thermal drying entirely. Major European converters are piloting EB systems for snack food pouches. This technology is electrifying throughput benchmarks while compressing energy costs and floor space requirements relative to conventional thermal cure lines.
REACH substance evaluation under the EU Green Deal is accelerating disclosure requirements across chemical supply chains. ECHA registration dossiers now mandate carbon footprint data for adhesive raw materials. German automotive interior suppliers are responding by qualifying reactive hot melt platforms with verified lifecycle assessments ahead of mandatory CSRD reporting deadlines.
Converter procurement departments are unbundling adhesive supply from equipment service contracts, forcing formulators to compete on total applied cost rather than kilogram pricing. Technical service subscriptions with uptime guarantees are displacing traditional volume rebate structures. This behavioral shift is most visible in North American flexible packaging, where Dow Inc. anchors large accounts through integrated polyurethane portfolios with performance-based pricing.
Laminating Adhesives Market Segmentation
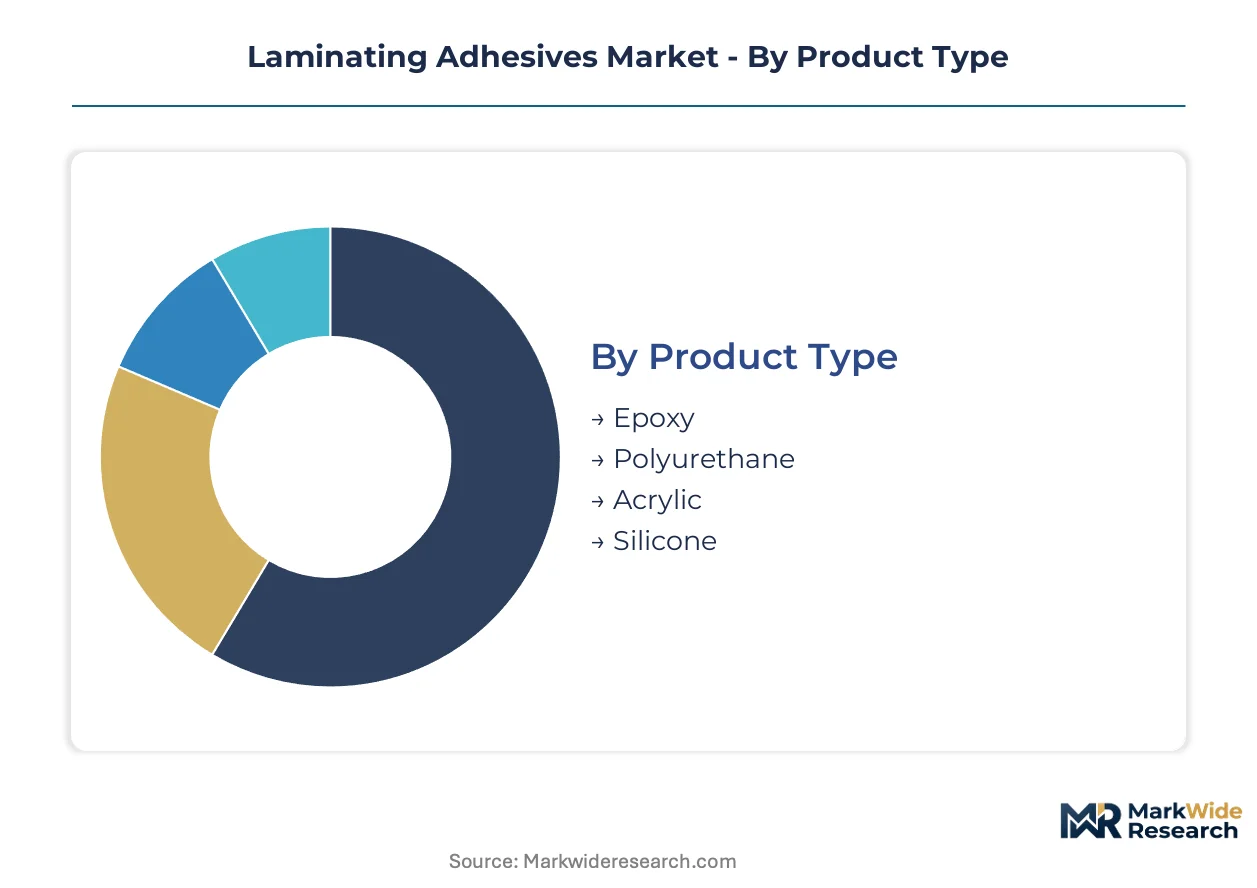
Laminating adhesives serve fundamentally different performance requirements across packaging barriers, automotive interiors, and flexible electronics substrates. Segmentation reveals how formulation chemistry and cure mechanisms align with end-use thermal, chemical, and mechanical stress profiles.
Product Type:
Polyurethane formulations anchor the deepest margin pools through versatile crosslinking chemistry adaptable to both packaging and automotive specifications.
- Polyurethane:Two-component systems combining polyols with aromatic or aliphatic isocyanates achieve peel strengths exceeding 5 N/cm for multi-layer barrier films. German automotive interior suppliers in the Düsseldorf-Cologne corridor specify these for dashboard lamination requiring thermal cycling resistance.
- Acrylic:UV-curable acrylic platforms command premium pricing tiers in flexible printed circuit board applications where thermal cure would damage temperature-sensitive polyimide substrates. Asian electronics substrate producers drive qualification programs for these systems.
- Epoxy:High crosslink density suits rigid substrate bonding in construction panel lamination.
- Silicone:Extreme temperature stability serves aerospace and industrial gasket applications with limited adhesive volume.
Polyurethane leads on scale; acrylic leads on momentum.
Application:
End-use concentration determines formulation selection, with food-contact compliance requirements filtering adhesive chemistry options.
- Packaging:Flexible packaging converters represent the dominant volume segment, with EFSA migration testing requirements shaping adhesive qualification timelines. Water-based and solventless systems are displacing solvent-borne formulations as REACH VOC limits tighten procurement specifications.
- Electronics:Flexible printed circuit board lamination demands UV-curable or reactive hot melt platforms that eliminate thermal stress on polyimide and liquid crystal polymer substrates. This segment commands the steepest pricing premiums per kilogram.
- Automotive:Interior trim lamination specifies reactive hot melts with verified lifecycle assessments ahead of mandatory CSRD reporting deadlines.
- Construction:Panel bonding applications favor epoxy and moisture-cure polyurethane for structural load-bearing requirements.
Packaging dominates volume throughput; electronics offers the steepest expansion trajectory.
Formulation:
Cure mechanism selection directly determines energy intensity, throughput speed, and regulatory compliance profile.
- Solventless:Two-component polyurethane systems eliminate solvent handling and thermal drying entirely, enabling high-speed lamination lines to achieve electrified throughput benchmarks. European snack food pouch converters pilot these systems most aggressively.
- Water-Based:Emulsion polymers disperse adhesive solids in aqueous carriers, satisfying EPA hazardous air pollutant restrictions and REACH emission ceilings. Longer thermal dwell times constrain throughput relative to solventless alternatives.
- Reactive:Moisture-cure or UV-activated chemistries decouple performance from thermal energy intensity.
- Hot Melt:Thermoplastic formulations enable rapid bonding without cure latency for non-structural applications.
Solventless systems lead on throughput efficiency; water-based platforms gain share fastest on regulatory pressure.
End User:
Procurement behavior diverges between integrated manufacturers specifying performance guarantees and intermediaries trading on kilogram pricing.
- Manufacturers:Flexible packaging converters and automotive OEMs drive technical service subscription models, bundling adhesive chemistry with application equipment monitoring and uptime guarantees rather than purchasing standalone resin volumes.
- Distributors:Regional chemical distributors serve mid-tier converters with standard formulation portfolios and volume rebate structures, capturing margin through logistics rather than technical integration.
- Contractors:Construction applicators purchase through distribution with limited formulation specification influence.
- Retailers:Consumer adhesive products represent negligible laminating adhesive volume.
Manufacturers lead on specification authority; distributors retain relevance in fragmented regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates machinery-adhesive integration while India builds converter capacity through import substitution incentives. China dominates electronics substrate lamination. The United States maintains flexible packaging R&D leadership. Japan specializes in precision electronics bonding.
United States
Flexible packaging converters in Wisconsin and Illinois drive solventless system adoption for snack food pouches. EPA hazardous air pollutant restrictions compel facility upgrades or formulation switches to water-based alternatives. The Midwest packaging belt anchors Dow Inc.'s polyurethane portfolio for large accounts with performance-based pricing structures.
Germany
Automotive interior suppliers specify reactive hot melts with verified lifecycle assessments ahead of mandatory CSRD reporting deadlines. REACH substance restrictions and EU Green Deal VOC limits tighten procurement specifications across the Düsseldorf-Cologne industrial corridor. Packaging machinery OEMs cluster around Düsseldorf, creating captive demand for high-performance polyurethane laminating systems with integrated application equipment.
China
Electronics substrate producers in the Yangtze River Delta and Pearl River Delta drive qualification programs for UV-curable acrylic platforms. NMPA and MIIT frameworks shape chemical registration requirements for food-contact laminates. Shenzhen and Suzhou concentrate flexible printed circuit board manufacturers commanding premium pricing tiers for temperature-sensitive polyimide bonding.
India
FSSAI food-contact compliance requirements and PLI scheme incentives for domestic manufacturing create first-mover advantages for adhesive suppliers establishing local technical service. BIS standards and DGFT import policies reshape supply chain configurations for packaging converters. Maharashtra and Gujarat host emerging flexible packaging clusters seeking solventless system qualifications.
Japan
Precision electronics manufacturers in Kanto and Kansai regions specify UV-curable and reactive hot melt platforms for flexible printed circuit board lamination. METI industrial standards and JIS certification requirements filter adhesive chemistry options for high-reliability applications. Tokyo-Osaka corridor companies command premium positioning through technical integration with substrate producers.
Laminating Adhesives Market Key Industry Players
Top-tier vendors anchor integrated chemistry-equipment portfolios, while mid-tier specialists compete on formulation customization for regional converters. The vendor base stratifies across three archetypes: diversified chemical conglomerates with adhesive divisions, pure-play adhesive formulators with technical service capabilities, and regional distributors capturing margin through logistics rather than specification authority. Dominant competitive moves include backward integration into polyol and isocyanate feedstocks, plus geographic expansion through local technical service subsidiaries.
Among diversified chemical conglomerates, Dow Inc. and Henkel AG & Co. KGaA exemplify the integrated portfolio archetype, bundling adhesive chemistry with application equipment monitoring and performance guarantees. DIC Corporation occupies a specialist position within Asian electronics substrate markets. Sika AG, Arkema S.A., and H.B. Fuller Company represent mid-tier formulators competing on regional technical service density. Ashland Global Specialty Chemicals Inc., 3M Company, and Coim Group anchor specialty positions across packaging and industrial lamination segments.
| Leading Market Players |
|---|
| Dow Inc. |
| Sika AG |
| Henkel AG & Co. KGaA |
| DIC Corporation |
| Ashland Global Specialty Chemicals Inc. |
| 3M Company |
| Arkema S.A. |
| Coim Group |
| H.B. Fuller Company |
| Others |
Cost & Logistics Intelligence
Aromatic isocyanate feedstock volatility cascades through polyurethane adhesive pricing tiers, compressing margin pools for two-component formulators while rewarding backward-integrated suppliers with captive polyol production in Germany and the United States.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade water-based laminating adhesives. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by EFSA food-contact certification status and technical service bundling intensity. Pricing pressure stems from isocyanate raw material swings, with flexible packaging converters in Wisconsin and Illinois exhibiting highest price sensitivity due to commodity snack food pouch specifications, while automotive interior suppliers in Germany show lowest sensitivity given performance-based contract structures.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive interior suppliers and North American flexible packaging converters. Raw material sourcing draws from aromatic isocyanate production concentrated in Germany, China, and the United States, with polyol feedstocks anchored in petrochemical corridors near Rotterdam and Houston. Single-source vulnerability around specialty aliphatic isocyanates for high-clarity laminates presents structural risk. Distribution runs through technical service subsidiaries for large accounts, with regional chemical distributors capturing fragmented converter demand in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as food and beverage brands shift specifications toward multi-layer barrier films with verified migration compliance, rewarding adhesive suppliers with integrated technical service capabilities.
For Market Incumbents: Hedge margin compression from isocyanate feedstock volatility through backward integration into polyol production or long-term offtake agreements with BASF and Covestro. Defend position against emerging Asian solventless specialists by accelerating reactive hot melt certification with German automotive OEMs ahead of CSRD reporting deadlines. Prioritize technical service subscription models that displace volume-based competitors in North American flexible packaging. For New Entrants and Emerging Players: The gap between premium UV-curable acrylics for flexible electronics and economy water-based packaging adhesives offers entry latitude. Target India's Maharashtra and Gujarat packaging clusters where FSSAI compliance requirements and PLI scheme incentives create first-mover advantages for local technical service investment. Penetrate through solventless system qualifications with mid-tier converters seeking REACH-compliant alternatives without German equipment OEM premiums. For Investors and Strategic Acquirers: Consolidation pressure builds where technical service capabilities concentrate among pure-play formulators lacking global scale. The laminating adhesives sector presents viable 5-10 year compounders through specialty positions in electronics substrate bonding and automotive interior lamination. Acquisition target archetype: regional European formulators with verified EFSA migration testing infrastructure and established Düsseldorf-Cologne corridor relationships. Monitor EB-curable pilot adoption rates at major European snack food converters as inflection indicator for next-generation platform displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Feedstocks | Captive isocyanate supply insulates margin pools from aromatic raw material volatility in Germany. |
| Technical Service Subscription Launch | Performance guarantees bundling chemistry with equipment monitoring displace volume rebate structures in North America. |
| EB-Curable Platform Pilot Expansion | Electron-beam systems eliminate thermal drying for European snack food pouch converters seeking throughput gains. |
| India Local Technical Service Subsidiary | FSSAI compliance capabilities capture PLI scheme incentives for domestic flexible packaging manufacturing in Maharashtra. |
| Reactive Hot Melt Lifecycle Assessment Certification | Verified carbon footprint data satisfies German automotive CSRD reporting deadlines ahead of mandatory disclosure. |
Research Approach
Direct dialogue with adhesive formulator R&D directors, flexible packaging converter procurement leads, automotive interior Tier 1 supplier technical managers, and German packaging machinery OEM application engineers grounded qualitative findings. Secondary validation drew from ECHA registration dossiers, EPA hazardous air pollutant emission databases, SEC 10-K filings of diversified chemical conglomerates, and Cefic industry statistics. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity assumptions.
Segment-level volume and value trajectories emerged from modeling chemistry-specific adoption curves across packaging, electronics, automotive, and construction end-uses. The analytical framework incorporated formulation technology transitions, regional regulatory compliance timelines, and equipment retrofit capex cycles throughout the projection horizon. CAGRs derived from elasticity-adjusted demand functions calibrated to historical substitution patterns between solvent-borne, water-based, and solventless systems. Forecast inputs included REACH substance evaluation schedules and FSSAI food-contact compliance rollout phases.
Caveats apply where ECHA per- and polyfluoroalkyl substance restrictions could accelerate high-barrier adhesive reformulation timelines, or where isocyanate feedstock disruptions might compress margin pools faster than modeled. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Sealants Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
Contact Cement Market
Adhesives & Sealants
Corrosion Protection Tapes Market
Adhesives & Sealants
Singapore Adhesives Market
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
Lamination Adhesive Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Waterproofing Admixture Market
Adhesives & Sealants
Italy Sealants Market
Adhesives & Sealants
China Sealants Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market