
 Indonesia Adhesives and Sealants Market | 2026-2036
Indonesia Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Adhesives and Sealants Market Foresight
Modular kit packaging for automotive assembly lines is rebalancing procurement patterns among tier-one suppliers in Indonesia. Henkel AG & Co. KGaA leverages its reactive technology portfolio to anchor high-performance bonding contracts with Japanese transplant automakers operating in Bekasi and Karawang. H.B. Fuller Company sustains dominance in water-based adhesives for corrugated packaging through direct mill partnerships with pulp and paper producers in South Sumatra. DEXTONE INDONESIA specializes in solvent-based construction sealants, occupying a cost-competitive niche in provincial building material distribution channels outside Java's premium tier.
Adhesives and sealants encompass formulated polymer systems—typically polyurethane, silicone, epoxy, or acrylic chemistries—engineered to achieve substrate-specific bonding, gap-filling, or environmental sealing through controlled viscosity, cure kinetics, and tensile-shear strength parameters. These materials serve as critical enabling components across manufacturing value chains, replacing mechanical fasteners in lightweighting strategies and providing barrier integrity in building envelopes. Water-based technology leads volume consumption in Indonesia's packaging sector due to lower volatile organic compound emissions and compatibility with recycled paperboard streams. Reactive systems, particularly polyurethane and epoxy formulations, command premium positioning in automotive structural bonding and electronics potting applications where thermal cycling resistance and dielectric properties determine specification. Hot melt adhesives compete aggressively in high-speed disposable hygiene and e-commerce fulfillment packaging lines where set speed and open time dictate operational throughput.
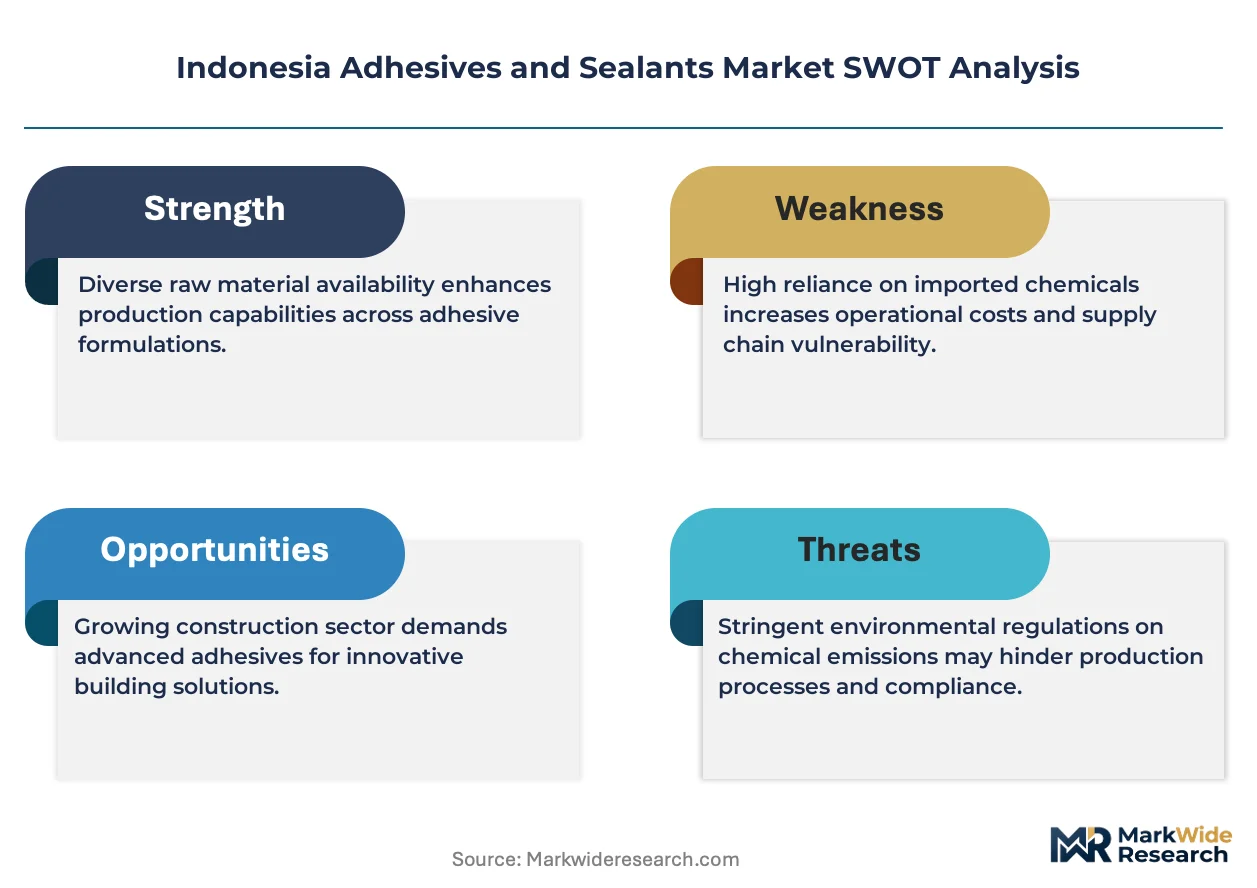
BIS certification requirements for imported epoxy and polyurethane raw materials shape formulation strategies for domestic compounders seeking to avoid certification delays on specialty resin grades. Indonesia's Ministry of Environment and Forestry enforces volatile organic compound emission thresholds for solvent-based adhesive manufacturing facilities in industrial zones, pushing capital expenditure toward enclosed reactor systems and thermal oxidizer installations. The national standards body, BSN, administers SNI marking for construction-grade sealants used in public infrastructure tenders, creating a compliance barrier for uncertified imports in government-funded projects. Stakeholders must monitor regulatory divergence between ASEAN harmonized standards and Indonesia's unilateral SNI requirements when evaluating regional supply chain integration versus dedicated domestic formulation assets.
Market Dynamics
Reactive polyurethane systems are displacing mechanical fasteners in automotive lightweighting programs across Bekasi and Karawang, compressing specification cycles and rewiring supplier qualification protocols for tier-one component manufacturers.
Growth Catalysts
- BSN SNI Marking Mandate:Mandatory certification for construction-grade sealants in public infrastructure tenders creates captive demand for domestic formulators with accredited testing capabilities.
- Japanese Transplant Automakers:Structural bonding specifications for hybrid vehicle battery enclosures are pulling high-performance epoxy and polyurethane volumes into Greater Jakarta's manufacturing corridor.
- Corrugated Packaging Mill Integration:Water-based adhesive demand concentrates at pulp and paper producers in South Sumatra as e-commerce fulfillment packaging scales.
Market Restraints
- BIS Certification Delays:Imported specialty epoxy and polyurethane raw materials face extended clearance timelines, forcing domestic compounders to hold larger buffer inventories.
- Volatile Organic Compound Compliance:Indonesia's Ministry of Environment and Forestry emission thresholds require capital-intensive thermal oxidizer installations at solvent-based manufacturing facilities.
- Silicone Sealant Substitution:Premium construction applications in Java's commercial building segment increasingly specify silicone for superior UV resistance and movement accommodation.
Strategic Opportunities
- Sumatra Provincial Distribution:Solvent-based construction sealant demand outside Java's premium tier remains underserved by cost-optimized regional formulators with localized logistics networks.
- Hot Melt Hygiene Applications:Disposable diaper and feminine hygiene manufacturing lines in Surabaya's industrial zone require high-speed adhesive systems with precise open time control.
- Recycled Paperboard Compatibility:Water-based adhesive formulations compatible with post-consumer fiber streams align with pulp and paper sector sustainability procurement criteria.
Industry Challenges
- Polymer Chemist Talent Pipeline:Formulation expertise in reactive system cure kinetics and rheology control remains concentrated among a narrow cohort of experienced specialists.
- Enclosed Reactor Capex Burden:Solvent-based adhesive producers face step-change capital requirements for enclosed manufacturing systems and emissions control infrastructure.
- SNI Testing Timeline Compression:Construction sealant certification cycles create working capital strain for domestic formulators bidding on government-funded infrastructure projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Adhesives and Sealants Market |
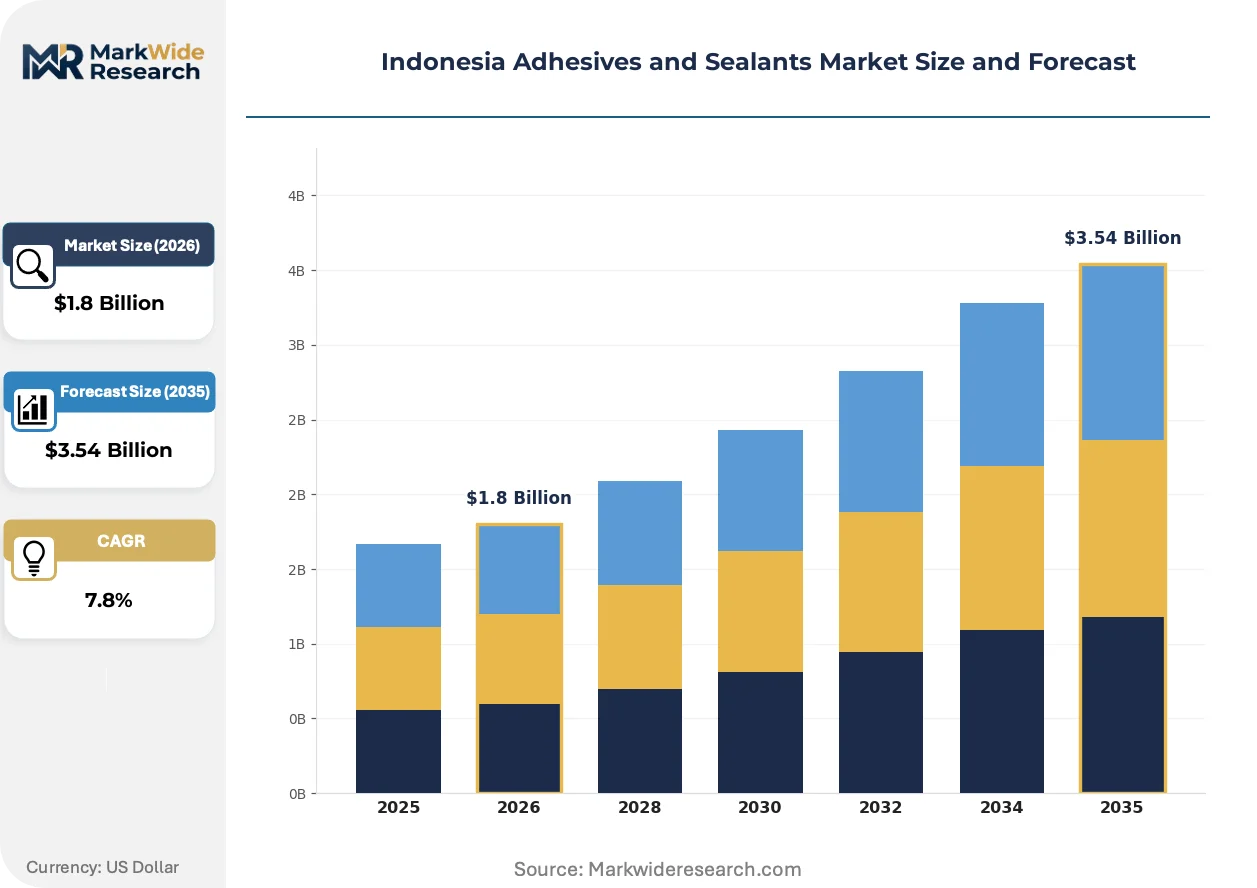
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Epoxy, Acrylic End User: Construction, Automotive, Packaging, Electronics Application: Woodworking, Assembly, Coatings, Bonding Technology: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | H.B. Fuller Company, DEXTONE INDONESIA, Henkel AG & Co. KGaA, Huntsman International LLC, Mapei Inc, 3M, Pidilite Industries Ltd, ALTECO co ltd, Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Adhesives and Sealants Market Shifts & Advancements
Digital dispensing and inline quality verification systems are rewiring adhesive application economics across high-volume manufacturing lines, compressing defect rates and reducing material waste in precision bonding operations.
Robotic dispensing platforms equipped with machine vision feedback loops are automating bead placement consistency in automotive assembly applications. Tier-one suppliers in Karawang industrial parks are deploying these systems at pilot scale for structural bonding operations. The technology is automating quality control checkpoints previously requiring manual inspection, reducing rework rates and accelerating line certification cycles with Japanese OEMs.
Indonesia's Ministry of Environment and Forestry is tightening volatile organic compound emission thresholds for adhesive manufacturing facilities operating in designated industrial zones. The regulatory pressure is forcing capital reallocation toward enclosed reactor systems and thermal oxidizer installations at solvent-based production sites. Domestic formulators in Greater Jakarta are responding by accelerating water-based technology migration for packaging applications while maintaining reactive system capacity for automotive and electronics segments.
Specification authority is migrating from procurement departments to manufacturing engineering teams as adhesive performance directly determines line speed and yield metrics. Direct mill partnerships between adhesive suppliers and pulp and paper producers in South Sumatra are displacing distributor-mediated transactions for corrugated packaging volumes. This pattern concentrates most visibly in e-commerce fulfillment packaging lines where set speed and open time parameters dictate operational throughput economics.
Indonesia Adhesives and Sealants Market Segmentation
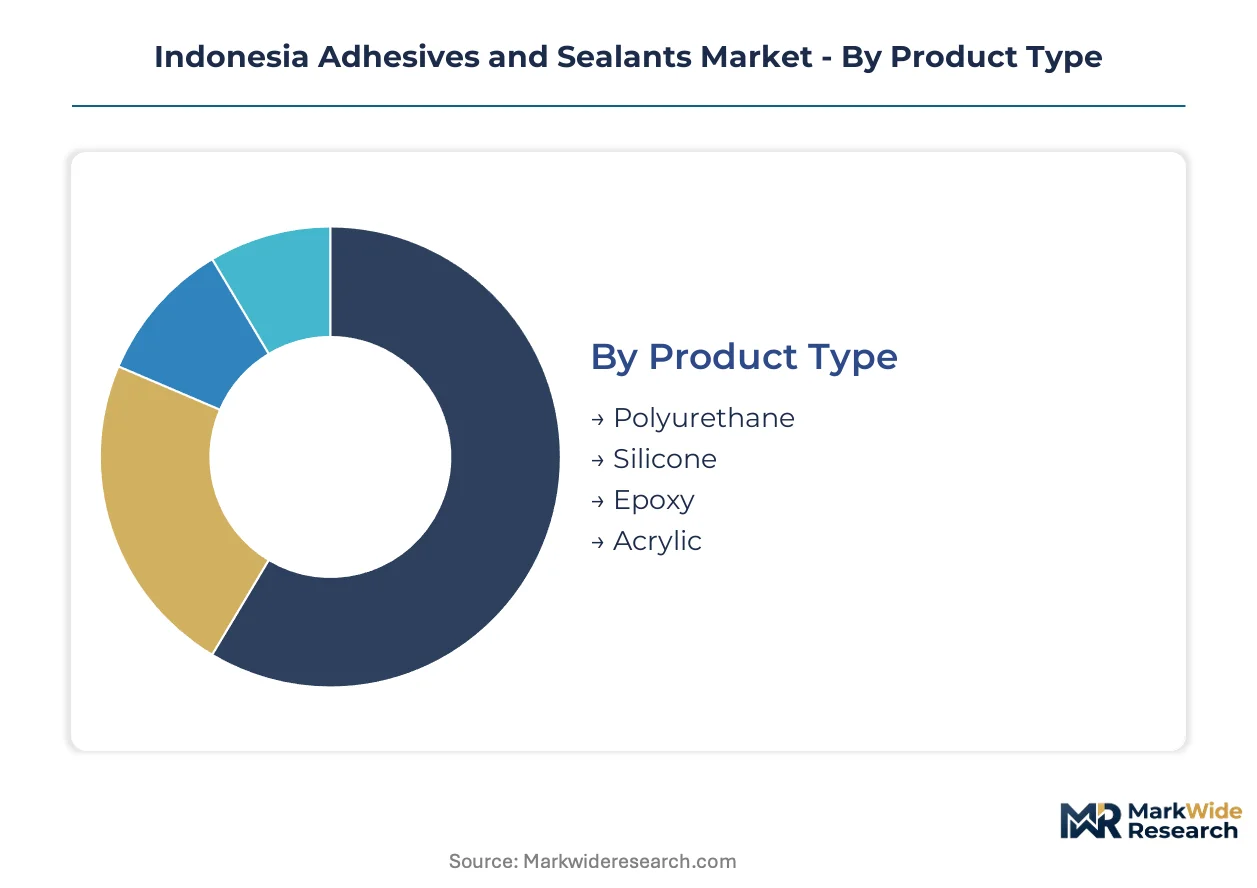
Segmentation reveals how formulation chemistry, application requirements, and regulatory compliance intersect to determine procurement patterns across Indonesia's manufacturing base. Buyers prioritize cure kinetics for automotive lines, emission profiles for packaging, and SNI certification status for public construction tenders.
Product Type:
Performance specifications and substrate compatibility drive chemistry selection, with thermal cycling resistance and UV stability separating premium from commodity grades.
- Polyurethane:Two-component systems cure through isocyanate-hydroxyl reactions to form elastomeric bonds with high tensile-shear strength. Japanese transplant automakers in Bekasi and Karawang specify these for battery enclosure structural bonding where thermal expansion accommodation is critical.
- Silicone:Room-temperature vulcanizing formulations deliver superior UV resistance and movement accommodation in building envelope applications. Commercial developments in Greater Jakarta increasingly specify silicone over polyurethane for facade sealing where 25-year service life guarantees are required.
- Epoxy:Rigid thermoset systems provide dielectric insulation and chemical resistance for electronics potting applications.
- Acrylic:Pressure-sensitive and structural variants serve high-speed packaging lines and general industrial assembly with rapid green strength development.
Polyurethane leads on scale through automotive localization; silicone leads on momentum through commercial building specification upgrades.
End User:
Volume concentration and certification requirements vary sharply across sectors, with government-funded projects imposing SNI compliance barriers that reshape competitive access.
- Construction:Sealant demand concentrates in public infrastructure tenders where BSN SNI marking is mandatory. Provincial building material distribution outside Java favors cost-optimized solvent-based formulations from regional compounders with localized logistics networks.
- Automotive:Structural bonding specifications from Japanese OEMs are displacing mechanical fasteners in lightweighting programs across Bekasi and Karawang industrial corridors.
- Packaging:Corrugated box production in South Sumatra drives water-based adhesive consumption compatible with recycled paperboard streams.
- Electronics:Potting and encapsulation applications require epoxy and polyurethane systems with precise dielectric properties and thermal cycling resistance.
Construction leads on scale through infrastructure spending; automotive leads on momentum through hybrid vehicle battery enclosure demand.
Application:
Process speed requirements and bond line durability specifications determine adhesive selection, with open time and set speed parameters dictating line economics.
- Woodworking:Edge banding and panel lamination applications in furniture manufacturing clusters specify hot melt and water-based systems with controlled open times for automated application equipment.
- Assembly:Multi-substrate bonding in appliance and industrial equipment production relies on reactive polyurethane and modified acrylic formulations.
- Coatings:Protective and decorative film applications require adhesive systems with specific viscosity and flow characteristics for uniform coverage.
- Bonding:Structural load-bearing applications across automotive and construction sectors demand validated tensile-shear performance with documented cure kinetics.
Assembly leads on scale through manufacturing diversification; bonding leads on momentum through structural adhesive substitution for mechanical fasteners.
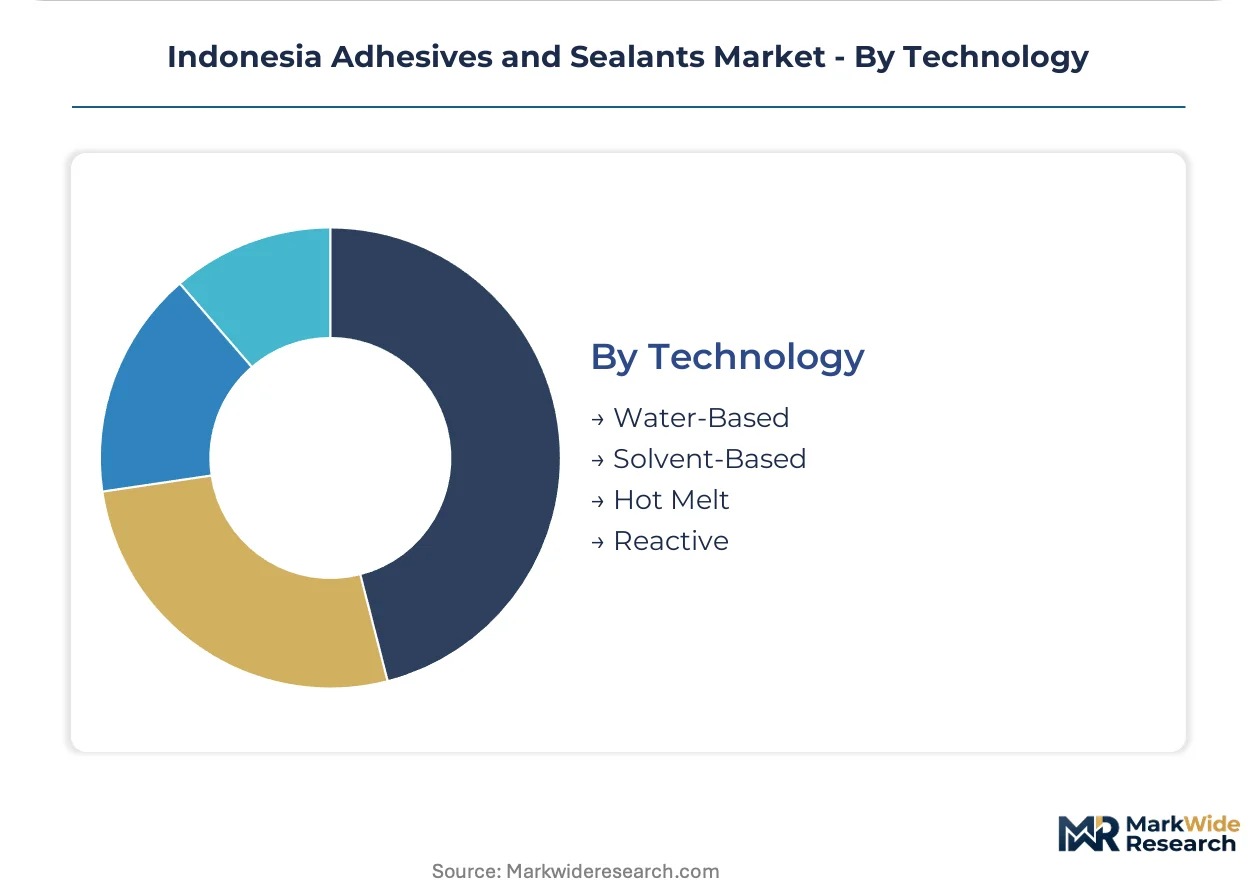
Technology:
Emission compliance costs and capital intensity separate technology tiers, with regulatory pressure from Indonesia's Ministry of Environment and Forestry accelerating migration patterns.
- Water-Based:Acrylic and polyurethane dispersions with low volatile organic compound emissions dominate corrugated packaging applications. Direct mill partnerships with South Sumatra pulp and paper producers concentrate procurement at manufacturing source.
- Solvent-Based:Construction sealants for provincial distribution channels outside Java's premium tier maintain cost competitiveness despite thermal oxidizer capital requirements for compliance.
- Hot Melt:Thermoplastic formulations enable high-speed disposable hygiene manufacturing in Surabaya's industrial zone where set speed determines line throughput.
- Reactive:Two-component polyurethane and epoxy systems command premium positioning in automotive structural bonding and electronics potting where performance validation protocols are extensive.
Water-based leads on scale through packaging sector dominance; reactive leads on momentum through automotive specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Indonesian adhesives and sealants industry traces its modern scaling to Japanese automotive transplants establishing manufacturing corridors in West Java during the 1990s, creating anchor demand for high-performance bonding systems that subsequently diffused into packaging and construction applications.
Java
Greater Jakarta's manufacturing corridor concentrates automotive OEM demand for reactive polyurethane systems in battery enclosure bonding, while Bekasi and Karawang industrial parks host tier-one suppliers qualifying under Japanese structural specifications. BSN SNI marking mandates for construction sealants create compliance barriers favoring domestic formulators with accredited testing facilities. Surabaya's industrial zone in East Java anchors disposable hygiene manufacturing lines requiring hot melt systems with precise open time control.
Sumatra
South Sumatra's pulp and paper producers drive water-based adhesive procurement through direct mill partnerships, displacing distributor channels for corrugated packaging volumes. Provincial building material distribution outside Java's premium tier favors cost-optimized solvent-based sealants from regional compounders with localized logistics networks. The Ministry of Environment and Forestry emission thresholds push capital expenditure toward thermal oxidizer installations at solvent-based facilities.
Kalimantan
Mining equipment maintenance operations in East Kalimantan generate industrial assembly demand for modified acrylic formulations serving multi-substrate bonding applications. Infrastructure projects linked to resource extraction create intermittent construction sealant procurement outside formal tender channels. Samarinda's industrial zone hosts regional distributors serving provincial contractors with limited SNI certification coverage.
Sulawesi
Nickel processing facilities in Central Sulawesi's Morowali Industrial Park pull epoxy potting systems for electronics applications in smelter automation equipment. Makassar's port logistics hub concentrates packaging adhesive demand for agricultural commodity export processing. Provincial construction activity remains price-sensitive, favoring uncertified imports over SNI-marked domestic formulations.
Bali and Eastern Indonesia
Tourism-related commercial building maintenance in Bali sustains niche silicone sealant demand for facade restoration and hospitality renovation projects. Limited manufacturing base constrains volume scale, with supply chains extending from Java-based distributors carrying inventory penalties. Kupang and Ambon ports serve as transshipment points for construction materials rather than adhesive formulation centers.
Indonesia Adhesives and Sealants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification status and technology tier, with SNI-accredited domestic formulators capturing public infrastructure tenders while uncertified imports compete on price in provincial channels. The market structure spans three distinct tiers: multinational chemical conglomerates with reactive technology portfolios, regional specialists in water-based packaging adhesives, and local compounders serving cost-driven construction segments. Strategic moves concentrate on direct mill partnerships with pulp and paper producers, and enclosed reactor investments for solvent-based compliance.
Among the multinational tier, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify divergent specialization patterns. Henkel anchors high-performance reactive system supply to Japanese automotive transplants in West Java. H.B. Fuller occupies the water-based packaging segment through direct integration with South Sumatra pulp and paper mills. DEXTONE INDONESIA represents the regional specialist archetype, concentrating on solvent-based construction sealants for provincial distribution channels where logistics proximity outweighs certification premiums.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| DEXTONE INDONESIA |
| Henkel AG & Co. KGaA |
| Huntsman International LLC |
| Mapei Inc |
| 3M |
| Pidilite Industries Ltd |
| ALTECO co ltd |
| Sika AG |
| Others |
Supply & Pricing Matrix
Japanese transplant automakers in Bekasi and Karawang anchor the premium tier through performance-validated reactive system contracts, while provincial construction contractors outside Java drive volume procurement of cost-optimized solvent-based formulations. This buyer archetype concentration produces a bifurcated pricing model where SNI certification premiums separate government-funded infrastructure awards from price-driven provincial distribution.
Pricing Analysis
Three-tier pricing structure across SNI-certified premium, standard industrial-grade, and economy solvent-based tiers dominates procurement negotiations. Price differentiation rests on BSN accreditation status and thermal cycling performance validation, with certified reactive systems commanding substantial premiums for automotive battery enclosure applications. Cost compression in the economy tier is intensifying as regional compounders compete for provincial building material contracts. Provincial contractors exhibit highest price sensitivity, while Japanese OEM procurement teams prioritize performance guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with specialty epoxy and polyurethane raw material streams drawn from Northeast Asian chemical producers. Domestic formulators depend on imported isocyanate and specialty resin grades subject to BIS certification delays, creating inventory strain. Tariff exposure on imported raw materials compounds working capital pressure for compounders serving public infrastructure tenders. Distribution runs through direct mill partnerships with South Sumatra pulp and paper producers for water-based packaging volumes, while solvent-based construction sealants reach provincial markets via regional distributor networks with localized logistics footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's adhesives and sealants market functions as a regulatory compounder where BSN SNI marking mandates create captive demand cycles for accredited domestic formulators. The mandatory certification regime for public infrastructure tenders locks in pricing power for compliant suppliers while excluding uncertified imports from government-funded projects.
For Market Incumbents: Lock in SNI-accredited testing capabilities and direct mill partnerships with South Sumatra pulp and paper producers to defend against water-based packaging margin erosion. Enclosed reactor investments for solvent-based compliance create regulatory moats against regional compounders lacking capital access. Thermal oxidizer infrastructure at Greater Jakarta facilities separates compliant producers from enforcement-vulnerable competitors. For New Entrants and Emerging Players: Provincial contractors in Sumatra and Kalimantan represent the most penetrable buyer archetype, with cost-optimized solvent-based sealant demand underserved by Java-centric distributors. Hot melt hygiene applications in Surabaya's industrial zone offer white-space entry through open time control specialization. Go-to-market execution should anchor in localized logistics networks with same-day delivery capability to provincial building material retailers. For Investors and Strategic Acquirers: Japanese automotive chemical suppliers are the most active acquirer in this space, seeking reactive technology capabilities for hybrid vehicle battery enclosure specifications. Long-term viability favors SNI-accredited domestic formulators with backward integration into water-based resin production. The inflection indicator to monitor is enforcement intensity from Indonesia's Ministry of Environment and Forestry on solvent-based emission thresholds, which would accelerate capital flight from non-compliant regional producers.| Strategic Initiative | Industry Significance |
|---|---|
| SNI Certification Investment | BSN accreditation unlocks public infrastructure tender access worth substantial recurring revenue. |
| Backward Integration into Resin Production | In-house water-based acrylic dispersion capacity reduces BIS certification exposure on imported raw materials. |
| Direct Mill Partnership Expansion | South Sumatra pulp and paper producer integration displaces distributor margins in corrugated packaging. |
| Thermal Oxidizer Installation | Emissions compliance infrastructure satisfies Ministry of Environment and Forestry thresholds for solvent-based manufacturing. |
| Hot Melt Formulation R&D | Open time precision for Surabaya hygiene manufacturing lines captures disposable diaper sector volume. |
Research Methodology
Multiple input streams — formulation chemist interviews, procurement director surveys, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged plant managers at solvent-based manufacturing facilities, technical R&D directors at multinational chemical suppliers, and procurement leads at Japanese automotive tier-one suppliers. Secondary validation drew from BSN certification databases, Ministry of Environment and Forestry enforcement records, customs import data for epoxy and polyurethane raw materials, and pulp and paper sector capacity disclosures. Bottom-up adhesive consumption modeling by end-use application was cross-checked against top-down chemical industry production estimates.
Data-stream reconciliation across the projection horizon applied segmented growth rate derivation by chemistry type, technology tier, and regional production cluster. The analytical framework modeled volume trajectories across polyurethane, silicone, epoxy, and acrylic product categories; water-based, solvent-based, hot melt, and reactive technology tiers; and construction, automotive, packaging, and electronics end-use segments. CAGRs were computed from annualized shipment data adjusted for inventory cycle effects. Forecast inputs incorporated BIS certification timeline assumptions, thermal oxidizer capex deployment schedules, and Japanese automotive transplant production forecasts.
Underlying measurement precision varies by segment; SNI-certified construction sealants and automotive reactive systems carry tighter precision than provincial solvent-based distribution. Forecasts reflect assumptions regarding regulatory enforcement continuity, raw material import clearance efficiency, and hybrid vehicle battery enclosure specification stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Polyurethane Adhesives Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Dental Impression Tray Adhesives Market
Adhesives & Sealants
Italy Sealants Market
Adhesives & Sealants
Europe Adhesives Market
Adhesives & Sealants
PVA Glue Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
Global Adhesion Barrier Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
EV Adhesives Market