
 Malaysia Sealants Market | 2026-2036
Malaysia Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Sealants Market Foresight
Technical advisory and application-support subscriptions is expanding as a revenue layer alongside bulk sealant sales. Dow leverages its silicone chemistry portfolio to anchor high-performance building envelope solutions across Malaysian commercial projects. Sika AG competes through specialized polyurethane systems for infrastructure joints and waterproofing applications. Mohm Chemical Sdn Bhd sustains domestic manufacturing scale serving regional contractors with cost-optimized acrylic formulations.
Sealants are polymeric compounds formulated from silicone, polyurethane, acrylic, or epoxy chemistries that cure to form flexible, adherent barriers resisting moisture, chemicals, and thermal cycling. These materials typically achieve Shore A hardness ratings between 15 and 50 and elongation-at-break exceeding 200 percent, enabling them to accommodate substrate movement in building joints, vehicle assemblies, and electronic enclosures. Silicone formulations dominate exterior construction applications due to UV stability and temperature resistance, while polyurethane captures growth in automotive and industrial bonding where paint compatibility and structural adhesion matter. Epoxy segments occupy specialized niches in electronics potting and aerospace assembly where rigidity and dielectric properties take priority over flexibility.
SIRIM QAS International enforces product certification under MS standards for construction sealants, while the Construction Industry Development Board mandates material compliance within contractor grading frameworks. Malaysia's Department of Environment imposes volatile organic compound limits that filter permissible formulations for interior applications. Stakeholders must monitor evolving green building rating tools and embodied carbon disclosure requirements that will reshape specification criteria and supplier qualification protocols.
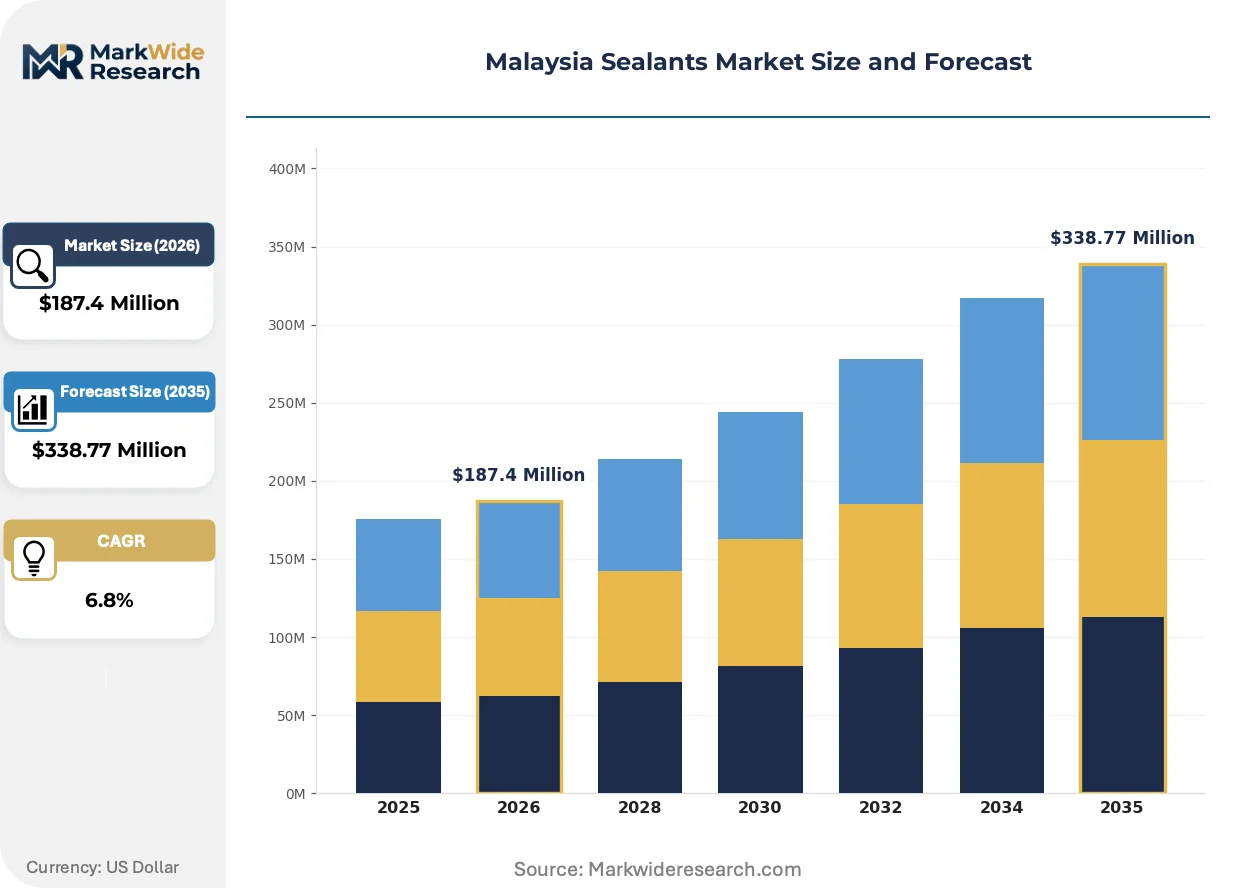
Market Dynamics
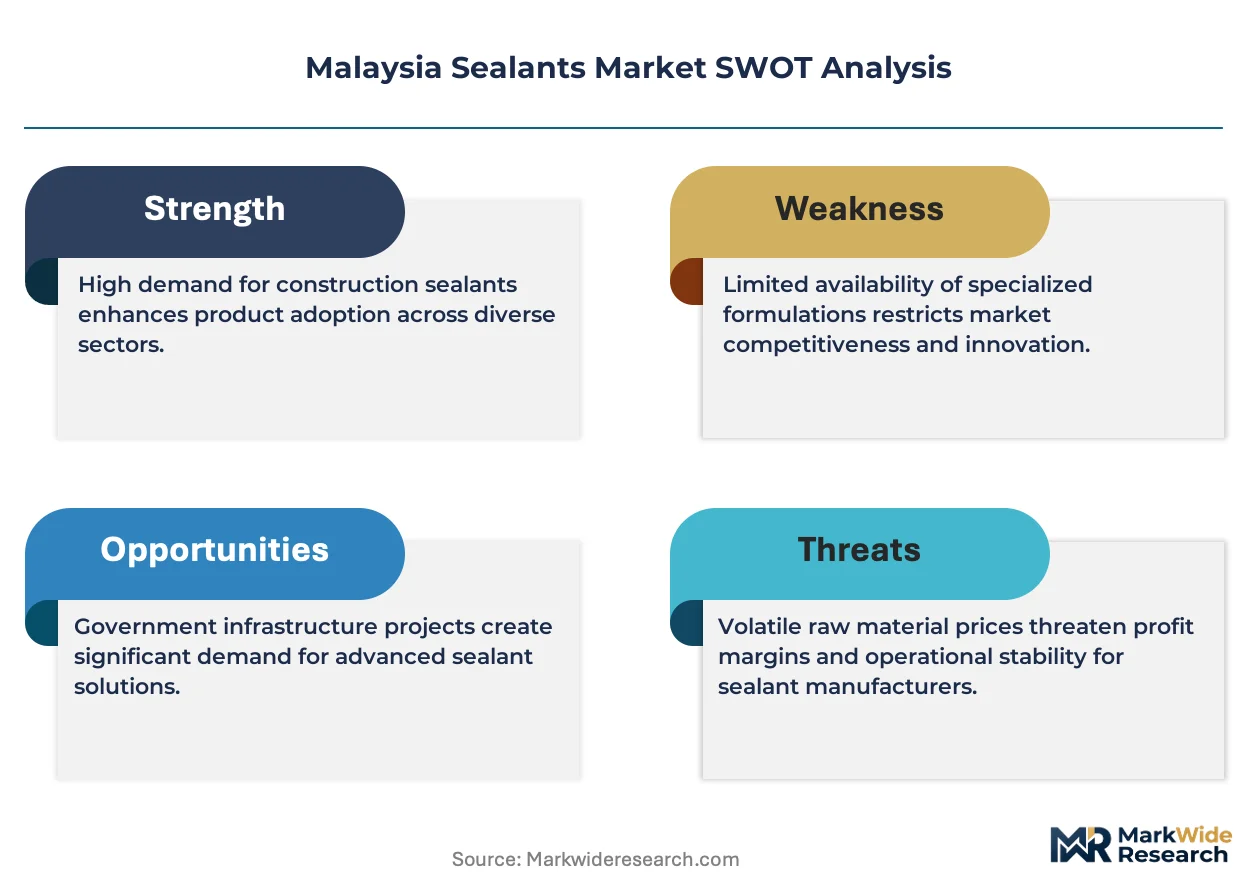
CIDB grading requirements and SIRIM certification standards are tightening compliance thresholds for building materials across Peninsular Malaysia, forcing contractors to upgrade specification protocols and suppliers to recertify product portfolios.
Growth Catalysts
- Iskandar Malaysia Infrastructure Corridor:Mega-projects linking Greater Kuala Lumpur to Johor Bahru are specifying high-performance silicone and polyurethane formulations for structural joints and waterproofing envelopes.
- SIRIM MS Standards Certification:Mandatory product testing under Malaysian national standards is filtering substandard imports and elevating demand for certified domestic manufacturing capacity.
- Green Building Rating Tools:Embodied carbon disclosure requirements under emerging sustainability frameworks are pulling low-VOC and bio-based sealant formulations into commercial specifications.
Market Restraints
- Petrochemical Feedstock Volatility:Polyurethane precursors and silicone monomers track global crude and methanol price swings, compressing margin stability for formulators serving price-sensitive infrastructure tenders.
- Import Dependency for Specialty Additives:Curing catalysts and UV stabilizers concentrate among Northeast Asian chemical suppliers, exposing Malaysian blenders to shipping cost spikes and currency fluctuation risk.
- Acrylic Substitution in Interior Applications:Cost-optimized water-based acrylics from regional producers capture non-structural sealing jobs where movement accommodation and weathering resistance are secondary priorities.
Strategic Opportunities
- East Malaysia Construction Uplift:Sarawak and Sabah infrastructure budgets remain underpenetrated by high-performance sealant suppliers, creating first-mover potential for SIRIM-certified distributors with local technical service capability.
- Technical Advisory Subscriptions:Application-support contracts layered onto bulk material sales are capturing sticky revenue streams from contractors seeking joint-design liability coverage.
- Photovoltaic Installation Surge:Solar farm deployment across northern Peninsular states is generating demand for frame-bonding and junction-box potting compounds with 25-year thermal cycling warranties.
Industry Challenges
- Certification Timeline Compression:SIRIM QAS International testing queues and CIDB material approval cycles delay new product launches by 8-14 months, punishing R&D-heavy portfolios.
- Applicator Skill Shortages:Proper surface preparation and joint-dimensioning for high-movement silicone systems require trained crews, and contractor grading frameworks do not mandate sealant-specific competency verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Sealants Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Silicone, Epoxy Application: Construction, Automotive, Aerospace, Electronics End User: Contractors, Manufacturers, Distributors, Homeowners Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialized Stores |
| Companies Covered | Dow, Mohm Chemical Sdn Bhd, 3M, Illinois Tool Works Inc, VITAL TECHNICAL SDN BHD, Sika AG, Arkema Group, Soudal, Henkel AG & Co KGaA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Sealants Market Shifts & Advancements
Formulation chemistry and compliance architecture are converging to reshape competitive positioning in Malaysian construction supply, with sustainability mandates and digital specification tools accelerating product obsolescence cycles.
Hybrid silicone-polyurethane intermediates are electrifying the high-performance building envelope segment. These materials combine silicone UV stability with polyurethane paint compatibility and structural adhesion. Main contractors in KLCC and TRX district towers are specifying them for curtainwall glazing and expansion joints. The technology is electrifying specification conversations away from single-chemistry dominance toward performance-guaranteed hybrid systems.
Malaysia's Department of Environment volatile organic compound limits for interior applications are tightening permissible formulation thresholds. Industrial consequence: water-borne and high-solids sealant R&D pipelines are displacing solvent-based legacy portfolios. Interior commercial fit-out segments in Selangor and Penang are responding fastest, with project environmental impact assessments now pre-screening material safety data sheets before tender award.
Specification decisions are migrating from general contractor procurement desks to facade consultant and architect digital libraries. BIM-embedded product databases with embedded SIRIM certification status are displacing traditional supplier relationships. This channel compression is most visible in Klang Valley commercial high-rise projects, where design-phase material lock-in now occurs 18-24 months before construction mobilization.
Malaysia Sealants Market Segmentation
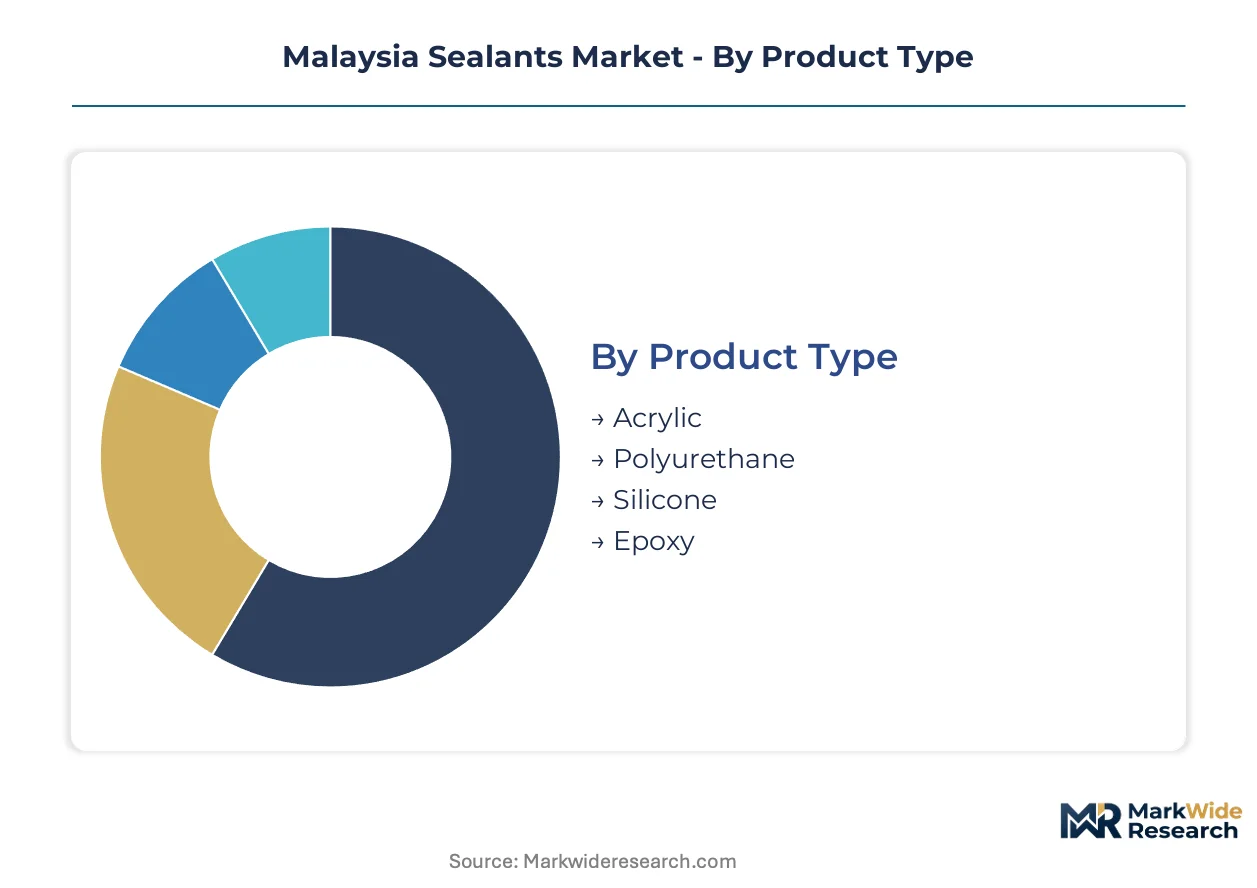
Malaysia's sealant procurement patterns track tightly to CIDB contractor grading tiers and SIRIM certification requirements. Specification decisions split across performance-critical infrastructure jobs and cost-optimized interior applications, with channel and end-user choices filtering through these compliance lenses.
Product Type:
Upgrade cycles in Malaysian construction favor reformulation toward higher-performance chemistries as facade consultants tighten movement-accommodation specifications.
- Silicone:UV-stable formulations with Shore A hardness between 20-40 dominate curtainwall glazing and expansion joints across KLCC and TRX district towers. Demand concentrates in Peninsular Malaysia's commercial high-rise corridor where 25-year weathering warranties are now standard specification clauses.
- Polyurethane:Paint-compatible systems with structural adhesion properties capture infrastructure waterproofing and automotive assembly applications. Johor Bahru contractors specify these for Iskandar Malaysia bridge joints and podium decks where load-bearing flexibility matters.
- Acrylic:Water-based cost-optimized formulations serve interior non-structural sealing in Selangor residential fit-outs.
- Epoxy:Rigid dielectric compounds occupy electronics potting niches in Penang's semiconductor assembly cluster.
Volume placements concentrate in silicone; the faster expansion belongs to polyurethane as infrastructure joint specifications tighten.
Application:
Project scale and compliance burden determine chemistry selection across Malaysian end-use segments.
- Construction:Structural joints, waterproofing envelopes, and facade glazing absorb the majority of high-performance sealant volume. Mega-projects linking Greater Kuala Lumpur to Iskandar Malaysia specify hybrid silicone-polyurethane systems for movement-critical applications.
- Automotive:Paint-compatible polyurethane bonding systems serve assembly plants in Selangor and Melaka where OEM durability standards apply.
- Electronics:Low-outgassing epoxy and silicone potting compounds protect PCB assemblies in Penang's manufacturing zone.
- Aerospace:Specialized fuel-resistant formulations serve MRO facilities at Subang and Senai airports.
Construction commands the dominant placement volume; electronics applications are climbing the fastest as semiconductor packaging demands intensify.
End User:
Procurement authority and technical competency requirements segment the Malaysian buyer base sharply.
- Contractors:CIDB-graded construction firms with G6-G7 classifications drive specification of SIRIM-certified high-performance systems. These entities maintain technical teams capable of joint-design liability coverage.
- Manufacturers:Automotive and electronics OEMs enforce incoming material testing protocols that filter uncertified suppliers.
- Distributors:Stocking intermediaries with SIRIM QAS International accreditation serve regional contractors requiring rapid replenishment.
- Homeowners:Retail purchasers in urban centers select convenience-oriented acrylic formulations for minor repair applications.
Contractor-grade procurement dominates absolute volume; manufacturer direct purchasing is gaining share fastest as OEMs tighten supply chain control.
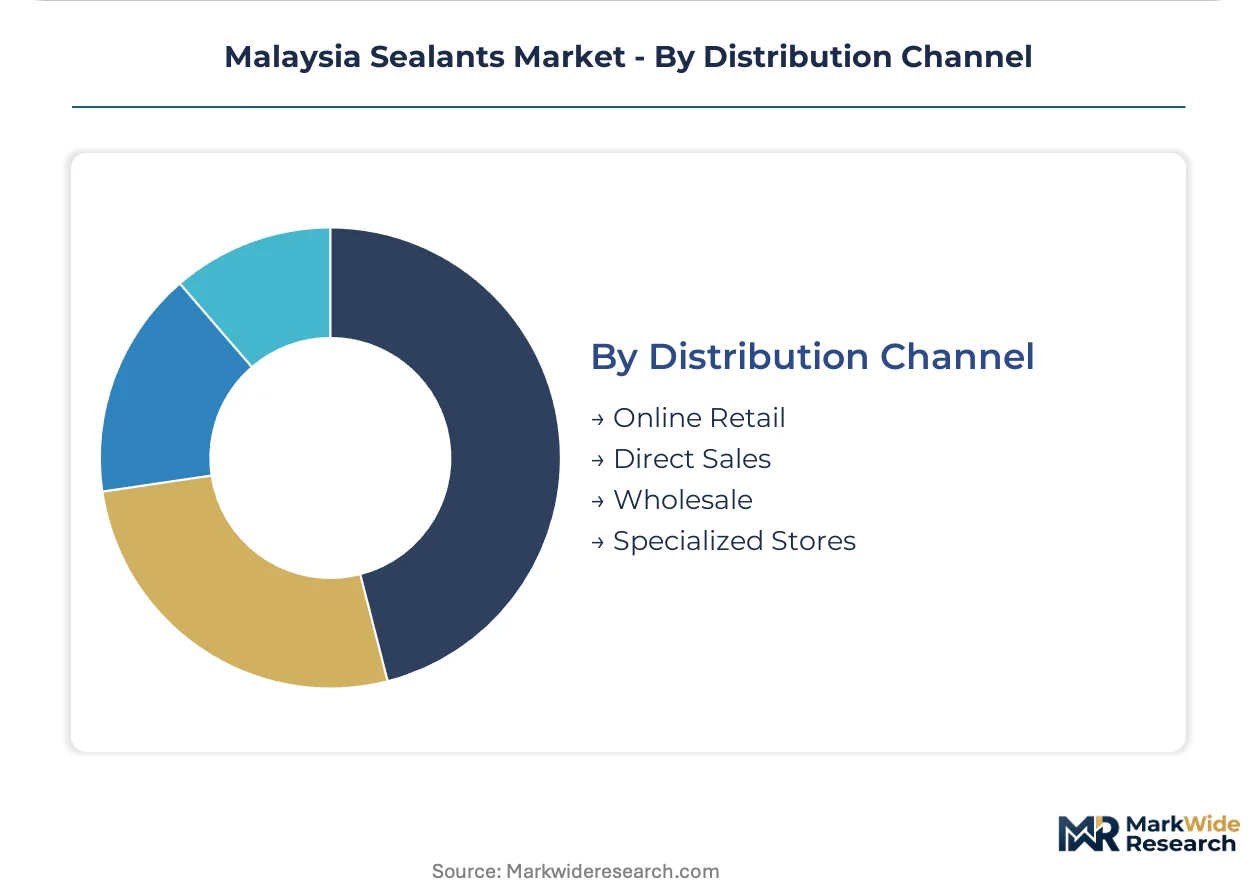
Distribution Channel:
Channel selection in Malaysia tracks to order size, technical service requirements, and certification verification needs.
- Direct Sales:Technical advisory subscriptions and application-support contracts anchor relationships between formulators and major contractors. Dow and Sika AG deploy field engineers to KLCC and Iskandar Malaysia project sites.
- Wholesale:Bulk volume flows through construction material distributors serving CIDB-graded contractor networks across the Klang Valley.
- Specialized Stores:SIRIM-certified product showrooms in Johor Bahru and Penang cater to specification-grade procurement with embedded compliance documentation.
- Online Retail:E-commerce platforms capture small-lot acrylic sales to homeowners and minor commercial maintenance crews.
Wholesale channels handle the greatest volume; direct sales with technical service attachments are expanding most quickly as liability coverage becomes a procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian sealant production concentrates in Peninsular Malaysia's industrial corridor while consumption splits between domestic infrastructure projects and electronics manufacturing exports. Local blenders serve construction-grade volume; specialty formulations for semiconductor packaging arrive from regional chemical hubs.
Greater Kuala Lumpur
Commercial high-rise construction in KLCC and TRX districts specifies SIRIM-certified silicone systems for curtainwall glazing with 25-year weathering warranties. CIDB G6-G7 contractors anchor procurement authority here. The Klang Valley's facade consultant networks lock material specifications 18-24 months ahead of construction mobilization.
Johor Bahru
Iskandar Malaysia infrastructure mega-projects specify polyurethane formulations for bridge joints and podium deck waterproofing where load-bearing flexibility matters. The Department of Environment enforces VOC limits that filter interior formulation approvals. Contractors here source hybrid silicone-polyurethane systems for movement-critical structural applications.
Penang
Electronics manufacturing clusters in Bayan Lepas and Batu Kawan drive demand for low-outgassing epoxy and silicone potting compounds protecting PCB assemblies. Semiconductor packaging facilities enforce incoming material testing protocols that filter uncertified suppliers. The state's free industrial zones attract specialty chemical distributors with technical service capability.
Selangor
Automotive assembly plants in Shah Alam and Rawang specify paint-compatible polyurethane bonding systems meeting OEM durability standards. Petrochemical feedstock volatility compresses margin stability for formulators serving price-sensitive tenders. The state's construction material distributors serve CIDB-graded contractor networks with rapid replenishment cycles.
Sarawak
Infrastructure budgets in Kuching and Miri remain underpenetrated by high-performance sealant suppliers despite growing civil works spending. SIRIM QAS International certification requirements delay new product launches by 8-14 months, punishing entrants lacking established compliance pathways. First-mover potential exists for distributors combining local technical service with pre-certified product portfolios.
Malaysia Sealants Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across Malaysia's sealant supply chain. The market structures into three tiers: multinational formulators with integrated R&D and field engineering, regional blenders serving cost-optimized volume, and specialized distributors with SIRIM accreditation and technical advisory capability. Strategic moves concentrate on certification timeline compression through pre-approved product platforms and application-support subscriptions layered onto bulk material sales.
Within the multinational tier, Dow and Sika AG anchor positions through field engineering deployments to KLCC and Iskandar Malaysia project sites. Mohm Chemical Sdn Bhd exemplifies domestic manufacturing scale serving regional contractors with certified formulation capacity. These three entities represent distinct archetypes: silicone chemistry leadership, polyurethane systems specialization, and cost-optimized local production respectively.
| Leading Market Players |
|---|
| Dow |
| Mohm Chemical Sdn Bhd |
| 3M |
| Illinois Tool Works Inc |
| VITAL TECHNICAL SDN BHD |
| Sika AG |
| Arkema Group |
| Soudal |
| Henkel AG & Co KGaA |
| Others |
Supply & Pricing Matrix
Petrochemical feedstock volatility cascades through Malaysian sealant manufacturing, with polyurethane precursors and silicone monomers tracking global crude and methanol swings that compress margin stability for formulators serving price-sensitive infrastructure tenders. This upstream cost pressure stratifies downstream pricing tiers as contractors balance SIRIM certification requirements against project budget constraints.
Pricing Analysis
Margin tightening in standard-grade formulations reflects acrylic substitution pressure from regional water-based producers capturing non-structural interior jobs. Three-tier pricing structure across premium SIRIM-certified silicone, mid-grade polyurethane, and economy acrylic levels filters procurement by CIDB contractor grading. Cost-down pressure on economy tiers accelerates because Malaysian Department of Environment VOC limits are disqualifying solvent-based legacy products. CIDB G6-G7 contractors demonstrate lowest price sensitivity due to liability coverage requirements, while residential fit-out segments in Selangor exhibit highest sensitivity to per-liter sealant costs.
Supply Chain Analysis
Dual-sourcing mandates from major contractors require SIRIM-certified distributors to maintain qualified backup suppliers for critical silicone and polyurethane formulations. Manufacturing gravity centers on Peninsular Malaysia's industrial corridor, with specialty curing catalysts and UV stabilizers drawing from Northeast Asian chemical suppliers in China, South Korea, and Japan. Single-source vulnerability concentrates among imported additive streams, exposing blenders to shipping cost spikes and currency fluctuation risk. Distribution runs through construction material wholesalers serving CIDB-graded networks, with direct technical advisory subscriptions gaining share in KLCC and Iskandar Malaysia mega-projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysian sealant suppliers are racing to secure backward integration into petrochemical feedstocks and captive technical service capacity as margin compression intensifies across standard-grade segments.
For Market Incumbents: Deepen field engineering deployments at KLCC and TRX district towers to lock specification decisions 18-24 months ahead of construction mobilization, while accelerating SIRIM pre-certification pipelines to compress 8-14 month approval timelines that punish R&D-heavy portfolios against acrylic substitutes. For New Entrants and Emerging Players: Launch via SIRIM-certified distribution partnerships targeting Sarawak and Sabah infrastructure budgets that remain underpenetrated by high-performance sealant suppliers despite growing civil works spending, with bundled technical advisory subscriptions as the primary go-to-market mechanism. For Investors and Strategic Acquirers: SIRIM QAS International queue compression is the leading indicator that certification-capable domestic blenders with established CIDB contractor relationships will command scarcity premiums, suggesting acquisition focus on mid-scale Malaysian manufacturers with pre-approved product platforms rather than greenfield capacity builds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Monomers | Captive supply of critical feedstock insulates margin stability from global crude volatility affecting Malaysian formulators. |
| SIRIM Pre-Certification Pipeline Investment | Pre-approved product platforms compress 8-14 month approval cycles that currently delay new sealant launches. |
| Technical Advisory Subscription Launch | Application-support contracts layered onto bulk sales capture sticky revenue from CIDB G6-G7 contractors seeking joint-design liability coverage. |
| East Malaysia Distribution Expansion | First-mover positioning in Sarawak and Sabah infrastructure corridors exploits underpenetrated demand for certified high-performance systems. |
| Hybrid Formulation R&D Partnership | Silicone-polyurethane intermediate development addresses KLCC and TRX district tower specifications for movement-critical curtainwall applications. |
Research Methodology
Document review covered customs and trade databases, CIDB contractor grading registries, and SIRIM QAS International certification records, complemented by interviews with procurement managers at G6-G7 construction firms, technical directors at facade consultancy practices, plant managers at Peninsular Malaysian blending facilities, and distribution channel partners across the Klang Valley. Secondary validation drew from Department of Environment VOC regulation filings, Construction Industry Development Board policy circulars, and petrochemical feedstock price indices. Bottom-up volume estimates from contractor-grade procurement patterns were triangulated against top-down market sizing from chemical import statistics.
Cross-referencing historical certification timeline data with panel input from specification consultants shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, CIDB contractor classification, application criticality, and regional infrastructure corridor penetration. CAGRs were derived from trend extrapolation of specification-grade procurement growth against acrylic substitution headwinds, with photovoltaic installation warranty requirements and semiconductor packaging demand serving as industry-specific volume anchors.
Petrochemical price volatility, SIRIM regulatory timeline shifts, and CIDB grading requirement amendments are the dominant revision risks to the forecast outlook. Deviation in Northeast Asian additive supply reliability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Waterproof Tapes Market
Adhesives & Sealants
Dural Sealant Market
Adhesives & Sealants
Global Silicone Adhesives Market
Adhesives & Sealants
Anti-Tacking Agents Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
South Africa Sealants Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
High Temperature Adhesives Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market