
 Polyurethane Sealant Market | 2026-2036
Polyurethane Sealant Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane Sealant Market Analysis
Buyer concentration in commercial construction is pivoting toward large-scale infrastructure contractors and national building firms that specify certified sealant systems for structural glazing and waterproofing. Sika AG leverages its vertical integration into raw polyol supply to sustain margin control across European project channels. BASF SE anchors its position through R&D intensity in low-VOC moisture-curing formulations. Dow Inc. competes on manufacturing scale, operating multi-continent production networks that service both OEM automotive lines and bulk construction supply.
Polyurethane sealant comprises a reaction product of polyols and isocyanates that cures through atmospheric moisture to form an elastomeric bond with elongation typically exceeding 400%, serving primarily to seal joints against water, air, and chemical ingress while accommodating structural movement. Single-component moisture-curing formulations dominate volume due to simplified field application, though multi-component systems command premium positioning in high-performance aerospace and marine applications where cure control and durability specifications are stringent. Construction absorbs the majority of value, while automotive application represents the fastest-expanding margin pool as OEMs adopt polyurethane for lightweight panel bonding and acoustic management.
REACH in Europe and EPA regulations in the United States restrict solvent-based and high-isocyanate formulations, compelling producers to certify low-emission alternatives for market access. China's MEE enforces GB standards on volatile organic compound content in building materials, reshaping import requirements and domestic formulation practices. Stakeholders must monitor regulatory divergence across these jurisdictions to determine whether regional product adaptation or unified platform strategies offer superior capital efficiency.
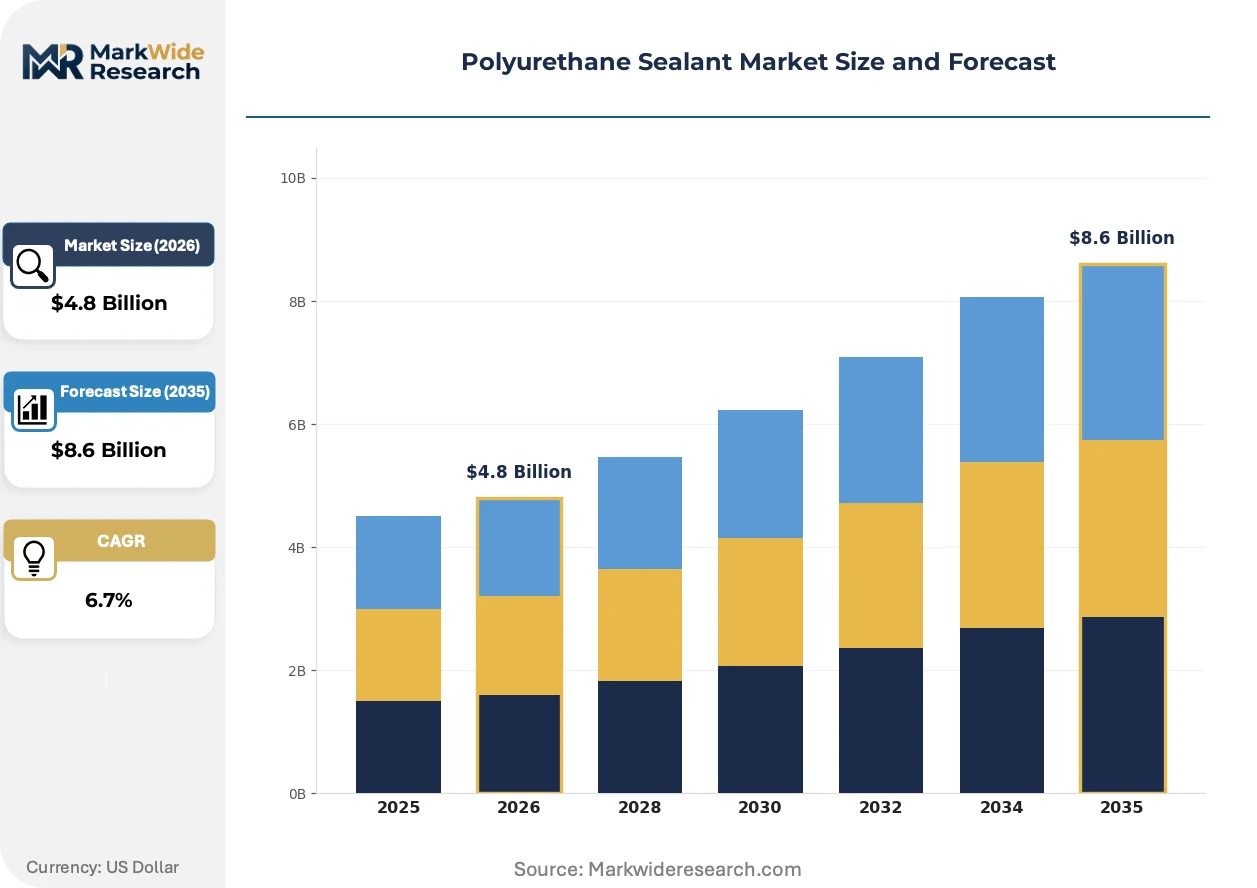
Market Dynamics
REACH compliance deadlines in Europe are forcing simultaneous reformulation across moisture-cure and solvent-based product lines, compressing R&D timelines while raw polyol supply concentrates among integrated chemical majors.
Growth Catalysts
- GB standards enforcement:China's MEE mandates on VOC content in building materials are redirecting procurement toward certified low-emission sealants for infrastructure tenders in Shanghai and Guangdong.
- Structural glazing specification:Commercial architects in Germany and the United Kingdom now require elastomeric joint systems with documented 400%+ elongation for high-rise envelope warranties.
- Lightweight panel bonding:Automotive OEMs specify polyurethane for acoustic-dampening assemblies, displacing mechanical fasteners in electric vehicle platforms.
Market Restraints
- Isocyanate price volatility:MDI feedstock costs fluctuate with crude oil and natural gas benchmarks, squeezing margin on standard-grade construction formulations.
- Technical limitation in extreme climates:Moisture-cure systems face extended tack-free times and compromised adhesion below 5°C, restricting winter application windows in Nordic markets.
- Silicone substitution threat:Neutral-cure silicones with superior UV resistance capture premium facade specification where 25-year service life is mandatory.
Strategic Opportunities
- Underpenetrated repair and maintenance:India's commercial building stock lacks systematic joint inspection protocols, creating first-mover advantage for certified applicator networks in Mumbai and Delhi.
- Dual-cure technology convergence:Hybrid UV-moisture systems enable rapid handling in marine assembly while retaining field-tolerance for complex geometries.
- IRA green building incentives:US tax credits for energy-efficient retrofits accelerate specification of air-sealing sealants in envelope remediation projects.
Industry Challenges
- Formulation chemist scarcity:Expertise in isocyanate-polyol stoichiometry and catalyst latency control concentrates among retiring specialists at major chemical firms.
- Multi-jurisdiction certification lag:Securing concurrent REACH, EPA, and GB standard approvals extends product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane Sealant Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-component, Multi-component, Moisture-curing, Solvent-based Application: Construction, Automotive, Aerospace, Marine End User: OEMs, Contractors, Manufacturers, DIY Enthusiasts Form: Caulk, Cartridge, Bulk, Foam |
| Companies Covered | 3M, Sika AG, H.B. Fuller Company, Henkel AG & Co. KGaA, Arkema, Dow Inc., BASF SE, MAPEI S.p.A, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane Sealant Market Emerging Trajectories
Formulation science is pivoting toward bio-based feedstocks and accelerated cure chemistries as regulatory thresholds on petrochemical content tighten across construction procurement channels.
Silane-terminated polyurethane (STPU) hybrid chemistry is overtaking conventional moisture-cure systems in high-movement joint applications. German facade contractors specify STPU for its primerless adhesion to anodized aluminum and concrete substrates. The technology is compressing installation labor costs while extending service intervals on commercial building envelopes.
REACH authorization requirements for diisocyanates entered full enforcement in August 2023. European formulators must now train downstream applicators on safe handling protocols or withdraw professional-grade products from distribution. Construction chemical distributors in France and Italy are consolidating supplier relationships to reduce compliance documentation burden.
Specification authority is migrating from general contractors to facade engineering consultants who mandate certified applicator networks with documented training records. This pattern displaces open-market bulk purchasing through construction merchants. The shift is most visible in Germany's commercial high-rise sector where warranty-backed installation now precedes material selection.
Polyurethane Sealant Market Segmentation
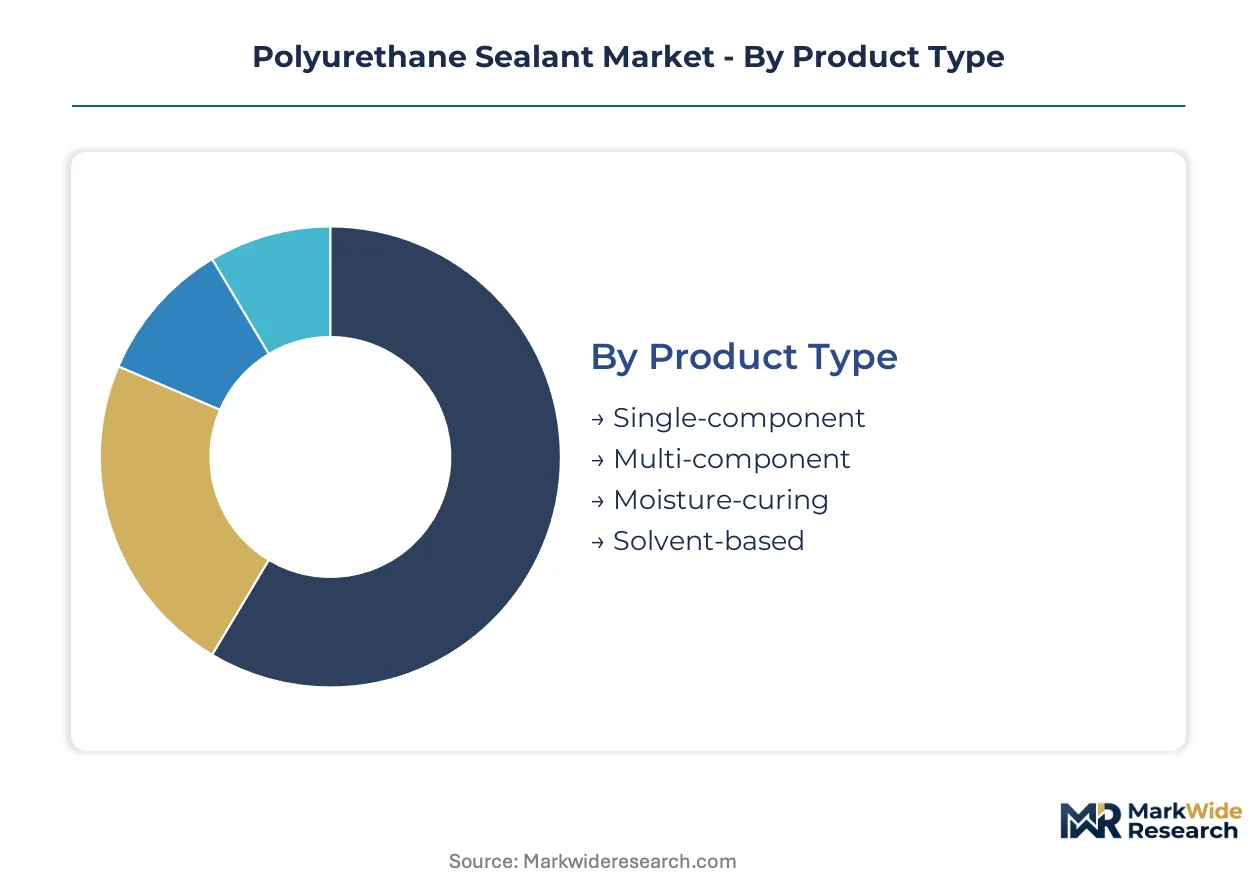
Segmentation in polyurethane sealants reveals how formulation chemistry and delivery format dictate procurement channels, warranty terms, and margin structures. Upgrade cycles differ sharply between construction retrofit work and automotive platform lifecycles, creating distinct replacement-demand rhythms across segments.
Product Type:
Replacement cycles accelerate as building codes tighten and applicator training mandates expand across European and Chinese jurisdictions.
- Single-component:Atmospheric moisture triggers isocyanate-polyol polymerization without field mixing, simplifying application for facade contractors. Demand clusters in German commercial high-rise envelope work where certified applicator networks specify pre-formulated cartridges to meet REACH documentation requirements.
- Multi-component:Metered mixing of base resin and catalyst enables precise cure control for marine and aerospace assemblies. Volume concentrates in Baltic shipyards and French yacht manufacturing where humidity-variable conditions demand tailored gel times.
- Moisture-curing:Ambient humidity drives crosslinking in field-applied construction joints. Chinese infrastructure contractors favor this chemistry for tunnel waterproofing under MEE GB standards compliance.
- Solvent-based:VOC-emitting formulations retain niche positioning in industrial maintenance where rapid tack development overrides emission restrictions. Regulatory pressure from EPA and REACH continues compressing this segment's accessible market.
Volume placements concentrate in Single-component; the faster expansion belongs to Moisture-curing.
Application:
Cost tier stratification separates specification-grade systems from commodity formulations across end-use channels.
- Construction:Structural glazing, waterproofing, and expansion joint sealing absorb the majority of formulation volume. German and UK commercial building codes now mandate elastomeric performance documentation for high-rise envelope warranties.
- Automotive:Polyurethane replaces mechanical fasteners in electric vehicle panel bonding and acoustic-dampening assemblies. OEM specification in Stuttgart and Shanghai production lines drives premium-grade demand.
- Aerospace:Fuel-resistant formulations seal airframe joints and fuel tank access panels. Certification timelines with FAA and EASA extend product development cycles.
- Marine:Saltwater-resistant elastomers seal deck-to-hull interfaces and through-hull fittings. Scandinavian and Mediterranean shipyards specify systems with documented 25-year service intervals.
Construction commands absolute volume leadership; Automotive climbs the fastest as lightweighting mandates proliferate.
End User:
Customer type determines whether procurement flows through certified applicator networks or open merchant distribution.
- OEMs:Automotive and marine manufacturers specify sealant systems at platform design stage, locking in multi-year supply agreements with documented batch traceability.
- Contractors:Commercial construction firms in Germany and China increasingly source through facade engineering consultants who mandate certified applicator credentials.
- Manufacturers:Industrial equipment builders integrate sealants into original assembly processes, requiring technical service support for substrate-specific adhesion protocols.
- DIY Enthusiasts:Home improvement channels move standard-grade cartridges through construction merchants, though regulatory training requirements in Europe constrain professional-grade access.
Contractor channel placements dominate value capture; OEM direct specification gains share fastest as platform integration deepens.
Form:
Packaging format shapes logistics economics and field productivity across project scales.
- Caulk:Sausage-pack formulations reduce packaging waste for high-volume commercial joint sealing. German contractors favor this format for continuous bead application on large facade projects.
- Cartridge:Standard 310ml and 600ml cartridges serve repair-maintenance and residential construction through merchant distribution. Chinese infrastructure tenders increasingly specify cartridge-based certified products for quality traceability.
- Bulk:Drum and pail delivery supports OEM manufacturing lines and large-scale construction projects with automated dispensing equipment.
- Foam:Expanding polyurethane foam seals irregular cavities and penetrations in building envelopes, competing with specialized sealant formulations in rough-opening applications.
Cartridge shipments lead in unit volume; Bulk format expands most quickly as manufacturing integration intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest share of polyurethane sealant volume through infrastructure tenders and automotive platform integration, while European demand concentrates in certified high-performance formulations for commercial envelope work.
China
Shanghai and Guangdong infrastructure contractors specify low-VOC sealants under MEE GB standards compliance for tunnel waterproofing and high-rise glazing projects. The country's dual carbon goals accelerate procurement shifts toward certified formulations in state-led construction tenders. Yangtze River Delta manufacturing clusters supply both domestic automotive OEMs and export markets with moisture-curing systems.
Germany
Commercial architects in Berlin and Frankfurt mandate elastomeric joint systems with documented 400% elongation for structural glazing warranties on high-rise envelopes. REACH diisocyanate authorization requirements force certified applicator networks and reformulation investments across moisture-cure product lines. Bavaria's industrial corridor hosts formulation R&D facilities serving Central European project channels.
United States
IRA green building tax credits accelerate air-sealing sealant specification in envelope remediation projects across commercial retrofit markets. EPA regulations restrict solvent-based formulations, compressing accessible markets for high-emission products. Texas and California construction corridors drive bulk procurement through national building firms and infrastructure contractors.
India
Mumbai and Delhi commercial building stock lacks systematic joint inspection protocols, creating expansion space for certified applicator networks in repair and maintenance channels. BIS standards on construction chemical performance reshape import requirements and domestic formulation practices. Western and Southern industrial zones concentrate automotive sealant demand from expanding OEM assembly operations.
Japan
Tokyo and Osaka automotive manufacturers specify polyurethane for lightweight panel bonding in electric vehicle platforms, displacing mechanical fasteners. METI industrial standards enforce quality certification for structural adhesive applications in transportation assembly. Kanto region chemical producers supply precision-formulated systems to domestic aerospace and marine assembly clusters.
Polyurethane Sealant Market Vendor Landscape
German and Swiss producers anchor the premium formulation tier; Chinese and American specialists hold volume positions in construction and automotive supply. The vendor base separates into three strategic tiers: integrated chemical majors with captive polyol supply, mid-scale regional formulators with certified applicator networks, and commodity distributors serving merchant channels. Competitive moves concentrate on backward integration into raw material supply and multi-jurisdiction certification acceleration.
Among European-integrated chemical producers, Sika AG, BASF SE, and Dow Inc. exemplify distinct strategic positions. Sika AG represents the vertically integrated archetype with control over raw polyol supply chains. BASF SE anchors the R&D-intensive tier through formulation investments in low-emission chemistries. Dow Inc. occupies the scale-driven position with multi-continent manufacturing footprints serving both construction bulk supply and OEM automotive lines.
| Leading Market Players |
|---|
| 3M |
| Sika AG |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Arkema |
| Dow Inc. |
| BASF SE |
| MAPEI S.p.A |
| Huntsman Corporation |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap German formulators with generational ownership structures maintain pricing discipline through captive applicator networks, while their reliance on spot-market MDI purchases exposes margins to feedstock volatility that integrated chemical majors avoid through backward integration into polyol production.
Pricing Analysis
Volume placements cluster in standard-grade moisture-curing cartridges where Chinese infrastructure tenders drive procurement scale, while premium formulations for structural glazing warranties in Germany and the United Kingdom command substantial margin premiums through certified applicator channel control. Pricing stratifies across REACH-certified premium tiers, MEE-compliant mid-market grades, and uncertified economy formulations for industrial maintenance. Cost compression in standard construction grades intensifies as Yangtze River Delta producers expand export capacity. OEM automotive buyers exhibit lowest price sensitivity due to platform-locked supply agreements, while merchant-channel contractors in India face acute pressure from unbranded local alternatives.
Supply Chain Analysis
Reverse-logistics flows for expired or off-specification sealants remain underdeveloped across all producing regions, creating latent liability for distributors managing REACH documentation trails on aged inventory. Raw material supply concentrates in Germany, China, and the United States where integrated chemical majors control polyol and isocyanate production. Formulation draws from MDI feedstocks, specialty polyols, and catalyst packages sourced through multi-year contracts with quarterly price adjustments. Single-source vulnerability concentrates in Baltic-region marine-grade catalyst suppliers serving Scandinavian shipyards. Distribution runs through certified applicator networks for premium construction grades, while bulk drum supply feeds OEM automotive lines directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory certification lag functions as a consolidation mechanism, forcing sub-scale formulators without dedicated compliance teams to exit or sell as REACH, EPA, and MEE deadlines compress simultaneously.
For Market Incumbents: Hedge margin exposure in standard-grade construction formulations by accelerating captive polyol supply investments in Central European production corridors, while building documented applicator training infrastructure to defend specification authority against silicone substitution in German facade markets. Prioritize STPU hybrid chemistry R&D to capture structural glazing upgrade cycles before patent-protected entrants consolidate high-movement joint applications. For New Entrants and Emerging Players: The gap between premium certified applicator-channel pricing and economy-grade merchant distribution offers entry space for mid-tier formulators with MEE-compliant platforms targeting Shanghai and Guangdong infrastructure tenders. India's repair and maintenance channels present the most penetrable geography given absent systematic joint inspection protocols. Pursue certified applicator network partnerships as the primary go-to-market mechanism rather than open merchant distribution. For Investors and Strategic Acquirers: REACH diisocyanate authorization enforcement completion is the leading indicator that European formulation assets will trade at scarcity premiums as compliance documentation becomes non-replicable. The five-to-ten-year viability window favors acquisition of mid-scale German or Swiss formulators with established applicator networks and captive raw material supply. Monitor Baltic marine-grade catalyst supplier consolidation as the signal for broader specialty chemical supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Supply | Sika AG's captive raw material production insulates margin from MDI price volatility in European project channels. |
| Dual-Cure Technology Development | Hybrid UV-moisture systems enable marine assemblers to compress handling times while retaining field tolerance for complex geometries. |
| Certified Applicator Network Expansion | BASF SE's documented training infrastructure satisfies REACH authorization requirements while locking out unqualified competitors. |
| MEE GB Standards Pre-Certification | Early compliance positioning captures Shanghai infrastructure tender flows before domestic Chinese formulators upgrade formulations. |
| STPU Hybrid Chemistry Patent Filing | Primerless adhesion to anodized aluminum secures specification authority from German facade engineering consultants. |
Methodological Framework
Multi-period observation of formulation patent filings, regulatory submission timelines, and certified applicator network expansions anchored the trend analysis, supplemented by interviews with plant managers at polyol production facilities, procurement leads at automotive OEMs, distribution channel partners in German construction chemicals, technical R&D directors at sealant formulators, and facade engineering consultants specifying structural glazing systems. Secondary validation drew from ECHA REACH authorization databases, EPA VOC emission filings, Chinese MEE GB standards documentation, customs and trade data for MDI and polyol movements, and SEC 10-K disclosures from integrated chemical majors. Bottom-up segment sizing triangulated against top-down construction spending and automotive production forecasts.
Segment-weighting across product type, application, end user, and form dimensions calibrated volume and value distributions throughout the forecast period. CAGRs derived from elasticity-adjusted demand modeling incorporating regulatory enforcement schedules, platform lifecycle transitions in electric vehicle assembly, and infrastructure spending patterns across the analysis window. Industry-specific inputs included REACH diisocyanate training mandate compliance curves, MEE GB standards adoption rates in provincial tenders, and STPU hybrid chemistry penetration trajectories in German commercial high-rise construction.
Underlying measurement precision varies by segment; certified applicator network coverage and REACH-compliant formulation volumes carry tighter precision than informal merchant-channel estimates in emerging markets. Forecasts reflect assumptions on regulatory enforcement continuity, feedstock price correlation stability, and substitution elasticity between polyurethane and silicone chemistries. Material deviation in REACH authorization timelines, MEE inspection intensity, or MDI supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
Corrosion Protection Tapes Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
South America Contact Adhesives Market
Adhesives & Sealants
Spain Sealants Market
Adhesives & Sealants
Nigeria Tile Adhesive Market