
 Global Solvent Evaporation Market | 2026-2036
Global Solvent Evaporation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solvent Evaporation Market Foresight
Pharmaceutical synthesis demand is shifting toward high-purity, low-temperature evaporation systems as biologic drug portfolios expand. Thermo Fisher Scientific sustains broad application coverage across research and production environments. BUCHI Labortechnik AG specializes in precision rotary evaporation for analytical laboratories. Yamato Scientific Co., Ltd. anchors Asian supply chains with manufacturing scale in Japan.
Solvent evaporation removes volatile organic compounds from liquid mixtures through controlled heat and pressure reduction, typically operating between 20°C and 150°C depending on vacuum level and solvent boiling point. The process recovers purified solvents for reuse while concentrating dissolved solids or active ingredients. Rotary evaporators dominate academic and small-batch pharmaceutical settings due to operational flexibility and lower capital requirements. Mechanical vapor recompression leads technology adoption where energy costs pressure operating margins, while vacuum evaporators capture share in heat-sensitive cosmetic and food applications. Thin film evaporators command premium positioning in continuous chemical processing.
EPA effluent guidelines and EU REACH substance restrictions compel manufacturers to invest in closed-loop solvent recovery rather than single-pass discharge. FDA current good manufacturing practice standards for pharmaceutical equipment validation further shape product design and documentation requirements. Japan's METI chemical management framework and South Korea's MFDS manufacturing standards add compliance layers for exporters. Stakeholders must weigh energy efficiency upgrades against regulatory compliance timelines when prioritizing capital deployment.
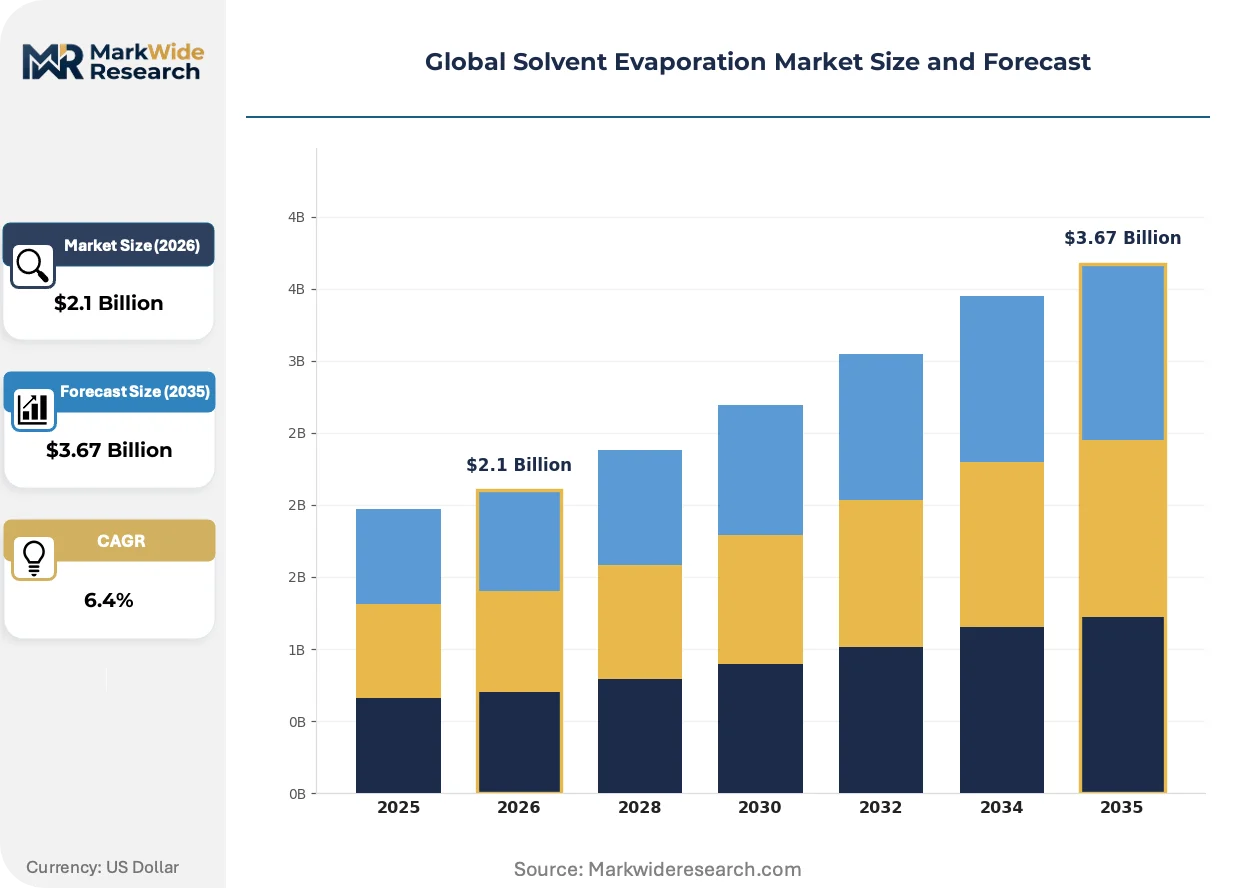
Market Dynamics
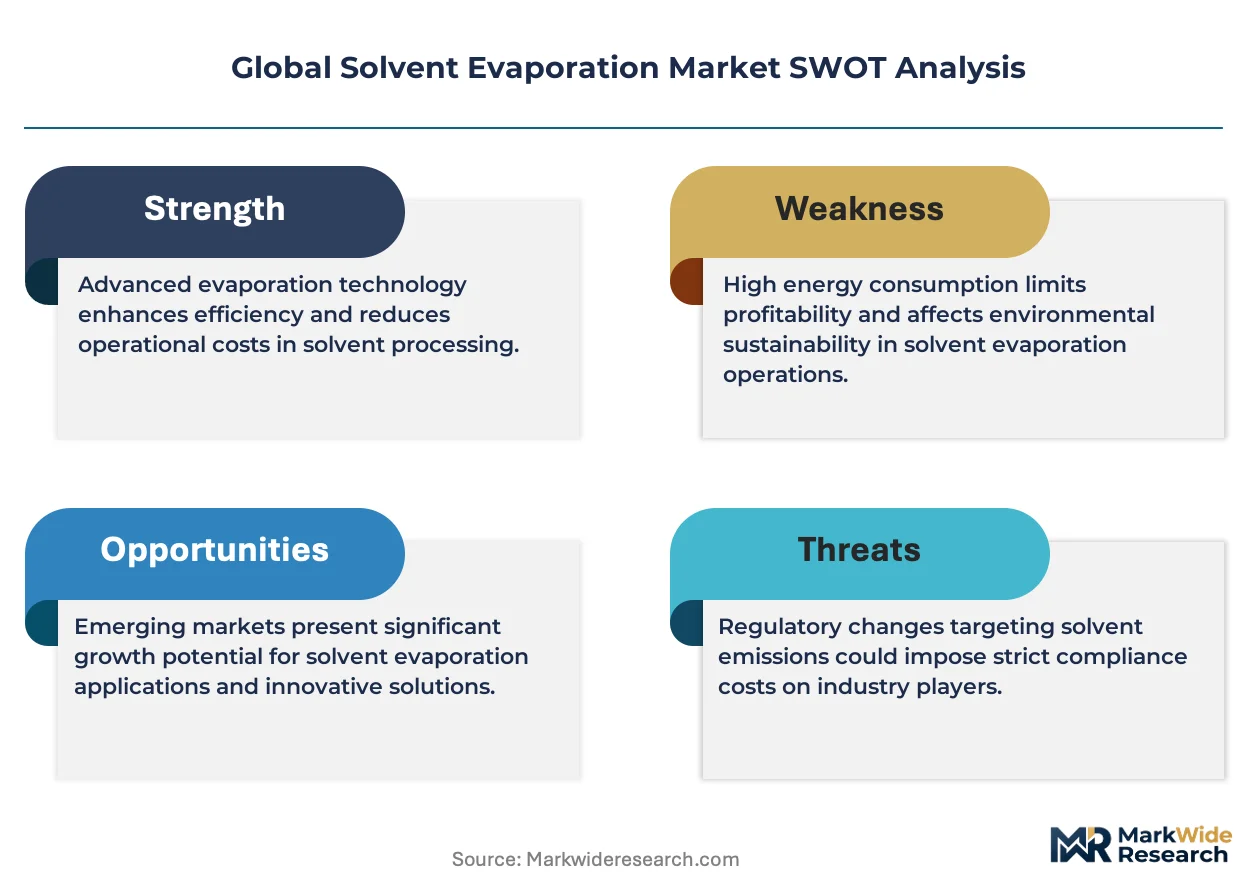
Mechanical vapor recompression technology is compressing operating margins for conventional thermal evaporator suppliers while pharmaceutical manufacturers accelerate closed-loop solvent recovery investments to preempt EPA and EU REACH enforcement escalation.
Growth Catalysts
- EPA Effluent Guideline Tightening:Pharmaceutical manufacturers in the United States are retrofitting facilities with vacuum recovery systems to meet pending discharge limit reductions for volatile organic compounds.
- Biologic Drug Portfolio Expansion:Heat-sensitive biologic synthesis is pulling demand toward low-temperature thin film evaporators that protect protein integrity during concentration.
- Contract Manufacturing Clustering:India and South Korea are attracting multi-site solvent recovery infrastructure investments as global pharmaceutical outsourcing concentrates in these geographies.
Market Restraints
- Stainless Steel Input Volatility:Evaporator vessel fabrication depends on nickel and chromium price swings that compress equipment margins during procurement cycles.
- German Technology Supplier Concentration:Mechanical vapor recompression compressor fabrication concentrates among a limited set of precision engineering suppliers in southern Germany.
- Heat Pump Efficiency Ceiling:Mechanical vapor recompression systems face thermodynamic limits when processing high-boiling-point solvents above 150°C.
Strategic Opportunities
- India Pharmaceutical Manufacturing:Domestic formulation capacity expansion under the country's PLI scheme is creating first-time demand for industrial-scale solvent recovery systems.
- EU Green Deal Industrial Emissions:Carbon border adjustment mechanisms are incentivizing European chemical processors to upgrade from single-pass to closed-loop evaporation.
- Digital Twin Convergence:Integration of predictive maintenance algorithms with mechanical vapor recompression units is enabling remote optimization of energy consumption profiles.
Industry Challenges
- Vacuum System Integration Complexity:Retrofitting legacy batch pharmaceutical plants with continuous thin film evaporators requires extensive piping reconfiguration and downtime coordination.
- FDA Equipment Validation Timelines:Current good manufacturing practice documentation for new solvent recovery installations extends commissioning cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solvent Evaporation Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Evaporators, Thin Film Evaporators, Falling Film Evaporators, Vacuum Evaporators, Spray Evaporators Technology: Mechanical Vapor Recompression, Thermal Vapor Recompression, Short Path Evaporation, Freeze Evaporation, Flash Evaporation Application: Pharmaceutical Synthesis, Chemical Processing, Food & Beverage Concentration, Pulp & Paper, Cosmetics Manufacturing End User: Chemical Manufacturers, Pharmaceutical Companies, Food Processors, Cosmetic Producers, Research Laboratories |
| Companies Covered | Yamato Scientific Co., Ltd., Thermo Fisher Scientific Inc., BUCHI Labortechnik AG, Porvair PLC, IKA-Werke GmbH & Co. KG, Heidolph Instruments GmbH & Co. KG, Biotage AB, Organomation Associates, Inc., Labconco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solvent Evaporation Market Shifts & Advancements
Equipment architecture is fragmenting between centralized multi-effect systems for commodity chemical processing and modular skid-mounted units serving distributed pharmaceutical manufacturing networks.
Mechanical vapor recompression is decentralizing solvent recovery infrastructure by enabling site-level energy autonomy without steam utility dependence. Mid-sized pharmaceutical manufacturers in Japan and Germany are deploying these systems to isolate operations from district heating price volatility. This technology is decentralizing capital planning away from centralized utility investments toward distributed equipment ownership models.
EU REACH substance restriction expansions are compelling chemical processors to document solvent fate through entire production chains. The regulation is forcing substitution of chlorinated solvents with recoverable alcohol-based alternatives in coating and cleaning applications. Pharmaceutical exporters to Europe are retrofitting validation protocols to satisfy ECHA substance of very high concern disclosure requirements.
Equipment-as-a-service contracting is displacing traditional capital purchase arrangements for evaporator systems in North American contract manufacturing. Third-party solvent recovery specialists are installing and operating units on pharmaceutical customer sites, charging per-liter processing fees. This model concentrates in New Jersey and Pennsylvania where toll manufacturing density supports shared infrastructure economics.
Global Solvent Evaporation Market Segmentation
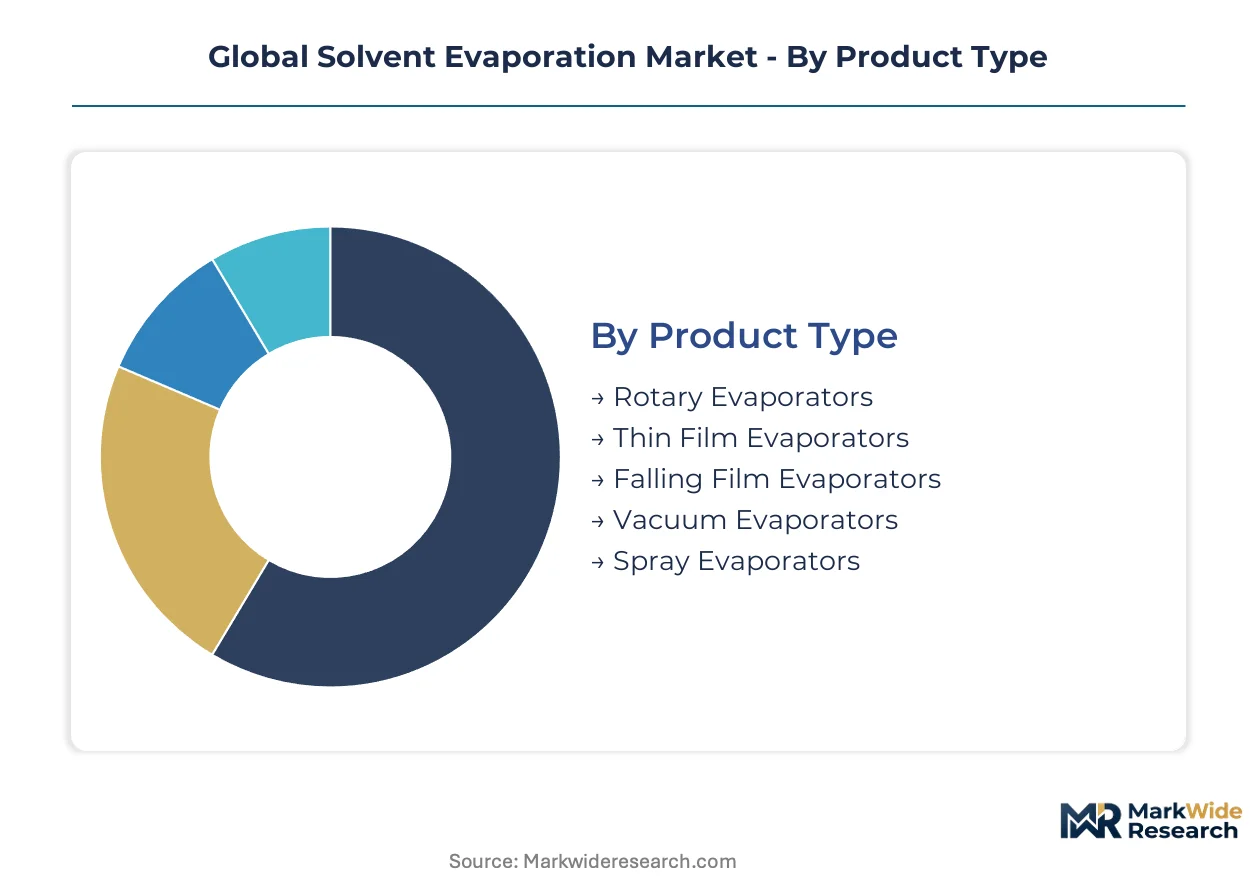
Solvent evaporation equipment serves divergent operational requirements across laboratory research and industrial production. Technology selection hinges on batch versus continuous processing needs, energy cost structures, and regulatory discharge constraints. Equipment specifications vary dramatically between pharmaceutical validation environments and commodity chemical throughput operations.
Product Type:
Volume concentration favors established thermal designs, while premium positioning attaches to specialized thin film systems for heat-sensitive applications.
- Rotary Evaporators:Batch-operated glass vessels with rotating flasks maximize surface area for gentle solvent removal under vacuum. Academic institutions and small-batch pharmaceutical developers in Germany and Japan favor these units for formulation flexibility and lower capital barriers.
- Thin Film Evaporators:Wiped or scraped surface designs maintain thin liquid films against heated walls for rapid evaporation with minimal thermal exposure. Biologic drug manufacturers specify these systems to protect protein integrity during active pharmaceutical ingredient concentration.
- Falling Film Evaporators:Gravity-fed liquid distribution across vertical tube bundles enables high-throughput continuous processing in large-scale chemical plants.
- Vacuum Evaporators:Reduced pressure operation lowers boiling points for temperature-critical separations in cosmetic and natural extract applications.
- Spray Evaporators:Atomized liquid injection into heated chambers handles viscous or solid-laden feeds in specialty chemical recovery.
Mature deployment sits with rotary evaporators. Newer deployment is concentrated in thin film systems for biologic manufacturing.
Technology:
Energy recovery mechanisms differentiate cost structures between steam-dependent thermal systems and electrically driven mechanical compression.
- Mechanical Vapor Recompression:Electric compressors elevate vapor pressure and temperature for reuse as heating steam, slashing external energy demand. Chemical processors in Germany deploy these systems to isolate operations from district heating price volatility.
- Thermal Vapor Recompression:Steam ejectors entrain and compress vapor using high-pressure steam motive force, prevalent where steam utilities remain cost-competitive.
- Short Path Evaporation:Molecular distillation at high vacuum separates heat-sensitive compounds with minimal residence time.
- Freeze Evaporation:Sublimation-based solvent removal preserves structural integrity of delicate biological materials.
- Flash Evaporation:Rapid pressure reduction induces instantaneous boiling for continuous feed concentration in pulp processing.
Mechanical vapor recompression dominates new industrial installations. Thermal recompression retains position in legacy chemical corridors with captive steam generation.
Application:
Regulatory stringency varies sharply between pharmaceutical validation requirements and food-grade concentration standards.
- Pharmaceutical Synthesis:FDA current good manufacturing practice compliance dictates equipment validation documentation, extended commissioning timelines, and closed-loop solvent recovery to meet EPA effluent guidelines.
- Chemical Processing:EU REACH substance restrictions compel processors to document solvent fate and substitute chlorinated compounds with recoverable alcohol-based alternatives.
- Food & Beverage Concentration:Thermal sensitivity of flavor compounds drives vacuum evaporator specification for juice and extract processing.
- Pulp & Paper:Black liquor concentration relies on multi-effect evaporator trains for chemical recovery and energy integration.
- Cosmetics Manufacturing:Botanical extract concentration demands low-temperature operation to preserve volatile aromatic compounds.
Pharmaceutical synthesis commands premium equipment specifications. Chemical processing represents the largest installed base volume.
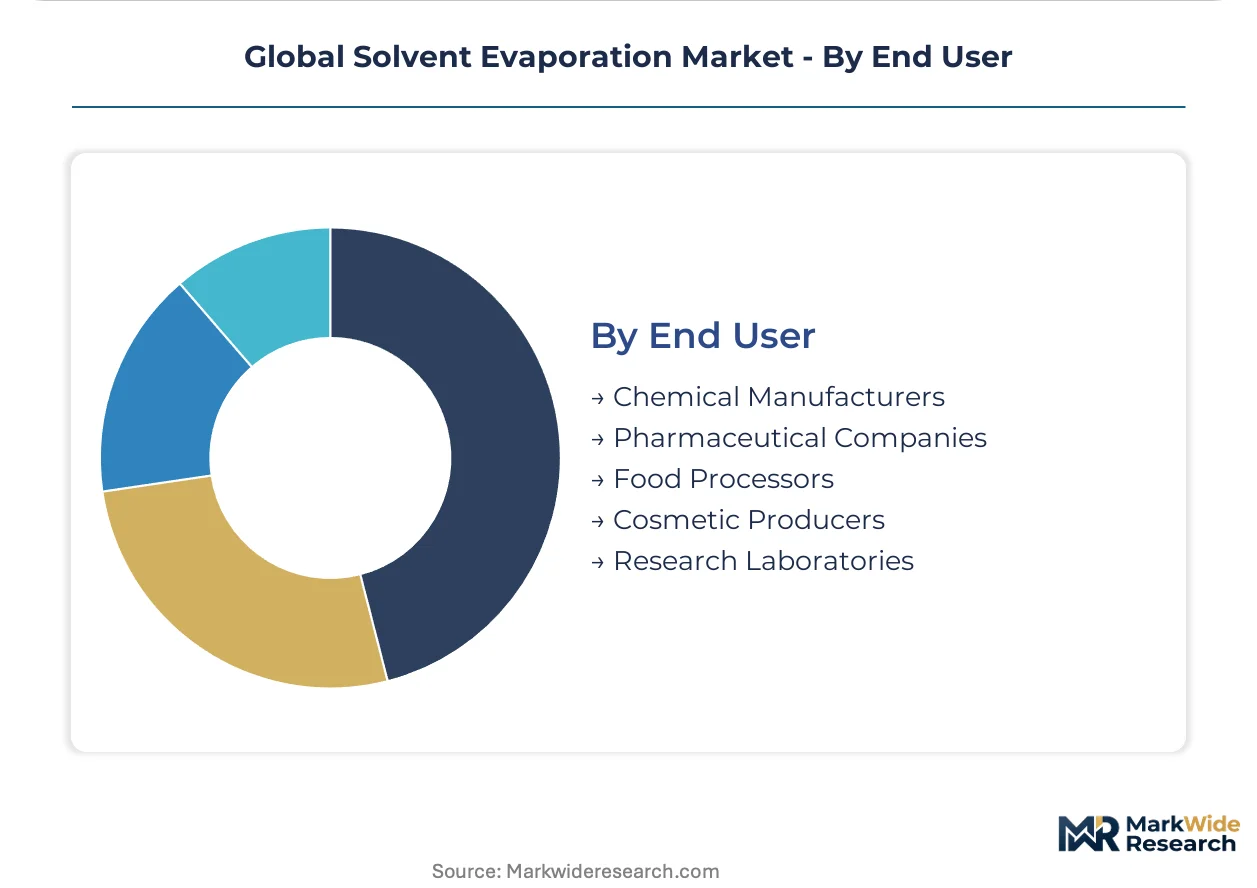
End User:
Capital deployment patterns separate centralized multi-site chemical producers from distributed contract manufacturing networks.
- Chemical Manufacturers:Integrated petrochemical and specialty chemical producers operate centralized evaporator batteries with utility-scale energy recovery.
- Pharmaceutical Companies:Multi-national drug makers balance captive manufacturing against toll manufacturing partnerships in India and South Korea.
- Food Processors:Seasonal agricultural input drives demand for flexible capacity in juice and dairy concentration.
- Cosmetic Producers:Natural ingredient sourcing concentrates evaporator demand in France and Switzerland for premium skincare formulations.
- Research Laboratories:Universities and contract research organizations favor bench-scale rotary evaporators for method development and small-batch synthesis.
Pharmaceutical companies are expanding fastest. Chemical manufacturers represent the most mature equipment replacement cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures precision evaporator components for export, while India and South Korea absorb capacity through contract pharmaceutical manufacturing expansion. Japan maintains integrated domestic supply chains for laboratory and industrial systems.
United States
Pharmaceutical manufacturers in New Jersey and Pennsylvania retrofit facilities with vacuum recovery systems to meet pending EPA effluent guideline reductions for volatile organic compounds. FDA current good manufacturing practice standards extend equipment validation timelines by twelve to eighteen months. Toll manufacturing density around Philadelphia supports equipment-as-a-service contracting models for solvent recovery infrastructure.
Germany
Chemical processors deploy mechanical vapor recompression systems to isolate operations from district heating price volatility in the Ruhr industrial corridor. EU REACH substance restrictions compel documentation of solvent fate through entire production chains. Precision engineering suppliers in southern Germany concentrate compressor fabrication for mechanical vapor recompression technology.
Japan
METI chemical management frameworks add compliance layers for pharmaceutical equipment exporters serving Asian markets. Domestic biologic drug portfolios expand demand for low-temperature thin film evaporators protecting protein integrity. Manufacturing scale in Tokyo and Osaka anchors regional supply chains for rotary and thin film systems.
India
Domestic formulation capacity expansion under the PLI scheme creates first-time demand for industrial-scale solvent recovery systems. CDSCO manufacturing standards shape equipment validation protocols for export-oriented pharmaceutical producers. Contract manufacturing clusters in Hyderabad and Ahmedabad attract multi-site solvent recovery infrastructure investments from multinational drug makers.
South Korea
MFDS manufacturing standards regulate equipment validation for pharmaceutical exporters to European and North American markets. Biologic synthesis facilities in Songdo and Incheon specify low-temperature evaporators for heat-sensitive active pharmaceutical ingredient concentration. Government-backed biotech incubators accelerate adoption of closed-loop solvent recovery in research-scale operations.
Global Solvent Evaporation Market Competitive Landscape
Top-tier vendors anchor pharmaceutical and analytical laboratory segments, while mid-tier fabricators serve commodity chemical processing and regional contract manufacturing markets. The competitive structure fragments across precision engineering specialists in Germany and Japan, diversified laboratory equipment conglomerates with broad application coverage, and regional fabricators in India and South Korea scaling for domestic pharmaceutical growth. Strategic moves concentrate on technology licensing for mechanical vapor recompression compressors and geographic expansion through distribution partnerships in emerging pharmaceutical manufacturing clusters.
Among diversified laboratory equipment conglomerates, Thermo Fisher Scientific Inc. represents broad application coverage across research and production environments, while Yamato Scientific Co., Ltd. exemplifies integrated Asian supply chain positioning with manufacturing scale in Japan. Within the precision engineering specialist tier, BUCHI Labortechnik AG occupies a position exemplifying analytical laboratory focus, and IKA-Werke GmbH & Co. KG anchors German fabrication expertise for rotary evaporation systems.
| Leading Market Players |
|---|
| Yamato Scientific Co., Ltd. |
| Thermo Fisher Scientific Inc. |
| BUCHI Labortechnik AG |
| Porvair PLC |
| IKA-Werke GmbH & Co. KG |
| Heidolph Instruments GmbH & Co. KG |
| Biotage AB |
| Organomation Associates, Inc. |
| Labconco Corporation |
| Others |
Supply & Pricing Matrix
Backward integration into precision compressor fabrication anchors both supply security and pricing power for mechanical vapor recompression system suppliers, while stainless steel input volatility feeds directly into equipment margin compression across German and Japanese manufacturing bases.
Pricing Analysis
Short lead-time premiums command pricing separation in pharmaceutical validation environments where FDA equipment qualification timelines extend commissioning cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Pricing pressure stems from nickel and chromium price swings compressing equipment margins during procurement cycles. Contract research organizations exhibit highest price sensitivity, while multi-national pharmaceutical companies absorb premium positioning for validated systems.
Supply Chain Analysis
Dual-sourcing requirements for precision compressor components mandate multi-supplier qualification among pharmaceutical equipment buyers seeking to isolate operations from German supplier concentration risk. Manufacturing concentrates in Germany, Japan, and Switzerland for precision engineering components. Stainless steel vessel fabrication draws from nickel and chromium supply chains tethered to mining operations in Indonesia and South Africa. Tariff exposure on precision-engineered compressor units from southern Germany suppliers concentrates supply chain risk. Distribution runs through direct OEM sales for large pharmaceutical accounts and specialized laboratory equipment distributors for research-scale installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical vapor recompression technology consolidation is accelerating as energy cost pressures force conventional thermal evaporator suppliers toward exit or acquisition, compressing viable vendor counts in industrial-scale solvent recovery.
For Market Incumbents: Deploy technology licensing as the primary lever to capture recurring revenue from compressor fabrication expertise while insulating against stainless steel margin compression. Expand captive validation documentation services to extend customer lock-in beyond equipment sale. Acquire regional fabricators in India and South Korea to anchor presence in contract manufacturing growth clusters before local players consolidate distribution control. For New Entrants and Emerging Players: The mid-tier price-point gap between premium German-engineered systems and economy Chinese imports offers entry space for validated equipment at 15-20% discount to incumbent positioning. Target Indian pharmaceutical formulation expansion under PLI scheme incentives as the most penetrable geography. Pursue equipment-as-a-service contracting models to bypass capital purchase barriers among North American toll manufacturers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified laboratory equipment conglomerates seeking mechanical vapor recompression capabilities. Long-term viability favors precision engineering specialists with captive compressor technology and established FDA validation protocols. Watch for EPA effluent guideline enforcement escalation as the signal indicating accelerated retrofit demand and valuation inflection for solvent recovery specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | German precision engineering firms monetize compressor expertise without capital-intensive manufacturing expansion. |
| Backward Integration into Stainless Steel Vessel Fabrication | Vertical control over nickel-chromium input costs insulates margins from commodity price volatility cycles. |
| Equipment-as-a-Service Contracting Model | Third-party operators capture recurring revenue from Philadelphia-New Jersey toll manufacturing density clusters. |
| Regulatory Validation Documentation Investment | FDA current good manufacturing practice compliance creates twelve-to-eighteen month customer switching costs. |
| Geographic Expansion through Distribution Partnership | Hyderabad and Ahmedabad manufacturing clusters attract multi-site infrastructure investments from multinational drug makers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving pharmaceutical plant engineers, equipment procurement leads at contract manufacturers, aftermarket service heads, and regulatory affairs specialists. EPA effluent guideline dockets, FDA 483 inspection observations, EU REACH substance restriction updates, and CDSCO manufacturing standard notifications supplied regulatory trajectory inputs. Bottom-up equipment shipment tallies triangulated against top-down pharmaceutical capital expenditure disclosures.
Product-type granularity modeled rotary, thin film, falling film, vacuum, and spray evaporator configurations separately across pharmaceutical synthesis, chemical processing, food concentration, pulp recovery, and cosmetic extraction applications. Technology-level differentiation captured mechanical vapor recompression, thermal vapor recompression, short path, freeze, and flash evaporation architectures. End-user segmentation distinguished captive chemical manufacturers, pharmaceutical companies, food processors, cosmetic producers, and research laboratories. CAGRs derived from regression analysis of historical equipment shipment patterns against pharmaceutical manufacturing capacity expansion timelines and regulatory enforcement intensity indices.
Inputs from customs records and regulatory filing databases were available through the study window; gaps in real-time stainless steel procurement pricing introduce uncertainty bands around equipment margin forecasts. Deviation in EPA effluent guideline enforcement timing or EU REACH substance restriction expansion scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Alpha-Methylstyrene Market
Solvents
Hydrophobic Solvents Market
Solvents
Butane Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Global Tert-Butanol Market
Solvents
Global Nitrochlorobenzene Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Electronic Cleaning Solvents Market
Solvents
1,2-Ethanedithiol Market
Solvents
Isopropylamine Market
Solvents
Coating Solvents Market
Solvents
Allyl Cyanide Market
Solvents
Global Bio Solvents Market
Solvents
Tetraethyl Benzene Market
Solvents
2,2-Dimethylbutyryl Chloride Market
Solvents
Citrus Solvents Market