
 Chemical Anchors Market | 2026-2036
Chemical Anchors Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Anchors Market Intelligence
Subscription-based anchor inspection and recertification services is hardening as a recurring revenue layer alongside product sales. Hilti Corporation leverages its fleet of direct-service technicians to lock in long-term maintenance contracts. Simpson Strong-Tie Company, Inc. anchors its competitive stance through specialized training programs for structural engineers. Sika AG extends its position by bundling chemical anchors with waterproofing membranes in bundled project bids.
Chemical anchors are resin-based fastening systems that bond threaded rods or rebar into concrete and masonry substrates, typically achieving pull-out strengths exceeding 15 kN in cracked concrete applications. Epoxy formulations dominate structural heavy-load applications due to their extended working time and high bond strength, while vinylester grades are displacing polyester in corrosive marine environments. The contractor end-user segment controls the largest volume channel, though DIY enthusiasts represent the fastest-growing demand pool through online retail channels. Wholesale distributors still occupy the margin-rich core for bulk infrastructure projects.
Federal Highway Administration guidelines and OSHA fall-protection standards in the United States shape product certification requirements and installation training mandates. The EU Construction Products Regulation and ECHA REACH restrictions on styrene emissions constrain polyester anchor formulations in European markets. Stakeholders must monitor evolving seismic design codes and low-VOC material mandates as these frameworks increasingly determine market access and product substitution patterns.
Market Dynamics
Infrastructure retrofit mandates across aging concrete structures are compressing specification cycles for high-performance fastening systems, while ECHA REACH restrictions on styrene emissions force polyester formulation phase-outs.
Growth Catalysts
- Federal infrastructure stimulus:United States federal funding directs procurement toward vinylester systems for bridge and tunnel rehabilitation, creating sustained demand pull through 2035.
- Seismic code evolution:Updated seismic design standards in Japan and California mandate post-installed rebar connections in new commercial construction, expanding epoxy anchor specifications.
- Marine corrosion resistance:Vinylester grades displace polyester in offshore wind turbine foundations and coastal infrastructure exposed to saltwater degradation.
Market Restraints
- Raw material concentration:Epoxy resin supply concentrates among Asian petrochemical producers, exposing formulators to bisphenol-A price volatility and freight cost spikes.
- Styrene emission caps:ECHA REACH restrictions on volatile organic compounds constrain polyester anchor production volumes across European manufacturing facilities.
- Mechanical anchor substitution:Expansion anchors capture light-duty applications in non-cracked concrete where pull-out requirements fall below 10 kN.
Strategic Opportunities
- DIY channel penetration:Online retail platforms in Germany and Australia unlock homeowner renovation demand through cartridge-format anchor kits with simplified installation instructions.
- Inspection service bundling:Subscription-based recertification contracts for installed anchors generate recurring revenue alongside initial product sales.
- Waterproofing integration:Bundled project bids combining chemical anchors with membrane systems capture specification control in below-grade construction.
Industry Challenges
- Installation certification gaps:OSHA fall-protection mandates require trained technicians for elevated work, constraining contractor deployment capacity.
- Pull-out testing standardization:Divergent national protocols for cracked concrete testing delay product approvals and fragment quality benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Anchors Market |
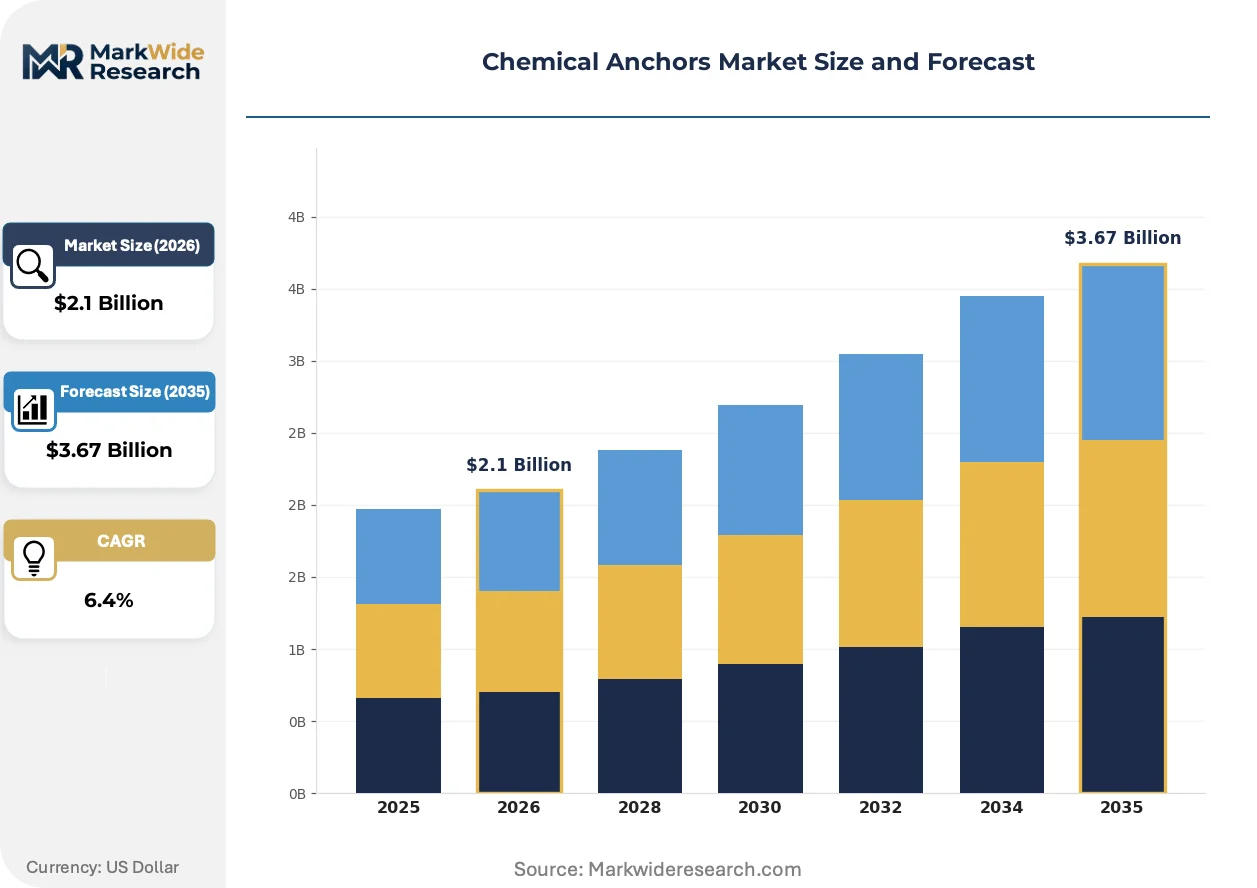
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyester, Vinylester, Methacrylate Application: Construction, Infrastructure, Automotive, Marine End User: Contractors, Engineers, Manufacturers, DIY Enthusiasts Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | BASF SE, Fischer Group, Hilti Corporation, Fosroc, Inc., Illinois Tool Works, Sika AG, Henkel AG & Co. KGaA, EJOT, Simpson Strong-Tie Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Anchors Market Strategic Shifts & Innovations
Formulation chemistry and service delivery models are converging to reshape competitive positioning, with regulatory compliance and digital distribution emerging as decisive vectors.
Hybrid vinylester-epoxy formulations are absorbing specification share in heavy-load applications previously reserved for pure epoxy systems. Infrastructure contractors in Germany and Japan specify these hybrids for their compressed cure times and comparable bond strength. The technology is absorbing working-time advantages from both parent chemistries while compressing project schedules.
REACH-aligned construction product regulations in Europe now mandate third-party pull-out testing for structural fixings under updated CE marking requirements. German regulators at KBA extend these protocols to transportation infrastructure anchors. Manufacturers serving EU markets respond by consolidating certification laboratories and pre-approving installation partners.
Specification authority is migrating from general contractors to structural engineers trained in substrate-specific anchor selection. Engineering firms in the United States and Australia now require manufacturer-provided calculation software before approving fastening details. This shift compresses distributor influence and rewards suppliers with embedded technical support capabilities.
Chemical Anchors Market Segmentation
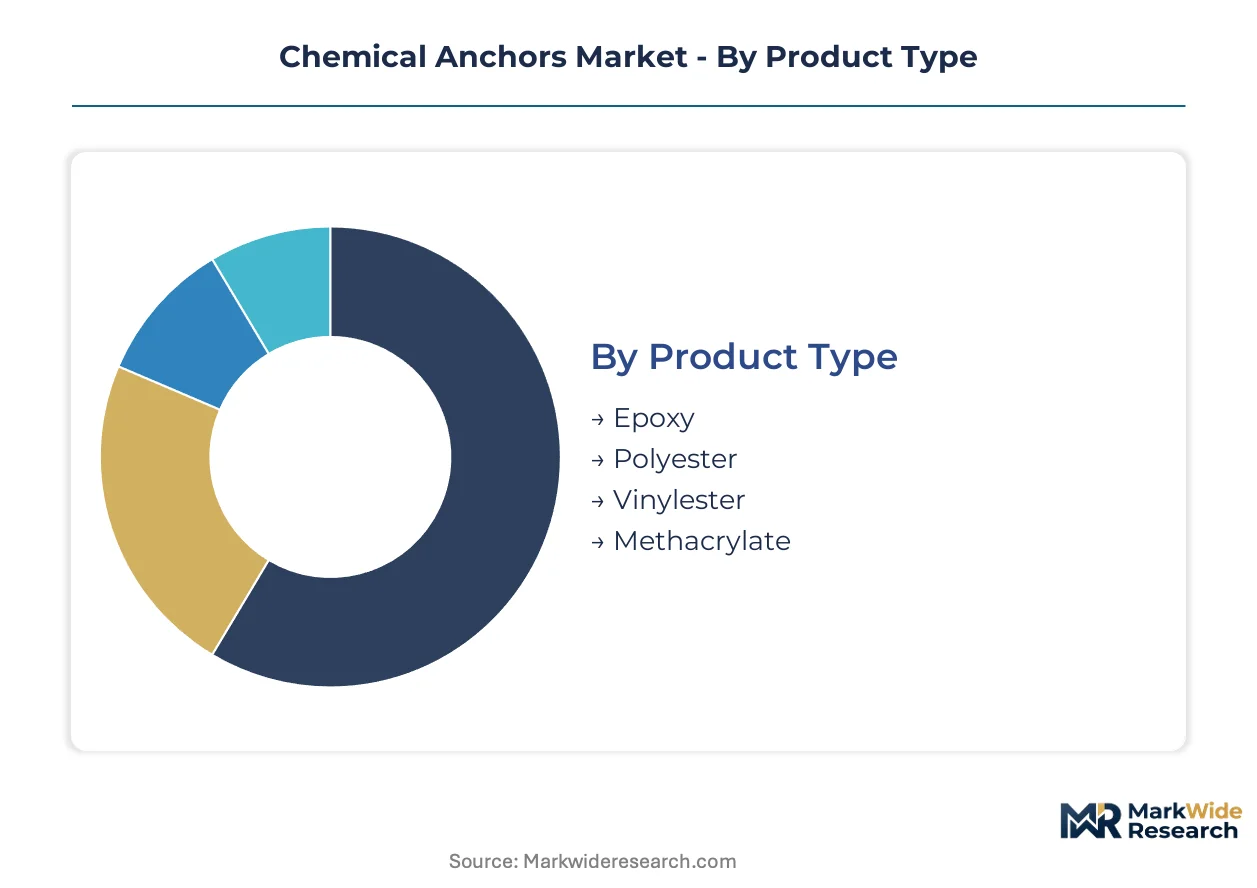
Chemical anchor specifications diverge sharply across load requirements, substrate conditions, and regulatory exposure. Segmentation reveals where formulation investments concentrate and which channels capture margin.
Product Type:
Customization intensity spans from engineered structural systems to commodity-grade cartridges, with performance certification acting as the primary price delimiter.
- Epoxy:Two-component systems based on bisphenol-A or bisphenol-F resins deliver working times exceeding 30 minutes and bond strengths above 20 kN in cracked concrete. Federal Highway Administration bridge rehabilitation specifications in the United States drive procurement toward extended-gel formulations that accommodate complex rebar placements.
- Vinylester:Hybrid styrene-free formulations achieve rapid cure in moist environments while resisting saltwater degradation. Offshore wind turbine foundation contractors in the North Sea and Sea of Japan specify these grades for their corrosion resistance under cathodic protection systems.
- Polyester:Lower-cost unsaturated polyester resins serve light-duty mechanical anchoring where pull-out requirements remain below 10 kN.
- Methacrylate:Rapid-cure acrylic systems enable cold-weather installation down to -20°C for winter construction schedules.
Most installed capacity flows through epoxy formulations. Expansion is steepest in vinylester as marine and corrosive infrastructure specifications multiply.
Application:
Project scale and structural liability exposure determine whether specifications demand third-party testing or standard-grade certification.
- Infrastructure:Bridge deck overlays, tunnel lining repairs, and seismic retrofits require post-installed rebar connections tested to ETAG 001 Annex C for cracked concrete performance. Japan's updated seismic codes and California Department of Transportation specifications mandate these anchors for ductile moment frame connections.
- Construction:Commercial building facades, curtain wall attachments, and precast panel connections utilize chemical anchors where mechanical fastening would compromise substrate integrity. German construction product regulations under MDR-aligned CE marking require pull-out documentation for structural fixings above 5 kN.
- Marine:Coastal piling, dock structures, and offshore substations expose anchors to chloride-induced corrosion and tidal wet-dry cycling.
- Automotive:Manufacturing facility installations for conveyor systems and press foundations require precision alignment capabilities that chemical anchors provide over expansion alternatives.
Contractor procurement concentrates in infrastructure. Specification volume is climbing fastest in marine applications as offshore wind buildouts accelerate.
End User:
Technical sophistication and liability exposure create distinct purchasing behaviors across professional and consumer segments.
- Contractors:General and specialty trade contractors represent the dominant volume channel, with purchasing decisions driven by installed-cost calculations and crew productivity metrics. OSHA fall-protection certification requirements constrain deployment capacity for elevated anchor installation work.
- Engineers:Structural engineering firms increasingly control specification authority through substrate-specific calculation software requirements. Firms in Australia and the United States now mandate manufacturer-provided design tools before approving fastening details.
- DIY Enthusiasts:Homeowner renovators purchasing through online retail channels represent the most rapidly expanding demand pool. Cartridge-format kits with simplified installation instructions unlock renovation demand in Germany and Australia.
- Manufacturers:Precast concrete producers and structural steel fabricators integrate chemical anchors into shop-controlled assembly processes.
Volume leadership sits with contractors. Share is accumulating fastest among DIY enthusiasts as digital distribution removes traditional procurement friction.
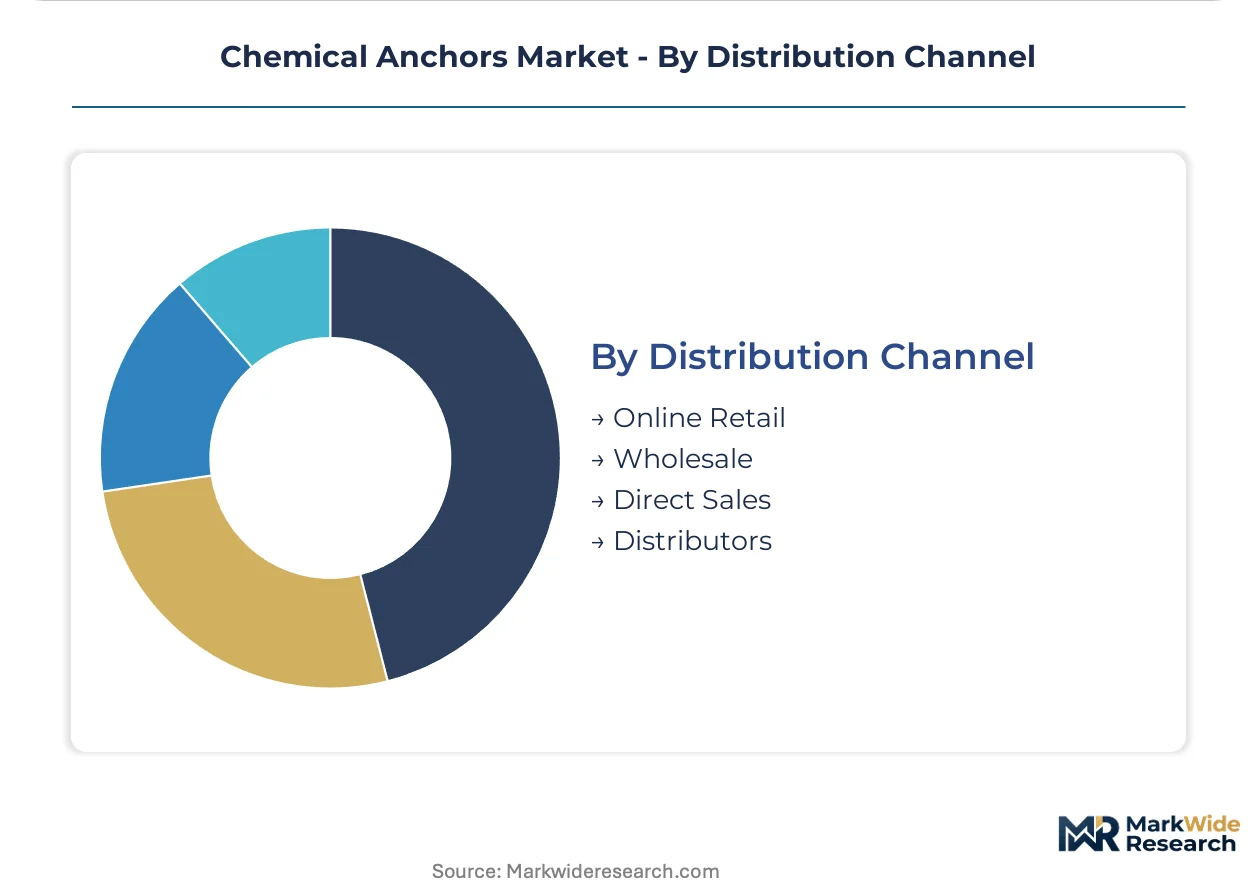
Distribution Channel:
Channel selection tracks project scale, urgency requirements, and the need for technical support integration.
- Wholesale:Regional and national building material distributors capture bulk infrastructure project demand through specification relationships with general contractors. These channels retain margin-rich positions on large-quantity epoxy and vinylester orders.
- Direct Sales:Manufacturers deploy technical sales engineers for complex structural applications requiring substrate analysis and custom engineering. Direct relationships enable bundled inspection service contracts and recertification agreements.
- Online Retail:E-commerce platforms serve fragmented DIY demand and small-contractor spot purchasing with cartridge-format anchor kits.
- Distributors:Specialized construction fastener distributors provide inventory proximity and same-day availability for time-sensitive repair work.
Wholesale channels handle the greatest transaction value. Online retail is expanding most quickly as homeowner renovation demand digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's MDR-aligned construction product regulations enforce stricter pull-out testing protocols than OSHA mandates in the United States, creating divergent compliance pathways for anchor manufacturers across these two major infrastructure markets.
United States
Federal Highway Administration bridge rehabilitation programs drive vinylester anchor procurement for aging infrastructure retrofits. OSHA fall-protection standards mandate certified technician deployment for elevated installations, constraining contractor capacity. California Department of Transportation specifications anchor seismic rebar connection demand in Los Angeles and San Francisco Bay Area construction corridors.
Germany
KBA transportation infrastructure protocols extend CE marking pull-out testing requirements to tunnel and bridge anchors. ECHA REACH styrene emission caps force polyester formulation phase-outs across manufacturing facilities. Industrial concentration in North Rhine-Westphalia and Bavaria clusters epoxy and vinylester production for domestic and export markets.
Japan
Updated seismic design codes mandate post-installed rebar connections in commercial moment frame construction. METI building standards enforcement tightens substrate-specific anchor certification requirements. Osaka and Nagoya industrial zones concentrate marine-grade vinylester demand for offshore wind foundation projects in the Sea of Japan.
Australia
Online retail channel expansion unlocks DIY homeowner renovation demand through cartridge-format anchor kits. TGA-aligned state building codes vary pull-out testing documentation requirements across jurisdictions. Sydney and Melbourne metropolitan construction activity absorbs specification-grade epoxy systems for high-rise facade attachments.
China
Dual carbon goals accelerate offshore wind turbine foundation deployment, absorbing corrosion-resistant vinylester anchor volumes. GB standards and MIIT regulations govern construction product certification for structural fixings. Yangtze River Delta manufacturing clusters supply domestic infrastructure projects while serving export markets across Southeast Asia.
Chemical Anchors Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with specification-controlled infrastructure projects favoring technical sales capabilities while commodity-grade construction channels reward scale economics. The vendor base concentrates among European and North American formulators with embedded distribution networks, though Asian producers capture volume in cost-sensitive polyester grades. Three archetypes dominate: integrated construction chemical suppliers bundling anchors with adjacent systems, pure-play fastening specialists leveraging inspection service contracts, and regional manufacturers competing on cartridge-format price points. M&A activity targets inspection service capabilities and regional distribution footprints, while portfolio diversification into waterproofing membranes captures specification control in below-grade applications.
Within the integrated chemical supplier tier, BASF SE and Sika AG exemplify the bundling archetype by anchoring project bids through adjacent construction system offerings. Hilti Corporation occupies a distinct position among fastening specialists, leveraging direct-service technician networks to lock in recurring inspection revenue. These three entities represent divergent strategic postures: chemical conglomerate diversification, construction systems integration, and service-enabled specialization.
| Leading Market Players |
|---|
| BASF SE |
| Fischer Group |
| Hilti Corporation |
| Fosroc, Inc. |
| Illinois Tool Works |
| Sika AG |
| Henkel AG & Co. KGaA |
| EJOT |
| Simpson Strong-Tie Company, Inc. |
| Others |
Cost & Logistics Intelligence
ECHA REACH styrene emission caps gate qualified supply for polyester formulations and compress premium-tier pricing access for REACH-compliant vinylester and epoxy systems. Buyers face bifurcated procurement landscapes where certified low-VOC products command structural premiums over constrained legacy supply.
Pricing Analysis
Capacity additions in China are reshaping price floors for bisphenol-A epoxy resin feedstock. Three-tier pricing structure across premium, standard, and economy levels separates ETAG 001 Annex C-certified structural anchors from standard-grade construction fixings and commodity polyester cartridges. Pricing pressure stems from freight cost volatility on Asian resin imports. DIY enthusiasts through online retail channels exhibit highest price sensitivity, while infrastructure contractors prioritize certified performance over unit cost.
Supply Chain Analysis
Domestic-content mandates in United States federal procurement specifications are reshaping sourcing patterns for bridge and tunnel rehabilitation projects. Epoxy resin production concentrates in China, South Korea, and Germany. Formulation chemistry draws from bisphenol-A, vinylester monomers, and methacrylate esters. Single-source vulnerability runs through Asian petrochemical feedstock corridors. Distribution runs through wholesale building material distributors for bulk infrastructure, direct technical sales for engineered applications, and e-commerce platforms for fragmented DIY demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between ECHA REACH-constrained European manufacturing and less regulated Asian production bases creates cost differentials for formulators with dual-hemisphere asset footprints.
For Market Incumbents: Hedge styrene supply exposure by accelerating vinylester formulation transitions ahead of ECHA phase-out deadlines. Secure backward integration into bisphenol-A resin supply through long-term offtake agreements with South Korean or Chinese producers. Certification investment in ETAG 001 Annex C testing protocols defends specification control against mechanical anchor substitution in light-duty segments. For New Entrants and Emerging Players: The 40-60% price-point gap between premium epoxy structural systems and economy polyester cartridges opens white-space in mid-tier hybrid vinylester-epoxy formulations. Target Australia's expanding DIY renovation market through cartridge-format anchor kits with TGA-aligned installation documentation. Pursue direct-to-contractor digital distribution to bypass wholesale distributor margin capture. For Investors and Strategic Acquirers: Valuations sit cheapest among regional European manufacturers facing ECHA compliance retrofit costs. Long-term viability favors integrated construction chemical suppliers with waterproofing bundling capabilities and embedded inspection service revenue streams. Watch offshore wind foundation procurement volumes in the North Sea and Sea of Japan as inflection indicators for vinylester demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive bisphenol-A sourcing from South Korean petrochemical producers insulates margin from freight volatility. |
| REACH-Aligned Formulation Transition | Styrene-free vinylester development ahead of ECHA deadlines secures continued EU market access. |
| Inspection Service Bundling | Recurring recertification contracts with infrastructure operators extend revenue beyond initial anchor sales. |
| DIY Channel Digital Expansion | Cartridge-format anchor kits through Australian and German e-commerce platforms capture homeowner renovation demand. |
| Waterproofing System Integration | Combined project bids with membrane suppliers capture specification control in below-grade construction segments. |
Research Approach
Coverage spans North America, Europe, Asia-Pacific, and Australia, with primary inputs from each region combined with secondary validation. Interviews with plant managers at formulation facilities, procurement leads at infrastructure contractors, distribution channel partners, and technical R&D directors informed supply-side and demand-side dynamics. Secondary sources include customs and trade data, SEC 10-K filings from listed construction chemical suppliers, ECHA REACH substance dossiers, and FHWA bridge rehabilitation program documentation. Bottom-up volume modeling triangulates against top-down market sizing across product chemistries.
Granularity-level modeling operates at formulation-grade tier, end-use application, and regional regulatory cluster dimensions. CAGRs derive from segmented volume projections reconciled against macro infrastructure spending trajectories. Forecast inputs incorporate seismic code evolution timelines, offshore wind foundation deployment pipelines, and ECHA regulatory phase-out schedules.
The model assumes a particular technology adoption path; alternative pathways for hybrid vinylester-epoxy formulations would alter the outlook if cure-time performance fails to match specification requirements. Forecasts reflect documented assumptions on raw material cost trajectories and regulatory enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Urethane Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
Global MS Polymer Adhesives Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
North America Construction Adhesives Market