
 Solar Interconnect Ribbon Market | 2026-2036
Solar Interconnect Ribbon Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Interconnect Ribbon Market Insights
Project finance tied to utility-scale solar deployment is tilting procurement power toward capital-rich module makers. Ulbrich Solar Technologies leverages its North American manufacturing footprint to serve domestic content requirements. Sveck Photovoltaic New Material anchors supply relationships with tier-one Chinese panel producers. Bruker-Spaleck GmbH specializes in precision-rolled copper alloys for high-load interconnection schemes.
Solar interconnect ribbon is a conductive metal strip, typically copper or aluminum with tin or silver coating, engineered to precise thickness tolerances between 0.1 mm and 0.3 mm for electrical and mechanical bonding of photovoltaic cells within a module. Its primary function is to collect current from individual solar cells and transfer it to busbars while withstanding thermal cycling and mechanical stress over decades of field exposure. Flat ribbon dominates volume shipments due to compatibility with standard cell architectures, though bifacial ribbon is gaining traction as double-glass module designs expand. Copper material commands the largest share of value given its superior conductivity, while conductive polymer formulations occupy a niche in flexible and lightweight applications where traditional metal fatigue poses reliability risks.
China's MIIT enforces GB standards that specify resistivity and elongation benchmarks for interconnect materials used in certified solar installations. The EU F-Gas Regulation and CE marking requirements indirectly shape ribbon demand by accelerating module replacement cycles in European rooftop and utility fleets. Stakeholders must track evolving IEC certification pathways and country-specific domestic content thresholds as these determine which material grades and coating technologies qualify for subsidized project pipelines.
Market Dynamics
Cell-to-module assembly lines in Jiangsu province are forcing ribbon suppliers to recalibrate thickness tolerances as bifacial and shingled cell architectures multiply electrical contact points per module.
Growth Catalysts
- MIIT dual carbon targets:China's updated GB standards for solar component efficiency mandate lower resistivity thresholds, compelling module makers to upgrade interconnect specifications.
- Double-glass module proliferation:Bifacial ribbon configurations capture rear-side current in utility-scale installations across desert and agrivoltaic sites.
- Copper coating chemistry:Silver-tin alloy layers deposited via electroplating improve solderability for high-density cell interconnection schemes.
Market Restraints
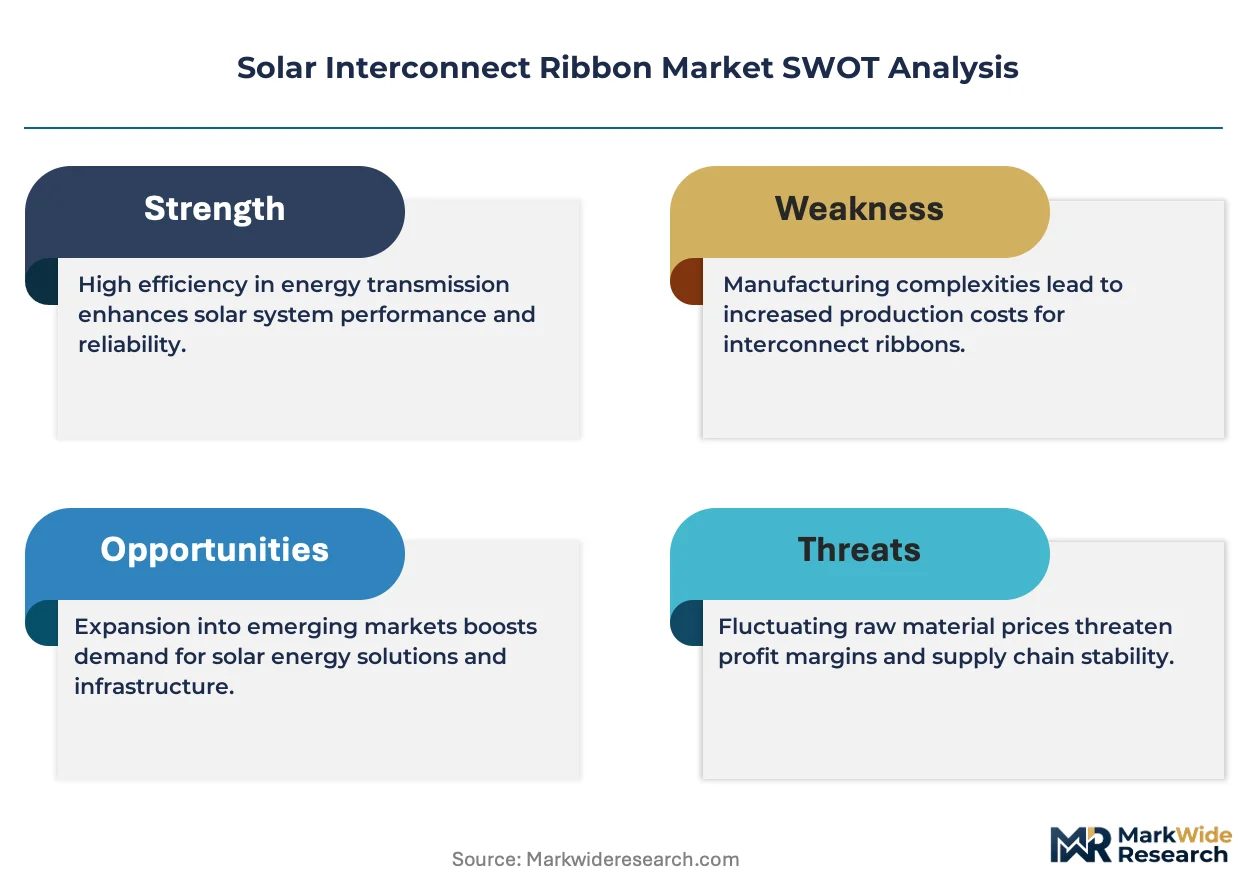
- Copper price volatility:LME copper futures expose ribbon margins to commodity swings that module makers resist passing through contract pricing.
- Jiangsu-Zhejiang supply concentration:Over 70% of global cell-to-module capacity clusters in two Chinese provinces, creating geographic vulnerability to regional logistics disruption.
- Conductive polymer substitution:Flexible organic formulations threaten metal ribbon in building-integrated and vehicle-integrated photovoltaics where weight constraints dominate.
Strategic Opportunities
- US domestic content thresholds:Inflation Reduction Act bonus credit rules incentivize North American ribbon sourcing for utility-scale project pipelines.
- Perovskite-silicon tandems:Next-generation cell stacks demand ultra-fine ribbon geometries that incumbent rolling mills have yet to commercialize.
- EU F-Gas module replacement:Accelerated retirement of fluorinated greenhouse gas-containing panels creates aftermarket ribbon demand for refurbishment contractors.
Industry Challenges
- Precision rolling technician scarcity:Sub-0.15 mm thickness control requires metallurgical expertise concentrated in German and Japanese equipment vendors.
- IEC 61215 certification timelines:Thermal cycling validation for new ribbon alloys extends qualification cycles by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Interconnect Ribbon Market |
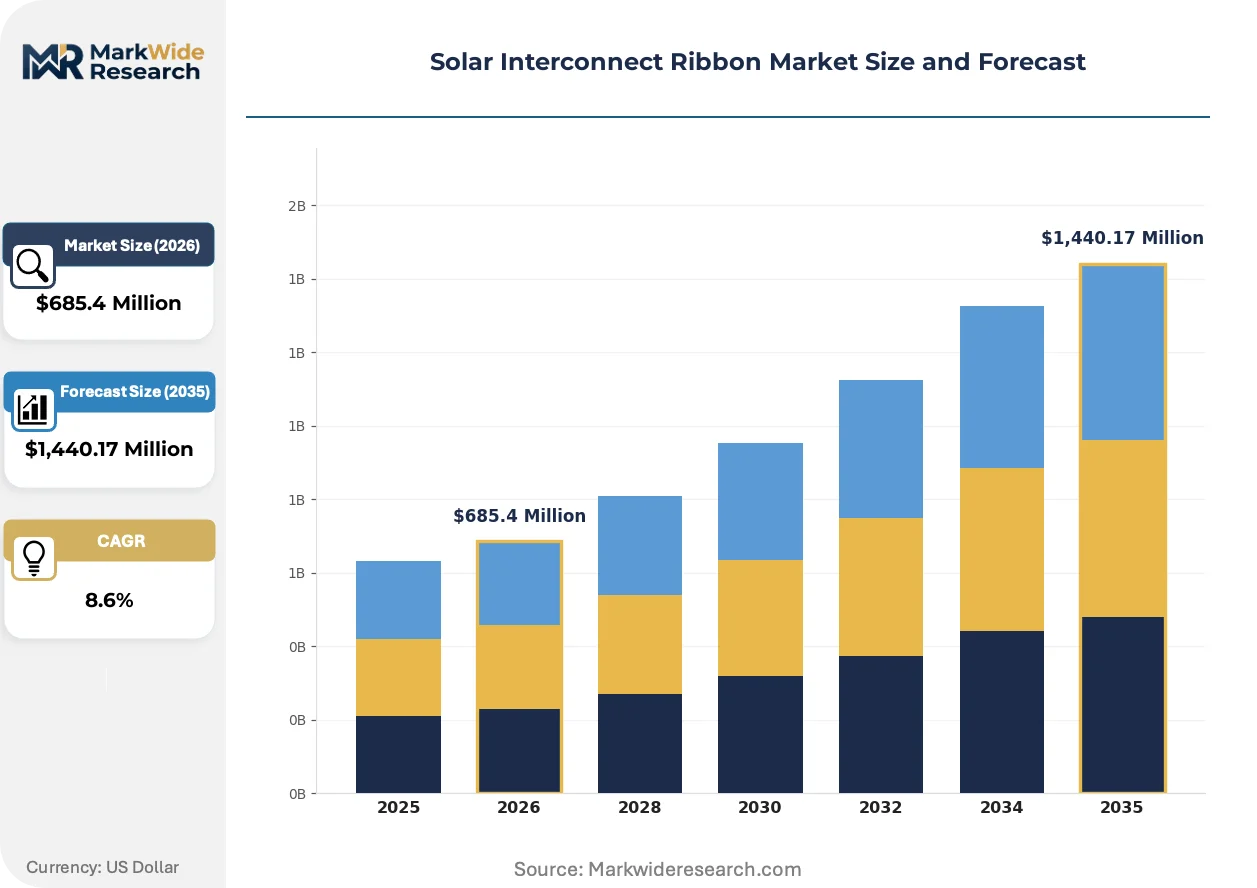
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,440.17 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Ribbon, Round Ribbon, Bifacial Ribbon, Coated Ribbon Material: Aluminum, Copper, Silver, Conductive Polymer End User: Module Manufacturers, Equipment Suppliers, Component Manufacturers, Research Institutions Application: Photovoltaic Systems, Solar Panels, Energy Storage, Industrial Applications |
| Companies Covered | Ulbrich Solar Technologies, Sveck Photovoltaic New Material, Hitachi Cable, Bruker-Spaleck GmbH, Sarkuysan, Luvata, Sumati Electronics, NEOCAB, Targray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Interconnect Ribbon Market Trends and Innovations
Interconnect technology is bifurcating between commodity flat ribbon for standard modules and precision-engineered variants for advanced cell architectures. Three developments are compressing supplier margins while opening technical differentiation paths.
Round wire interconnect is rendering obsolete traditional flat ribbon in shingled cell modules. LONGi Solar and Tongwei have shifted pilot lines to circular cross-section conductors that reduce silver consumption at cell edges. This geometry is rendering obsolete planar soldering processes, forcing equipment vendors to develop laser-assisted bonding systems.
EU F-Gas Regulation amendments tighten phase-down schedules for hydrofluorocarbons used in module encapsulants. European project developers are front-loading ribbon procurement to complete installations before 2027 refurbishment deadlines. Module recyclers in Germany and the Netherlands are extracting copper ribbon from end-of-life panels to bypass virgin material premiums.
Direct purchasing by utility-scale developers is consolidating procurement decisions previously fragmented across EPC contractors. Independent power producers in Texas and California now specify ribbon conductivity grades in module supply agreements. This concentration compresses supplier margins while rewarding rolling mills with captive copper smelting capacity.
Solar Interconnect Ribbon Market Segmentation
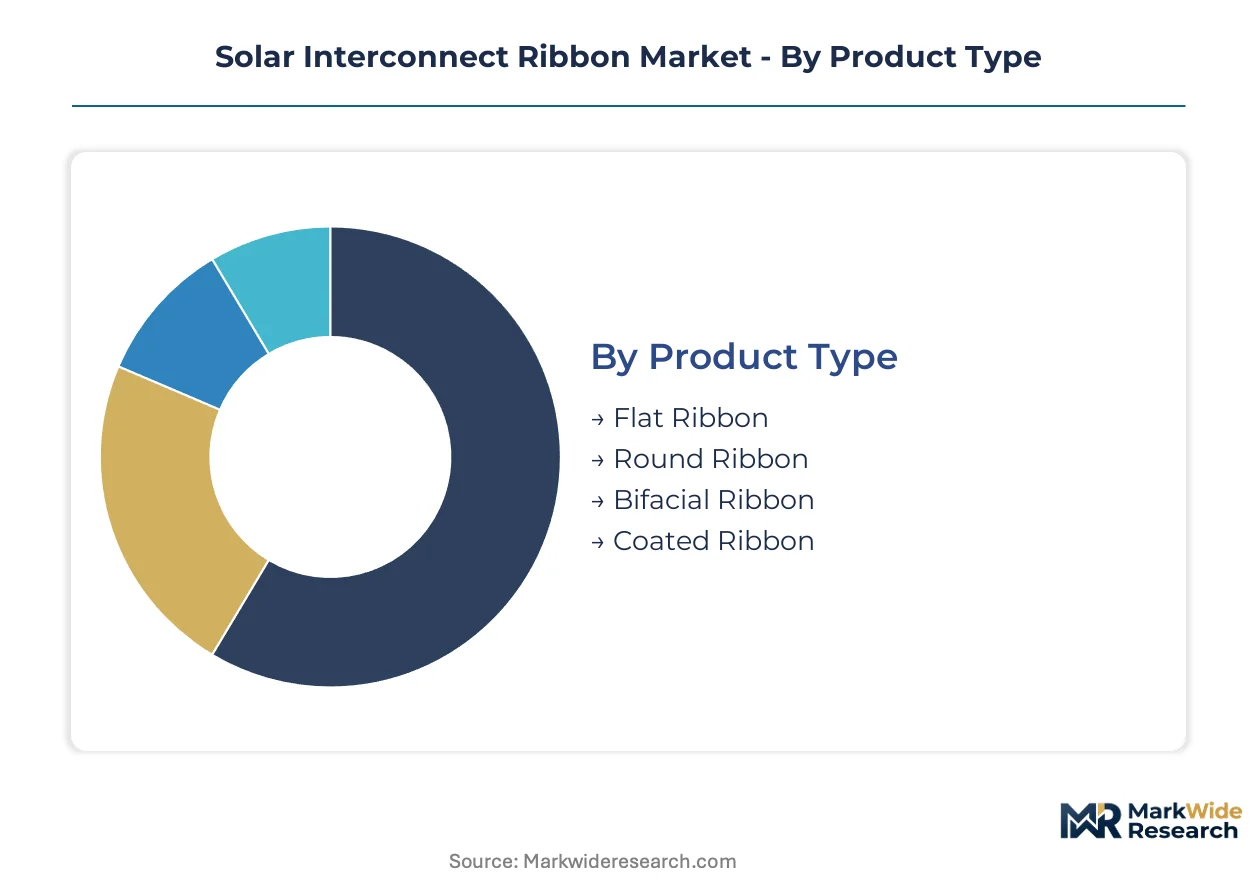
Ribbon geometry and material composition determine module efficiency thresholds and manufacturing compatibility. Cell architecture evolution—from standard monofacial to shingled and tandem designs—forces suppliers to maintain parallel production lines across multiple specification bands.
Product Type:
Use-case spectrum spans commodity modules requiring basic electrical continuity to advanced architectures demanding precision-engineered contact geometries.
- Flat Ribbon:Rectangular copper or aluminum strips with tin or silver plating, typically 0.1–0.3 mm thick, remain the default for standard cell interconnection. Jiangsu province module assembly lines consume the majority of global flat ribbon volume as they retrofit for higher-density cell layouts.
- Bifacial Ribbon:Specialized configurations capture current from both front and rear cell surfaces in double-glass module assemblies. Desert and agrivoltaic installations in utility-scale pipelines are accelerating procurement of these variants as rear-side gain becomes economically material.
- Round Ribbon:Circular cross-section conductors reduce silver consumption at cell edges in shingled module designs. Pilot lines at tier-one Chinese manufacturers are validating laser-assisted bonding processes for this geometry.
- Coated Ribbon:Electroplated silver-tin alloy layers improve solderability for high-density interconnection schemes. Coating chemistry differentiation separates premium suppliers from commodity rollers.
Established volume favors flat ribbon; emerging adoption favors bifacial ribbon.
Material:
Conductivity requirements and cost structures split procurement between base metal commodities and specialized formulations.
- Copper:Superior electrical conductivity and thermal cycling resistance make this the value-dominant material. LME price volatility compresses rolling mill margins, yet module makers resist contract pass-throughs.
- Aluminum:Lightweight alternative for building-integrated and vehicle-integrated photovoltaics where weight constraints override conductivity optimization. Jiangsu-Zhejiang suppliers are expanding aluminum rolling capacity for niche applications.
- Silver:High-conductivity plating layers deposited via electroplating enhance solder joint reliability. Silver content per meter is declining as coating thickness specifications tighten.
- Conductive Polymer:Organic formulations address flexible applications where metal fatigue poses reliability risks. Building-integrated photovoltaic architects specify these for curved substrate compatibility.
Copper commands revenue concentration; conductive polymer climbs the fastest.
End User:
Procurement authority is consolidating toward capital-rich module makers with direct utility-scale developer relationships.
- Module Manufacturers:Tier-one panel producers in Jiangsu and Zhejiang provinces specify ribbon conductivity grades in multi-year supply agreements. These buyers dominate volume and are forcing thickness tolerance recalibration.
- Equipment Suppliers:Cell-to-module assembly line vendors integrate ribbon feeding systems into turnkey equipment packages. Their specifications influence ribbon width and spool formatting standards.
- Component Manufacturers:Junction box and busbar producers procure ribbon for sub-assembly integration. These intermediaries face margin pressure from direct purchasing by module makers.
- Research Institutions:Perovskite-silicon tandem development programs demand ultra-fine ribbon geometries for experimental cell stacks. Commercial rolling mills have yet to commercialize these specifications.
Module manufacturers anchor procurement volume; research institutions drive specification frontier.
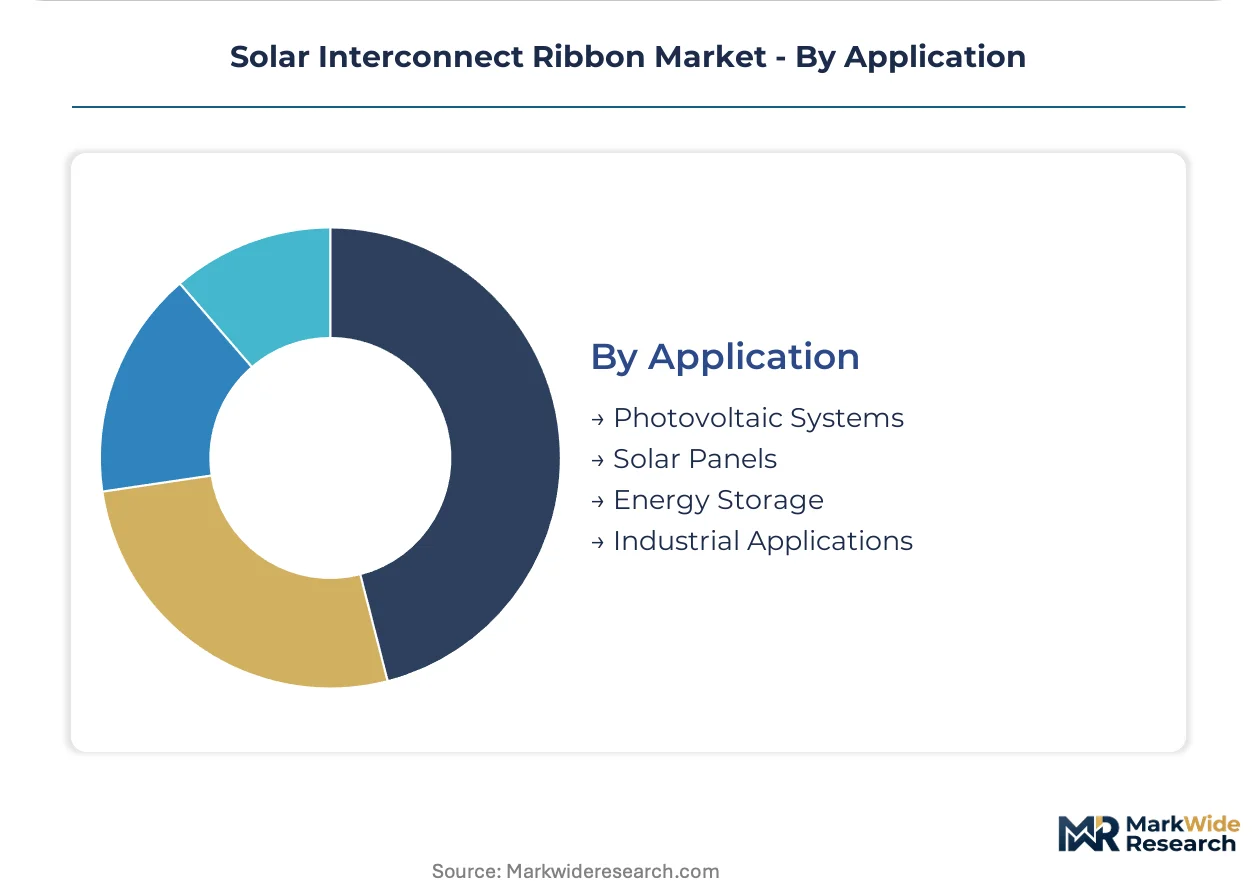
Application:
Field exposure conditions and electrical load profiles determine ribbon durability requirements across deployment contexts.
- Photovoltaic Systems:Utility-scale and distributed generation installations subject ribbon to decades of thermal cycling and mechanical stress. IEC 61215 certification validates long-term reliability for these deployments.
- Solar Panels:Rooftop and building-integrated applications prioritize lightweight ribbon configurations. EU F-Gas Regulation amendments are accelerating replacement cycles in European rooftop fleets.
- Energy Storage:Grid-scale battery integration with solar generation creates auxiliary ribbon demand for power conversion equipment. These applications emphasize current-carrying capacity over cost minimization.
- Industrial Applications:Specialized manufacturing equipment and off-grid industrial power systems require custom ribbon specifications. Volume remains fragmented across niche use cases.
Photovoltaic systems sustain revenue base; energy storage offers steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in solar interconnect ribbon track the geographic mismatch between copper smelting capacity and cell-to-module assembly clusters. China runs a structural surplus in processed ribbon, while the United States and European Union absorb cross-border shipments to cover domestic content gaps.
China
Jiangsu province hosts the densest concentration of ribbon consumption, with Zhejiang province adding significant assembly capacity for export-oriented module production. MIIT dual carbon goals and updated GB standards for component efficiency mandate lower resistivity thresholds, forcing rolling mills to recalibrate thickness tolerances. Suzhou and Ningbo industrial corridors anchor the procurement networks of tier-one panel producers.
United States
Utility-scale developers in Texas and California now specify ribbon conductivity grades directly in module supply agreements, bypassing traditional EPC contractor intermediaries. Inflation Reduction Act domestic content bonus credits incentivize North American sourcing, though rolling mill capacity remains concentrated in legacy wire and cable facilities. Arizona and Ohio host emerging ribbon fabrication investments tied to utility-scale project pipelines.
Germany
EU F-Gas Regulation amendments accelerate module replacement cycles, generating aftermarket ribbon demand from refurbishment contractors in Bavaria and North Rhine-Westphalia. Precision rolling expertise concentrates in German equipment vendors serving sub-0.15 mm thickness specifications. Berlin-Brandenburg research clusters drive qualification protocols for next-generation alloy compositions.
Japan
METI efficiency standards for distributed generation systems elevate material specifications for residential rooftop installations. Kansai and Chubu industrial regions maintain captive ribbon production for integrated module manufacturers. Japanese rolling mills supply ultra-fine geometries for experimental perovskite-silicon tandem development programs.
India
PLI scheme allocations for solar module manufacturing are drawing ribbon procurement decisions toward Gujarat and Tamil Nadu assembly corridors. Central Electricity Authority grid integration mandates indirectly shape material durability requirements. Domestic copper semis capacity in Jhagadia and Tuticorin feeds emerging ribbon rolling investments.
Solar Interconnect Ribbon Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream where thickness tolerance and coating chemistry determine qualification. The vendor base separates into consolidated rolling mills with captive copper smelting, precision equipment vendors with metallurgical expertise, and regional fabricators serving domestic content requirements. Three archetypes dominate: commodity rollers competing on scale, precision specialists defending technical differentiation, and geography-anchored suppliers leveraging trade policy. Competitive moves center on backward integration into copper semis and strategic partnerships with cell-to-module equipment vendors.
Among North American fabricators, Ulbrich Solar Technologies occupies a position tied to domestic content thresholds, while Bruker-Spaleck GmbH exemplifies the precision-specialist archetype with its German engineering heritage. Sveck Photovoltaic New Material anchors the China-based supply relationships with tier-one panel producers. These three represent the geographic and technical segmentation that structures procurement decisions across utility-scale project pipelines.
| Leading Market Players |
|---|
| Ulbrich Solar Technologies |
| Sveck Photovoltaic New Material |
| Hitachi Cable |
| Bruker-Spaleck GmbH |
| Sarkuysan |
| Luvata |
| Sumati Electronics |
| NEOCAB |
| Targray |
| Others |
Pricing and Supply Chain Analysis
Jiangsu province's cell-to-module assembly corridors concentrate procurement leverage among tier-one panel producers, compressing ribbon supplier margins while amplifying buyer negotiating power across multi-year supply agreements. LME copper volatility transmits directly into rolling mill cost structures, yet module makers resist price pass-throughs that would erode their own project economics.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on thickness tolerance precision and IEC 61215 certification status. Price differentiation hinges on coating chemistry sophistication and captive copper smelting integration, with commodity rollers facing margin compression from silver-tin alloy specification upgrades. Pricing pressure stems from direct purchasing consolidation by utility-scale developers, while EPC contractors retain greatest price sensitivity due to fixed-bid project exposure.
Supply Chain Analysis
Precision rolling capacity concentrates in German and Japanese equipment vendors, with Chinese rolling mills in Jiangsu and Zhejiang provinces feeding downstream module assembly clusters. Raw material dependencies center on LME copper cathodes, silver electroplating chemistry, and high-purity tin alloys for solderability enhancement. Single-source vulnerability looms in sub-0.15 mm thickness control expertise, where metallurgical technician scarcity constrains capacity expansion. Distribution runs through direct procurement by tier-one module makers, bypassing traditional component manufacturer intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra-fine geometry rolling capabilities for perovskite-silicon tandem architectures represent the critical skill gap separating qualified suppliers from commodity rollers, with commercial mills yet to achieve production-scale tolerances below 0.1 mm.
For Market Incumbents:Pre-empt conductive polymer substitution threats in building-integrated photovoltaics by securing aluminum rolling capacity and flexible substrate compatibility certifications. Backward integration into captive copper semis production defends margin position against LME volatility, while strategic equipment partnerships with laser-assisted bonding vendors lock in round ribbon process control.
For New Entrants and Emerging Players:Establish a beachhead in North American domestic content supply chains by locating ribbon fabrication capacity in Arizona or Ohio to capture Inflation Reduction Act bonus credit flows. White-space opportunity concentrates in perovskite-silicon tandem development programs where ultra-fine geometry specifications exceed incumbent commercial capabilities. Go-to-market leverage rests on precision rolling technician recruitment from German equipment vendor networks.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified wire and cable parents with underutilized rolling mill assets and latent solar ribbon qualification pathways. Long-term viability favors suppliers with captive copper semis and coating chemistry intellectual property. Monitor IEC 61215 certification timeline extensions for new alloy compositions as inflection signal for technical differentiation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Semis | Captive supply of LME-linked cathodes insulates rolling margins from commodity volatility. |
| Laser-Assisted Bonding Equipment Partnership | Round wire geometries for shingled cells demand precision bonding systems from German vendors. |
| Perovskite-Silicon Tandem Ribbon Development | Sub-0.1 mm thickness specifications unlock next-generation cell stack procurement relationships. |
| North American Domestic Content Capacity | Arizona and Ohio fabrication assets qualify for IRA bonus credits in utility-scale pipelines. |
| Silver-Tin Coating Chemistry Investment | Electroplating differentiation separates premium suppliers from commodity Jiangsu-Zhejiang rollers. |
Research Methodology
Operator-level perspectives from cell-to-module assembly line managers, rolling mill metallurgists, utility-scale procurement officers, and IEC certification auditors anchored the qualitative base for this study. Primary interview findings triangulated against secondary sources including MIIT GB standard filings, EU F-Gas Regulation amendments, LME copper futures data, and module manufacturer supply agreement disclosures. Bottom-up volume estimates from Jiangsu-Zhejiang capacity clusters converged with top-down value projections across the analysis window.
Scenario-bracketing framed demand trajectories across ribbon geometry types, material compositions, and end-user procurement authority segments throughout the forecast period. CAGRs derived from elasticity-adjusted capacity expansion rates and substitution threat penetration curves. Industry-specific inputs incorporated perovskite-silicon tandem commercialization timelines and IRA domestic content threshold enforcement patterns.
Sensitivities concentrate around LME copper price volatility bands, IEC 61215 certification timeline extensions for novel alloys, and conductive polymer substitution rates in flexible applications. Forecasts embed assumptions regarding MIIT dual carbon policy continuity and EU F-Gas module replacement acceleration. Quarterly review of rolling mill capacity utilization in Jiangsu province and perovskite tandem pilot line announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Graphene Solar Cell Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
Vietnam Solar Energy Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Flexible Parylene-Based Solar Cells Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Chile Renewable Energy Market
Solar Power Systems
Asia-Pacific Bifacial Solar Market