
 Solar Carport Market | 2026-2036
Solar Carport Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Carport Market Analysis
Multi-source procurement for steel and photovoltaic modules is recalibrating how solar carport developers manage project margins and delivery timelines. SolarEdge Technologies leverages its power electronics specialization to capture value at the inverter level in integrated carport systems. Schletter Solar GmbH anchors European supply chains through its mounting systems expertise. Tata Power Solar Systems Ltd. competes on manufacturing scale across utility-scale and distributed solar structures in South Asia.
A solar carport is a purpose-built overhead canopy structure integrating photovoltaic panels into its roofing surface, typically engineered with galvanized steel framing and module tilt angles optimized for local solar irradiance, designed to generate electricity while providing weather protection for parked vehicles. Commercial end users currently dominate installed capacity, driven by parking lot electrification mandates and fleet decarbonization commitments across retail and logistics operators. Monocrystalline technology leads efficiency metrics in premium integrated systems, while modular carport designs gain traction where rapid deployment and relocation flexibility matter.
The US Federal Energy Regulatory Commission and state-level public utility commissions shape interconnection rules that determine project payback periods for grid-tied solar carports. California's building energy code and the EU Green Deal's renewable targets for commercial real estate create compliance-driven demand floors in their respective jurisdictions. Stakeholders must monitor evolving local content requirements and tariff structures that alter component sourcing economics across major deployment corridors.
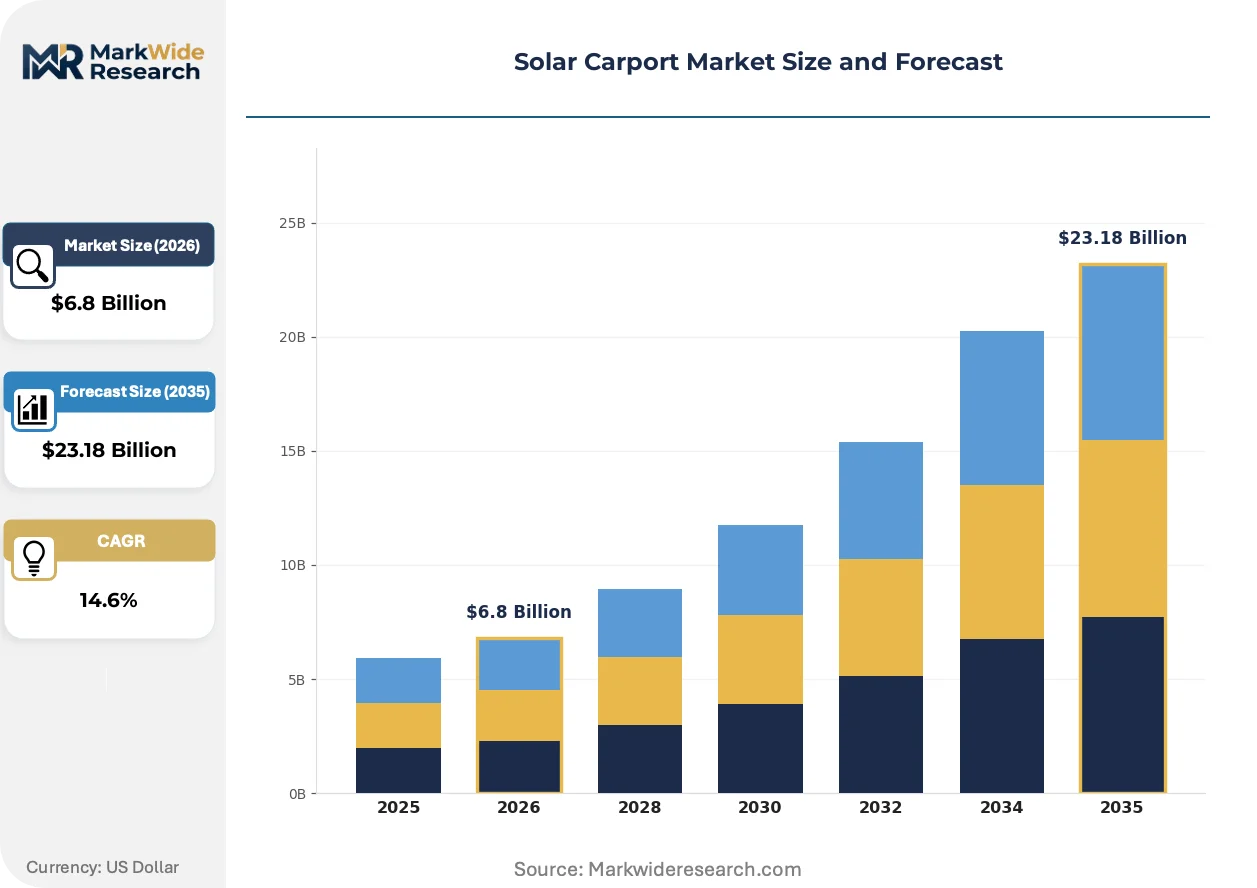
Market Dynamics
The US Inflation Reduction Act's transferability provisions for investment tax credits are restructuring project finance for commercial solar carport developers, compressing payback timelines and accelerating deployment velocity across retail and municipal parking infrastructure.
Growth Catalysts
- California's Title 24 Building Energy Code:Mandates solar-ready infrastructure in new commercial parking construction, creating baseline demand for integrated canopy systems across retail and office developments.
- Fleet electrification commitments:Logistics operators and last-mile delivery services require powered parking infrastructure to support medium-duty electric vehicle charging at distribution hubs.
- Bifacial photovoltaic modules:Improved rear-side energy capture from reflective parking surfaces boosts yield per square meter, improving project economics in high-albedo environments like Arizona and Nevada.
Market Restraints
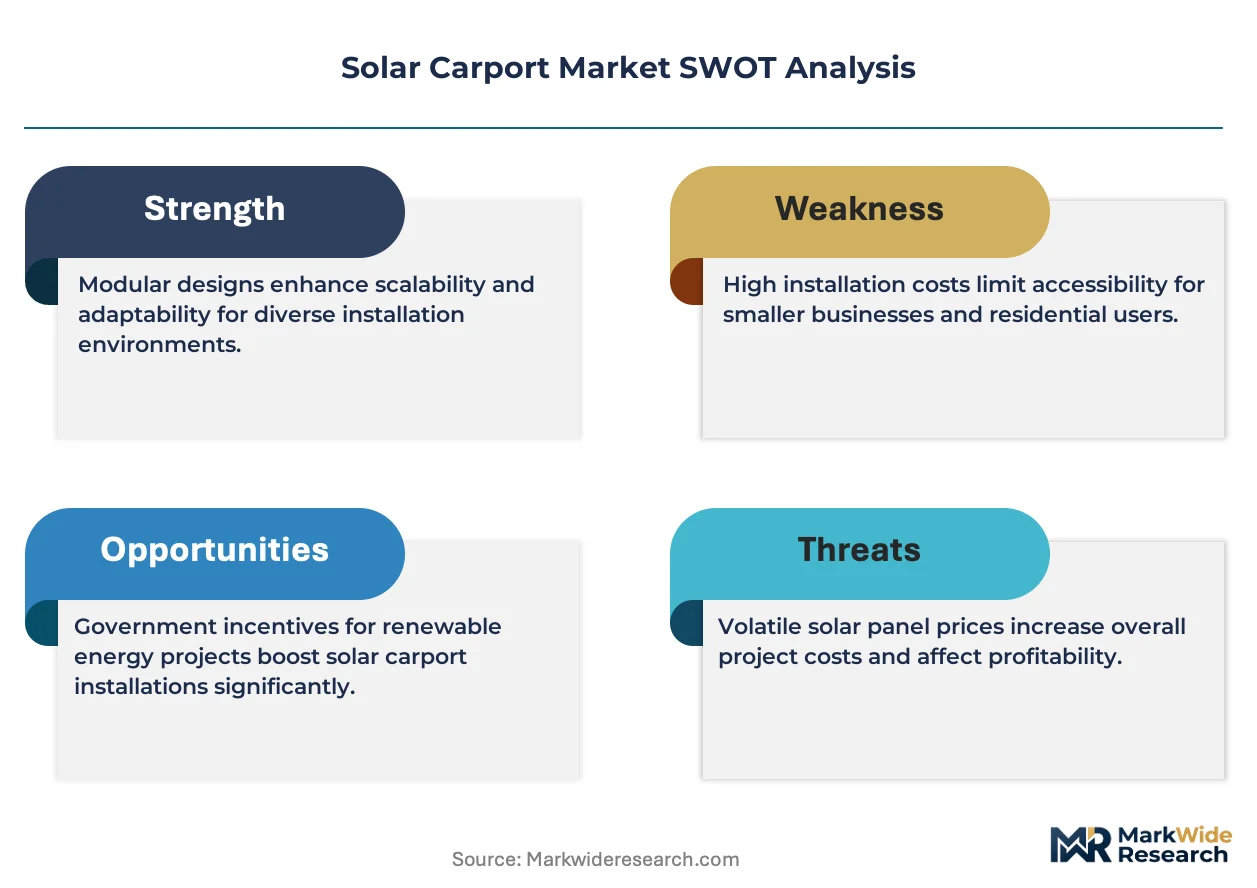
- Steel price volatility:Galvanized structural framing represents 35-45% of installed costs, exposing margins to commodity swings from integrated mill suppliers in the US and South Korea.
- Interconnection queue congestion:Utility processing delays in PJM and CAISO territories extend commissioning timelines by 12-18 months for grid-tied commercial installations.
- Rooftop solar substitution:Building-mounted PV offers lower structural costs and simpler permitting, capturing projects where roof age and load capacity permit.
Strategic Opportunities
- EV charging integration:Bidirectional vehicle-to-grid capability at workplace parking facilities creates new revenue streams through grid services contracts with regional transmission organizations.
- Community solar carve-outs:State-level shared solar programs in New York, Massachusetts, and Colorado enable off-site subscription models for residential customers without suitable rooftops.
- Agrivoltaic-adjacent designs:Elevated canopy structures preserving ground-level vegetation access are expanding into airport long-term parking and corporate campus applications.
Industry Challenges
- Structural engineering specialization:Finite element analysis for vehicle impact loads and seismic design requires licensed professionals scarce in secondary metropolitan markets.
- Utility coordination complexity:Synchronizing solar generation profiles with EV charging load curves demands advanced energy management software integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Carport Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canopy, Shade Structure, Integrated System, Modular Carport End User: Commercial, Residential, Industrial, Government Installation Type: Ground-mounted, Roof-mounted, Portable, Permanent Technology: Monocrystalline, Polycrystalline, Thin-film, Bifacial |
| Companies Covered | SolarEdge Technologies, Schletter Solar GmbH, Tata Power Solar Systems Ltd., ANTA I TECHNOLOGY CO., LTD., Baja Carports, Envision Solar, SunPower Corporation, Phoenix Solar Panel Systems, Quest Renewables, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Carport Market Emerging Trajectories
Module-level power electronics and prefabricated steel framing systems are compressing installation timelines while enabling more sophisticated energy management at the parking facility level.
Integrated energy storage is expanding into commercial solar carport configurations, allowing fleet operators to buffer solar generation against peak demand charges and participate in utility demand response programs. Warehouse operators with overnight charging requirements are adopting these hybrid systems most aggressively. The technology is expanding into airport and hospital parking structures where resilience requirements justify premium capital deployment.
The US Federal Energy Regulatory Commission's Order 2222 implementation is enabling aggregated distributed energy resources to bid into wholesale markets, creating new revenue pathways for solar carport-plus-storage assets. State public utility commissions in New York, California, and Illinois are drafting implementation rules that determine compensation structures. Commercial parking operators in these jurisdictions are restructuring power purchase agreements to capture capacity market value.
Corporate renewable energy buyers are migrating from virtual power purchase agreements toward on-site physical installations to meet science-based targets with verifiable carbon accounting. Retail chains with extensive parking footprints are prioritizing direct ownership models over third-party leases. This preference shift is most pronounced among Fortune 500 companies with net-zero commitments and established sustainability reporting under the EU CSRD or equivalent frameworks.
Solar Carport Market Segmentation
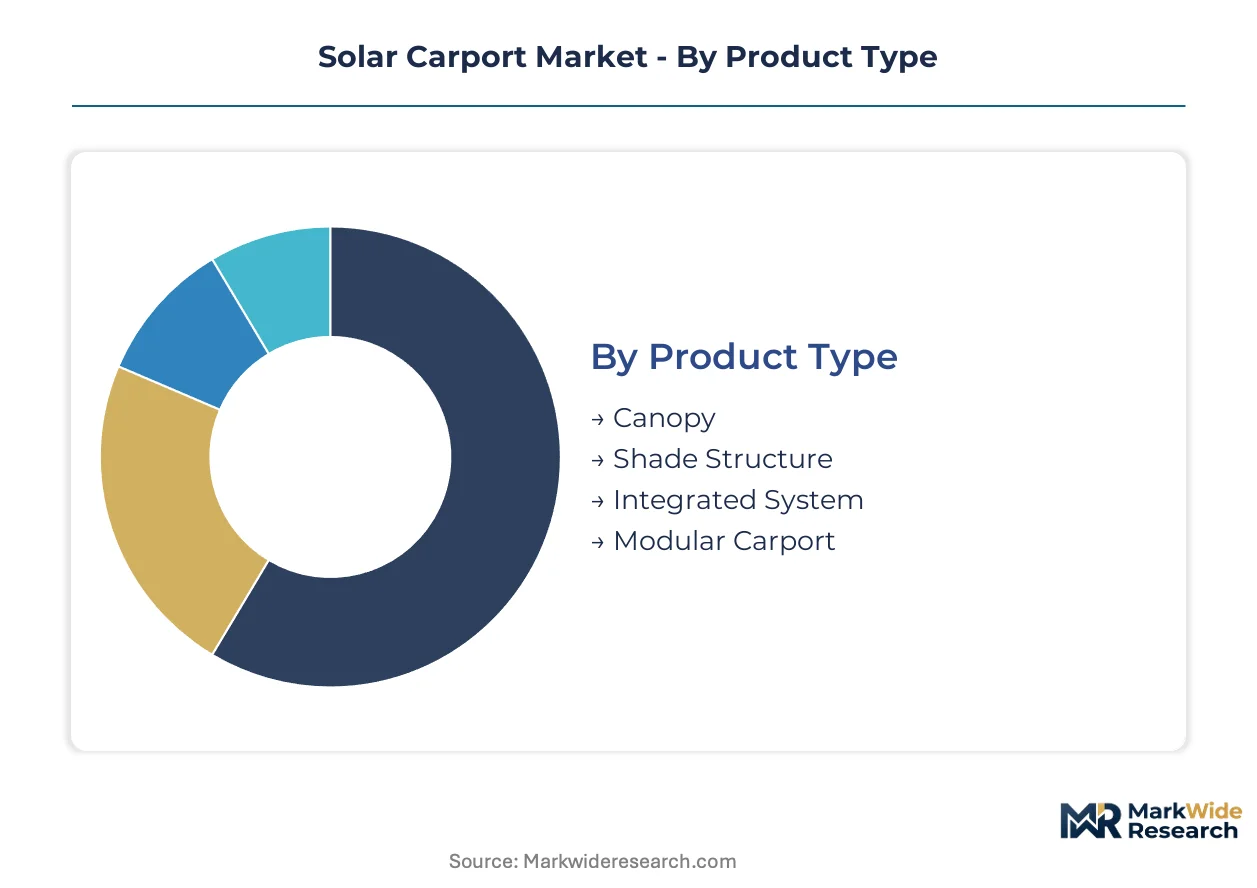
Solar carport configurations vary sharply in structural engineering requirements and permitting pathways, creating distinct competitive arenas where specialized fabricators hold advantages over generalist solar contractors. Understanding these segment boundaries clarifies where capital deployment concentrates and which technical capabilities differentiate winning bids.
Product Type:
Supply concentration in steel fabrication and module integration tilts competitive dynamics toward vendors with captive structural manufacturing or exclusive racking partnerships.
- Canopy:Single-slope or gable roof structures with standardized column spacing engineered for retail parking rows. California municipal procurement favors these configurations for their predictable load distribution and streamlined plan review processes.
- Shade Structure:Architecturally finished systems with powder-coated columns and integrated LED lighting, commanding premium pricing in corporate campus and healthcare settings where aesthetic compliance matters.
- Integrated System:Factory-assembled modules pre-wired to inverter stations, cutting field labor by 40% and enabling rapid deployment for fleet electrification deadlines at logistics hubs.
- Modular Carport:Bolt-together steel components designed for disassembly and relocation, attracting rental property operators and temporary event infrastructure providers seeking asset mobility.
Canopy structures absorb the bulk of installed capacity; modular designs are expanding most quickly in secondary metropolitan markets.
End User:
Customer procurement sophistication spans from standardized RFP processes to bespoke engineering engagements, fragmenting vendor strategies across account types.
- Commercial:Retail chains and office park operators with dedicated sustainability officers driving parking lot electrification mandates. Target, Walmart, and Kroger have established internal capital allocation frameworks for solar canopy deployment across distribution centers.
- Residential:Single-family and multi-family property owners with limited roof space or unsuitable roof conditions, typically served through community solar subscriptions or third-party ownership models rather than direct purchase.
- Industrial:Manufacturing facilities and warehouse operators with 24/7 EV charging requirements and peak demand charge exposure, prioritizing battery-integrated configurations for load shifting.
- Government:Municipal parking authorities and federal installations subject to executive order carbon reduction targets, with procurement governed by Davis-Bacon prevailing wage requirements and domestic content preferences.
Commercial end users command the largest share of current deployment; industrial applications show the steepest expansion trajectory as fleet electrification accelerates.
Installation Type:
Foundation engineering and electrical interconnection complexity separate installation approaches, with soil conditions and grid access determining optimal configurations.
- Ground-mounted:Pile-driven or ballasted foundations in surface parking lots, the default for large-scale commercial deployments where geotechnical surveys confirm load-bearing capacity.
- Roof-mounted:Elevated structures atop existing parking garages, requiring structural reinforcement and wind load analysis that extends permitting timelines by 4-6 months.
- Portable:Ballasted systems on temporary foundations for construction sites, military forward operating bases, and event venues with 2-5 year deployment horizons.
- Permanent:Engineered foundations with 25-year design life and seismic compliance, standard for municipal and institutional installations with long-term asset ownership.
Ground-mounted systems dominate cumulative installations; portable configurations are gaining share fastest in disaster recovery and temporary infrastructure markets.
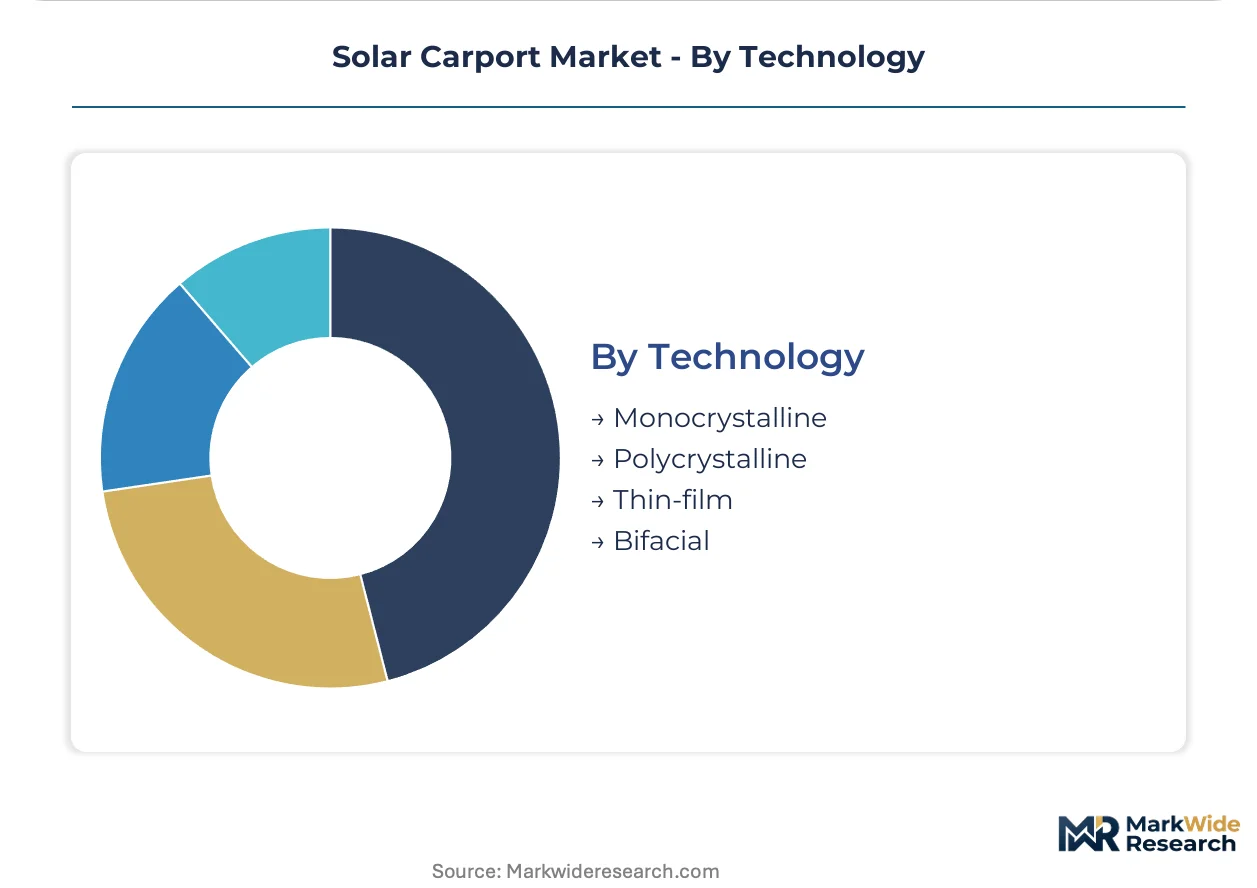
Technology:
Module efficiency and rear-side energy capture characteristics segment photovoltaic technology choices, with albedo conditions and space constraints driving selection.
- Monocrystalline:Silicon ingots sliced from single crystal boules delivering 20-22% conversion efficiency, preferred in premium integrated systems where roof area limits total array size.
- Polycrystalline:Multi-crystal silicon cells with marginally lower efficiency but cost advantages in price-sensitive municipal procurement where space constraints are less severe.
- Thin-film:Cadmium telluride or copper indium gallium selenide deposited on glass, offering superior high-temperature performance in desert climates with elevated ambient temperatures.
- Bifacial:Double-glass modules capturing direct and reflected irradiance, with yield gains of 8-15% on high-albedo surfaces like concrete parking lots in Arizona and Nevada.
Monocrystalline technology holds the largest installed base; bifacial modules are climbing the fastest as parking surface reflectivity optimization becomes standard practice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabrication clusters in South Korea and photovoltaic module manufacturing zones in eastern China anchor supply-side capacity for solar carport deployment worldwide.
United States
Retail parking electrification mandates and fleet decarbonization commitments drive commercial adoption. The Inflation Reduction Act's transferability provisions for investment tax credits compress project payback timelines. California's Title 24 Building Energy Code mandates solar-ready infrastructure in new commercial parking construction across Los Angeles and San Diego metropolitan corridors.
Germany
Corporate renewable energy procurement under EU CSRD reporting frameworks accelerates on-site physical installations. The EU Green Deal's renewable targets for commercial real estate establish compliance-driven demand floors. Industrial clusters in Bavaria and Baden-Württemberg concentrate engineering expertise for integrated canopy systems serving automotive manufacturing facilities.
China
Dual carbon goals and state-owned enterprise fleet electrification programs expand distributed solar infrastructure. The Ministry of Ecology and Environment oversees carbon intensity reduction mandates affecting commercial real estate development. Yangtze River Delta manufacturing zones supply prefabricated steel framing systems for domestic and export markets.
India
Central Electricity Authority regulations and state-level solar rooftop policies create procurement pathways for commercial parking operators. The Production-Linked Incentive scheme for solar modules improves domestic component economics. Maharashtra and Gujarat industrial corridors host manufacturing scale for utility-scale and distributed solar structures.
United Arab Emirates
Net-zero commitments by sovereign wealth-backed real estate developers prioritize on-site renewable generation for carbon accounting verification. Dubai's building codes increasingly mandate solar integration in new commercial developments. Masdar City and Dubai South logistics zones deploy elevated canopy structures preserving ground-level functionality.
Solar Carport Market Vendor Landscape
Global majors compete with regional champions across steel fabrication and power electronics integration, producing a tiered structure where specialized mounting system engineers hold pricing power in premium segments. The vendor base spans inverter specialists, structural fabricators, and integrated solution providers with captive manufacturing. Three archetypes dominate: power electronics-first integrators, steel-structure fabricators with exclusive racking partnerships, and utility-scale solar contractors extending into distributed structures. Competitive moves concentrate on strategic partnerships for module supply security and backward integration into galvanized steel production.
Among power electronics specialists, SolarEdge Technologies occupies a position exemplifying inverter-level value capture in integrated carport systems. Schletter Solar GmbH anchors European supply chain configurations through mounting systems expertise. Tata Power Solar Systems Ltd. represents manufacturing scale archetypes competing across utility-scale and distributed solar structures in South Asian deployment corridors.
| Leading Market Players |
|---|
| SolarEdge Technologies |
| Schletter Solar GmbH |
| Tata Power Solar Systems Ltd. |
| ANTA I TECHNOLOGY CO., LTD. |
| Baja Carports |
| Envision Solar |
| SunPower Corporation |
| Phoenix Solar Panel Systems |
| Quest Renewables |
| Others |
Supply Flow & Price Mechanics
Captive steel fabrication anchoring the structural framing tier concentrates pricing power with integrated manufacturers while compressing margins for assembly-only contractors competing on module procurement efficiency. The IRA's domestic content bonus credits reshape sourcing economics, favoring US-based galvanizing capacity over imported structural components.
Pricing Analysis
Warranty bundling separates premium integrated systems from unbundled canopy configurations, with 25-year performance guarantees and O&M service contracts commanding structural premiums. Pricing stratifies across premium, standard, and economy tiers based on module efficiency grade and seismic certification level. Cost compression in standard canopy segments is intensifying because of steel price volatility and module oversupply. Municipal procurement authorities exhibit highest price sensitivity, while corporate campus operators prioritize aesthetic compliance over unit economics.
Supply Chain Analysis
Domestic content requirements under the IRA's bonus credit structure are reshaping sourcing patterns, pushing developers toward US-based steel galvanizing and North American module assembly. Supply draws from South Korea for structural steel, China for photovoltaic cells, and Vietnam for module assembly. Raw material dependencies center on galvanized steel coil, aluminum racking extrusions, and silicon wafer supply. Tariff exposure on Chinese-origin cells creates single-source vulnerability for bifacial module configurations. Distribution runs through EPC contractors with captive structural fabrication partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Structural engineering capacity constraints prop pricing power for licensed seismic designers, creating supply-constrained conditions that favor incumbents with established professional networks.
For Market Incumbents: Cement structural engineering capabilities through acquisition of regional seismic design firms, countering the threat of interconnection queue delays eroding project IRRs. Prioritize backward integration into galvanized steel production to defend margin position against commodity volatility from South Korean integrated mills.
For New Entrants and Emerging Players: EV charging infrastructure providers represent the most penetrable channel partner type for modular carport configurations, given fleet electrification deadlines and limited incumbent presence in bidirectional power electronics. Target temporary event infrastructure and disaster recovery applications where asset mobility commands premium pricing and procurement cycles compress.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to utility-scale solar contractors seeking distributed generation capabilities. Long-term viability hinges on structural engineering licensure moats and interconnection queue management expertise. Watch FERC Order 2222 implementation rules as the signal for aggregated DER compensation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Fabrication | Captive galvanizing capacity secures IRA domestic content bonus credits and margin protection. |
| EV Charging Infrastructure Partnership | Bidirectional V2G capability unlocks grid services revenue through CAISO and PJM market participation. |
| Structural Engineering Firm Acquisition | Licensed seismic design capabilities address talent scarcity in secondary metropolitan markets. |
| Prefabricated Module Assembly Scale-Up | Factory pre-wiring cuts field labor costs and accelerates deployment for fleet electrification deadlines. |
| Community Solar Program Enrollment | Shared solar carve-outs in New York and Massachusetts expand addressable market beyond on-site load. |
Methodological Framework
Document review covered FERC interconnection filings, state PUC rulemaking dockets, and EPC contractor project databases, complemented by interviews with utility planning officers, commercial parking facility managers, structural engineering principals, and solar developer procurement leads. Secondary sources included EIA distributed generation statistics, IEA renewable investment trackers, and SEC 10-K disclosures from power electronics manufacturers. Bottom-up project pipeline aggregation was cross-referenced against top-down market sizing from trade associations.
Historical deployment trajectories were cross-referenced against expert panel input on interconnection timeline assumptions and steel price elasticity. The analytical framework modeled capacity across product type, end user, installation configuration, and regional regulatory cluster throughout the forecast period. CAGRs were derived from weighted average project IRR thresholds and capital availability indices. Key inputs included IRA transferability utilization rates and bifacial module albedo gain coefficients by climate zone.
Caveats apply where interconnection queue reform or steel tariff adjustments could materially shift the outlook for commercial deployment velocity. Forecasts reflect assumptions on policy continuity and commodity price stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
PERC Solar Panels Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
Solar PV Mounting Systems Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Alternative Solar Photovoltaic Technologies Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Solar Photovoltaic Modules Market