
 Solar Thermal Fuel Market | 2026-2036
Solar Thermal Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Thermal Fuel Market Intelligence
Silicon-based thermal storage media is broadening the addressable cost envelope for solar thermal fuel systems. Abengoa Solar leverages its concentrated solar power heritage to anchor utility-scale thermal regeneration projects across Iberia and the Middle East. Heliogen differentiates through AI-driven heliostat fields that sustain temperatures exceeding conventional molten salt thresholds. Siemens competes on system integration, extending its industrial automation portfolio into chemical synthesis control systems for thermal fuel loops.
Solar thermal fuel denotes molecular systems that absorb, store, and release solar energy through reversible photochemical or thermochemical transformations, typically operating across temperature differentials of 100–300°C with energy densities approaching 250–500 kJ/kg. These materials enable dispatchable heat and power by decoupling solar collection from energy consumption across diurnal or seasonal cycles. Phase change materials currently dominate commercial installations due to lower system complexity, while thermochemical materials represent the fastest-expanding technology category given their superior gravimetric energy density and minimal self-discharge. Liquid organic hydrides concentrate margin pools in aerospace and green transportation end users, where weight-sensitive applications command premium pricing structures.
The EU Green Deal and REACH frameworks in Europe, alongside EPA emissions standards in the United States, are tightening permissible carbon intensities for industrial process heat and compelling chemical manufacturers to qualify solar-derived thermal alternatives. Japan's METI supports domestic demonstration projects through procurement preferences for metallic hydride systems in remote facility applications. Stakeholders must monitor regulatory harmonization between CE marking requirements and emerging ISO standards for thermochemical storage safety certification to preempt market access fragmentation.
Market Dynamics
Industrial decarbonization mandates are compressing payback thresholds for thermochemical storage systems, forcing chemical manufacturers to qualify solar-derived process heat alternatives ahead of 2030 compliance deadlines.
Growth Catalysts
- EU Green Deal industrial mandates:Germany's chemical corridor around Ludwigshafen and Leverkusen is prioritizing thermochemical storage retrofits to meet binding carbon intensity reduction targets for process heat applications.
- Aerospace thermochemical adoption:Weight-sensitive applications in satellite thermal management and aircraft auxiliary power systems are commanding premium pricing for liquid organic hydride systems with superior gravimetric energy density.
- Silicon-based media cost envelope:Abundant silicon feedstocks are broadening addressable market entry points for distributed thermal regeneration installations previously constrained by rare earth material costs.
Market Restraints
- REACH registration timelines:Novel molecular storage materials face extended European Chemicals Agency evaluation periods that delay commercial deployment by 18-36 months versus conventional phase change materials.
- Heliostat field concentration:Precision heliostat manufacturing capacity clusters in Spain and the United States, creating supply vulnerability for Middle Eastern and Asian project developers.
- Molten salt substitution threat:Established concentrated solar power plants with sunk infrastructure costs resist thermochemical retrofits despite superior energy density, locking in incumbent technology.
Strategic Opportunities
- Japan remote facility applications:METI procurement preferences for metallic hydride demonstration projects in island and mountain installations create first-mover advantages for systems integrators.
- AI-heliostat convergence:Machine learning optimization of mirror alignment algorithms combined with thermochemical receiver design is opening sub-100°C applications previously uneconomical for solar thermal fuel.
- ISO thermochemical safety standards:Emerging international certification frameworks for high-temperature molecular storage systems will harmonize market access across CE marking jurisdictions and North American approval pathways.
Industry Challenges
- Photochemist talent scarcity:The intersection of materials science and solar engineering expertise required for molecular storage R&D concentrates in German, Swiss, and Japanese research institutes, constraining scale-up velocity.
- Legacy DCS integration friction:Chemical plant distributed control systems from the 1990s lack native interfaces for thermal fuel loop automation, demanding costly middleware development for each installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Thermal Fuel Market |
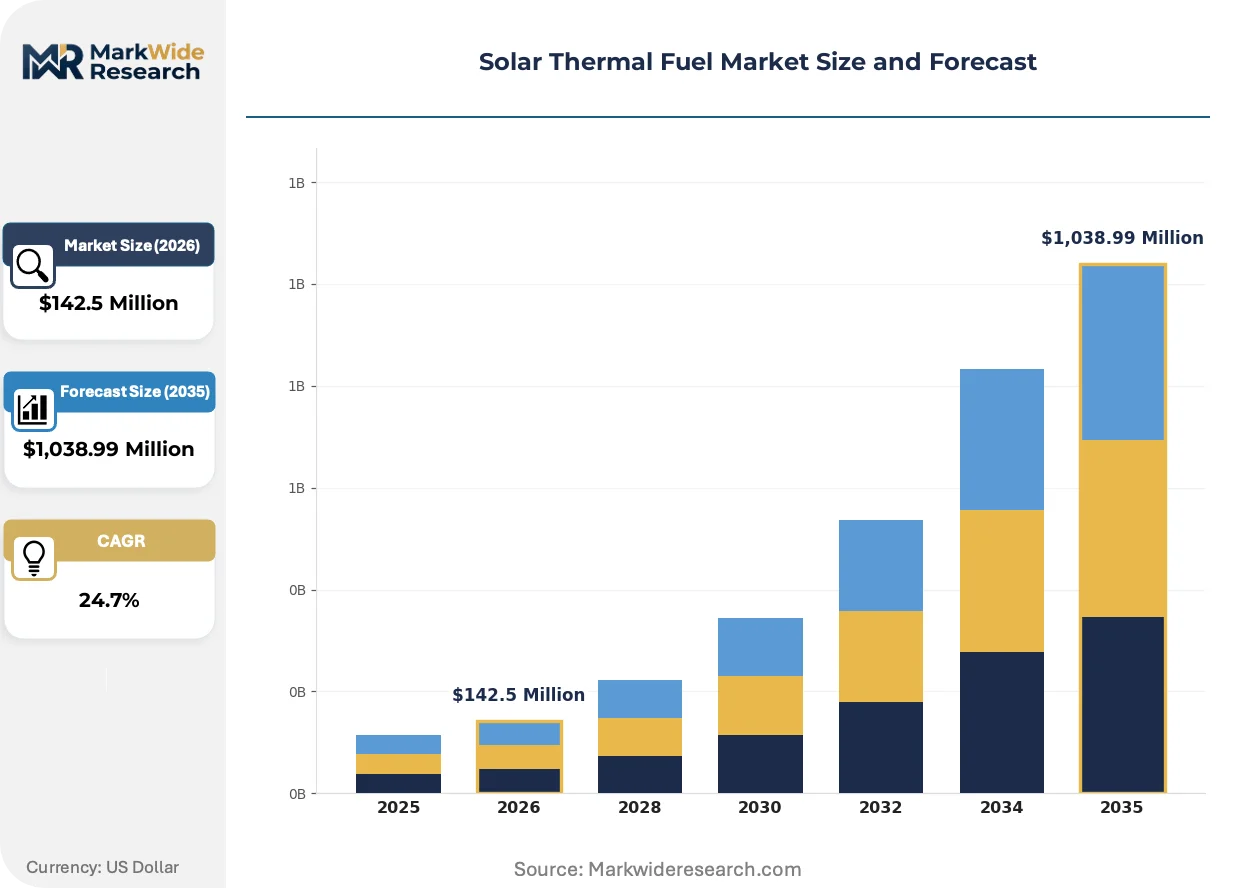
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $1,038.99 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phase Change Materials, Thermochemical Materials, Metallic Hydrides, Liquid Organic Hydrides, Bio-Based Fuels Technology: Photothermal Conversion, Catalytic Storage, Chemical Synthesis, Thermal Regeneration, Solar Desorption Application: Building Heating, Power Generation, Industrial Process Heat, Off-Grid Energy, Thermal Management End User: Renewable Energy Plants, Aerospace Operators, Chemical Manufacturers, Remote Facility Operators, Green Transportation |
| Companies Covered | Abengoa Solar, BrightSource Energy, SolarReserve, Schott Solar, Siemens, Acciona, Heliogen, eSolar, Solareast Holdings Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Thermal Fuel Market Strategic Shifts & Innovations
Photochemical molecular engineering is crossing threshold efficiencies that enable seasonal storage, while regulatory carbon accounting rules are rewriting procurement specifications for industrial heat contracts.
Thermochemical materials with reversible bond storage mechanisms are expanding into district heating networks previously served by fossil peaking plants. Nordic municipal utilities are piloting norbornadiene derivative systems for winter heat dispatch. The structural consequence is compressing seasonal storage cost curves toward parity with natural gas thermal batteries.
EPA emissions standards for industrial process heat are tightening permissible carbon intensities for chemical manufacturers in Texas and Louisiana. Facilities must now qualify solar-derived thermal alternatives in Title V operating permit renewals. Refinery and petrochemical complexes are responding by pre-qualifying thermochemical storage vendors ahead of 2027 compliance deadlines.
After-sales service unbundling is fragmenting traditional EPC contracts in utility-scale solar thermal installations. Owner-operators now procure heliostat fields, thermal receivers, and molecular storage media through separate competitive tenders rather than single-source turnkey agreements. This pattern is most visible in Iberian concentrated solar power expansions where Abengoa heritage projects established independent O&M capabilities.
Solar Thermal Fuel Market Segmentation
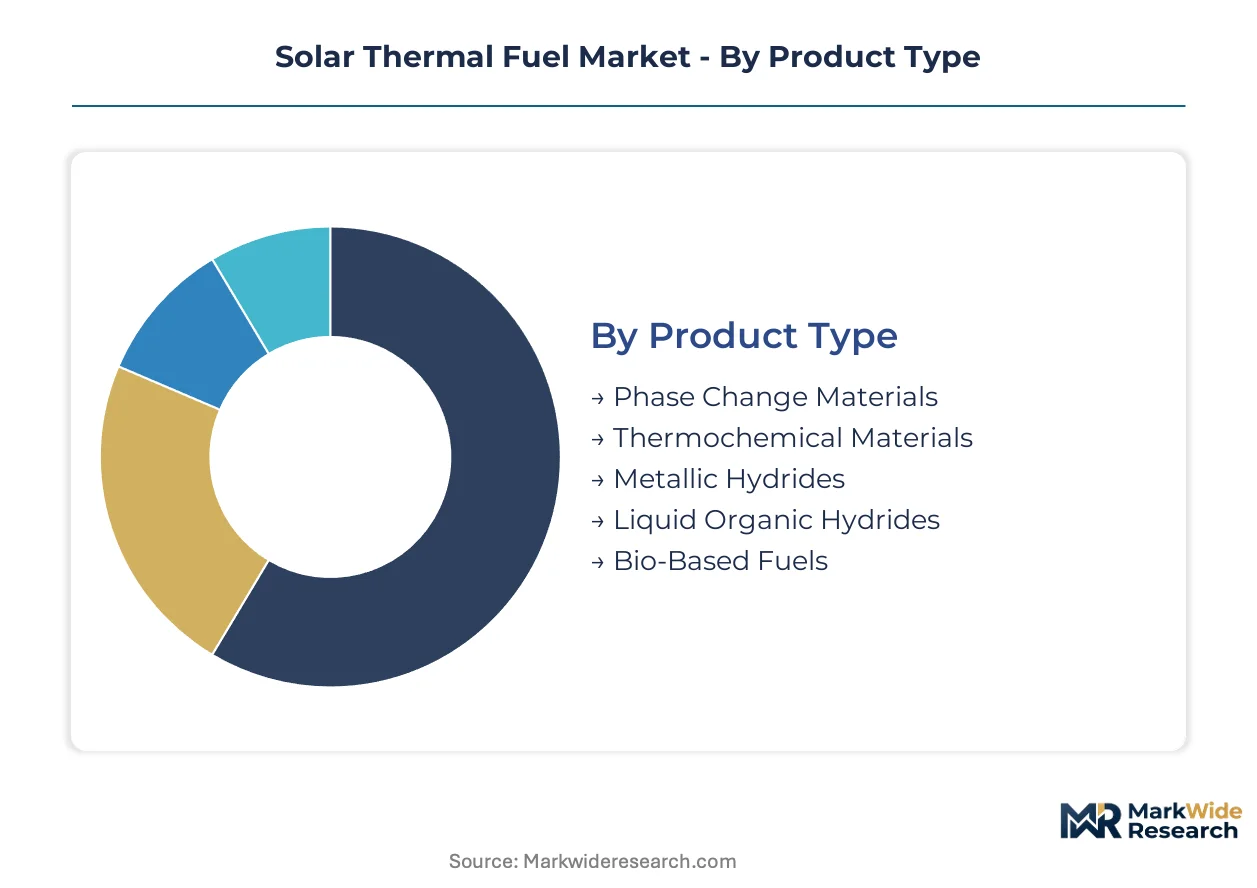
Solar thermal fuel markets fragment across molecular storage mechanisms, conversion pathways, and heat delivery applications. Each segmentation axis reveals distinct margin structures and capital intensity thresholds that shape procurement patterns among industrial buyers.
Product Type:
Supply concentration in rare earth precursors and specialty chemical feedstocks determines regional manufacturing footprints for each storage medium.
- Thermochemical Materials:Reversible bond storage systems achieve gravimetric densities of 250–500 kJ/kg through molecular isomerization reactions. Demand concentrates in Germany's chemical corridor around Ludwigshafen and Leverkusen, where ECHA REACH compliance timelines compress vendor qualification cycles.
- Phase Change Materials:Latent heat storage through solid-liquid transitions dominates current installations due to lower system complexity and established supply chains. Building heating applications in Nordic district networks absorb the majority of volume, though self-discharge rates limit seasonal deployment economics.
- Metallic Hydrides:Hydrogen absorption-desorption cycles enable compact thermal storage for remote facility applications.
- Liquid Organic Hydrides:Norbornadiene-quadricyclane derivatives command premium pricing in aerospace thermal management where weight constraints override capital costs.
- Bio-Based Fuels:Molecular systems derived from lignocellulosic precursors face feedstock consistency challenges in scaled production.
Phase change materials absorb the bulk of installed capacity; thermochemical materials are expanding most quickly.
Technology:
Cost tier separation between mature thermal regeneration and emerging photochemical pathways is widening as AI optimization reduces heliostat field capital requirements.
- Thermal Regeneration:Concentrated solar power infrastructure drives endothermic molecular recharging at 200–400°C temperature differentials. Iberian utility-scale projects leverage Abengoa heritage installations for baseload heat dispatch.
- Photothermal Conversion:Broadband absorption across visible and near-infrared spectra enables direct solar-to-chemical energy translation without thermal intermediation. Japan's METI demonstration programs in remote island facilities are validating system economics outside grid-connected markets.
- Catalytic Storage:Surface-mediated reaction kinetics accelerate charge-discharge cycling for industrial process heat applications.
- Chemical Synthesis:On-site molecular manufacturing integrates with existing chemical plant distributed control systems.
- Solar Desorption:Temperature-swing release mechanisms enable passive heat delivery in off-grid energy configurations.
Thermal regeneration commands the dominant share of operational capacity; photothermal conversion is climbing the fastest as efficiency thresholds cross commercial viability.
Application:
Customer type differentiation between continuous industrial loads and intermittent building thermal demands determines storage duration specifications and molecular system selection.
- Industrial Process Heat:High-temperature thermal delivery for chemical manufacturing, refining, and materials processing requires storage systems sustaining 300°C+ discharge temperatures. EPA Title V operating permit renewals in Texas and Louisiana are compelling pre-qualification of solar-derived alternatives ahead of compliance deadlines.
- Building Heating:District network and distributed residential applications prioritize cost per kWh over energy density. Nordic municipal utilities pilot norbornadiene derivatives for winter heat dispatch, compressing seasonal storage cost curves toward natural gas parity.
- Power Generation:Steam cycle integration demands rapid thermal discharge rates matched to turbine ramp specifications.
- Thermal Management:Satellite and aircraft auxiliary systems require extreme gravimetric performance.
- Off-Grid Energy:Remote facility operators value dispatch independence from fuel logistics.
Industrial process heat captures the largest addressable value pool; building heating is gaining share fastest as district network pilots validate seasonal storage economics.
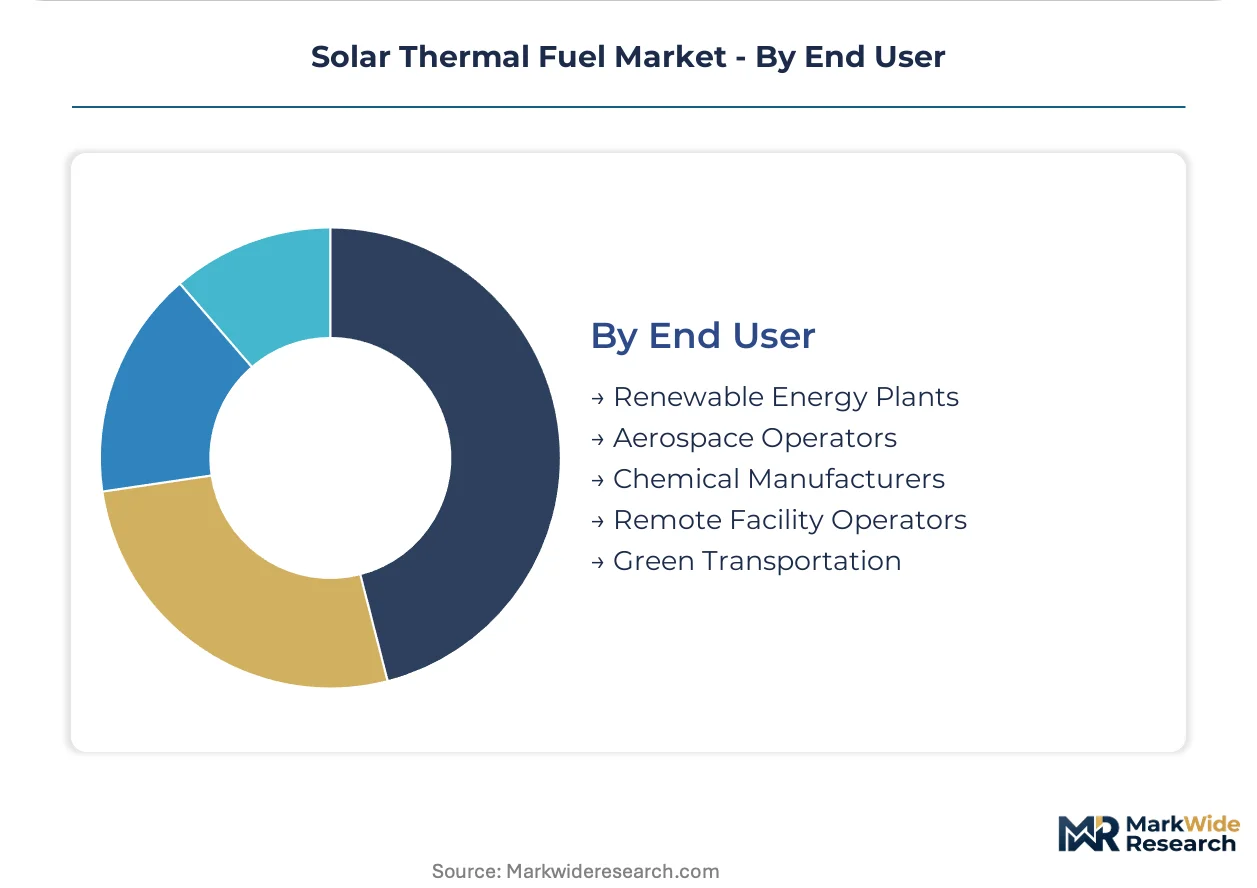
End User:
Margin structure variation across end users reflects divergent procurement authority, with chemical manufacturers optimizing total cost of ownership while aerospace operators prioritize performance guarantees.
- Chemical Manufacturers:BASF, Covestro, and Lanxess operations in Germany's Rhine-Neckar chemical cluster are retrofitting thermochemical storage to meet EU Green Deal binding carbon intensity reduction targets for process heat.
- Aerospace Operators:Satellite thermal management and aircraft auxiliary power systems command premium pricing for liquid organic hydride systems. Weight-sensitive applications accept 3–5x capital cost multiples versus terrestrial alternatives.
- Renewable Energy Plants:Concentrated solar power developers seek molten salt substitution pathways.
- Remote Facility Operators:Island and mountain installations in Japan leverage METI procurement preferences for metallic hydride demonstrations.
- Green Transportation:Maritime and heavy-duty vehicle applications are validating onboard thermal fuel storage.
Chemical manufacturers deploy the greatest cumulative capacity; aerospace operators are expanding most quickly on a percentage basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Neckar chemical corridor operates as a de facto special economic zone for thermochemical storage deployment, channeling EU Green Deal funding into Ludwigshafen and Leverkusen facility retrofits ahead of binding carbon intensity deadlines.
United States
Texas and Louisiana refinery complexes face EPA Title V operating permit renewals that mandate solar-derived process heat alternatives by 2027. Chemical manufacturers in the Gulf Coast corridor are pre-qualifying thermochemical storage vendors to secure compliance pathways. Houston and Port Arthur industrial clusters absorb the majority of metallic hydride pilot installations.
Japan
Remote island and mountain facilities drive demand for dispatch-independent thermal systems outside grid-connected markets. METI procurement preferences channel public funding into metallic hydride demonstration projects. Kyushu and Hokkaido installations validate system economics for isolated industrial loads.
Spain
Abengoa heritage concentrated solar power infrastructure anchors utility-scale thermal regeneration capacity across Iberia. Precision heliostat manufacturing concentrates in Andalusia and Extremadura, creating supply advantages for domestic project developers. Seville and Badajoz host the densest clusters of operational molten salt substitution pilots.
China
Dual carbon policy targets compress payback thresholds for industrial decarbonization investments in chemical manufacturing. MIIT standards harmonization accelerates domestic certification timelines versus European REACH equivalents. Yangtze River Delta chemical parks around Shanghai and Ningbo pilot silicon-based thermal storage media at scale.
Solar Thermal Fuel Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with heritage concentrated solar power developers commanding utility-scale thermal regeneration while materials science startups capture aerospace premium pricing. The vendor base concentrates around three strategic archetypes: legacy CSP infrastructure operators, AI-enabled heliostat field optimizers, and industrial automation integrators. Dominant competitive moves include backward integration into specialty chemical feedstock production and geographic expansion through Middle Eastern and Asian licensing partnerships.
Among heritage infrastructure operators, Abengoa Solar and BrightSource Energy exemplify the scale-driven archetype, anchoring project development capabilities across Iberia and North American desert regions. Heliogen occupies a distinct position within the AI-optimization tier, representing machine learning convergence with thermochemical receiver design. Siemens AG sits within the industrial automation integrator category, extending control systems expertise into chemical synthesis loops for thermal fuel applications.
| Leading Market Players |
|---|
| Abengoa Solar |
| BrightSource Energy |
| SolarReserve |
| Schott Solar |
| Siemens |
| Acciona |
| Heliogen |
| eSolar |
| Solareast Holdings Co. Ltd |
| Others |
Cost & Logistics Intelligence
Silicon feedstock indices and rare earth oxide benchmarks cascade through solar thermal fuel manufacturing into three-tier pricing structure across premium, standard, and economy levels. Aerospace buyers absorbing liquid organic hydride systems at 3–5x terrestrial multiples subsidize cost compression in industrial process heat tiers.
Pricing Analysis
Lead-time compression commands substantial premiums in heliostat field procurement, with spot inventory of precision mirrors trading at discounts to long-dated contracts. Project-based long-term offtake dominates utility-scale thermal regeneration, while modular storage media follow unit transactional models. Price differentiation separates REACH-registered molecular systems from pre-certified alternatives, with certification tier and volume scale as dual drivers. Cost compression in silicon-based media is intensifying because abundant feedstock expansion outpaces specialty chemical constraints. Chemical manufacturers in Germany's Rhine-Neckar cluster exhibit highest price sensitivity; aerospace operators accept premium positioning with minimal negotiation.
Supply Chain Analysis
Freight costs from Andalusian heliostat manufacturing clusters to Middle Eastern project sites impose location premiums that reshape procurement geography. Supply concentrates in Spain, Germany, and the United States for precision mirror fabrication; China and Japan anchor metallic hydride precursor production. Raw material dependencies draw from high-purity silicon, norbornadiene derivatives, and rare earth lanthanide feedstocks. Single-source vulnerability in precision heliostat manufacturing capacity creates chokepoint exposure for Asian developers. Distribution runs through EPC-contractor intermediaries in utility-scale segments, with direct procurement emerging in modular storage media.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar thermal fuel market functions as a cost-of-compliance arena where EU Green Deal binding carbon intensity targets erect regulatory moats favoring REACH-registered incumbents over unqualified entrants.
For Market Incumbents: Cement dominance in Germany's chemical corridor through captive supply of norbornadiene derivatives and backward integration into specialty chemical feedstock production. Lock in multi-year thermal service contracts with BASF, Covestro, and Lanxess ahead of 2030 compliance deadlines. Molten salt substitution resistance from sunk CSP infrastructure represents the primary substitution threat requiring pre-emptive retrofit bundling. For New Entrants and Emerging Players: Remote facility operators in Japan's island and mountain installations present the most penetrable buyer archetype given METI procurement preferences and limited incumbent presence. Metallic hydride systems for off-grid industrial loads offer white-space positioning outside grid-connected competitive intensity. Partner with domestic systems integrators for demonstration project credibility rather than direct EPC competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor AI-enabled heliostat optimizers with machine learning differentiation in Spain and the southwestern United States. Long-term viability across the analysis window hinges on ISO thermochemical safety standard harmonization unlocking cross-jurisdictional market access. Monitor ECHA registration completion rates for novel molecular storage materials as inflection indicator for competitive supply expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Chemical Feedstocks | Captive norbornadiene supply secures margin control against REACH-registered competitor pricing. |
| AI-Heliostat Field Optimization Partnership | Machine learning alignment algorithms unlock sub-100°C applications previously uneconomical for thermal regeneration. |
| ISO Thermochemical Safety Certification Program | Harmonized standards bridge CE marking and North American approval pathways for molecular storage systems. |
| Long-Term Thermal Service Agreement | Multi-year contracts with Ludwigshafen and Leverkusen chemical manufacturers lock in compliance-driven demand. |
| Metallic Hydride Demonstration Scale-Up | METI-funded island installations validate remote facility economics outside grid-connected competitive intensity. |
Research Approach
Trade data from Eurostat and UN Comtrade, ECHA REACH registration databases, and IEA technology roadmaps formed the secondary backbone for supply chain and regulatory mapping. Primary interviews with CSP project developers, thermochemical storage R&D directors, chemical plant procurement leads, and EPC contractors validated technical and commercial assumptions. Bottom-up installation capacity modeling combined with top-down policy-driven demand projections enabled cross-verification of market sizing across the analysis window.
Historical trendline analysis of concentrated solar power deployment rates and thermochemical storage pilot completions informed growth trajectory assumptions. Segmentation modeling covered molecular storage mechanism, conversion pathway technology, heat delivery application, and end-user procurement authority. CAGRs derived from policy deadline alignment, technology cost curve trajectories, and industrial decarbonization investment cycles. Forecast inputs incorporated EU Green Deal compliance timeline rigidity and EPA Title V permit renewal schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA evaluation period extensions, heliostat manufacturing capacity expansion rates, and molten salt substitution resistance in legacy CSP assets. Forecasts reflect documented assumptions about regulatory harmonization and technology efficiency thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Thermal Energy Storage
Thermal Recovery Market
Thermal Energy Storage
Thermal Energy Storage (TES) Market
Thermal Energy Storage
Africa Thermal Energy Storage Market
Thermal Energy Storage
Europe Thermal Energy Storage Market
Thermal Energy Storage
Molten Salt Thermal Energy Storage (TES) Market
Thermal Energy Storage
Russia Thermal Power Market
Thermal Energy Storage
United States Thermal Power Market
Thermal Energy Storage
China Thermal Power Plant Market
Thermal Energy Storage
Asia-Pacific Thermal Energy Storage Market
Thermal Energy Storage
Southeast Asia Thermal Power Market
Thermal Energy Storage
North America Thermal Power Market
Thermal Energy Storage
Ice Thermal Storage Systems Market
Thermal Energy Storage
Europe District Heating Market
Thermal Energy Storage
Middle-East and Africa Thermal Power Market
Thermal Energy Storage
North America Thermal Energy Storage Market