
 Southeast Asia Thermal Power Market | 2026-2036
Southeast Asia Thermal Power Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Thermal Power Market Analytics
The premium ultra-supercritical segment is restructuring away from subcritical commodity builds as efficiency mandates and fuel cost volatility widen the performance gap between high-efficiency installations and legacy plants. PT Perusahaan Listrik Negara (PLN) leverages its integrated fuel procurement position to anchor Indonesian coal-fired expansion. Electricity Generating Authority of Thailand (EGAT) competes through gas-fired combined cycle diversification. Mitsubishi Power dominates technology licensing for advanced turbine systems across the region.
Southeast Asia thermal power encompasses electricity generation facilities that combust fossil fuels or biomass to produce steam or hot gases driving turbine-generator sets, with operational parameters ranging from subcritical (below 221 bar) to ultra-supercritical (above 250 bar, 600°C+) steam conditions. These installations primarily serve baseload and intermediate dispatch requirements for national grids and industrial complexes. Coal-fired capacity retains the largest installed base among type segments, though combined cycle gas turbine technology captures expanding share as LNG import infrastructure matures across Thailand, Malaysia, and Singapore. The retrofit and upgrade installation category gathers momentum as aging subcritical fleets face efficiency compliance deadlines and carbon intensity benchmarks tighten.
Indonesia's Ministry of Energy and Mineral Resources enforces domestic market obligation rules on coal supply, while Thailand's Department of Alternative Energy Development and Efficiency imposes efficiency standards under the Energy Conservation Act. Vietnam's Ministry of Industry and Trade governs power development planning through sequential PDP iterations that determine project licensing timelines. Stakeholders must weigh fuel price hedging instruments against technology lock-in risks as the region's generation mix navigates between energy security imperatives and decarbonization trajectories.
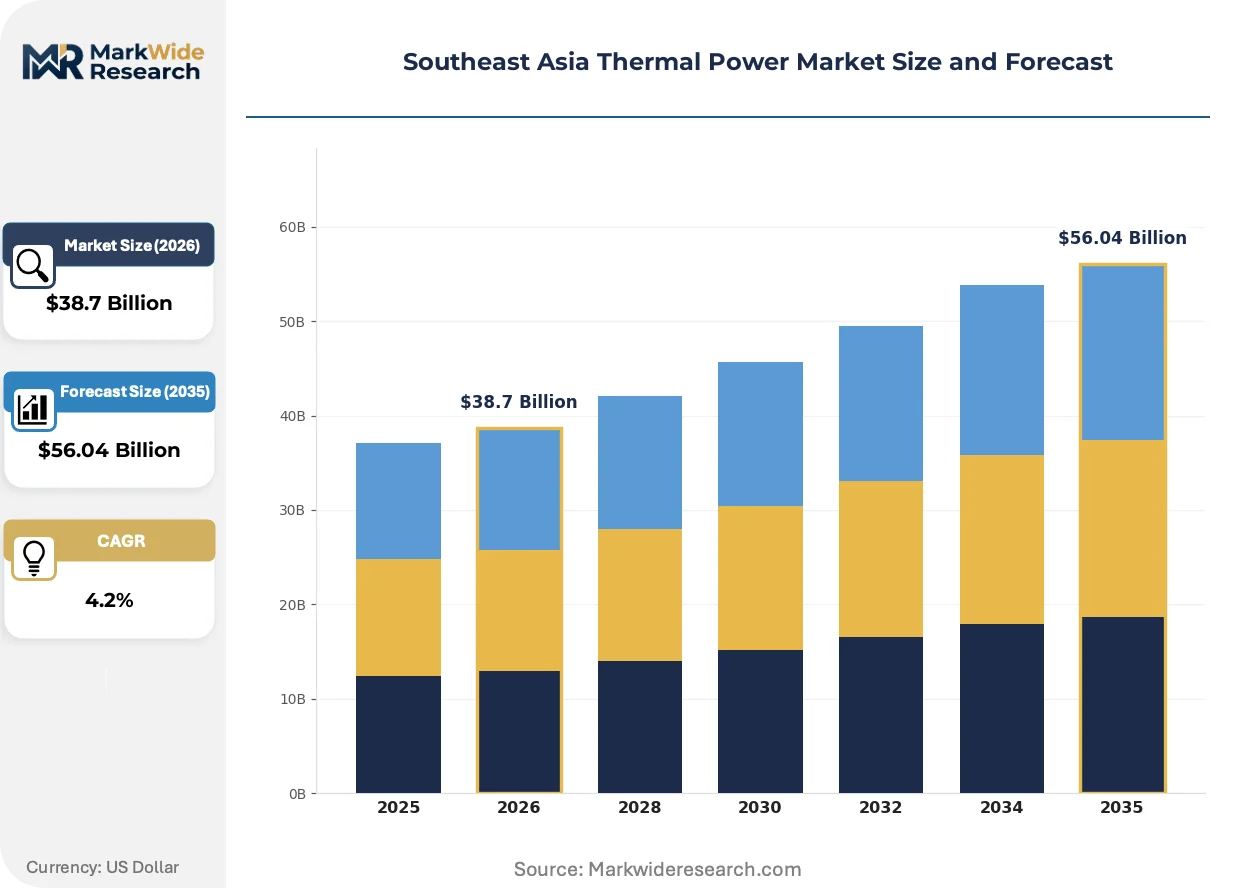
Market Dynamics
Ultra-supercritical steam technology is compressing the economic viability window for subcritical coal installations across Vietnam, Indonesia, and Thailand as efficiency mandates harden and fuel cost volatility intensifies.
Growth Catalysts
- ASEAN Power Grid Integration:Cross-border transmission protocols are unlocking regional electricity trading, enabling surplus thermal generation in Indonesia to serve demand spikes in Thailand and Vietnam.
- Industrial Load Expansion:Smelters, petrochemical complexes, and data centers across the region are driving baseload capacity additions as manufacturing reshoring accelerates.
- Domestic Market Obligation Rules:Indonesia's Ministry of Energy and Mineral Resources mandates that coal producers reserve specific volumes for local power generation, securing fuel supply certainty for PLN's expansion program.
Market Restraints
- Capital Intensity of Ultra-Supercritical Builds:Advanced turbine systems require substantially higher upfront investment than subcritical alternatives, constraining project finance availability for independent power producers.
- LNG Price Volatility:Thailand and Singapore's gas-fired combined cycle fleets face margin compression when spot LNG prices spike, undermining dispatch competitiveness against coal.
- Carbon Border Adjustment Mechanisms:The EU's CBAM is pressuring export-oriented industrial zones in Vietnam to demonstrate lower-carbon electricity sourcing, threatening thermal power offtake contracts.
Strategic Opportunities
- Retrofit and Upgrade Services:Aging subcritical fleets in the Philippines and Malaysia face efficiency compliance deadlines, creating aftermarket revenue pools for turbine OEMs and engineering contractors.
- Biomass Co-firing Integration:Palm oil residues and agricultural waste offer fuel diversification pathways for existing coal plants seeking carbon intensity reductions under emerging sustainability frameworks.
- Industrial Captive Generation:Mining and smelting operations in Indonesia's eastern provinces are developing self-supply thermal capacity where grid extension remains uneconomical.
Industry Challenges
- Specialized Welding and Materials Expertise:Ultra-supercritical conditions demand advanced alloys and precision fabrication capabilities that remain scarce across Southeast Asian engineering workforces.
- Grid Synchronization Complexity:Variable renewable penetration in Thailand and Vietnam is forcing thermal operators to cycle more frequently, accelerating turbine fatigue and maintenance cost escalation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Thermal Power Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Coal, Natural Gas, Oil, Biomass Technology: Conventional, Combined Cycle, Integrated Gasification, Supercritical End User: Utilities, Industrial, Commercial, Residential Installation: New Build, Retrofit, Upgrade, Maintenance |
| Companies Covered | PT Perusahaan Listrik Negara (PLN), Electricity Generating Authority of Thailand (EGAT), Tenaga Nasional Berhad, Singapore Power, First Gen Corporation, Mitsubishi Power, China Huaneng Group, Duke Energy Corporation, Eskom Holdings SOC Ltd., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Thermal Power Market Evolving Landscape
Digital plant control systems and advanced materials science are redefining operational economics for thermal assets, while regulatory pressure on carbon intensity accelerates technology substitution cycles.
Distributed battery energy storage is decentralizing grid balancing responsibilities away from centralized thermal peaking plants. Industrial facilities in Thailand are installing co-located storage to manage ramping requirements, reducing reliance on gas-fired spinning reserve. This shift is compressing revenue streams for intermediate-load thermal units that previously captured scarcity pricing during demand spikes.
Thailand's Energy Conservation Act imposes efficiency standards on generation assets above specific capacity thresholds, mandating heat rate improvements or retirement timelines. The Department of Alternative Energy Development and Efficiency enforces compliance through periodic audits, pushing EGAT toward combined cycle upgrades. Coal-dependent utilities face accelerated depreciation schedules as regulatory depreciation allowances tighten for subcritical technology classes.
Power purchase agreement structures are evolving from single-buyer, take-or-pay contracts toward merchant exposure and index-linked pricing. Industrial offtakers in Vietnam's northern economic zones are negotiating shorter-term agreements with multiple suppliers, fragmenting revenue predictability for project developers. This behavioral shift concentrates in manufacturing corridors where alternative supply options from captive generation or cross-border imports create negotiating leverage.
Southeast Asia Thermal Power Market Segmentation
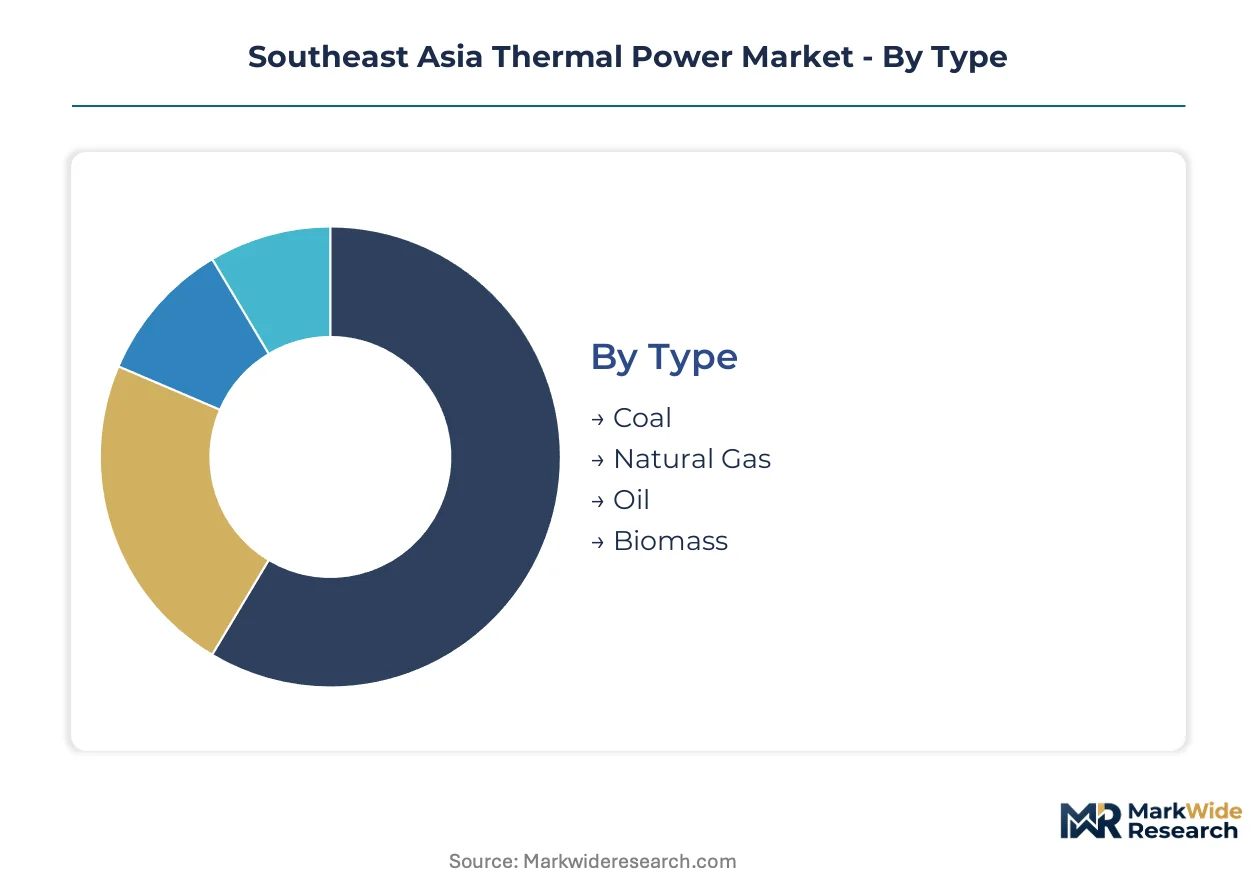
Thermal power assets in Southeast Asia fragment across fuel types, technology classes, and ownership structures that determine capital deployment patterns and regulatory exposure. Understanding these segment boundaries clarifies where PLN, EGAT, and independent developers allocate engineering resources and procurement budgets.
Type:
Capital intensity varies sharply across fuel categories, with coal and integrated gasification requiring the heaviest upfront infrastructure investment while oil and biomass offer lower entry thresholds.
- Coal:Subcritical and ultra-supercritical steam plants combust pulverized coal or lignite to drive turbine-generator sets at pressures ranging from 170 bar to 300 bar. Indonesian domestic market obligation rules secure fuel supply for PLN's base-load expansion across Java and Sumatra, though carbon border adjustment exposure from EU trade policy threatens export-zone offtake.
- Natural Gas:Combined cycle gas turbines and simple-cycle peakers combust regasified LNG or pipeline gas, offering faster ramp rates than coal alternatives. Thailand's EGAT and Malaysia's TNB concentrate capacity additions around LNG import terminals at Map Ta Phut and Sungai Udang, where spot price volatility compresses dispatch margins during supply shocks.
- Oil:Diesel and heavy fuel oil plants serve remote island grids and emergency peaking roles where pipeline or LNG infrastructure remains uneconomical. Philippine utilities in the Visayas archipelago retain oil-fired spinning reserve for grid stability.
- Biomass:Agricultural residues and energy crops combust in dedicated boilers or co-fire with coal, reducing carbon intensity for existing assets. Palm oil mill effluent and rice husks concentrate supply in Indonesia's Riau province and Thailand's central plains.
Most installed capacity flows through Coal. Expansion is steepest in Natural Gas.
Technology:
Efficiency tiers separate segments by heat rate performance and emissions intensity, with advanced cycles commanding premium equipment costs and specialized maintenance protocols.
- Conventional:Subcritical steam and simple-cycle gas turbines operate at established thermodynamic limits with mature supply chains. Aging conventional fleets in the Philippines face efficiency compliance deadlines under Department of Energy regulations.
- Combined Cycle:Gas turbines exhaust into heat recovery steam generators to extract additional work, achieving thermal efficiencies above 60%. EGAT's Chana and Nam Phong stations anchor Thailand's intermediate dispatch capacity.
- Integrated Gasification:Coal or biomass converts to synthetic gas before combustion, enabling carbon capture integration and fuel flexibility. Demonstration projects in Indonesia's Riau province test operational economics at scale.
- Supercritical:Ultra-supercritical steam conditions above 250 bar and 600°C maximize thermal efficiency for coal units. Vietnam's Vinh Tan and Duyen Hai complexes deploy Mitsubishi Power turbine systems under Ministry of Industry and Trade licensing.
Conventional technology retains the largest operating base. Combined Cycle is gaining share fastest.
End User:
Customer concentration and contract duration differentiate segments, with utilities locking in long-term power purchase agreements while industrial offtakers negotiate shorter indexed terms.
- Utilities:State-owned PLN, EGAT, and TNB operate transmission-connected generation under regulated tariff frameworks. Vietnam's Electricity of Vietnam procures capacity through competitive bidding rounds governed by sequential power development plans.
- Industrial:Smelters, petrochemical complexes, and data centers develop captive generation or contract directly with independent power producers. Indonesia's nickel processing corridors in Sulawesi anchor rising thermal demand from battery material supply chains.
- Commercial:Shopping centers, hospitals, and office towers install distributed gas engines and diesel backup where grid reliability fluctuates. Bangkok and Ho Chi Minh City building codes increasingly mandate on-site resilience.
- Residential:Mini-grid diesel and biomass units serve unelectrified settlements beyond centralized network reach. Indonesia's Nusa Tenggara islands and Philippine Mindanao barangays concentrate off-grid thermal deployment.
Utilities channel the majority of capacity investment. Industrial offtake is expanding most quickly.
Installation:
Project lifecycle positioning determines revenue timing and competitive intensity, with new builds requiring extended development timelines while retrofit services offer faster conversion cycles.
- New Build:Greenfield coal, gas, and biomass plants proceed through permitting, financing, and construction phases spanning multiple years. Indonesia's 35,000 MW program and Vietnam's PDP8 drive pipeline concentration.
- Retrofit:Emissions control and efficiency upgrades extend operational life for aging subcritical assets. Malaysian coal plants face tightening Department of Environment standards on particulate and sulfur oxide emissions.
- Upgrade:Turbine blade replacement, control system modernization, and heat rate improvements enhance performance without full rebuild. EGAT's combined cycle fleet undergoes scheduled hot gas path inspections and compressor overhauls.
- Maintenance:Long-term service agreements and spare parts procurement sustain availability guarantees for OEM-installed equipment. Mitsubishi Power and Siemens Energy anchor aftermarket revenue pools across the region.
New Build commands the largest capital deployment. Retrofit activity is accelerating most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's coal-fired expansion outpaces Vietnam's gas diversification, while Thailand anchors regional LNG import infrastructure and the Philippines confronts aging fleet modernization pressures.
Indonesia
Domestic market obligation rules secure coal supply for PLN's 35,000 MW program across Java and Sumatra. The Ministry of Energy and Mineral Resources mandates local fuel reservation, insulating generators from international price spikes. Nickel smelting corridors in Sulawesi's Morowali Industrial Park drive captive thermal demand as battery material supply chains concentrate.
Vietnam
Power Development Plan 8 reorients capacity licensing toward gas-fired combined cycle and LNG terminals. The Ministry of Industry and Trade governs competitive bidding rounds for independent power producers. Northern economic zones around Hai Phong and Bac Ninh host manufacturing clusters negotiating shorter-term indexed supply contracts.
Thailand
EGAT diversifies from coal dependence through Map Ta Phut LNG import infrastructure and Chana combined cycle expansion. The Department of Alternative Energy Development and Efficiency enforces heat rate standards under the Energy Conservation Act. Eastern Economic Corridor industrial estates attract data center and petrochemical loads requiring baseload reliability.
Philippines
Aging subcritical coal fleets in Luzon face Department of Energy efficiency compliance deadlines and emissions control retrofits. Visayas archipelago utilities retain oil-fired spinning reserve where pipeline infrastructure remains uneconomical. Mindanao barangays concentrate off-grid diesel and biomass mini-grid deployment beyond centralized network reach.
Malaysia
Tenaga Nasional Berhad anchors capacity additions around Sungai Udang LNG terminals and peninsula grid interconnection. The Department of Environment tightens particulate and sulfur oxide standards on existing coal assets. Sarawak and Sabah eastern provinces develop remote industrial captive generation where transmission extension costs prove prohibitive.
Southeast Asia Thermal Power Market Competitive Landscape
Top-tier vendors anchor technology licensing and long-term service agreements, while independent power producers and state utilities occupy project development and asset operation tiers. Market structure concentrates around three strategic archetypes: integrated state utilities controlling fuel procurement and grid access, multinational turbine OEMs capturing equipment and aftermarket revenue, and regional engineering contractors executing EPC delivery. Competitive moves center on ultra-supercritical technology partnerships and retrofit service contract capture.
Within the state utility archetype, PT Perusahaan Listrik Negara and Electricity Generating Authority of Thailand exemplify vertically integrated market presence through generation, transmission, and fuel procurement control. Mitsubishi Power occupies the technology licensing tier, representing advanced turbine system providers serving regional ultra-supercritical deployments. These entities exemplify how fuel supply certainty and equipment specialization divide competitive positioning across the Southeast Asian thermal power value chain.
| Leading Market Players |
|---|
| PT Perusahaan Listrik Negara (PLN) |
| Electricity Generating Authority of Thailand (EGAT) |
| Tenaga Nasional Berhad |
| Singapore Power |
| First Gen Corporation |
| Mitsubishi Power |
| China Huaneng Group |
| Duke Energy Corporation |
| Eskom Holdings SOC Ltd. |
| Others |
Value Network & Pricing Analysis
Industrial offtakers in Vietnam's northern economic zones negotiating shorter-term indexed supply contracts are forcing project developers toward merchant exposure models that compress revenue predictability and intensify price competition for baseload capacity.
Pricing Analysis
Capacity additions in Indonesia and Vietnam are reshaping price floors for ultra-supercritical coal installations as efficiency mandates harden and fuel cost volatility intensifies. Project-based long-term offtake contracts with take-or-pay structures dominate utility-scale developments, while industrial captive generation commands premium pricing for reliability guarantees. Price differentiation rests on technology tier and fuel supply certainty, with PLN's integrated coal procurement insulating Indonesian assets from international price spikes. Cost compression in gas-fired combined cycle capacity is intensifying because spot LNG volatility undermines dispatch economics against coal alternatives. State utilities exhibit lowest price sensitivity due to regulated tariff frameworks, while independent power producers face acute margin pressure from financing cost escalation.
Supply Chain Analysis
Dual-sourcing requirements for advanced turbine systems are mandating multi-supplier qualification across Mitsubishi Power, Siemens Energy, and domestic engineering contractors to mitigate fabrication bottlenecks. Manufacturing concentration centers on Japan, Germany, and China for precision-forged rotors and advanced alloy components. Raw material dependencies draw from nickel superalloys, high-grade steel forgings, and specialized welding consumables. Single-source vulnerability persists for ultra-supercritical pressure vessel fabrication capabilities. Distribution runs through EPC contractors executing turnkey delivery for PLN, EGAT, and Vietnam's Electricity of Vietnam procurement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Thailand's Energy Conservation Act efficiency mandates and Indonesia's domestic market obligation rules are accelerating technology substitution cycles and reshaping competitive positioning.
For Market Incumbents: To counter carbon border adjustment exposure from EU trade policy, PLN and EGAT should deepen backward integration into fuel procurement while accelerating combined cycle upgrades at Chana and Nam Phong stations. Certification investment in biomass co-firing integration offers pathway to carbon intensity compliance without stranded asset risk. For New Entrants and Emerging Players: Nickel smelting corridors in Sulawesi's Morowali Industrial Park represent the most penetrable white-space target, with captive thermal demand from battery material supply chains outpacing grid extension timelines. Engineering contractors should target retrofit and upgrade services for aging subcritical fleets in the Philippines facing Department of Energy compliance deadlines. Go-to-market positioning through long-term service agreements with Mitsubishi Power technology licensing anchors aftermarket revenue capture. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized welding and materials expertise providers serving ultra-supercritical turbine deployments, where capability scarcity commands premium valuation multiples. Five-to-ten year viability framing favors retrofit service contractors over greenfield developers given permitting timeline compression. The signal to watch is frequency of grid synchronization events forcing thermal cycling, which accelerates maintenance cost escalation and expands addressable aftermarket spend.| Strategic Initiative | Industry Significance |
|---|---|
| Ultra-Supercritical Technology Licensing | Mitsubishi Power anchors regional turbine supply through proprietary steam condition designs exceeding 250 bar. |
| Biomass Co-firing Integration | Palm oil residues in Riau province and rice husks in Thailand's central plains enable carbon intensity reduction for existing coal assets. |
| Retrofit and Upgrade Services | Philippine subcritical fleets facing Department of Energy deadlines create aftermarket revenue pools for blade replacement and control modernization. |
| Industrial Captive Generation | Mining and smelting operations in Indonesia's eastern provinces develop self-supply capacity where grid extension remains uneconomical. |
| Cross-Border Power Trading | ASEAN power grid integration protocols unlock regional electricity trading from Indonesian surplus to Thai and Vietnamese demand spikes. |
Research Methodology
Multiple input streams — structured interviews with utility planning officers and IPP project developers, EPC contractor project databases, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged fuel supply specialists, grid operators, and aftermarket service heads across Indonesia, Vietnam, Thailand, and the Philippines. Secondary validation drew from EIA data, IEA power market reports, FERC comparable filings, and ASEAN energy integration protocols. Bottom-up project pipeline enumeration was cross-checked against top-down national power development plan targets to ensure methodological consistency.
Data-stream reconciliation across fuel source, generation capacity tier, project scale, and regional grid type dimensions enabled granular forecasting without mechanical extrapolation. CAGRs were derived from segment-level buildout trajectories and technology substitution elasticity estimates across the projection horizon. Model inputs incorporated Ministry of Industry and Trade licensing timelines, PLN procurement schedules, and LNG terminal commissioning sequences as industry-specific demand drivers.
Underlying measurement precision varies by segment; new build capacity pipelines carry tighter precision than retrofit activity given permitting visibility. Forecasts reflect documented assumptions on regulatory enforcement intensity and cross-border transmission protocol implementation. Deviation in EU carbon border adjustment mechanism scope expansion or domestic market obligation rule relaxation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Thermal Energy Storage
Molten Salt Thermal Energy Storage (TES) Market
Thermal Energy Storage
Asia-Pacific Thermal Energy Storage Market
Thermal Energy Storage
Solar Thermal Fuel Market
Thermal Energy Storage
Ice Thermal Storage Systems Market
Thermal Energy Storage
United States Thermal Power Market
Thermal Energy Storage
Thermal Energy Storage (TES) Market
Thermal Energy Storage
Thermal Recovery Market
Thermal Energy Storage
Europe District Heating Market
Thermal Energy Storage
Middle-East and Africa Thermal Power Market
Thermal Energy Storage
North America Thermal Energy Storage Market
Thermal Energy Storage
North America Thermal Power Market
Thermal Energy Storage
Africa Thermal Energy Storage Market
Thermal Energy Storage
Russia Thermal Power Market
Thermal Energy Storage
China Thermal Power Plant Market
Thermal Energy Storage
Europe Thermal Energy Storage Market