
 Middle-East and Africa Thermal Power Market | 2026-2036
Middle-East and Africa Thermal Power Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Thermal Power Market Foresight
The premium-to-commodity split in turbine procurement is rebalancing as utilities prioritize heat-rate efficiency over unit cost for baseload duty cycles. Saudi Electricity Company leverages captive fuel supply chains and long-term service agreements to sustain fleet availability across the Kingdom's summer peak load regime. Eskom Holdings SOC Ltd anchors South Africa's coal-reliant grid while navigating fuel quality constraints and transmission bottlenecks. Siemens AG competes on combined cycle technology leadership, offering F-class and H-class turbines optimized for Middle Eastern ambient temperature profiles.
Middle-East and Africa thermal power encompasses electricity generation facilities that combust fossil fuels or biomass to produce steam or hot exhaust gases driving turbine-generator sets, with modern combined cycle plants achieving thermal efficiencies exceeding sixty percent through sequential gas and steam turbine operation. The primary purpose is reliable baseload and intermediate power delivery to national grids, industrial parks, and desalination complexes across arid and semi-arid climates. Natural gas-fired capacity dominates new additions across the Gulf states, while coal-fired generation retains structural share in South Africa's mining belt and emerging African markets. Combined cycle technology captures the fastest growth trajectory as utilities seek to maximize output per unit of fuel consumed amid domestic gas reservation policies. Desalination co-production applications concentrate margin pools in Saudi Arabia and the UAE, where dual-purpose plants integrate power and water output.
Saudi Arabia's Energy Efficiency Center and South Africa's National Energy Regulator shape plant licensing, emissions benchmarking, and grid connection standards across the region. Egypt's electricity regulator and the Gulf Cooperation Council's interconnected grid codes are tightening NOx and particulate thresholds, forcing retrofit investments or early retirement of open-cycle peakers. Stakeholders must monitor fuel subsidy reform timelines and carbon border adjustment preparations in key export destinations.
Market Dynamics
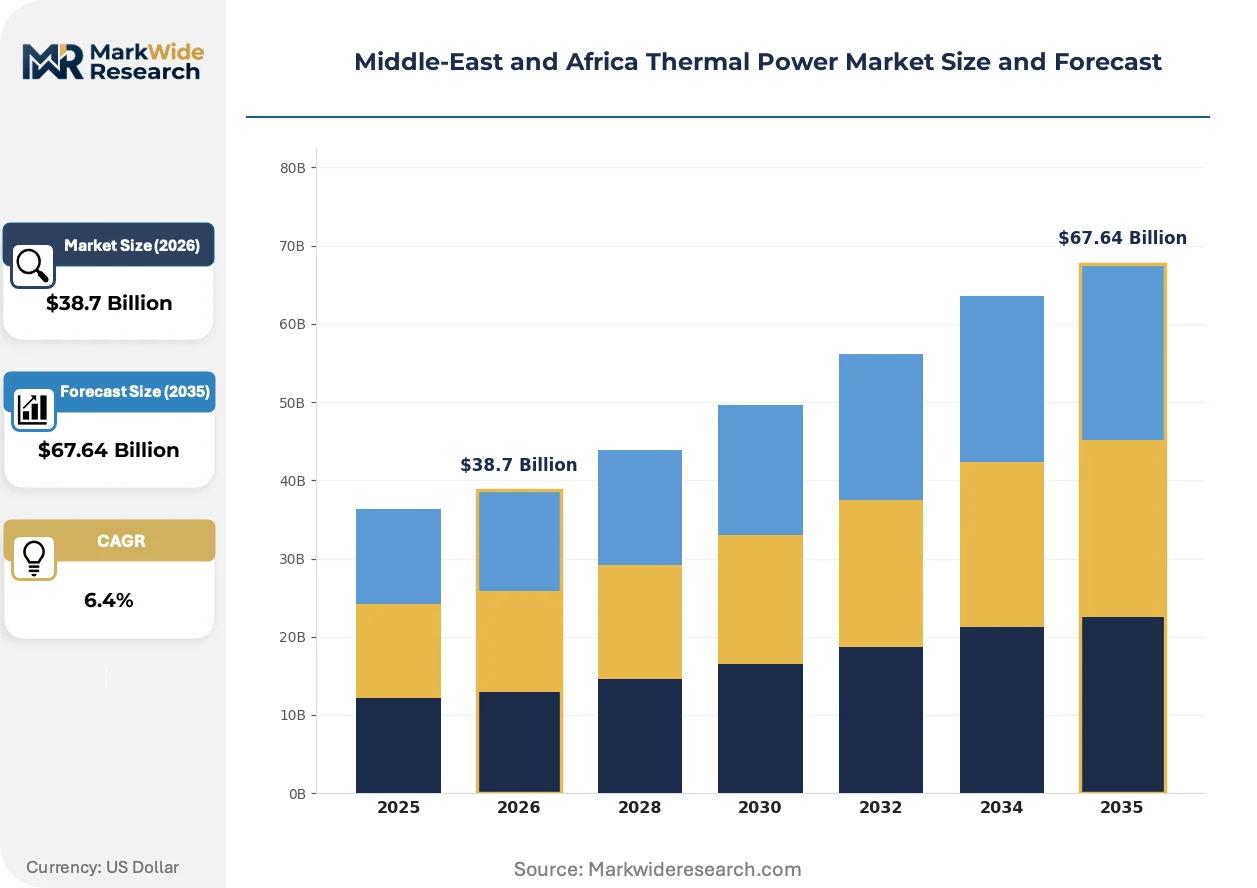
Combined cycle gas turbine technology is reconfiguring procurement priorities across the Middle-East and Africa as utilities trade unit capital cost for heat-rate efficiency in baseload duty cycles. Saudi Arabia's domestic gas reservation policies and Egypt's industrial zone electrification mandates are accelerating this equipment transition.
Growth Catalysts
- Desalination co-production demand:Dual-purpose power and water facilities in Saudi Arabia and the UAE concentrate capital deployment toward high-efficiency thermal blocks. These integrated plants command premium turbine specifications.
- Saudi Energy Efficiency Center mandates:National efficiency benchmarking and emissions licensing standards force fleet upgrades. Compliance deadlines compress procurement timelines for combined cycle retrofits.
- Gulf Cooperation Council grid interconnection:Cross-border transmission capacity expansion enables larger baseload units. Member utilities synchronize procurement to capture scale economies in turbine supply.
Market Restraints
- Domestic gas supply reservation policies:Saudi Arabia and Qatar prioritize feedstock for petrochemicals over power generation. Fuel allocation uncertainty delays project financial close.
- Steam turbine OEM supply concentration:European and Japanese manufacturers control H-class blade casting capacity. Lead times extend to 24 months for critical hot gas path components.
- Coal quality degradation in South Africa:Eskom's aging mine-mouth plants face calorific value decline and ash content rise. Boiler tube erosion accelerates maintenance outages.
Strategic Opportunities
- Morocco and Algeria gas import infrastructure:LNG terminal expansions and Maghreb-Europe pipeline reversals enable new combined cycle siting. These markets remain underpenetrated by F-class turbine vendors.
- Carbon capture retrofit readiness:Post-combustion solvent systems and oxy-fuel turbine designs converge. Early-mover utilities in the UAE position for future blue hydrogen export certification.
- Long-term service agreement unbundling:Independent power producers negotiate component-level maintenance contracts. This channel innovation fragments OEM aftermarket capture.
Industry Challenges
- Gas turbine controls engineering talent scarcity:Distributed control system programming and combustion tuning expertise concentrates in European and North American labor pools. Local training pipelines remain underdeveloped.
- Grid code harmonization across Gulf Cooperation Council interconnectors:Frequency response and voltage ride-through standards vary by member state. Equipment certification complexity extends commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Thermal Power Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coal-Fired, Natural Gas, Oil-Fired, Biomass Technology: Combined Cycle, Open Cycle, Steam Turbine, Geothermal Application: Power Generation, Industrial Use, District Heating, Desalination End User: Utilities, Independent Power Producers, Government, Commercial |
| Companies Covered | Saudi Electricity Company, Eskom Holdings SOC Ltd, Dubai Electricity and Water Authority, Acwa Power Barka SAOG, Siemens AG, Electricite de France SA, Egyptian Electricity Holding Company, Marubeni Corporation, General Electric Company, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Thermal Power Market Shifts & Advancements
Equipment specification standards are tightening as ambient temperature performance and part-load efficiency displace nameplate capacity as primary procurement metrics. This reorientation favors advanced cooling systems and sequential combustion architectures.
H-class gas turbines with sequential combustion and advanced blade cooling are overtaking F-class units in new-build procurement across the Gulf Cooperation Council. Saudi Electricity Company and Emirates Water and Electricity Company specify these machines for 60°C ambient operation. The technology is compressing heat rates below 6,300 kJ/kWh and enabling larger single-train blocks that reduce civil works intensity.
Saudi Arabia's Energy Efficiency Center and South Africa's National Energy Regulator are tightening NOx emissions thresholds and mandating continuous emissions monitoring systems. These frameworks force retrofit investments in selective catalytic reduction and dry low-NOx combustors. Open-cycle peakers in Egypt's Red Sea corridor face accelerated retirement or expensive compliance upgrades.
Power purchase agreement tenor compression is reshaping project finance structures and equipment ownership models. Independent power producers in Morocco and Jordan now seek 15-year debt tenors versus historical 20-25 year arrangements. This pattern concentrates procurement risk on OEMs and EPC contractors, who must absorb residual value exposure in shorter contractual frameworks.
Middle-East and Africa Thermal Power Market Segmentation
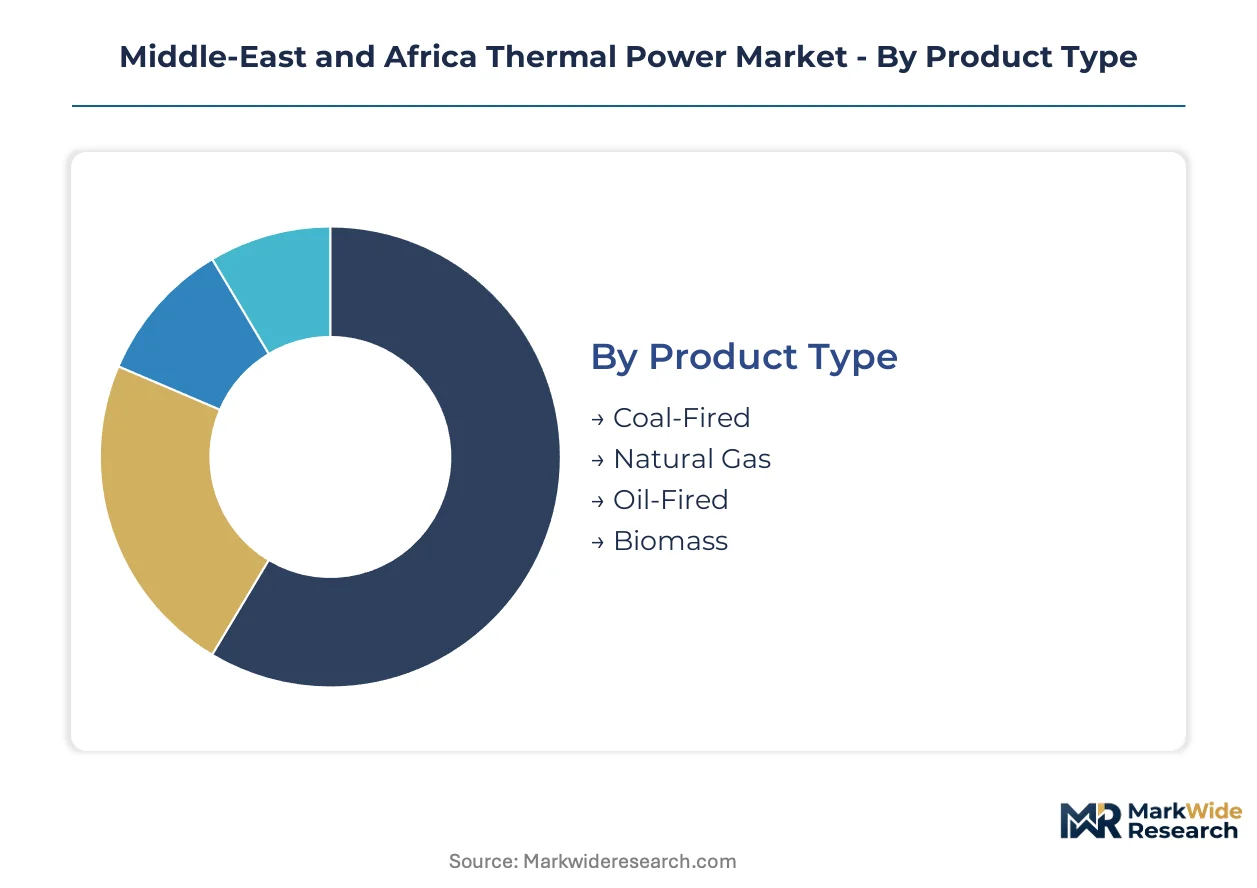
Thermal power procurement across the Middle-East and Africa fragments across fuel types, turbine technologies, and end-use applications. Equipment specification and ownership structure determine financing terms, service contract design, and regulatory compliance obligations for developers and utilities.
Product Type:
Natural gas and coal occupy opposite ends of the integration spectrum—gas turbines embed in combined cycle blocks while coal units often operate as standalone mine-mouth stations.
- Natural Gas:Combined cycle configurations dominate new capacity additions across Saudi Arabia, the UAE, and Egypt. Saudi Electricity Company specifies F-class and H-class turbines for 60°C ambient operation in dual-purpose power and desalination facilities.
- Coal-Fired:Eskom Holdings SOC Ltd operates sub-critical and super-critical units in South Africa's Mpumalanga mining belt. Calorific value degradation and ash content rise accelerate maintenance outages and tube erosion.
- Oil-Fired:Open-cycle peakers in Egypt's Red Sea corridor and Lebanon's grid provide seasonal peak shaving. Saudi Arabia's Energy Efficiency Center mandates are forcing early retirement or expensive retrofit investments.
- Biomass:Agricultural residue combustion in Morocco and Tunisia remains nascent. Feedstock logistics and seasonal supply variability constrain baseload deployment.
Volume placements concentrate in Natural Gas; the faster expansion belongs to Biomass pilot projects under Gulf renewable diversification mandates.
Technology:
Capital intensity and efficiency gradients separate turbine architectures, with heat-rate performance now displacing nameplate capacity as the primary procurement metric.
- Combined Cycle:Sequential gas and steam turbine operation achieves thermal efficiencies exceeding sixty percent. Emirates Water and Electricity Company and Saudi Electricity Company specify these systems for baseload duty cycles and desalination co-production.
- Open Cycle:Simple gas turbines provide fast-start peaking capacity. Egypt's electricity regulator is tightening NOx thresholds that threaten continued operation of aging Red Sea corridor units.
- Steam Turbine:Coal and nuclear applications in South Africa rely on sub-critical and super-critical steam cycles. European and Japanese OEMs control H-class blade casting capacity with twenty-four-month lead times.
- Geothermal:Rift Valley resources in Ethiopia and Kenya remain pre-commercial. Exploration drilling and reservoir confirmation delays project development timelines.
Procurement volume clusters in Combined Cycle; Open Cycle faces structural decline under emissions compliance pressure.
Application:
Duty cycle characteristics—capacity factor, ramp rate requirements, and output predictability—shape equipment selection and project economics across use cases.
- Power Generation:Grid-connected baseload and intermediate capacity serves national utilities and Gulf Cooperation Council interconnectors. Saudi Arabia's domestic gas reservation policies constrain fuel allocation certainty.
- Desalination:Dual-purpose facilities in Saudi Arabia and the UAE integrate power and water output. These plants command premium turbine specifications and long-term service agreements.
- Industrial Use:Captive power for petrochemical complexes and aluminum smelters in Qatar and Bahrain. Industrial zone electrification mandates in Egypt are accelerating dedicated capacity additions.
- District Heating:Combined heat and power applications remain limited by climate and urban density. Morocco and Algeria pilot projects test technical viability.
Capital deployment concentrates in Power Generation; Desalination claims the steepest expansion trajectory under water security pressures.
End User:
Balance sheet strength and fuel access determine procurement scale, technology tier, and contract structure across ownership categories.
- Utilities:Saudi Electricity Company and Eskom Holdings SOC Ltd anchor fleet expansion with sovereign-backed financing. Long-term service agreements sustain availability across summer peak load regimes.
- Independent Power Producers:Merchant and contracted developers in Morocco and Jordan negotiate shorter power purchase agreement tenors. Fifteen-year debt arrangements concentrate residual value risk on EPC contractors.
- Government:Direct ownership of strategic reserve capacity and rural electrification assets. Procurement timelines compress around compliance deadlines from national efficiency regulators.
- Commercial:Captive industrial generation for mining and manufacturing operations in South Africa and Ghana. Grid reliability concerns and tariff volatility drive behind-the-meter investment.
Contract volume concentrates in Utilities; Independent Power Producers are gaining share fastest under privatization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jubail Industrial City corridor anchors thermal power deployment across the Middle-East and Africa, hosting dual-purpose desalination complexes that command premium turbine specifications for 60°C ambient operation.
Saudi Arabia
Saudi Electricity Company expands baseload capacity to serve industrial zones and desalination complexes under the Kingdom's national industrial strategy. The Saudi Energy Efficiency Center mandates continuous emissions monitoring and efficiency benchmarking that compress procurement timelines for combined cycle retrofits. Riyadh and the Eastern Province concentrate fleet investment where captive fuel supply chains sustain availability across summer peak load regimes.
United Arab Emirates
Emirates Water and Electricity Company specifies H-class turbines for integrated power and water facilities facing water security pressures. Dubai Electricity and Water Authority shapes procurement standards through long-term service agreements and grid interconnection requirements. The Jebel Ali power and desalination complex exemplifies dual-purpose capital deployment toward high-efficiency thermal blocks.
Egypt
Industrial zone electrification mandates accelerate dedicated capacity additions to serve manufacturing corridors. The Egyptian Electricity Holding Company navigates tightening NOx thresholds that threaten continued operation of aging Red Sea corridor open-cycle peakers. The Suez Canal Economic Zone concentrates new combined cycle siting where gas import infrastructure expansion enables larger baseload units.
South Africa
Eskom Holdings SOC Ltd operates sub-critical and super-critical coal units in the Mpumalanga mining belt while facing calorific value degradation and ash content rise. The National Energy Regulator shapes plant licensing and emissions benchmarking standards across the national grid. Johannesburg and the Highveld cluster anchor coal-reliant generation where transmission bottlenecks constrain fleet dispatch flexibility.
Morocco
LNG terminal expansions and Maghreb-Europe pipeline reversals enable new combined cycle siting in underpenetrated markets. Independent power producers negotiate shorter power purchase agreement tenors that concentrate residual value risk on EPC contractors. The Tangier Med industrial port zone attracts captive power investment for automotive and aeronautics manufacturing operations.
Middle-East and Africa Thermal Power Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology tier and service integration depth in the Middle-East and Africa thermal power market. Equipment specification standards favor heat-rate efficiency over unit capital cost, compressing vendor margins for standardized F-class turbines while rewarding advanced cooling and sequential combustion architectures. Two strategic archetypes dominate: integrated OEM-EPC consortia that bundle long-term service agreements, and independent power producers that unbundle component-level maintenance contracts. Competitive moves concentrate on technology licensing partnerships and captive fuel supply chain integration.
Among Gulf-based utilities, Saudi Electricity Company and Dubai Electricity and Water Authority exemplify the sovereign-anchored procurement archetype that leverages scale economies in turbine supply. Siemens AG and General Electric Company occupy positions as technology licensors whose F-class and H-class turbine portfolios are optimized for regional ambient temperature profiles. Marubeni Corporation represents the Japanese trading house model that structures project finance and equipment procurement across emerging African markets.
| Leading Market Players |
|---|
| Saudi Electricity Company |
| Eskom Holdings SOC Ltd |
| Dubai Electricity and Water Authority |
| Acwa Power Barka SAOG |
| Siemens AG |
| Electricite de France SA |
| Egyptian Electricity Holding Company |
| Marubeni Corporation |
| General Electric Company |
| Others |
Supply & Pricing Matrix
Gulf Cooperation Council utilities concentrate procurement volume for combined cycle turbines, anchoring contract-based long-term offtake structures that bundle equipment supply with multi-year service agreements. Saudi Electricity Company and Emirates Water and Electricity Company leverage scale economies to negotiate heat-rate performance guarantees that override unit capital cost in supplier selection.
Pricing Analysis
Heat-rate efficiency guarantees anchor value-based pricing for H-class and F-class turbines in Saudi Arabia and the UAE. Three-tier pricing structure across premium, standard, and economy levels separates sequential combustion architectures with advanced blade cooling from refurbished F-class units and aging open-cycle peakers. Cost compression in the standard tier is intensifying because European and Japanese OEMs extend lead times for hot gas path components to twenty-four months. Independent power producers in Morocco and Jordan exhibit highest price sensitivity due to compressed power purchase agreement tenors, while sovereign-backed utilities in the Gulf states prioritize performance specifications over unit cost.
Supply Chain Analysis
Dual-sourcing qualification requirements for critical rotating components compel turbine OEMs to maintain qualified foundry relationships across Germany, Japan, and the United States. Blade casting capacity draws from specialized superalloy suppliers in these jurisdictions, with nickel-based alloys and thermal barrier coatings constituting primary material dependencies. Single-source vulnerability concentrates in H-class hot gas path manufacturing where European and Japanese producers control precision casting capabilities. Distribution runs through EPC contractor-led project consortiums that bundle engineering, procurement, and construction with long-term service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where emissions compliance deadlines and efficiency mandates force sub-scale operators into asset sales or early retirement. Saudi Arabia's Energy Efficiency Center benchmarking requirements compress timelines for fleet upgrades, eliminating weaker players lacking capital reserves for combined cycle retrofits.
For Market Incumbents: Acquire stranded mid-life F-class turbine assets in Egypt's Red Sea corridor before emissions regulations force accelerated retirement. Siemens AG and General Electric Company should deepen backward integration into blade casting capacity to secure supply continuity amid twenty-four-month lead times. Certification investment in continuous emissions monitoring systems defends market position against emerging Chinese turbine vendors seeking Gulf Cooperation Council grid code approval.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in combined cycle long-term service agreements offers entry latitude for independent maintenance specialists. Morocco and Algeria gas import infrastructure expansions present the most penetrable geography for F-class turbine vendors. A component-level maintenance contract go-to-market angle fragments OEM aftermarket capture and aligns with independent power producer preferences for unbundled service arrangements.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated EPC-service specialists with captive fuel supply chain relationships. Long-term viability over the next decade hinges on carbon capture retrofit readiness positioning for blue hydrogen export certification. Watch for Saudi domestic gas reservation policy relaxation as the inflection signal triggering accelerated project financial close.
| Strategic Initiative | Industry Significance |
|---|---|
| Combined Cycle Capacity Buildout | Saudi Electricity Company specifications for 60°C ambient operation concentrate procurement toward H-class sequential combustion architectures. |
| Long-term Power Purchase Agreement | Fifteen-year debt tenors in Morocco and Jordan shift residual value exposure onto EPC contractors and OEM balance sheets. |
| Technology Licensing Partnership | Siemens AG and General Electric Company optimize F-class and H-class turbine portfolios for Middle Eastern ambient temperature profiles. |
| Backward Integration into Casting | European and Japanese OEMs secure H-class blade supply continuity against twenty-four-month lead time constraints. |
| Carbon Capture Retrofit Readiness | UAE utilities position for future blue hydrogen export certification through post-combustion solvent system preparation. |
Research Methodology
Multi-period observation of turbine procurement volumes, heat-rate efficiency benchmarks, and emissions compliance deadlines anchored the trend analysis, supplemented by interviews with utility planning officers, independent power producer project developers, EPC contractors, and fuel supply specialists. Primary fieldwork combined with secondary validation from EIA data, IEA reports, FERC filings, and regional project development databases. Bottom-up unit economics modeling triangulated against top-down market sizing across fuel source, generation capacity tier, and regional grid type segmentation.
Segment-weighting approaches applied differential growth assumptions to combined cycle versus open-cycle deployments, with natural gas-fired capacity receiving higher weighting coefficients than coal-fired generation across the projection horizon. Modeled dimensions encompassed fuel source, turbine technology class, project ownership structure, and regulatory framework cluster. CAGRs derived from unit placement forecasts and average contract values, incorporating Saudi Energy Efficiency Center mandate timelines and Gulf Cooperation Council grid interconnection expansion schedules as industry-specific inputs.
Inputs from utility procurement databases and EPC contractor backlogs were available through the study window; gaps in proprietary long-term service agreement pricing introduce uncertainty bands around aftermarket revenue projections. Forecasts reflect documented assumptions regarding domestic gas allocation policies and emissions threshold trajectories. Deviation in Saudi Arabia's feedstock reservation priorities or European Union carbon border adjustment implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Thermal Energy Storage
Molten Salt Thermal Energy Storage (TES) Market
Thermal Energy Storage
Thermal Recovery Market
Thermal Energy Storage
Asia-Pacific Thermal Energy Storage Market
Thermal Energy Storage
North America Thermal Energy Storage Market
Thermal Energy Storage
China Thermal Power Plant Market
Thermal Energy Storage
Russia Thermal Power Market
Thermal Energy Storage
Africa Thermal Energy Storage Market
Thermal Energy Storage
Ice Thermal Storage Systems Market
Thermal Energy Storage
Europe District Heating Market
Thermal Energy Storage
Thermal Energy Storage (TES) Market
Thermal Energy Storage
Southeast Asia Thermal Power Market
Thermal Energy Storage
United States Thermal Power Market
Thermal Energy Storage
North America Thermal Power Market
Thermal Energy Storage
Europe Thermal Energy Storage Market
Thermal Energy Storage
Solar Thermal Fuel Market