
 North America Thermal Energy Storage Market | 2026-2036
North America Thermal Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Thermal Energy Storage Market Analytics
California is tilting the regional investment map through aggressive utility-scale storage procurement mandates and solar thermal park expansions. Trane Technologies leverages its HVAC channel density to place ice storage systems in commercial retrofits across the Sun Belt. CALMAC sustains technology leadership in phase change material integration for peak-shaving installations. Steffes Corporation anchors Midwest manufacturing of ceramic brick thermal mass units for agricultural and industrial heating applications.
Thermal energy storage captures excess thermal energy—typically from electricity, solar radiation, or industrial waste heat—in media such as molten salt, chilled water, or phase change materials for later dispatch, with operating temperatures ranging from sub-zero ice slurries to over 500°C salt mixtures. The technology buffers supply-demand mismatches in power grids and building HVAC systems, reducing peak capacity requirements and enabling renewable dispatch. Molten salt systems dominate utility-scale margin pools due to their compatibility with concentrated solar power plants and long-duration discharge profiles. Ice storage systems lead commercial building penetration where time-of-use electricity rates create arbitrage value. Phase change materials represent the fastest-growing technology segment as material science advances widen operational temperature bands and reduce supercooling penalties.
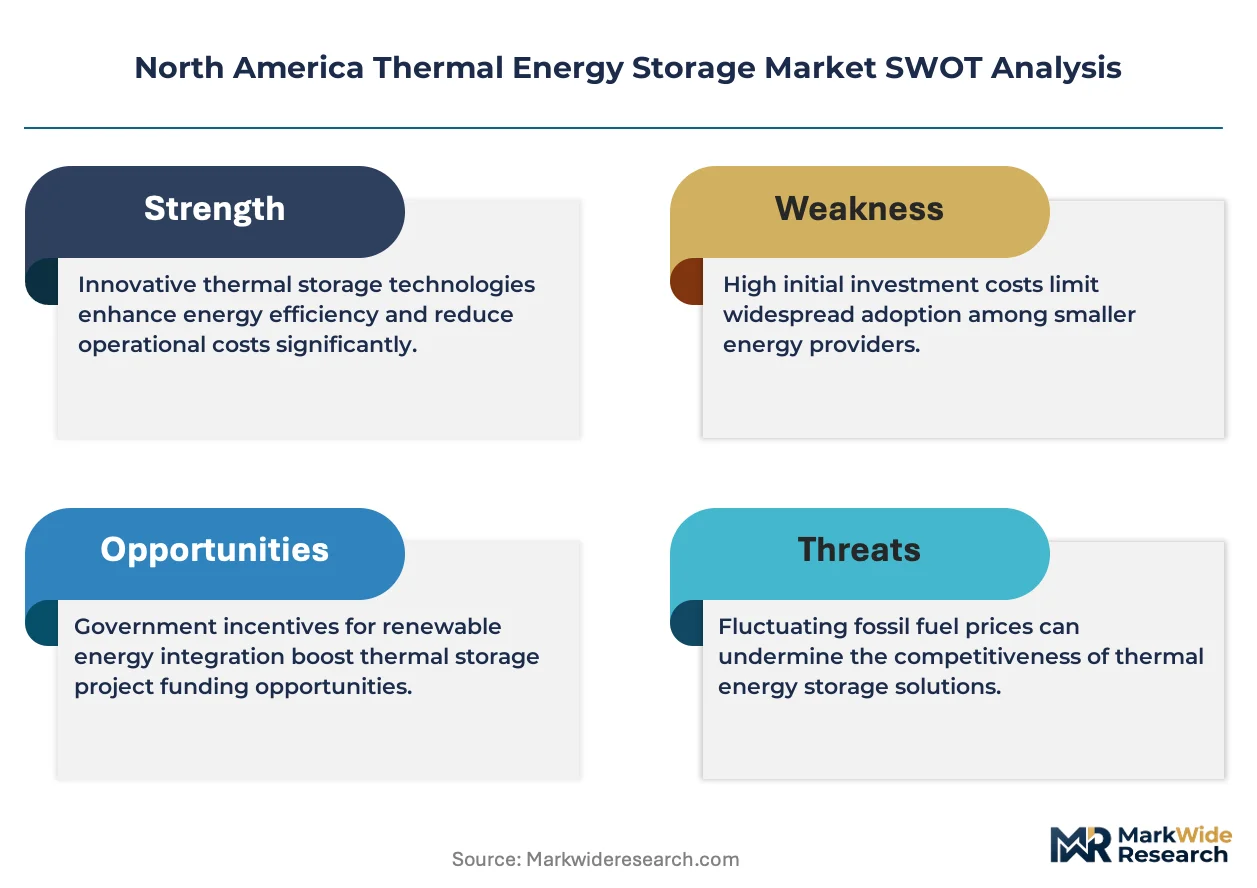
The US Federal Energy Regulatory Commission and the EPA shape market access through interconnection standards and emissions compliance pathways for thermal-to-electric systems. California's Title 24 building code and the Inflation Reduction Act storage investment tax credit directly expand addressable project volume by reducing payback periods. The Canadian Standards Association and provincial regulators in Ontario and Alberta govern grid-scale thermal storage interconnection and safety protocols. Stakeholders must track evolving state-level clean peak standards and utility integrated resource plans to anticipate procurement waves and technology qualification windows.
Market Dynamics
The Inflation Reduction Act's storage investment tax credit compresses project payback periods and redirects capital flows toward molten salt and ice-based thermal systems across the United States and Canada.
Growth Catalysts
- California Title 24 Mandates:The state's building code requires thermal energy storage in large commercial new construction and major retrofits, creating guaranteed procurement volume for ice and chilled water systems.
- Utility-Scale Solar Pairing:Texas and California grid operators require thermal buffering for concentrated solar power plants to manage evening ramp events and satisfy resource adequacy requirements.
- Phase Change Material Advances:Research institutions in Ontario and Alberta are widening operational temperature bands for salt hydrate and paraffin composites, reducing supercooling penalties in district heating networks.
Market Restraints
- Supply Concentration in Molten Salt:Nitrate salt precursor production clusters in Chile and the Middle East, exposing North American project developers to shipping cost volatility and geopolitical supply interruptions.
- High Capital Intensity:Utility-scale molten salt systems require substantial upfront investment in insulated tank farms and heat exchangers, limiting deployment to large institutional buyers with balance sheet capacity.
- Permitting Complexity:The US EPA's New Source Review process and state-level environmental impact assessments extend development timelines for thermal-to-electric installations by 18-36 months.
Strategic Opportunities
- Data Center Thermal Recovery:Hyperscale facilities in Northern Virginia and Phoenix are piloting waste heat capture into district heating loops, creating new demand for ceramic brick and concrete thermal mass units.
- Canadian Cold Climate Arbitrage:Alberta's deregulated power market and extreme winter heating loads create favorable economics for seasonal thermal storage in borehole fields and aquifer systems.
- Agricultural Process Heat:Greenhouse operators in Michigan and Ontario are adopting distributed molten salt buffers to displace propane-fired heating during peak electricity pricing windows.
Industry Challenges
- Specialized Welding and Metallurgy Skills:High-temperature salt containment systems require certified welders proficient in nickel alloy fabrication, a labor pool concentrated in Gulf Coast petrochemical corridors.
- Legacy HVAC Integration:Building automation systems in existing commercial stock often lack control protocols compatible with ice storage dispatch algorithms, forcing costly controller upgrades.
- Material Compatibility Testing:Novel phase change formulations require extended thermal cycling validation under CSA and UL protocols, stretching product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Thermal Energy Storage Market |
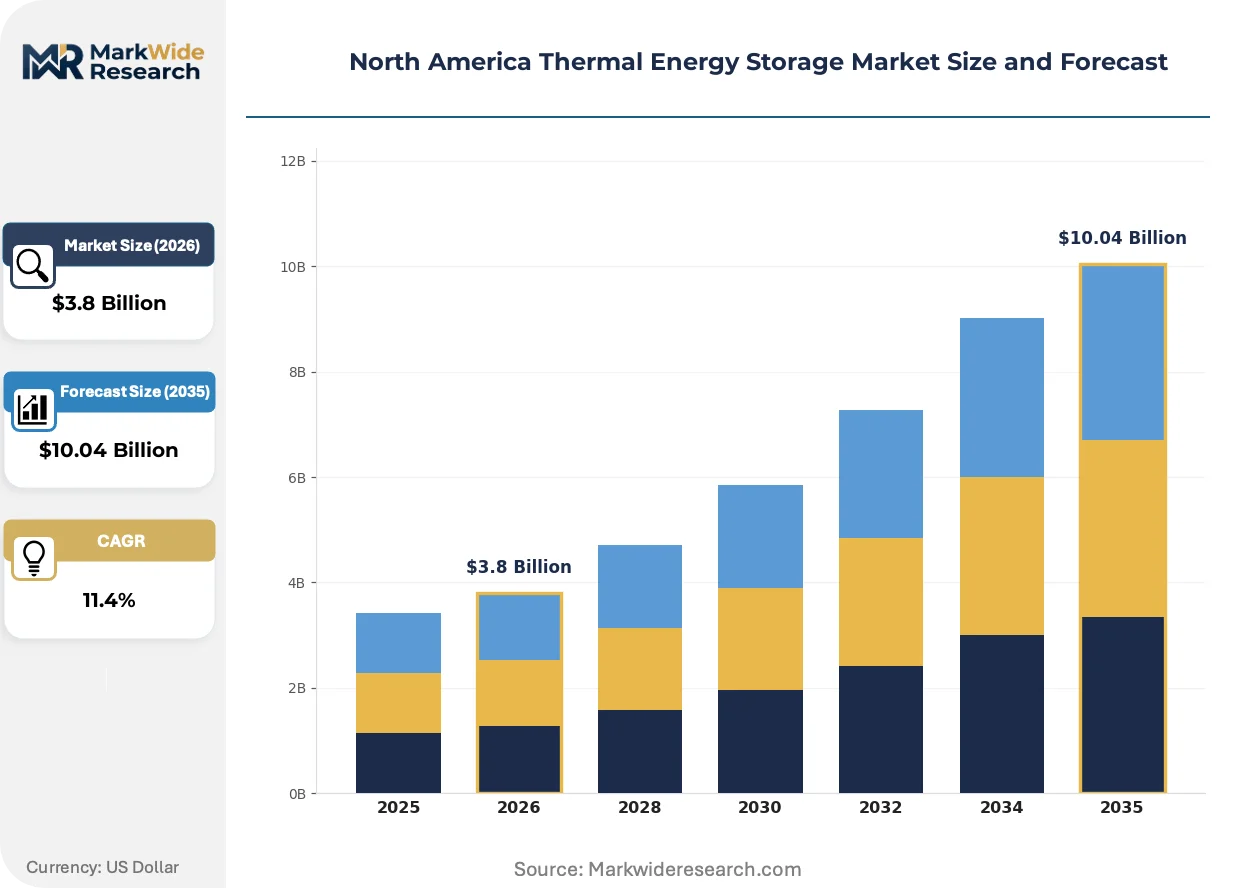
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Thermal Energy Storage Tanks, Phase Change Materials, Molten Salt Systems, Ice Storage Systems End User: Commercial Buildings, Industrial Facilities, Utility Providers, District Heating Systems Application: Load Shifting, Demand Charge Reduction, Renewable Integration, Backup Power Delivery Mode: Onsite Storage, Centralized Systems, Distributed Systems, Mobile Solutions |
| Companies Covered | Steffes Corporation, Caldwell Energy Company, CALMAC, BrightSource Energy, Abengoa, Baltimore Aircoil Company, Terrafore Technologies, EVAPCO, Trane Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Thermal Energy Storage Market Evolving Landscape
Digital twin technology and advanced material science are compressing system design cycles while expanding the addressable temperature range for thermal storage media across North American power and building markets.
Phase change material research is virtualizing the traditional tradeoff between energy density and thermal conductivity. Salt hydrate composites with graphene additives achieve fourfold improvement in heat transfer rates compared to conventional paraffin waxes. Industrial process heat buyers in Texas petrochemical corridors are piloting these formulations for 200-300°C buffering applications. The technology is virtualizing the historical dominance of molten salts in this temperature band by reducing containment costs and eliminating freeze-thaw cycling damage.
The US Inflation Reduction Act's standalone storage credit removes the prior requirement for solar co-location, enabling pure thermal storage projects to qualify for 30% investment tax credits. The FERC's Order 2222 implementation is forcing regional transmission organizations to establish participation models for distributed thermal assets in wholesale markets. Texas ERCOT and California CAISO are most affected, with both grid operators issuing technical requirements for ice storage aggregation in demand response programs.
Energy-as-a-service contracting is displacing traditional equipment ownership in commercial building retrofits. Third-party thermal storage providers in the Sun Belt assume capital risk and capture arbitrage value through utility incentive programs. Johnson Controls and Trane channel partners are most disrupted, as this model severs their historical equipment-plus-installation revenue streams. Southern California and Arizona utilities are the geography where this shift is most visible, driven by aggressive time-of-use rate restructuring.
North America Thermal Energy Storage Market Segmentation
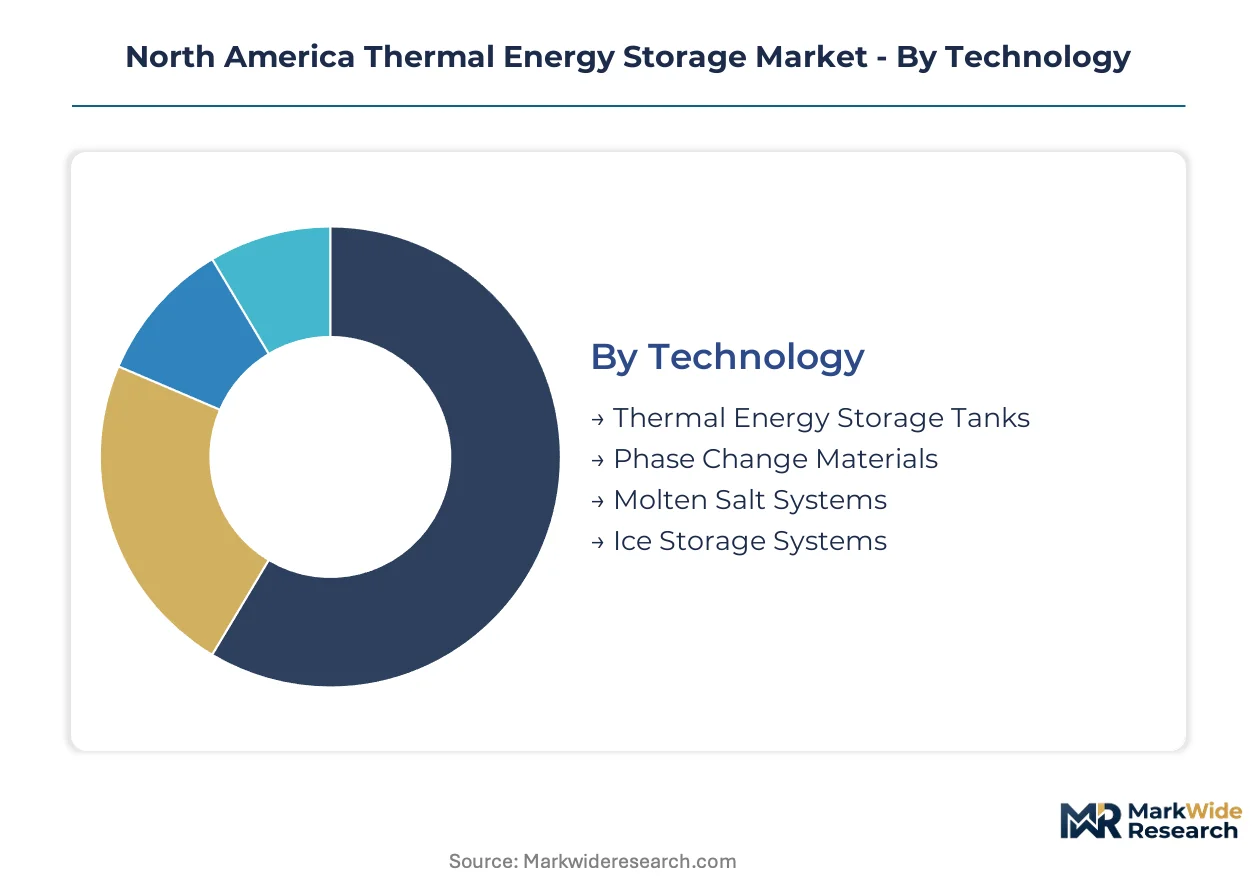
Thermal energy storage deployments fragment across four distinct dimensions that determine equipment specifications, project economics, and procurement channels. Technology selection drives containment costs and operating temperature ranges. End-user scale dictates whether systems integrate at building level or grid scale. Application purpose shapes dispatch algorithms and revenue stacking strategies. Delivery mode determines ownership structures and regulatory pathways.
Technology:
Mature molten salt installations anchor utility-scale deployment pipelines while emerging phase change formulations compress payback periods in commercial segments.
- Molten Salt Systems:Nitrate salt mixtures operate above 500°C, storing heat in insulated tank farms for concentrated solar power plants and industrial process applications. California and Texas utility-scale solar developers dominate procurement, driven by evening ramp management mandates and the Inflation Reduction Act's standalone storage credit eligibility.
- Phase Change Materials:Salt hydrate and paraffin composites absorb and release latent heat at constant temperature, enabling compact footprints in building retrofits. Ontario and Alberta research institutions are widening operational temperature bands for district heating networks, reducing supercooling penalties that historically degraded cycle efficiency.
- Ice Storage Systems:Chilled water and ice slurry systems exploit time-of-use electricity arbitrage in commercial HVAC applications across California's Title 24 compliance market.
- Thermal Energy Storage Tanks:Chilled water and hot water stratified tanks serve large campus and district heating installations where volume cost tradeoffs favor sensible heat over phase change media.
Molten salt systems handle the majority of throughput; phase change materials are gaining share fastest as material science advances reduce containment costs.
End User:
Customer scale separates project finance structures, with utility procurement enabling long-duration discharge profiles that building-level installations cannot justify.
- Utility Providers:Grid-scale operators in ERCOT and CAISO procure thermal buffering for renewable integration and resource adequacy compliance. Texas concentrated solar power corridors and California solar thermal parks concentrate deployment, with FERC Order 2222 implementation forcing wholesale market participation models for distributed thermal assets.
- Commercial Buildings:Office and retail properties in California and Arizona deploy ice storage for demand charge reduction under aggressive time-of-use rate restructuring. Southern California utilities drive this segment through incentive programs that third-party energy-as-a-service providers exploit.
- Industrial Facilities:Petrochemical corridors in Texas pilot 200-300°C phase change buffers for process heat applications, displacing fossil-fired thermal sources.
- District Heating Systems:Great Lakes networks expand procurement of seasonal storage in borehole fields and aquifer systems, with Alberta's deregulated power market creating favorable economics for cold climate arbitrage.
Utility providers command the largest project sizes; commercial buildings are expanding most quickly as Title 24 mandates harden procurement volume.
Application:
Revenue stacking complexity varies by use case, with single-purpose backup power installations yielding simpler permitting than multi-value stream renewable integration projects.
- Renewable Integration:Thermal buffering manages intermittency for utility-scale solar and wind, concentrating in California and Texas where resource adequacy requirements mandate dispatchable capacity. The EPA's New Source Review process extends development timelines for thermal-to-electric installations.
- Load Shifting:Time-of-use arbitrage drives ice storage deployment in commercial buildings across the Sun Belt, with Arizona and Nevada utilities restructuring rates to favor thermal storage dispatch.
- Demand Charge Reduction:Peak shaving applications concentrate in California commercial retrofits where Title 24 compliance creates guaranteed procurement volume.
- Backup Power:Critical facility resilience applications remain niche, limited by thermal-to-electric conversion efficiency penalties versus electrochemical alternatives.
Renewable integration absorbs the greatest capital deployment; load shifting is climbing the fastest as rate restructuring spreads beyond California.
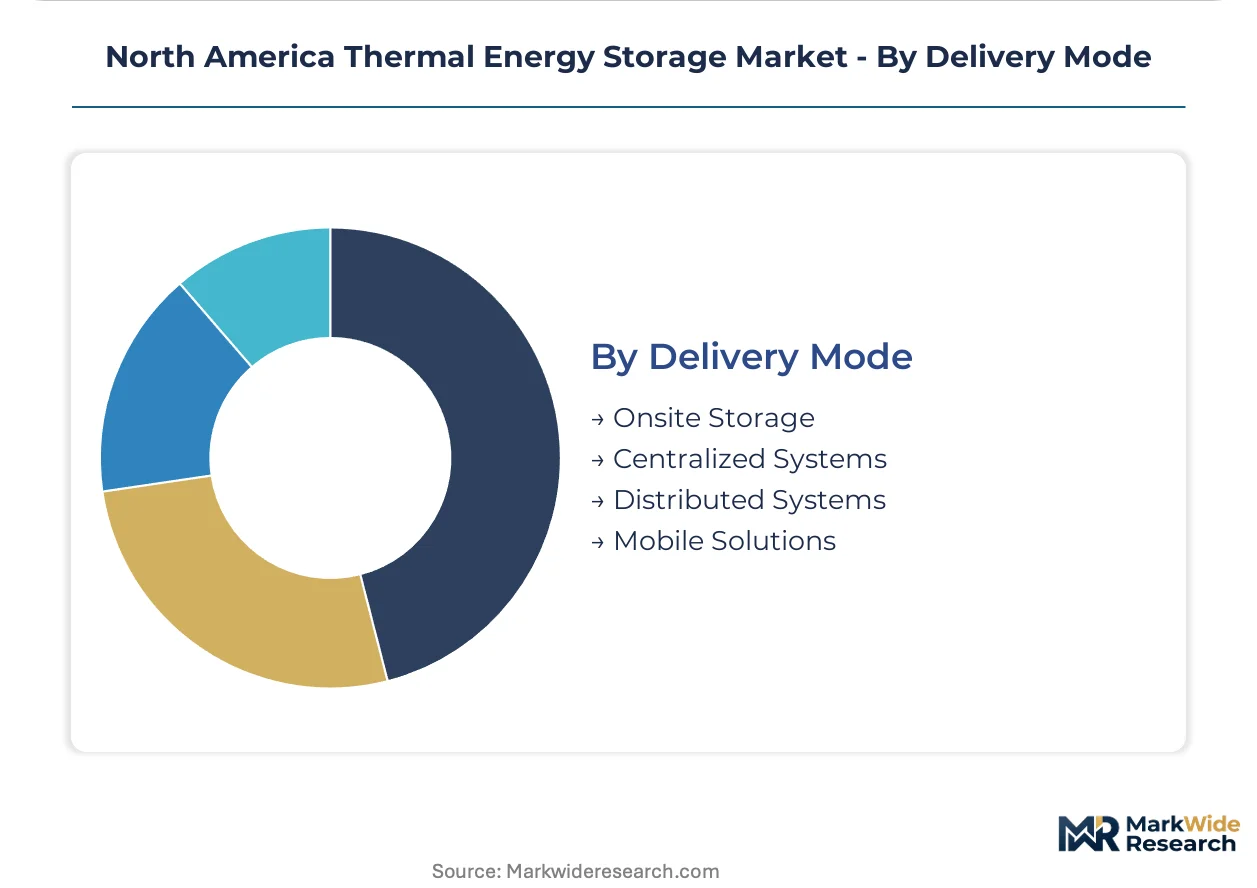
Delivery Mode:
Ownership and operational control models diverge sharply between capital-intensive centralized installations and distributed assets aggregated through demand response programs.
- Centralized Systems:Utility-owned molten salt tank farms and district heating seasonal storage require institutional balance sheet capacity and extended development timelines. Canadian provincial regulators in Ontario and Alberta govern interconnection and safety protocols for these installations.
- Distributed Systems:Building-level ice storage and phase change units aggregate into virtual power plants through CAISO and ERCOT demand response programs, with technical requirements for ice storage aggregation now formalized.
- Onsite Storage:Captive industrial installations in Texas petrochemical corridors and Michigan agricultural processing facilities bypass wholesale market participation complexity.
- Mobile Solutions:Containerized thermal storage for temporary industrial heating and emergency response remains experimental, constrained by transportation logistics and heat loss during transit.
Centralized systems dominate capital flows; distributed systems are expanding most quickly as FERC Order 2222 implementation forces regional transmission organization participation models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes thermal energy storage through utility-scale molten salt systems paired with concentrated solar plants, while Canada deploys seasonal borehole storage for district heating arbitrage against deregulated power markets. Mexico remains nascent, with limited procurement concentrated near northern industrial corridors.
United States
California's Title 24 building code mandates thermal storage in commercial new construction, compressing payback periods for ice storage retrofits across Los Angeles and San Diego metro areas. The FERC's Order 2222 implementation forces CAISO and ERCOT to establish participation models for distributed thermal assets in wholesale markets. Texas concentrated solar power corridors anchor molten salt deployment, with evening ramp management requirements driving procurement in West Texas and the Permian Basin.
Canada
Ontario's district heating networks in Toronto and Ottawa are expanding seasonal thermal storage in aquifer systems to buffer against winter peak pricing. The Canadian Standards Association governs grid-scale interconnection protocols, with provincial regulators in Alberta and Ontario issuing safety standards for high-temperature salt containment. Alberta's deregulated power market creates arbitrage economics for borehole thermal storage in Calgary and Edmonton, where extreme cold climate loads justify capital-intensive seasonal buffering.
Mexico
Northern border states including Nuevo León and Baja California pilot industrial process heat storage for maquiladora facilities seeking to displace natural gas during CENACE peak pricing windows. The country's national energy regulator establishes interconnection standards for thermal-to-electric systems, though implementation lags US and Canadian frameworks. Monterrey's industrial corridor concentrates early deployment of chilled water storage for commercial cooling arbitrage against CFE time-of-use rates.
Great Lakes Region
Michigan and Ohio agricultural processors adopt distributed molten salt buffers to displace propane-fired heating during peak electricity pricing windows. State-level clean peak standards in Illinois and Minnesota redirect utility procurement toward thermal storage for renewable integration. Chicago's district heating network and Detroit's industrial corridors anchor regional demand for ceramic brick thermal mass units manufactured in the Upper Midwest.
North America Thermal Energy Storage Market Competitive Landscape
Capability concentration sits with specialized material science developers; scale advantage sits with diversified HVAC conglomerates with existing channel density. The vendor base stratifies across three tiers: utility-scale molten salt integrators, commercial ice storage specialists, and phase change material innovators. Dominant competitive moves include strategic partnerships with research institutions for material qualification and geographic expansion through utility incentive program capture.
Within the specialized technology tier, CALMAC and Steffes Corporation exemplify divergent archetypes—CALMAC anchors phase change material integration for peak-shaving installations, while Steffes Corporation represents Midwest manufacturing concentration for ceramic brick thermal mass units. Trane Technologies occupies a position bridging commercial HVAC channel access with thermal storage product placement, leveraging existing service infrastructure across the Sun Belt. Baltimore Aircoil Company and EVAPCO sit within the evaporative cooling equipment segment, extending product portfolios into ice storage containment systems for California Title 24 compliance markets.
| Leading Market Players |
|---|
| Steffes Corporation |
| Caldwell Energy Company |
| CALMAC |
| BrightSource Energy |
| Abengoa |
| Baltimore Aircoil Company |
| Terrafore Technologies |
| EVAPCO |
| Trane Technologies |
| Others |
Value Network & Pricing Analysis
Chilean nitrate salt precursor production anchors upstream supply for North American molten salt systems, concentrating pricing power with Gulf Coast petrochemical converters who command long-term offtake premiums from utility-scale developers in Texas and California.
Pricing Analysis
Long-term offtake agreements dominate utility-scale procurement, with molten salt tank farm developers locking in decade-spanning contracts to secure nitrate salt volumes against spot market volatility. Price differentiation rests on containment certification tier—UL-listed versus CSA-approved systems—and geographic delivery cost to remote solar corridors. Cost compression in commercial ice storage segments is intensifying because third-party energy-as-a-service providers are disintermediating traditional HVAC channel margins. Commercial building operators in Arizona exhibit the highest price sensitivity, while Texas utility procurement teams prioritize discharge duration over unit economics.
Supply Chain Analysis
Contract manufacturing capacity for high-temperature nickel alloy containment vessels concentrates with Gulf Coast petrochemical fabricators and specialized Canadian pressure vessel shops in Alberta and Ontario. Raw material dependencies span Chilean sodium nitrate, Indonesian nickel for corrosion-resistant alloys, and domestic graphite for thermal interface components. Single-source vulnerability in South American salt precursor supply exposes project timelines to shipping route disruptions. Distribution runs through EPC contractors with established FERC interconnection experience, who bundle engineering, procurement, and construction risk for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where FERC Order 2222 interoperability mandates are forcing wholesale market participation models for aggregated distributed thermal assets, creating ecosystem lock-in opportunities for control software and dispatch algorithm providers.
For Market Incumbents: Pre-empt disintermediation by energy-as-a-service aggregators through captive financing arms that capture utility incentive arbitrage directly. Deepen backward integration into phase change material formulation to defend margin position against specialty chemical entrants. Lock in exclusive channel partnerships with California Title 24 compliance consultants before retrofit market saturation hardens. For New Entrants and Emerging Players: Establish a beachhead in Alberta's deregulated power market seasonal storage segment, where extreme cold climate loads and favorable borehole economics create penetrable white space absent dominant incumbents. Target Michigan and Ontario agricultural process heat applications, where propane displacement mandates and distributed molten salt buffer demand outstrip qualified supplier capacity. Pursue go-to-market alignment with district heating network engineering firms rather than direct utility sales cycles. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated phase change material innovators with captive R&D pipelines and CSA/UL qualification progress, as material science advances are concentrating competitive moats in formulation IP rather than manufacturing scale. The long-term viability window favors asset-light control software platforms over capital-intensive tank farm ownership. Watch for FERC Order 2222 implementation velocity across ERCOT and CAISO as the signal indicating when distributed aggregation economics will inflect.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing | Phase change material patents from Ontario research institutions unlock commercial temperature band expansion. |
| Long-term Supply Agreement | Chilean nitrate salt offtake contracts secure feedstock for California and Texas utility pipelines. |
| Capacity Buildout | Gulf Coast nickel alloy fabrication expansion addresses certified welder scarcity for high-temperature containment. |
| Power Purchase Agreement | ERCOT and CAISO demand response program enrollment creates recurring revenue streams for ice storage aggregators. |
| Vertical Integration into Storage | Captive phase change formulation production compresses payback periods for commercial building retrofits. |
Research Methodology
The analysis maps molten salt utility-scale, ice storage commercial, phase change material distributed, and seasonal borehole district heating segments, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators across primary interviews combined with secondary triangulation against EIA data, FERC filings, IEA reports, and project development databases. Bottom-up equipment shipment tracking and top-down regulatory mandate sizing were cross-referenced to anchor volume estimates.
Assumptions around IRA tax credit continuity, FERC Order 2222 implementation timelines, and California Title 24 enforcement stringency were held fixed across baseline scenarios while stress-tested against regulatory repeal and interconnection delay variants. Segmentation dimensions modeled include technology type, end-user scale, application purpose, and delivery mode. CAGRs were derived from installed capacity buildout curves and technology-specific cost learning rates applied across the projection horizon.
Stress conditions across IRA credit phase-out schedules, nitrate salt supply disruptions, and FERC interconnection queue reform were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory, technological, or commodity price shifts. Quarterly review of FERC docket filings, CAISO and ERCOT demand response program enrollment data, and Chilean nitrate export volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Thermal Energy Storage
Molten Salt Thermal Energy Storage (TES) Market
Thermal Energy Storage
China Thermal Power Plant Market
Thermal Energy Storage
Russia Thermal Power Market
Thermal Energy Storage
Africa Thermal Energy Storage Market
Thermal Energy Storage
Southeast Asia Thermal Power Market
Thermal Energy Storage
Middle-East and Africa Thermal Power Market
Thermal Energy Storage
United States Thermal Power Market
Thermal Energy Storage
Solar Thermal Fuel Market
Thermal Energy Storage
Europe District Heating Market
Thermal Energy Storage
Ice Thermal Storage Systems Market
Thermal Energy Storage
Europe Thermal Energy Storage Market
Thermal Energy Storage
North America Thermal Power Market
Thermal Energy Storage
Asia-Pacific Thermal Energy Storage Market
Thermal Energy Storage
Thermal Energy Storage (TES) Market
Thermal Energy Storage
Thermal Recovery Market