
 China Thermal Power Plant Market | 2026-2036
China Thermal Power Plant Market Size, Share, and Industry Trends Forecast 2026-2036
China Thermal Power Plant Market Outlook
Ultra-supercritical alloys is consolidating around nickel-based superalloy forgings that withstand steam temperatures above 600°C, cutting coal consumption per kilowatt-hour. China Energy Investment Group leverages captive mining-to-generation integration across Inner Mongolia. Huaneng Power International sustains ultra-supercritical technology leadership through dedicated R&D centers in Beijing. Datang International Power Generation Company anchors coastal gas turbine portfolios in Jiangsu and Zhejiang provinces.
China thermal power plants convert chemical energy from fossil or biomass fuels into electrical energy through steam or gas turbine cycles, with modern ultra-supercritical units achieving thermal efficiencies near 47% at 31 MPa pressure. Steam turbine equipment dominates capital expenditure for new coal installations, though gas turbine segments attract faster growth from distributed energy policies. Retrofit installations command premium margins as existing operators face MEE emission deadlines without greenfield permitting. Utility companies represent the largest end-user category, while independent power producers gain share through provincial electricity market reforms.
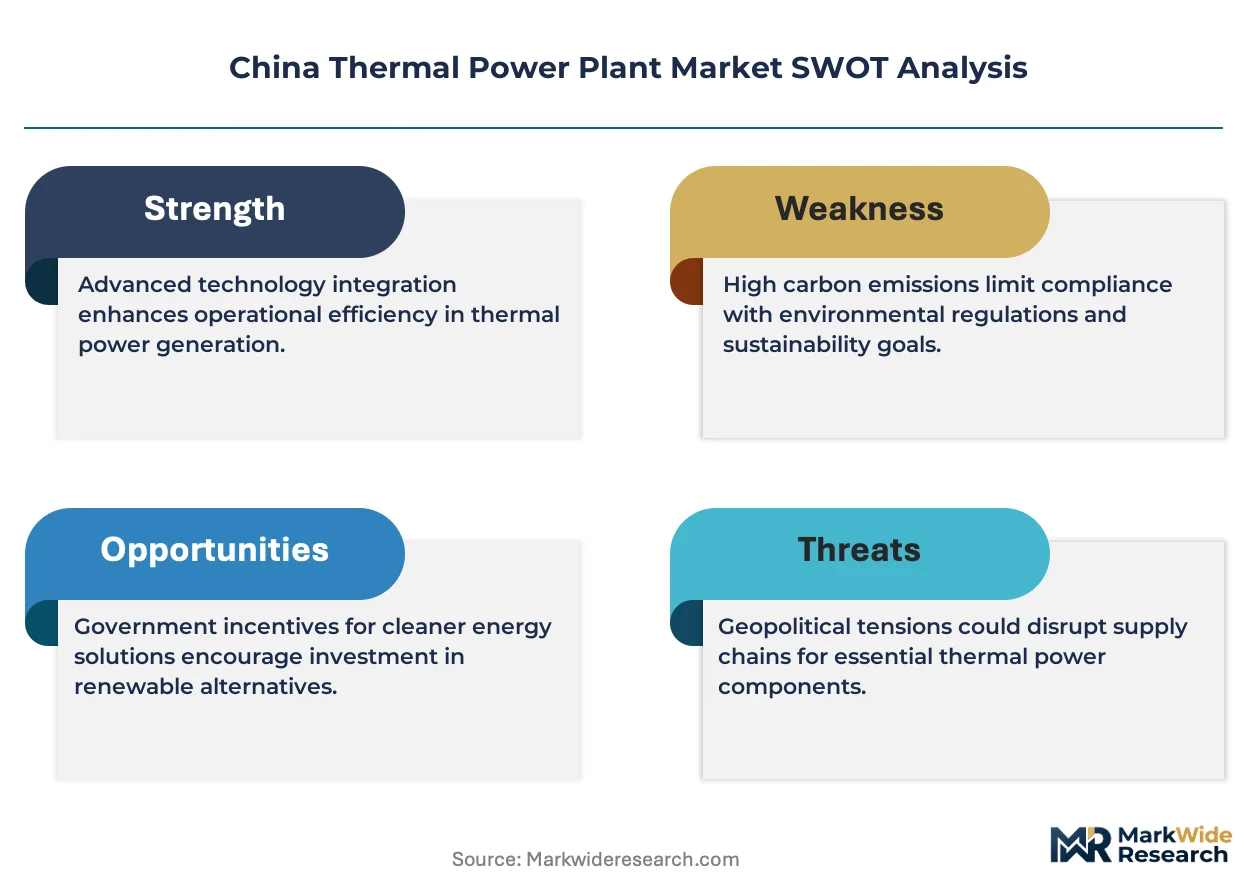
MEE emission standards, GB 13223 thermal power air pollutant limits, and National Energy Administration capacity replacement rules collectively mandate efficiency thresholds and emission caps that filter market access. MIIT equipment certification requirements further constrain turbine and boiler supplier qualification. Stakeholders must weigh retrofit economics against decommissioning timelines as carbon intensity benchmarks tighten across eastern provinces.
Market Dynamics
Ultra-supercritical steam technology is electrifying capacity planning across eastern provinces, as operators face MEE emission deadlines that render subcritical units economically unviable without substantial retrofit investment.
Growth Catalysts
- MEE Emission Mandates:GB 13223 thermal power air pollutant limits force efficiency upgrades, creating replacement demand for ultra-supercritical boiler and turbine systems in coastal provinces.
- Yangtze River Delta Industrial Load:Manufacturing clusters in Jiangsu and Zhejiang require baseload expansion, driving coal-fired capacity additions with advanced steam parameters.
- Guangdong Grid Stability Requirements:Peak shaving obligations favor gas turbine installations, accelerating distributed energy deployment across the Pearl River Delta.
Market Restraints
- Nickel Superalloy Supply Concentration:Forged turbine blades depend on concentrated specialty alloy suppliers, exposing project timelines to raw material bottlenecks.
- Greenfield Permitting Friction:National Energy Administration capacity replacement rules constrain new coal plant approvals, limiting expansion to retrofit and replacement cycles.
- Renewable Substitution Pressure:Wind and solar capacity additions in Inner Mongolia and Gansu displace thermal dispatch priority, compressing capacity factor economics.
Strategic Opportunities
- Retrofit Service Contracts:Existing subcritical operators in Shandong and Henan face MEE deadlines without decommissioning timelines, creating premium-margin upgrade opportunities.
- Gas Turbine Peaker Deployment:Provincial electricity market reforms enable independent power producers to capture scarcity pricing through fast-ramp installations.
- Biomass Co-firing Integration:Carbon intensity benchmarks in eastern provinces incentivize fuel blending retrofits, opening boiler modification revenue streams.
Industry Challenges
- Welding Technician Scarcity:Ultra-supercritical fabrication demands specialized ASME-certified welders, with training pipelines failing to match project backlogs.
- Legacy Control System Integration:Digital turbine governors must interface with 1990s-era distributed control systems, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Thermal Power Plant Market |
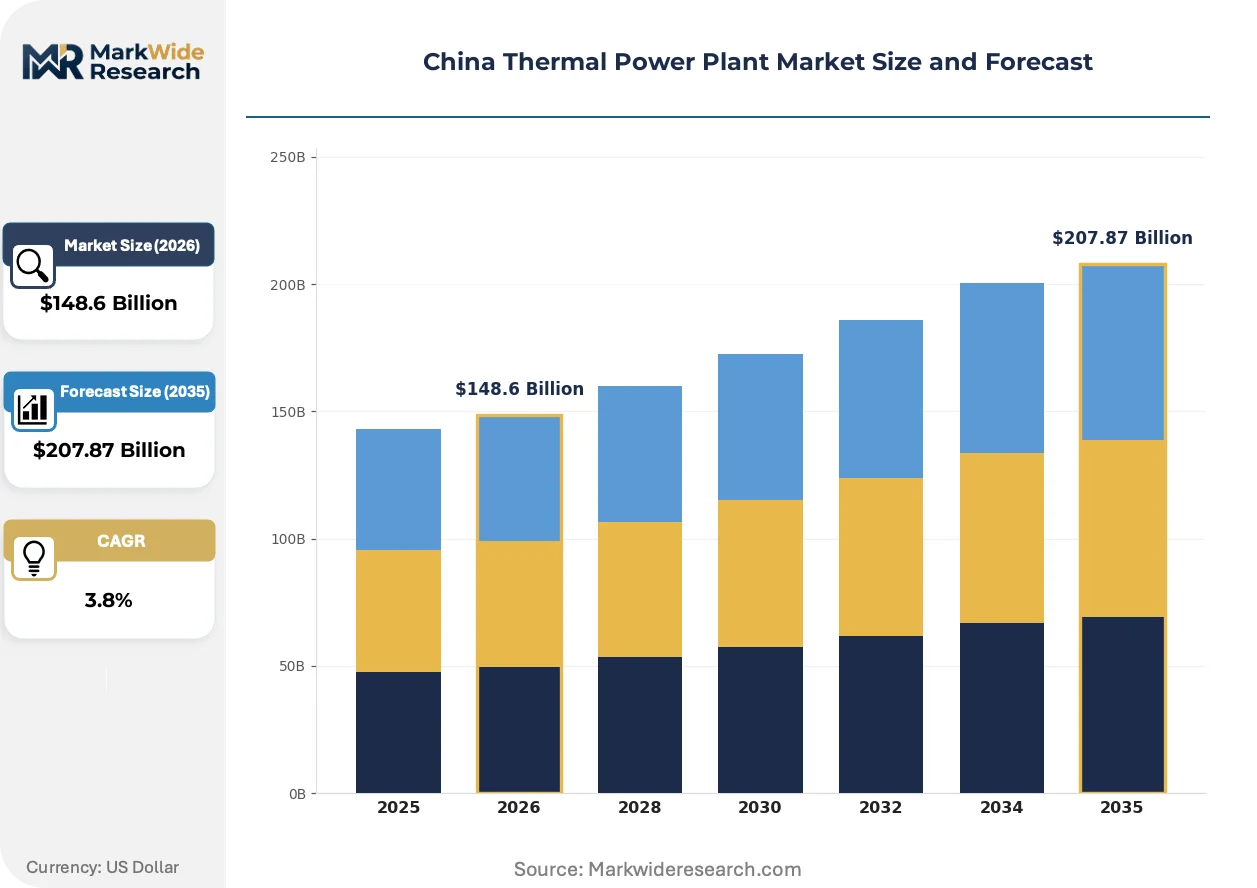
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $207.87 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Turbine, Gas Turbine, Boiler, Generator Installation Type: New, Retrofit, Upgrade, Expansion Fuel Type: Coal, Natural Gas, Biomass, Oil End User: Utility Companies, Industrial Users, Independent Power Producers, Others |
| Companies Covered | China Energy Engineering Corporation, China Huadian Corporation, China Yangtze Power, China National Nuclear Power, Huaneng Power International, China Energy Investment Group, CGN Power, Sichuan Chuantou Energy, Datang International Power Generation Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Thermal Power Plant Market Strategic Shifts
Technology trajectories in China's thermal power sector center on efficiency maximization under tightening environmental constraints, with equipment specifications and procurement patterns undergoing parallel transformation.
Advanced nickel-based superalloy forgings are electrifying steam turbine design, enabling sustained operation above 600°C steam temperatures that push thermal efficiency toward 47%. State-owned generation groups in Beijing and Shanghai accelerate procurement of these high-grade units. The technology is compressing the economic viability window for subcritical generation assets.
MIIT equipment certification requirements now mandate third-party validation of turbine and boiler performance parameters before grid connection approval. Manufacturers must submit to extended testing protocols that extend delivery cycles. Suppliers with established Beijing certification relationships capture disproportionate share in new procurement rounds.
Independent power producers are consolidating procurement authority previously fragmented across provincial grid subsidiaries, centralizing technical specification decisions. Equipment vendors now face consolidated buyer negotiation power with standardized performance guarantees. This concentration is most visible in Guangdong and Jiangsu, where market reform pilots advanced furthest.
China Thermal Power Plant Market Segmentation
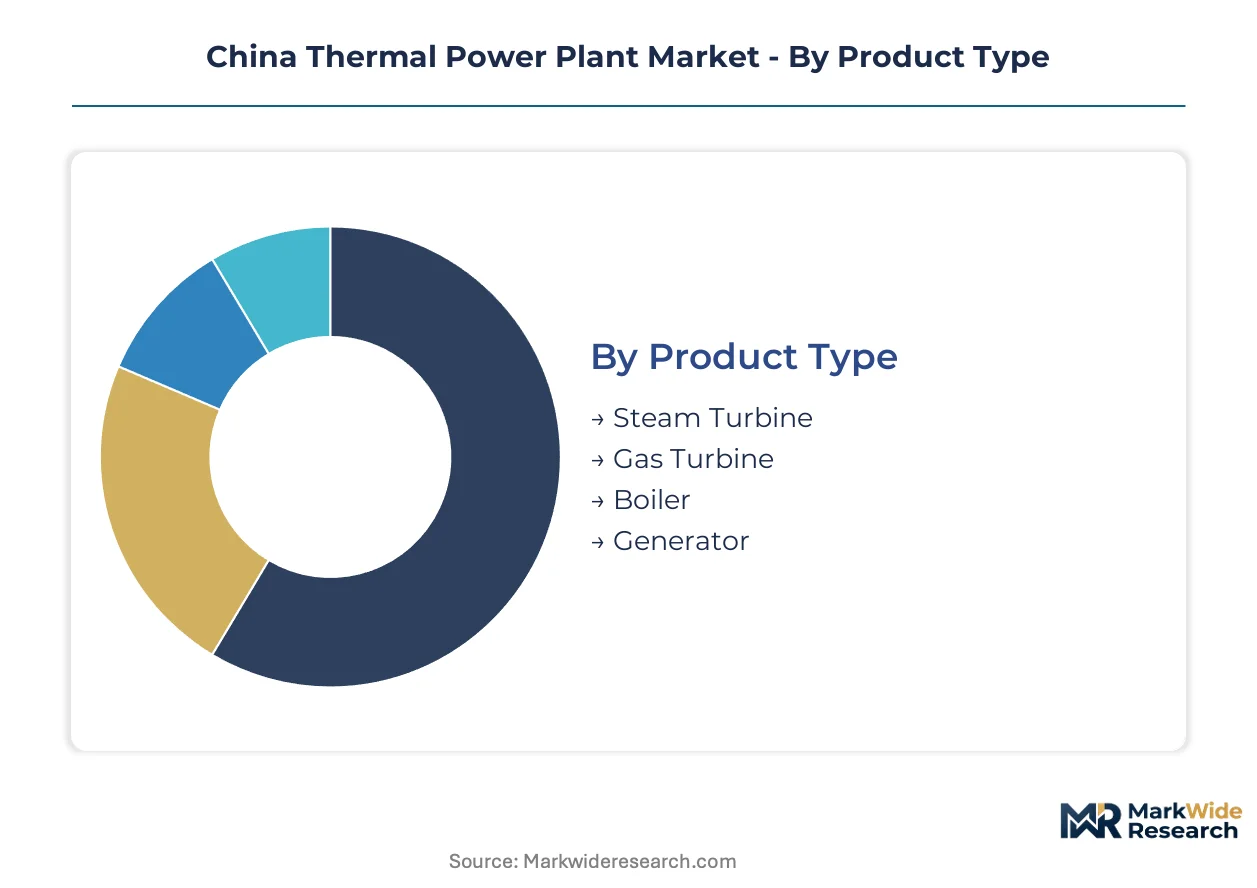
Equipment specification tiers and installation lifecycle stages segment China's thermal power market into distinct procurement channels. Each category reflects divergent capital intensity, regulatory exposure, and technology upgrade pathways under MEE emission mandates.
Product Type:
Steam turbine systems anchor capital expenditure through ultra-supercritical alloy specifications, while gas turbine segments accelerate from distributed energy policies.
- Steam Turbine:Nickel-based superalloy forgings withstand steam temperatures above 600°C, pushing thermal efficiency toward 47%. Demand concentrates in Jiangsu and Zhejiang baseload expansions where Yangtze River Delta manufacturing clusters require reliable capacity.
- Gas Turbine:Fast-ramp aeroderivative and heavy-frame units serve peak shaving obligations across Guangdong's Pearl River Delta. Grid stability requirements favor these installations where renewable intermittency creates scarcity pricing opportunities.
- Boiler:Ultra-supercritical waterwall and superheater assemblies dominate new coal procurement under GB 13223 emission limits.
- Generator:Hydrogen-cooled and air-cooled synchronous machines pair with turbine specifications in integrated power train deliveries.
Mature deployment sits with steam turbine systems. Newer deployment is concentrated in gas turbine peaker installations.
Installation Type:
Capital allocation splits between greenfield capacity and emission-driven retrofit cycles, with permitting constraints favoring existing asset modification.
- New:Greenfield construction faces National Energy Administration capacity replacement rules that limit approvals to efficiency benchmarks above 45% thermal efficiency. Inner Mongolia captive mining-to-generation integration sustains limited new coal development.
- Retrofit:Subcritical operators in Shandong and Henan face MEE deadlines without decommissioning timelines, creating premium-margin upgrade opportunities for emission control and steam parameter enhancement.
- Upgrade:Digital turbine governor integration with legacy distributed control systems extends commissioning timelines but unlocks efficiency gains.
- Expansion:Existing site capacity additions bypass greenfield permitting friction through capacity replacement mechanisms.
Retrofit and upgrade installations command margin premiums. New construction concentrates in integrated captive generation.
Fuel Type:
Carbon intensity benchmarks and fuel supply security shape procurement across coal dominance, gas acceleration, and biomass blending trials.
- Coal:Bituminous and sub-bituminous grades feed ultra-supercritical units in coastal provinces where import infrastructure and rail networks converge. Inner Mongolia and Shanxi domestic production anchors supply security for state-owned generation groups.
- Natural Gas:LNG import terminals in Guangdong and Jiangsu enable combined-cycle deployment with lower emission profiles than coal alternatives. Provincial electricity market reforms accelerate independent power producer entry.
- Biomass:Agricultural residue and forestry waste co-firing trials proceed in eastern provinces under tightening carbon accounting.
- Oil:Distillate and residual fuel oils serve remote island and emergency backup applications with limited grid connection.
Coal retains baseload dominance. Natural gas is expanding most quickly from distributed energy and peak shaving mandates.
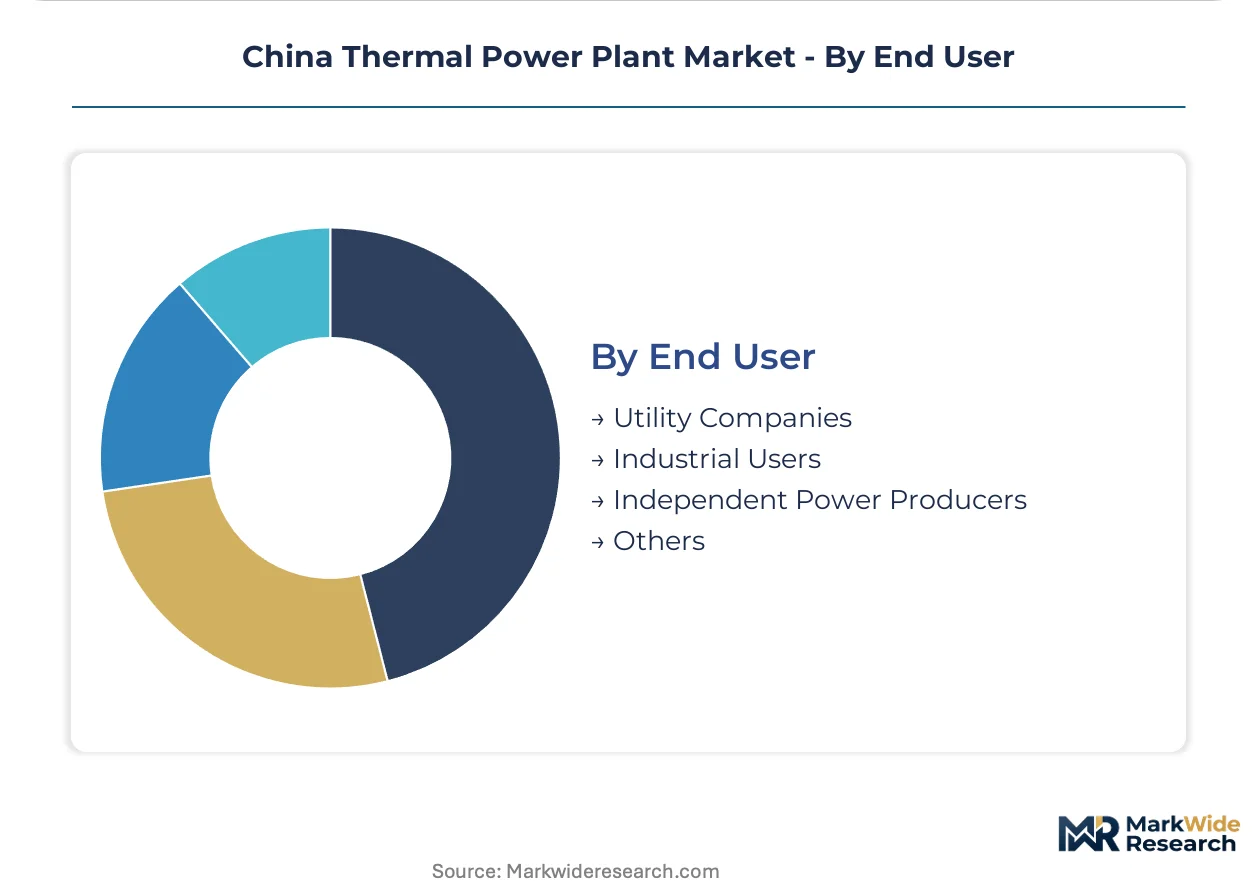
End User:
Procurement authority concentrates through market reform pilots, fragmenting previously centralized grid subsidiary purchasing.
- Utility Companies:State-owned generation groups including China Energy Investment Group and Huaneng Power International dominate capacity ownership through dedicated R&D centers and captive fuel integration.
- Industrial Users:Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang expand self-generation capacity to secure power quality and hedge grid pricing volatility.
- Independent Power Producers:Provincial electricity market reforms in Guangdong and Jiangsu enable new entrants to capture scarcity pricing through fast-ramp gas turbine deployment.
- Others:District heating utilities and captive industrial power systems serve specialized thermal load requirements.
Utility companies anchor procurement volume. Independent power producers are gaining share fastest through market reform participation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones along the eastern seaboard concentrate thermal power investment through preferential permitting and tax incentives for ultra-supercritical upgrades.
Guangdong Province
Grid stability mandates and peak shaving obligations drive gas turbine deployment across the Pearl River Delta. MEE emission standards under GB 13223 enforce strict air pollutant limits on existing coal assets. Shenzhen and Guangzhou manufacturing clusters anchor independent power producer entry through electricity market reform pilots.
Jiangsu Province
Yangtze River Delta industrial load expansion requires reliable baseload capacity with advanced steam parameters. National Energy Administration capacity replacement rules filter new approvals toward efficiency thresholds above 45%. Nanjing and Suzhou manufacturing corridors sustain utility-led ultra-supercritical procurement.
Inner Mongolia
Captive mining-to-generation integration sustains limited new coal development despite greenfield permitting friction. Dual carbon goals impose tightening carbon intensity benchmarks on existing assets. Hohhot and Ordos energy bases anchor state-owned generation group consolidation.
Zhejiang Province
Coastal manufacturing clusters demand power quality hedging through self-generation capacity expansion. MIIT equipment certification requirements extend delivery cycles for turbine and boiler systems. Hangzhou and Ningbo industrial zones concentrate retrofit service demand from subcritical operators facing MEE deadlines.
Shandong Province
Legacy subcritical fleet operators confront emission control retrofit economics without decommissioning timelines. GB 13223 thermal power air pollutant limits force efficiency upgrades on coastal installations. Qingdao and Jinan industrial corridors generate premium-margin upgrade opportunities for boiler modification and steam parameter enhancement.
China Thermal Power Plant Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with state-owned generation groups commanding integrated procurement authority while independent power producers fragment purchasing through market reform pilots. The competitive structure concentrates around three archetypes: captive fuel-integrated utilities, technology-specialized equipment vendors, and reform-enabled independent generators. Consolidation pressures intensify as MEE emission mandates compress the economic viability window for subcritical assets. Dominant competitive moves include strategic partnerships for nickel superalloy supply security and portfolio diversification into gas turbine peaker installations.
Within the state-integrated utility tier, China Energy Investment Group and Huaneng Power International exemplify archetypes of captive mining-to-generation consolidation and dedicated R&D center investment respectively. Datang International Power Generation Company occupies a position representing coastal gas turbine portfolio anchoring. These entities sit within a competitive dynamic where procurement authority centralization through provincial electricity market reforms reshapes vendor negotiation leverage.
| Leading Market Players |
|---|
| China Energy Engineering Corporation |
| China Huadian Corporation |
| China Yangtze Power |
| China National Nuclear Power |
| Huaneng Power International |
| China Energy Investment Group |
| CGN Power |
| Sichuan Chuantou Energy |
| Datang International Power Generation Company |
| Others |
Value Chain & Pricing Dynamics
GB 13223 thermal power air pollutant limits gate qualified supply access and premium-tier pricing for ultra-supercritical equipment, as MIIT certification requirements filter vendor participation and concentrate procurement authority among Beijing-validated suppliers. State-owned generation groups leverage captive fuel integration to negotiate volume discounts, while independent power producers absorb spot-market premiums for fast-track delivery.
Pricing Analysis
Short lead-time premiums of 15-25% apply to ultra-supercritical turbine forgings with delivery cycles compressed below standard 18-month windows, while spot inventory of nickel-based superalloy castings trades at discounts to long-term offtake contracts. Project-based pricing dominates greenfield installations, with cost differentiation driven by MIIT certification tier and after-sales service bundling. Cost compression in standard-grade boiler assemblies is intensifying because of renewable substitution pressure on capacity factors. Industrial users in the Yangtze River Delta exhibit highest price sensitivity due to self-generation economics, while utility companies with captive mining integration show least sensitivity.
Supply Chain Analysis
Regional distribution centers in Shanghai and Tianjin anchor hub-and-spoke patterns for turbine component logistics, with final assembly concentrated at coastal manufacturing bases. Nickel superalloy forging capacity concentrates in China, Germany, and Japan. Raw material dependencies include Indonesian nickel ore, Australian coking coal, and specialty refractory ceramics from South Korea. Single-source vulnerability in ASME-certified welding technician pools creates project timeline risk. Distribution runs through state-owned equipment trading companies with provincial grid subsidiary relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where GB 13223 emission standards create a barrier-to-entry moat for MIIT-certified equipment vendors and retrofitted operators.
For Market Incumbents: Acquire stranded subcritical asset portfolios in Shandong and Henan to capture retrofit service revenue streams before MEE deadline convergence. Consolidate nickel superalloy supply agreements with forged blade specialists to defend against raw material bottlenecks threatening project delivery. Backward integration into captive refractory manufacturing reduces exposure to South Korean ceramic supply volatility.
For New Entrants and Emerging Players: Launch via independent power producer market reform participation in Guangdong and Jiangsu, where electricity market pilots enable scarcity pricing capture through fast-ramp gas turbine deployment. Target peaker installation segments with lowest incumbent concentration and shortest certification pathways. Pursue biomass co-firing retrofit contracts in eastern provinces as the most penetrable application with favorable carbon accounting treatment.
For Investors and Strategic Acquirers: Provincial electricity market reform advancement is the leading indicator that independent power producer entry will accelerate gas turbine demand and compress utility procurement timelines. Five-to-ten year viability favors equipment vendors with established Beijing certification relationships and service contract backlogs. Watch for MIIT certification queue length as the signal of supply constraint intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultra-Supercritical Technology Licensing | Huaneng Power International leverages Beijing R&D centers to transfer 600°C steam parameter expertise to provincial operators. |
| Captive Nickel Superalloy Supply Agreement | China Energy Investment Group secures forged blade allocations from Inner Mongolia-integrated specialty metal producers. |
| Gas Turbine Peaker Deployment | Datang International anchors coastal portfolios in Jiangsu and Zhejiang to capture grid stability mandate premiums. |
| Retrofit Service Contract Consolidation | Subcritical operators in Shandong face MEE deadlines without decommissioning timelines, creating premium-margin upgrade demand. |
| Biomass Co-Firing Integration | Eastern provincial carbon intensity benchmarks incentivize agricultural residue blending retrofits for emission compliance. |
Study Parameters
Multi-period observation of capacity replacement approvals, MIIT certification queues, and provincial electricity market reform pilots anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from National Energy Administration filings, MEE emission standard bulletins, MIIT equipment certification registries, and state-owned generation group procurement disclosures. Bottom-up project pipeline aggregation and top-down capacity factor modeling enabled cross-verification of investment trajectories.
Segment-weighting applied fuel type, installation lifecycle stage, and end-user procurement authority as primary dimensions across the projection horizon. CAGRs were derived from regression-based capacity addition modeling and efficiency upgrade cycle analysis. Forecast inputs incorporated GB 13223 compliance timeline assumptions and nickel superalloy supply elasticity estimates.
Regulatory enforcement variance, raw material supply disruption, and renewable dispatch priority shifts are the dominant revision risks that could alter capacity investment patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Thermal Energy Storage
Europe Thermal Energy Storage Market
Thermal Energy Storage
Solar Thermal Fuel Market
Thermal Energy Storage
Molten Salt Thermal Energy Storage (TES) Market
Thermal Energy Storage
Thermal Energy Storage (TES) Market
Thermal Energy Storage
Ice Thermal Storage Systems Market
Thermal Energy Storage
United States Thermal Power Market
Thermal Energy Storage
Africa Thermal Energy Storage Market
Thermal Energy Storage
Middle-East and Africa Thermal Power Market
Thermal Energy Storage
Asia-Pacific Thermal Energy Storage Market
Thermal Energy Storage
Thermal Recovery Market
Thermal Energy Storage
North America Thermal Energy Storage Market
Thermal Energy Storage
Southeast Asia Thermal Power Market
Thermal Energy Storage
North America Thermal Power Market
Thermal Energy Storage
Russia Thermal Power Market
Thermal Energy Storage
Europe District Heating Market