
 Africa Thermal Energy Storage Market | 2026-2036
Africa Thermal Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Thermal Energy Storage Market Outlook
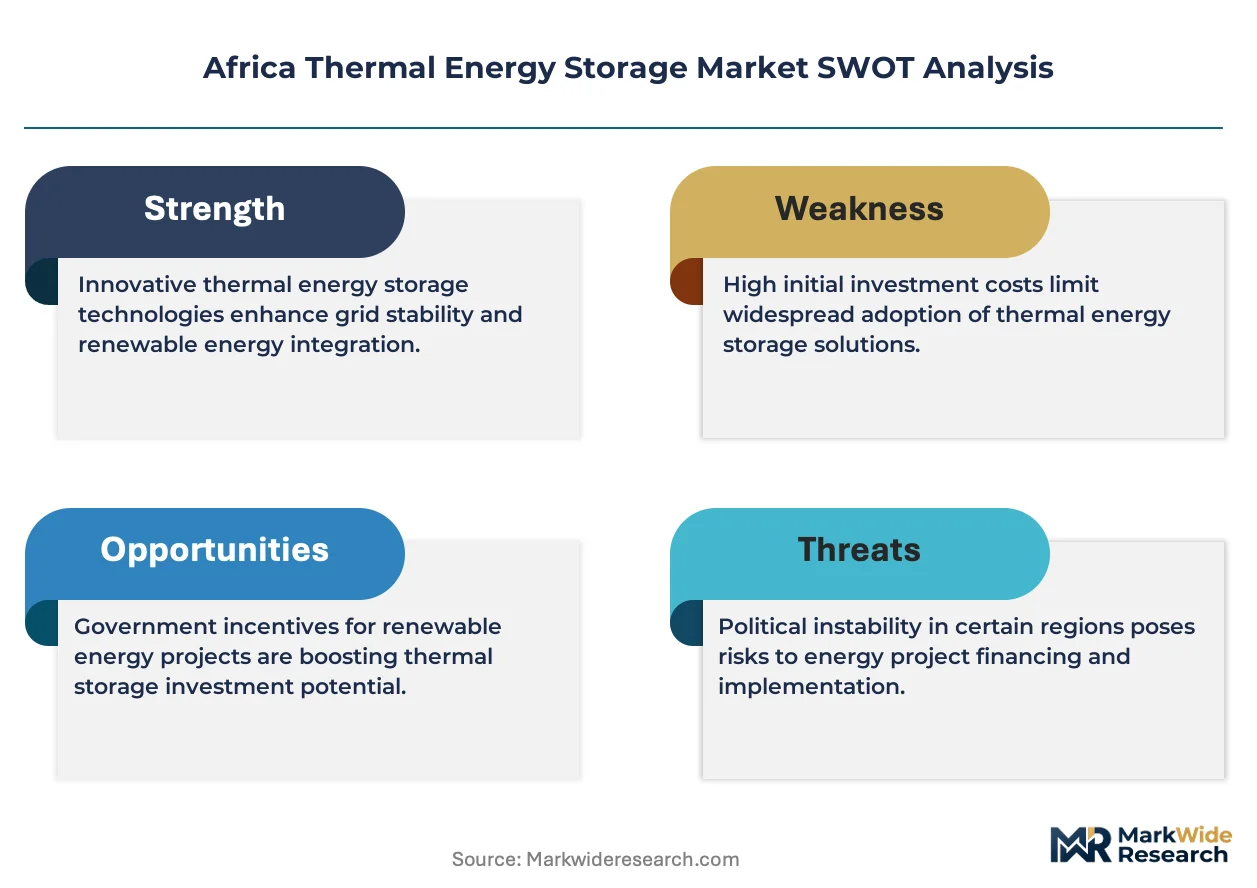
The gap between utility-scale molten salt installations and small-scale commercial ice storage is hardening across African markets. Eskom Holdings SOC Ltd leverages its grid infrastructure dominance to anchor large thermal storage procurement in South Africa. Abengoa SA sustains technology leadership through specialized concentrated solar power engineering capabilities. ACWA Power International competes aggressively on independent power producer frameworks across Morocco and South Africa.
Africa Thermal Energy Storage encompasses systems that capture thermal energy in media such as molten salt mixtures operating above 220°C, phase change materials with defined latent heat capacities, or chilled water and ice banks, then discharge that stored energy to balance electricity loads or provide process heat. Molten salt technology dominates utility-scale installations due to its proven heat retention above twelve hours, while phase change materials are gaining traction in commercial building retrofits where space constraints limit water tank volumes. District heating applications remain nascent across the continent, though load shifting for industrial off-takers commands the strongest near-term margins.
South Africa's National Energy Regulator and the country's Department of Mineral Resources and Energy shape project licensing and grid connection standards for thermal storage assets. Morocco's Moroccan Agency for Sustainable Energy and ONEE enforce technical specifications that favor molten salt configurations in Noor Ouarzazate-style developments. Stakeholders must monitor how evolving renewable energy auction designs across these jurisdictions allocate risk between storage developers and offtakers.
Market Dynamics
The divergence between South Africa's utility-scale molten salt procurement and Morocco's concentrated solar power pipeline is restructuring competitive entry requirements across the continent. Eskom's grid connection queue reforms and Morocco's ONEE technical specifications are forcing technology providers to choose between scale specialization and geographic diversification.
Growth Catalysts
- REIPPPP auction redesign:South Africa's Renewable Energy Independent Power Producer Procurement Programme now mandates storage co-location, creating guaranteed offtake channels for molten salt developers in the Northern Cape.
- Industrial load shifting:Mining sector energy arbitrage in South Africa's platinum belt is pulling commercial-scale phase change material installations as tariff structures penalize peak consumption.
- Molten salt cost curves:Nitrate salt mixture supply localization in Morocco is compressing installed costs for Noor Ouarzazate-style developments.
Market Restraints
- Input cost volatility:Lithium carbonate and nickel price swings transmit directly to phase change material formulations, squeezing project IRRs for commercial building retrofits.
- Supply concentration risk:Specialist molten salt engineering capability clusters in Spain and the United States, creating procurement bottlenecks for African independent power producers.
- Technical limitation:Heat exchanger corrosion rates in high-humidity coastal zones degrade molten salt system availability below utility contract thresholds.
Strategic Opportunities
- Underpenetrated geography:Egypt's New and Renewable Energy Authority feed-in tariff revisions open concentrated solar power corridors in the Western Desert with minimal incumbent competition.
- Technology convergence:Hybrid photovoltaic-thermal installations paired with ice storage are integrating into South African commercial retail estates seeking behind-the-meter optimization.
- Regulatory tailwind:Kenya's Energy and Petroleum Regulatory Authority net metering framework enables distributed thermal storage aggregation for industrial park microgrids.
Industry Challenges
- Certification timeline compression:South Africa's National Energy Regulator grid code compliance testing for thermal storage inverters extends project commissioning by eight to fourteen months.
- Skill scarcity in high-temperature systems:Welding and piping specialists qualified for 550°C molten salt circuits command premiums that distort EPC pricing in the Northern Cape.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Thermal Energy Storage Market |
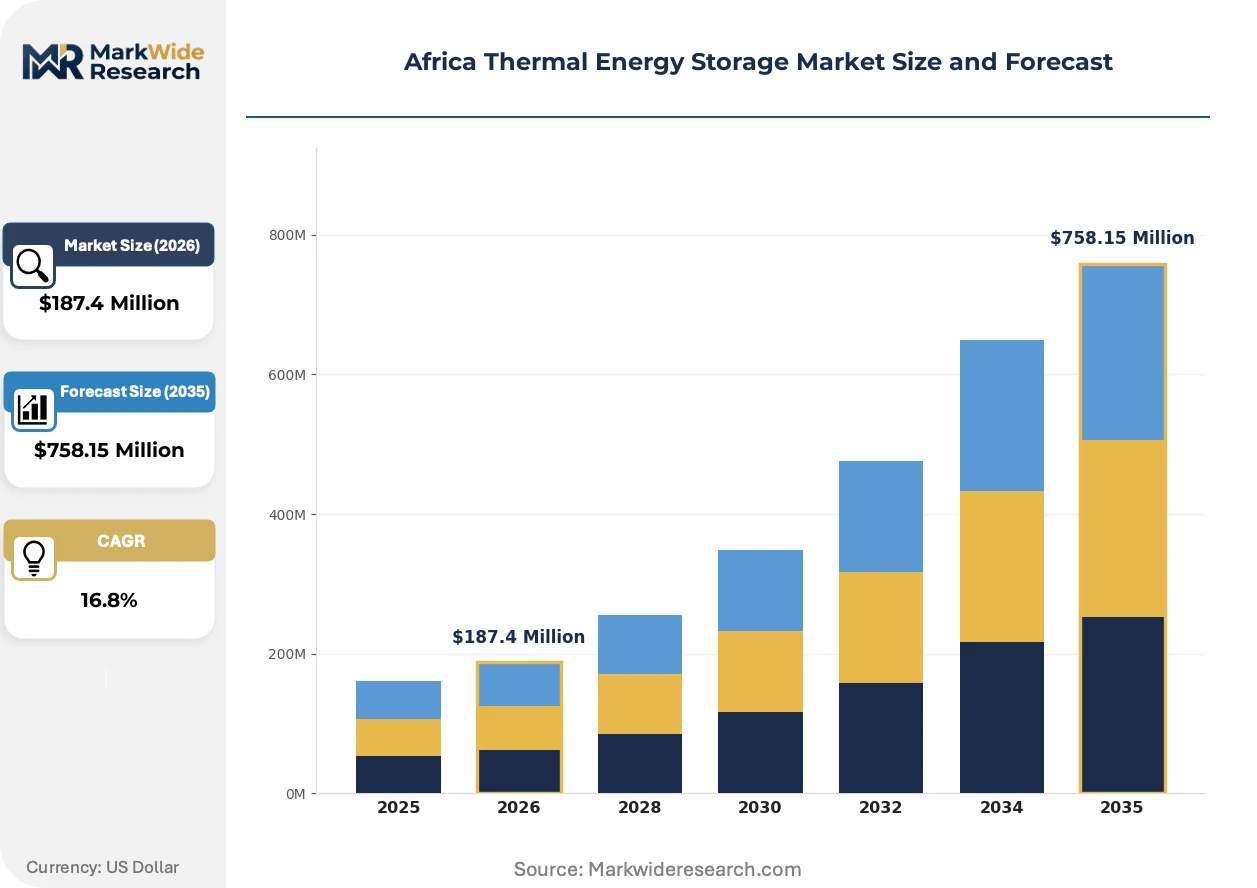
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Molten Salt, Phase Change Materials, Ice Storage, Water Tanks End User: Industrial, Commercial, Residential, Utilities Application: Load Shifting, Renewable Integration, Peak Shaving, District Heating Installation: On-site, Off-site, Retrofits, New Build |
| Companies Covered | Eskom Holdings SOC Ltd, Abengoa SA, ACWA Power International, SENER Group, Engie SA, Azelio AB, BrightSource Energy Inc, SolarReserve LLC, Calmac, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Thermal Energy Storage Market Strategic Shifts
Technology convergence between photovoltaic generation and thermal storage media is collapsing the cost gap between standalone solar and dispatchable renewable assets. This shift is rewriting procurement specifications for utility buyers and industrial offtakers alike.
Molten salt two-tank systems is integrating advanced nitrate mixture formulations that extend operating temperature ranges above 565°C. South African utility procurement teams are specifying these configurations in REIPPPP bid submissions to maximize round-trip efficiency. The technology is integrating into project finance structures that previously excluded thermal assets due to perceived technology risk.
Morocco's ONEE technical specifications for grid-connected concentrated solar power now mandate minimum twelve-hour storage duration, exceeding earlier six-hour thresholds. This regulatory tightening disqualifies single-tank thermocline designs from Noor Ouarzazate follow-on projects. Developers are responding with enlarged hot salt inventory designs that increase civil works costs by fifteen to twenty percent.
Industrial offtakers in South Africa's mining corridor are consolidating energy procurement under single buyer entities to negotiate thermal storage tolling agreements. This buyer concentration is displacing individual site-level contracting that dominated prior renewable energy procurement. The pattern is most visible in the platinum group metals sector, where shared services organizations now aggregate demand across multiple smelter and refinery locations.
Africa Thermal Energy Storage Market Segmentation
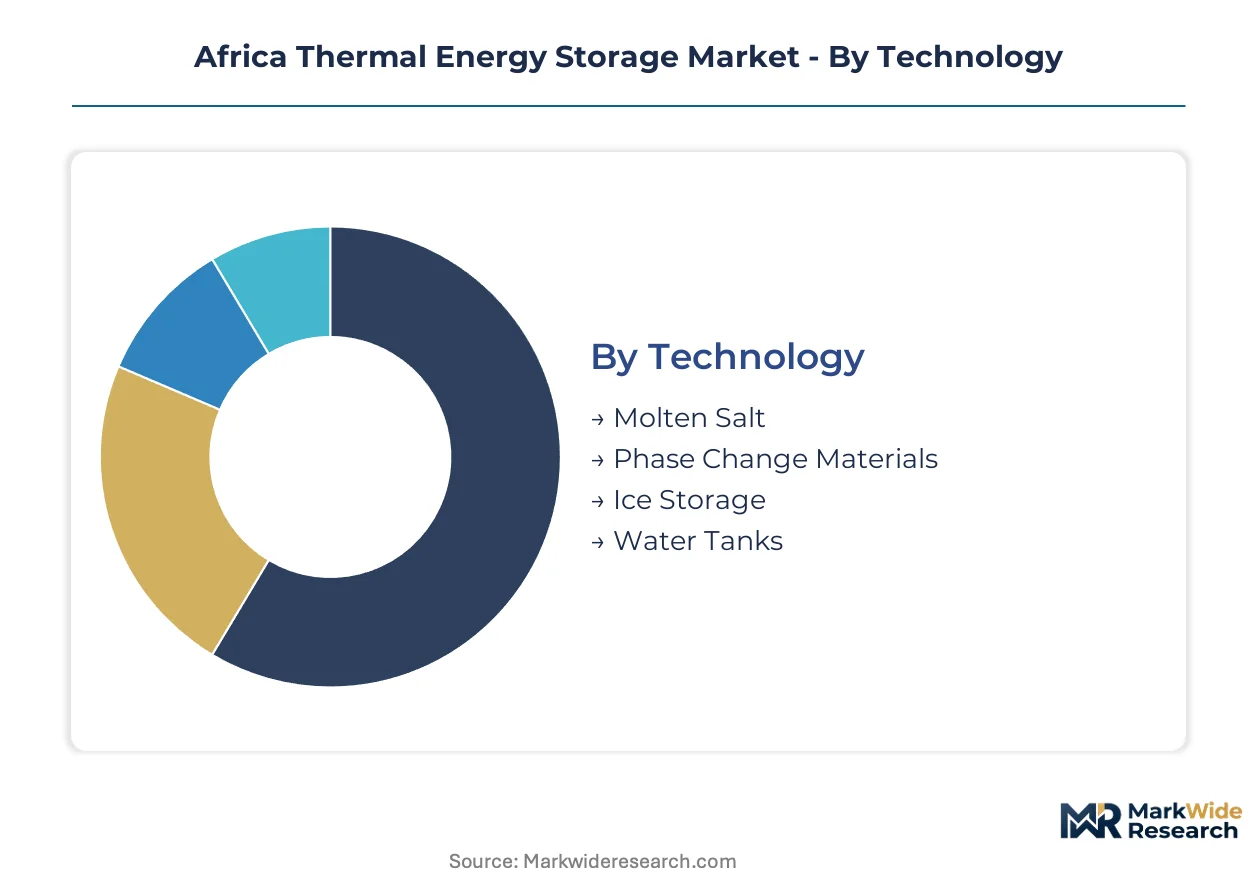
Technology selection in African thermal energy storage hinges on temperature requirements, duration needs, and capital intensity. End-user procurement patterns diverge sharply between utility-scale offtakers seeking dispatchable renewable capacity and industrial buyers optimizing tariff arbitrage.
Technology:
Molten salt configurations command premium pricing due to extended duration capability, while ice storage and water tanks occupy volume tiers where upfront cost sensitivity dominates buyer decisions.
- Molten Salt:Nitrate salt mixtures operate above 220°C, delivering heat retention exceeding twelve hours through dual-tank configurations. Demand concentrates in South Africa's Northern Cape concentrated solar power clusters, where REIPPPP auction rules now mandate storage co-location as a condition of bid eligibility.
- Phase Change Materials:Latent heat storage media with defined melting points enable compact thermal buffering in space-constrained environments. Mining sector procurement in South Africa's platinum belt is pulling commercial-scale installations as time-of-use tariff structures penalize peak consumption.
- Ice Storage:Chilled water and ice banks provide commercial cooling load shifting with lower capital intensity than molten salt systems. South African retail estate developers favor behind-the-meter configurations paired with rooftop photovoltaic arrays.
- Water Tanks:Sensible heat storage in insulated vessels serves low-temperature applications with minimal technical complexity. Moroccan hospitality and healthcare facilities deploy these systems where maintenance capability constraints exclude high-temperature alternatives.
Mature deployment sits with molten salt systems in utility-scale procurement. Newer deployment is concentrated in phase change materials for industrial tariff optimization.
End User:
Procurement authority and offtake scale determine technology access, with utilities and large industrials capturing advanced molten salt configurations while commercial and residential segments remain tethered to lower-temperature alternatives.
- Industrial:Mining, smelting, and refining operations require process heat and electricity load management across extended operating schedules. South Africa's platinum group metals sector is consolidating procurement under shared services organizations to negotiate thermal storage tolling agreements across multiple facility locations.
- Utilities:Grid operators and independent power producers procure multi-hour duration storage to firm renewable generation and meet dispatch obligations. Eskom Holdings SOC Ltd anchors procurement through grid infrastructure dominance and connection queue control.
- Commercial:Retail, hospitality, and office building operators seek behind-the-meter optimization with shorter duration storage. Kenya's Energy and Petroleum Regulatory Authority net metering framework enables distributed aggregation for industrial park microgrids serving commercial tenants.
- Residential:Single-family and multi-unit dwellings deploy small-scale thermal storage for water heating and space conditioning. High capital costs and limited technical service networks constrain penetration outside South Africa's urban centers.
Industrial offtakers command technology customization and contract structuring. Utility procurement is expanding fastest as auction designs embed storage mandates.
Application:
Duration requirements and revenue mechanisms differentiate application segments, with renewable integration demanding the longest discharge periods and peak shaving capturing the highest marginal value per kilowatt-hour.
- Load Shifting:Temporal displacement of electricity consumption from high-tariff to low-tariff periods. Mining operations in South Africa's Northern Cape deploy molten salt and phase change material systems to arbitrage Eskom's time-of-use pricing structures.
- Renewable Integration:Firming variable solar and wind generation through stored thermal discharge. Morocco's ONEE technical specifications now mandate minimum twelve-hour storage duration for concentrated solar power grid connection, exceeding earlier six-hour thresholds.
- Peak Shaving:Reduction of maximum demand charges through stored energy discharge during network-constrained periods. Commercial installations in Johannesburg and Cape Town target distribution network capacity limits.
- District Heating:Centralized thermal generation and distribution to multiple buildings through piped networks. Applications remain nascent across Africa due to urban density patterns and limited legacy infrastructure.
Renewable integration anchors utility-scale investment. Peak shaving is gaining share fastest in commercial behind-the-meter deployment.
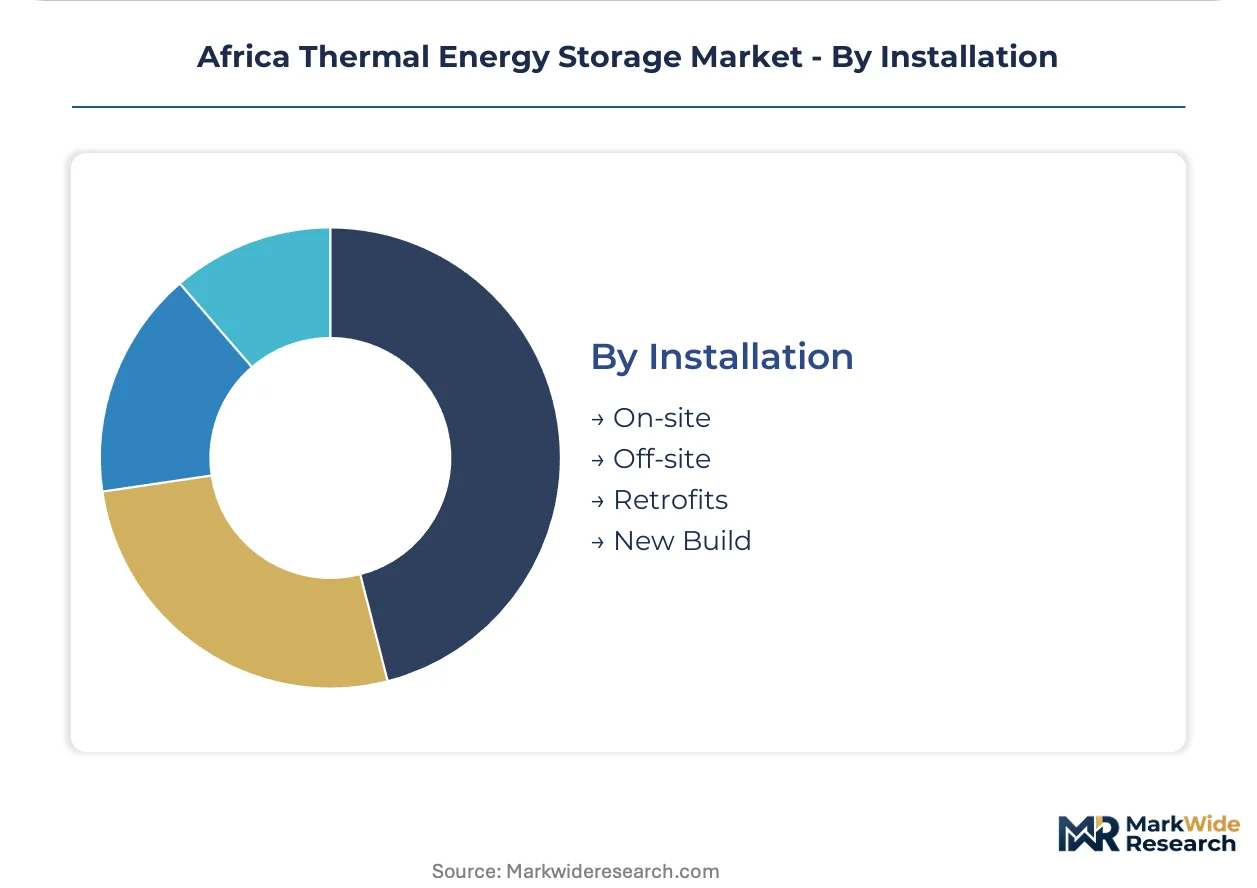
Installation:
Site control and construction timing determine installation mode selection, with greenfield developments integrating storage from design and existing facilities facing space and interconnection constraints.
- On-site:Storage assets located within facility boundaries with direct connection to generation or load. Concentrated solar power developers in Morocco's Noor Ouarzazate complex favor integrated on-site configurations to minimize thermal transport losses.
- Off-site:Standalone storage facilities connected through transmission or distribution networks. Limited deployment due to heat transfer economics and African grid infrastructure constraints.
- Retrofits:Addition of thermal storage to existing buildings or generation facilities. South African commercial building retrofits favor phase change materials where mechanical room volumes constrain water tank deployment.
- New Build:Storage integrated during original construction of generation or consumption facilities. REIPPPP auction winners in South Africa specify molten salt systems during engineering design to optimize civil works and heat exchanger placement.
New build installations capture utility-scale procurement. Retrofits are expanding most quickly in commercial building energy optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upington anchors Africa's thermal energy storage deployment through its concentrated solar power corridor in South Africa's Northern Cape province. This cluster concentrates molten salt engineering expertise and grid connection infrastructure. Four national markets structure the continental landscape.
South Africa
Eskom's time-of-use tariff restructuring drives mining sector demand for phase change material systems across the platinum belt. The Department of Mineral Resources and Energy administers REIPPPP auction rules that now mandate storage co-location for bid eligibility. Northern Cape project pipelines concentrate molten salt installations near Upington and De Aar.
Morocco
Noor Ouarzazate complex expansion sustains demand for extended-duration nitrate salt configurations. ONEE technical specifications enforce minimum twelve-hour storage duration thresholds for grid-connected concentrated solar power. The Ouarzazate solar cluster attracts engineering procurement from Spanish and Gulf-based contractors.
Egypt
New and Renewable Energy Authority feed-in tariff revisions open concentrated solar power corridors in the Western Desert. The national electricity utility negotiates long-term power purchase agreements for dispatchable renewable capacity. Benban solar development zones near Aswan host pilot thermal storage integration projects.
Kenya
Industrial park microgrids pull distributed thermal storage aggregation under Energy and Petroleum Regulatory Authority net metering frameworks. Geothermal-hybrid project developers test molten salt buffering for steam turbine optimization. Naivasha and Olkaria energy corridors host technology demonstration sites.
Africa Thermal Energy Storage Market Competitive Environment
Premium-margin players sit above commodity-margin players across engineering specialization and project finance access. The market structures around three tiers: utility-scale developers with sovereign-backed offtake relationships, technology licensors with proprietary molten salt formulations, and regional EPC contractors bidding on civil works packages. Dominant competitive moves include strategic partnerships with national utilities and geographic expansion into underpenetrated North African markets.
Among utility-anchored developers, Eskom Holdings SOC Ltd occupies a position as the continent's dominant grid operator and procurement gatekeeper. Spanish engineering specialists Abengoa SA and SENER Group exemplify the technology-licensor archetype, representing concentrated solar power design capabilities transferred from European project experience. Saudi-listed ACWA Power International sits within the independent power producer tier, anchoring competitive positioning across Morocco and South Africa through long-term concession frameworks.
| Leading Market Players |
|---|
| Eskom Holdings SOC Ltd |
| Abengoa SA |
| ACWA Power International |
| SENER Group |
| Engie SA |
| Azelio AB |
| BrightSource Energy Inc |
| SolarReserve LLC |
| Calmac |
| Others |
Value Chain & Pricing Dynamics
Utility-scale independent power producers in South Africa's REIPPPP framework anchor pricing power through long-term power purchase agreements that compress risk premiums for molten salt developers. This buyer concentration enables value-based contracting tied to dispatchable capacity guarantees rather than equipment cost-plus structures.
Pricing Analysis
Dispatch reliability premiums dominate pricing structures, with developers capturing value through guaranteed capacity payments indexed to grid stability outcomes. Price differentiation separates projects with twelve-hour storage duration from six-hour alternatives, with Moroccan ONEE technical specifications enforcing this tiering through grid connection eligibility. Cost compression in nitrate salt mixtures is intensifying because Moroccan supply localization is displacing European imports. Mining sector offtakers in South Africa's platinum belt exhibit highest price sensitivity due to tariff arbitrage margins, while utility buyers prioritize technical compliance over unit cost.
Supply Chain Analysis
Welding and piping specialists qualified for 550°C molten salt circuits command wage premiums that distort EPC pricing in South Africa's Northern Cape. Manufacturing concentration centers on Spain and the United States for specialist heat exchanger engineering, with nitrate salt mixture production clustering in Morocco's chemical corridor. Raw material dependencies include sodium nitrate, potassium nitrate, and high-grade stainless steel alloys. Single-source vulnerability runs through Spanish engineering houses that dominate concentrated solar power design transfer. Distribution feeds from EPC contractors through to project developers under engineering-procurement-construction contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molten salt engineering capability scarcity props pricing premiums, with specialist welding certifications creating a supply-side bottleneck that sustains margin structures for qualified contractors.
For Market Incumbents: Cement technology leadership through captive training programs for high-temperature piping specialists in South Africa's Northern Cape, locking in workforce access before competitor capacity expansion. Deepen backward integration into nitrate salt mixture formulation to capture margin from Moroccan supply localization trends. Defend against emerging Chinese EPC entrants by embedding proprietary heat exchanger designs into REIPPPP bid specifications. For New Entrants and Emerging Players: The premium-to-economy gap between utility-scale molten salt and commercial ice storage creates entry space for hybrid photovoltaic-thermal configurations targeting South African retail estates. Target Egypt's Western Desert concentrated solar power corridors where feed-in tariff revisions have attracted minimal incumbent competition. Pursue tolling agreement structures with mining shared services organizations to bypass individual site-level procurement complexity. For Investors and Strategic Acquirers: The window for entry favors technology licensors with proprietary molten salt formulations and demonstrated project execution records. Long-term viability rests on regulatory embedding through national storage mandates rather than voluntary procurement. Watch for REIPPPP auction rule changes that expand storage duration requirements as the inflection signal for capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | REIPPPP auction winners in South Africa's Northern Cape expand molten salt inventory to meet twelve-hour duration mandates. |
| Power Purchase Agreement | Eskom's time-of-use tariff restructuring enables mining sector tolling agreements for phase change material systems. |
| Technology Licensing | Spanish engineering specialists transfer concentrated solar power designs to Moroccan Noor Ouarzazate follow-on projects. |
| Backward Integration | Moroccan developers localize nitrate salt mixture supply to compress installed costs for extended-duration configurations. |
| Green Certification Program | Kenya's Energy and Petroleum Regulatory Authority net metering framework enables distributed thermal storage aggregation. |
Study Parameters
Regulatory filings from South Africa's National Energy Regulator, Morocco's ONEE, and Egypt's New and Renewable Energy Authority formed the secondary backbone for auction rule and technical specification analysis. Primary interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators combined with secondary validation from IEA reports and project development databases. Bottom-up and top-down triangulation anchored market sizing across technology and end-user segments.
Bottom-up modeling tracked individual project pipelines through engineering design phases, while top-down analysis cross-checked against national renewable energy targets and grid connection queue data. Segmentation dimensions included technology type, end-user category, application purpose, and installation mode across the analysis window. CAGRs derived from project commissioning timelines and capacity addition forecasts, with inputs from molten salt cost curves and regulatory auction schedules.
Underlying measurement precision varies by segment; utility-scale molten salt installations carry tighter precision than nascent commercial ice storage deployment. Forecasts reflect assumptions about REIPPPP auction continuity and Moroccan ONEE technical specification stability. Material deviation in storage duration mandates or nitrate salt supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Thermal Energy Storage
Ice Thermal Storage Systems Market
Thermal Energy Storage
Thermal Energy Storage (TES) Market
Thermal Energy Storage
Europe District Heating Market
Thermal Energy Storage
Solar Thermal Fuel Market
Thermal Energy Storage
Southeast Asia Thermal Power Market
Thermal Energy Storage
North America Thermal Energy Storage Market
Thermal Energy Storage
Russia Thermal Power Market
Thermal Energy Storage
Asia-Pacific Thermal Energy Storage Market
Thermal Energy Storage
China Thermal Power Plant Market
Thermal Energy Storage
Molten Salt Thermal Energy Storage (TES) Market
Thermal Energy Storage
North America Thermal Power Market
Thermal Energy Storage
Middle-East and Africa Thermal Power Market
Thermal Energy Storage
United States Thermal Power Market
Thermal Energy Storage
Thermal Recovery Market
Thermal Energy Storage
Europe Thermal Energy Storage Market