
 Molten Salt Thermal Energy Storage (TES) Market | 2026-2036
Molten Salt Thermal Energy Storage (TES) Market Size, Share, and Industry Trends Forecast 2026-2036
Molten Salt Thermal Energy Storage (TES) Market Foresight
The EU Green Deal's carbon border adjustment mechanism is hardening demand for dispatchable renewable assets across member states. Abengoa SA leverages decades of parabolic trough engineering to sustain project pipelines in Spain and export markets. ACWA Power anchors large-scale deployment in Saudi Arabia, while SENER Grupo de Ingenieria competes on integrated EPC capabilities for tower configurations.
Molten salt thermal energy storage employs alkali nitrate mixtures, typically 60% sodium nitrate and 40% potassium nitrate, heated to 290–565°C to store thermal energy for later electricity generation through steam turbines. The technology serves grid-scale renewable dispatch and industrial heat decarbonization. Power Towers command structural attention for their higher operating temperatures and superior round-trip efficiency, while Parabolic Troughs retain installed base dominance due to lower capital intensity and proven financing structures. The Renewable Energy Integration application absorbs the largest share of new capacity, though Load Shifting applications attract premium margins where time-of-use spreads justify longer-duration storage configurations.
Spain's CNMC and the EU F-Gas Regulation shape equipment standards and working fluid compliance for molten salt systems deployed across Europe. China's National Energy Administration and MIIT coordinate domestic manufacturing scale-up and grid interconnection protocols for tower projects. Stakeholders must monitor regulatory treatment of long-duration storage in capacity markets and evolving carbon accounting rules for thermal assets.
Market Dynamics
Power tower configurations are consolidating technical preference over parabolic troughs as developers prioritize higher thermodynamic efficiency and extended discharge duration in dispatchable solar assets.
Growth Catalysts
- China's dual carbon framework:Feed-in tariff reforms and streamlined grid interconnection protocols under the National Energy Administration are accelerating approvals for tower systems with integrated molten salt storage.
- Saudi gigawatt procurement:Vision 2030 initiatives are mandating salt-based TES at multiple solar sites to enable overnight generation and grid stability services.
- EU Green Deal carbon border mechanism:The CBAM is hardening demand for dispatchable renewable assets across member states, favoring thermal storage that displaces fossil peaking capacity.
Market Restraints
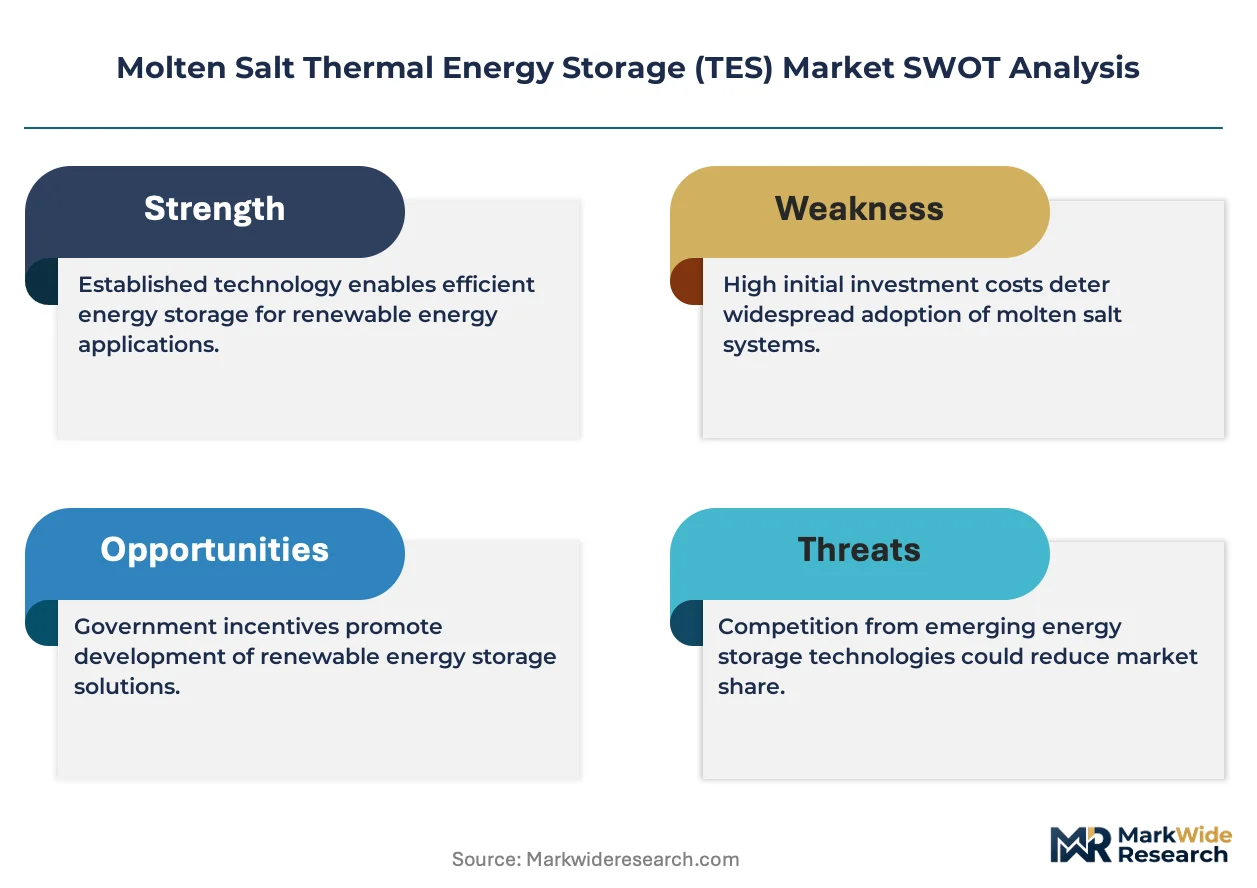
- Nitrate salt price volatility:Sodium nitrate and potassium nitrate input costs fluctuate with fertilizer market cycles and mining supply disruptions in Chile and Israel.
- High-temperature corrosion:Structural materials degradation at 565°C operating limits requires costly nickel-based alloys that extend project payback periods.
- Geographic supply concentration:EPC capability for tower systems concentrates in Spain and China, creating bottleneck risk for developers in emerging markets.
Strategic Opportunities
- Industrial heat decarbonization:Cement and steel producers in Germany and Japan are piloting molten salt systems for process heat substitution, opening non-power revenue streams.
- EU F-Gas Regulation phase-down:Restrictions on synthetic heat transfer fluids are creating regulatory tailwind for salt-based alternatives in European trough retrofits.
- Hybrid renewable configurations:Co-location with photovoltaic and wind assets enables arbitrage across multiple generation profiles and capacity market participation.
Industry Challenges
- Thermal systems engineering talent:Specialized expertise in high-temperature heat exchanger design and salt chemistry remains concentrated among legacy CSP engineering firms.
- Extended commissioning timelines:Molten salt system heat-up and freeze protection protocols add months to project schedules compared to battery storage alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molten Salt Thermal Energy Storage (TES) Market |
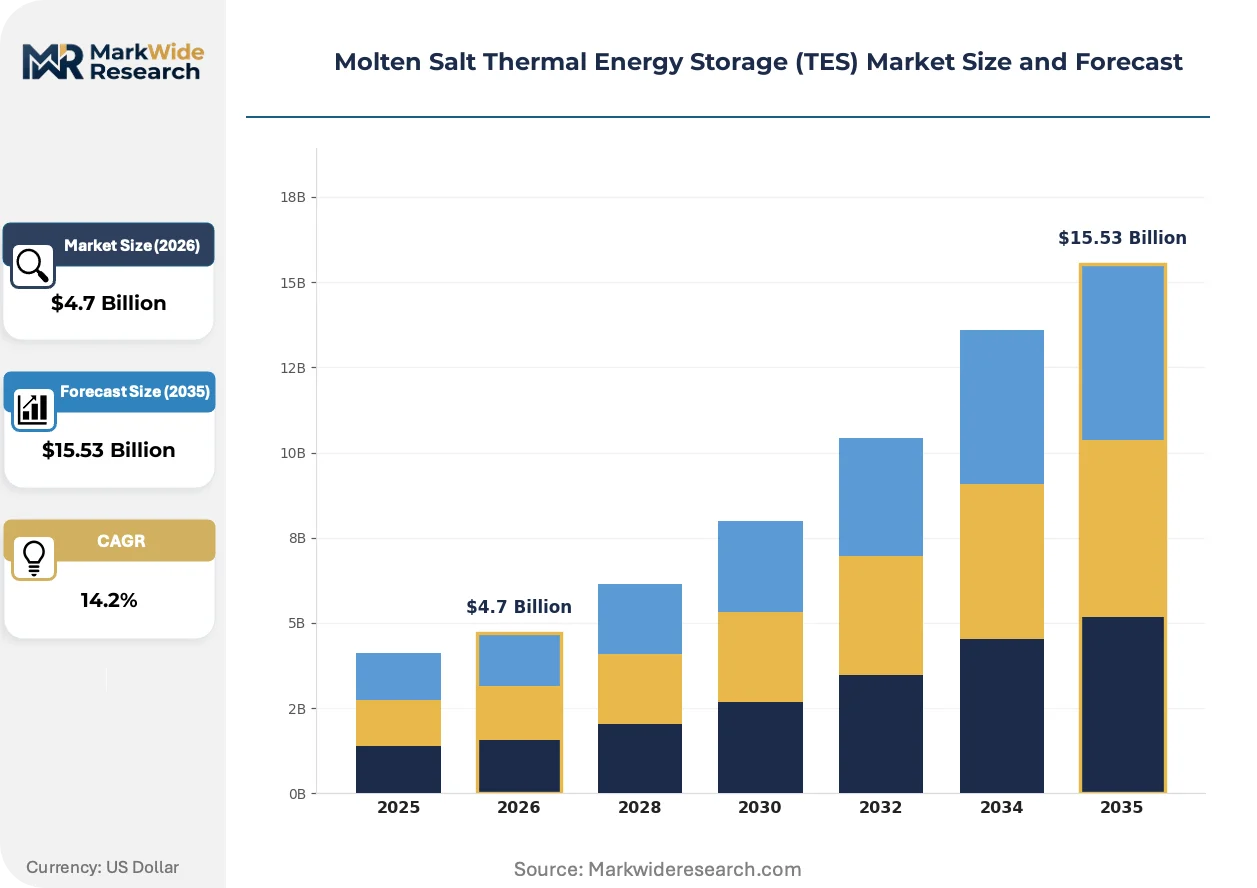
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parabolic Troughs, Power Towers, Linear Fresnel, Dish Stirling Technology: Thermal Energy Storage, Heat Transfer Fluids, Phase Change Materials, Solar Thermal End User: Power Utilities, Industrial Processes, Residential Applications, Commercial Buildings Application: Renewable Energy Integration, Peak Shaving, Load Shifting, Backup Power |
| Companies Covered | Acciona SA, Abengoa SA, BrightSource Energy, SolarReserve, SUPCON, ACWA Power, ESolar, SENER Grupo de Ingenieria, Torresol Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molten Salt Thermal Energy Storage (TES) Market Shifts & Advancements
Developers are converging on standardized tower configurations while salt chemistry advances and procurement models evolve to accommodate longer-duration storage economics.
Ternary and quaternary salt mixtures with expanded liquidus ranges are consolidating technical roadmaps for next-generation systems. Sandia National Laboratories and German aerospace research centers are validating chloride and carbonate formulations that push operating temperatures toward 700°C. These formulations enable higher steam turbine inlet conditions and improved round-trip efficiency. The technology is consolidating competitive positioning around thermodynamic performance rather than capital cost minimization.
The EU F-Gas Regulation and Spain's CNMC equipment standards are reshaping working fluid compliance requirements for European deployments. Restrictions on hydrofluorocarbon heat transfer fluids are forcing trough operators to evaluate direct salt heating or alternative organic compounds. Spanish project pipelines face extended environmental permitting timelines as regulators scrutinize salt spill containment and groundwater protection protocols.
Utility offtakers are restructuring procurement toward availability-based contracts with energy-only settlement rather than traditional EPC turnkey structures. Saudi Arabia's ACWA Power and emerging developers in Morocco are negotiating long-term service agreements that unbundle O&M from initial construction. This shift transfers operational risk to technology providers and favors EPC firms with integrated asset management capabilities.
Molten Salt Thermal Energy Storage (TES) Market Segmentation
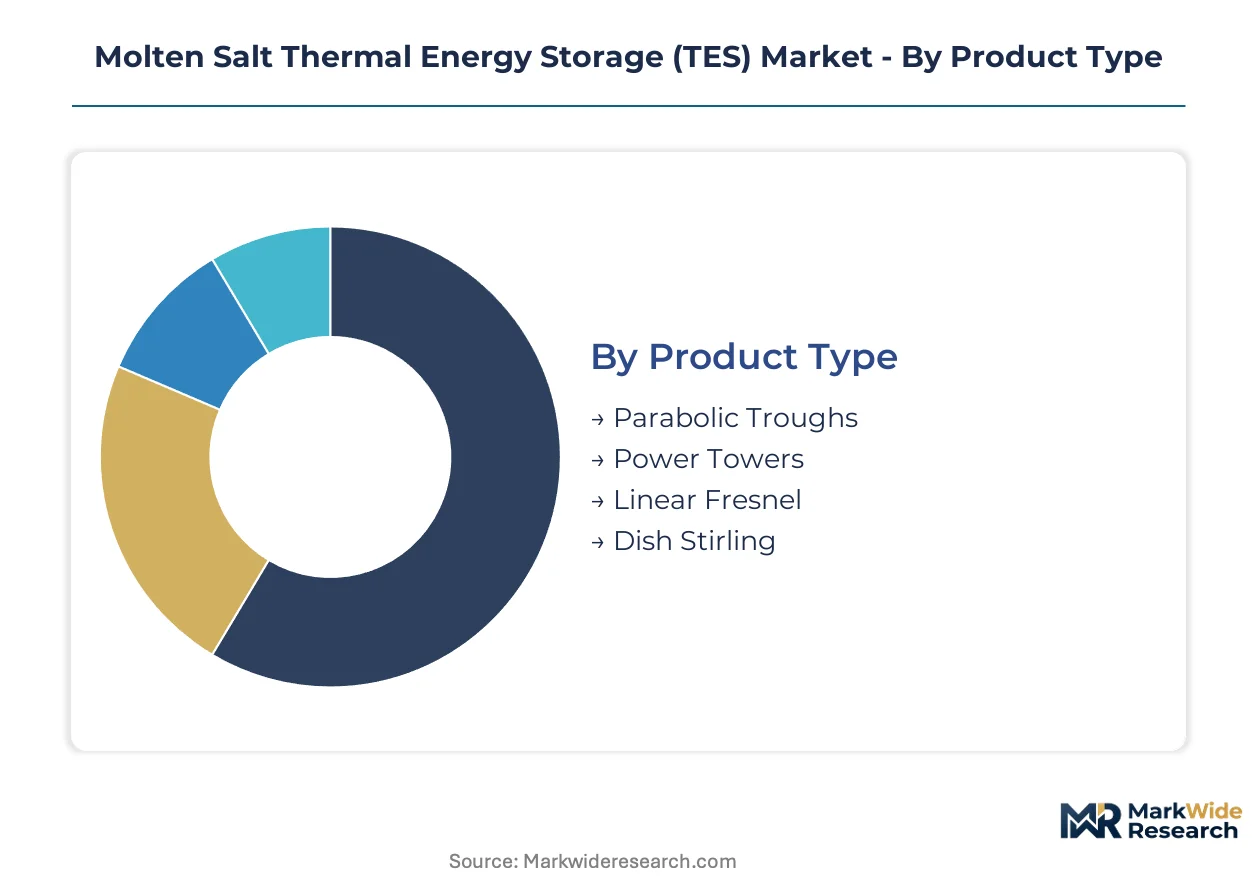
Molten salt TES deployment patterns diverge sharply across technology configurations and end-use economics. Product type selection determines thermodynamic ceiling and project finance structure, while application segmentation separates grid-scale utilities from industrial heat substitution plays.
Product Type:
Power towers command premium positioning through superior temperature ranges, while parabolic troughs anchor volume deployment via proven bankability.
- Power Towers:Central receiver systems achieve 565°C operating temperatures using molten salt as both heat transfer fluid and storage medium. Saudi Arabia's ACWA Power and China's National Energy Administration are prioritizing tower configurations for gigawatt-scale procurement under streamlined interconnection protocols. Higher thermodynamic efficiency enables extended discharge duration and improved round-trip economics.
- Parabolic Troughs:Linear concentrator arrays with synthetic oil heat transfer and indirect salt storage dominate installed base capacity. Spain's CNMC equipment standards and legacy project pipelines sustain trough deployment across European markets, though F-Gas Regulation restrictions on hydrofluorocarbon working fluids are forcing operational retrofits.
- Linear Fresnel:Fixed-tube receiver geometry reduces structural steel requirements and enables direct steam generation with simplified salt integration.
- Dish Stirling:Point-focus parabolic dishes with Stirling engine conversion achieve highest solar-to-electric efficiency but face salt storage integration challenges at distributed scale.
Today's leader: Parabolic Troughs. Tomorrow's challenger: Power Towers.
Technology:
Storage chemistry innovations are displacing conventional heat transfer architectures as developers prioritize duration economics over instantaneous output.
- Thermal Energy Storage:Dual-tank molten salt systems employing 60% sodium nitrate and 40% potassium nitrate mixtures enable 6-15 hour discharge duration. Sandia National Laboratories validation of chloride and carbonate formulations above 700°C is reshaping next-generation system design toward higher steam turbine inlet conditions.
- Heat Transfer Fluids:Synthetic oils and molten salts serve distinct temperature regimes in trough versus tower configurations. EU F-Gas Regulation phase-down is accelerating salt-based alternatives for European retrofits.
- Phase Change Materials:Salt hydrate and metallic phase change media offer higher volumetric energy density for compact industrial heat applications.
- Solar Thermal:Collector field configurations integrate with storage subsystems to enable dispatchable renewable generation beyond daylight hours.
Storage duration requirements favor Thermal Energy Storage. Phase Change Materials are climbing fastest for industrial process heat substitution.
End User:
Utility procurement scale contrasts with industrial heat decarbonization margins as divergent customer economics reshape technology roadmaps.
- Power Utilities:Grid-scale developers under Saudi Vision 2030 and China's dual carbon framework mandate salt-based TES for overnight generation and ancillary services. Availability-based contracting with energy-only settlement is transferring operational risk to EPC integrators.
- Industrial Processes:Cement and steel producers in Germany and Japan pilot molten salt systems for process heat substitution, opening premium-margin revenue streams outside power markets.
- Residential Applications:Distributed solar thermal with compact salt storage serves niche heating markets in high-insolation regions.
- Commercial Buildings:Cogeneration and district heating integration enables load management for large thermal consumers.
Power Utilities dominate capacity deployment. Industrial Processes offer steepest margin expansion as carbon border mechanisms harden compliance requirements.
Application:
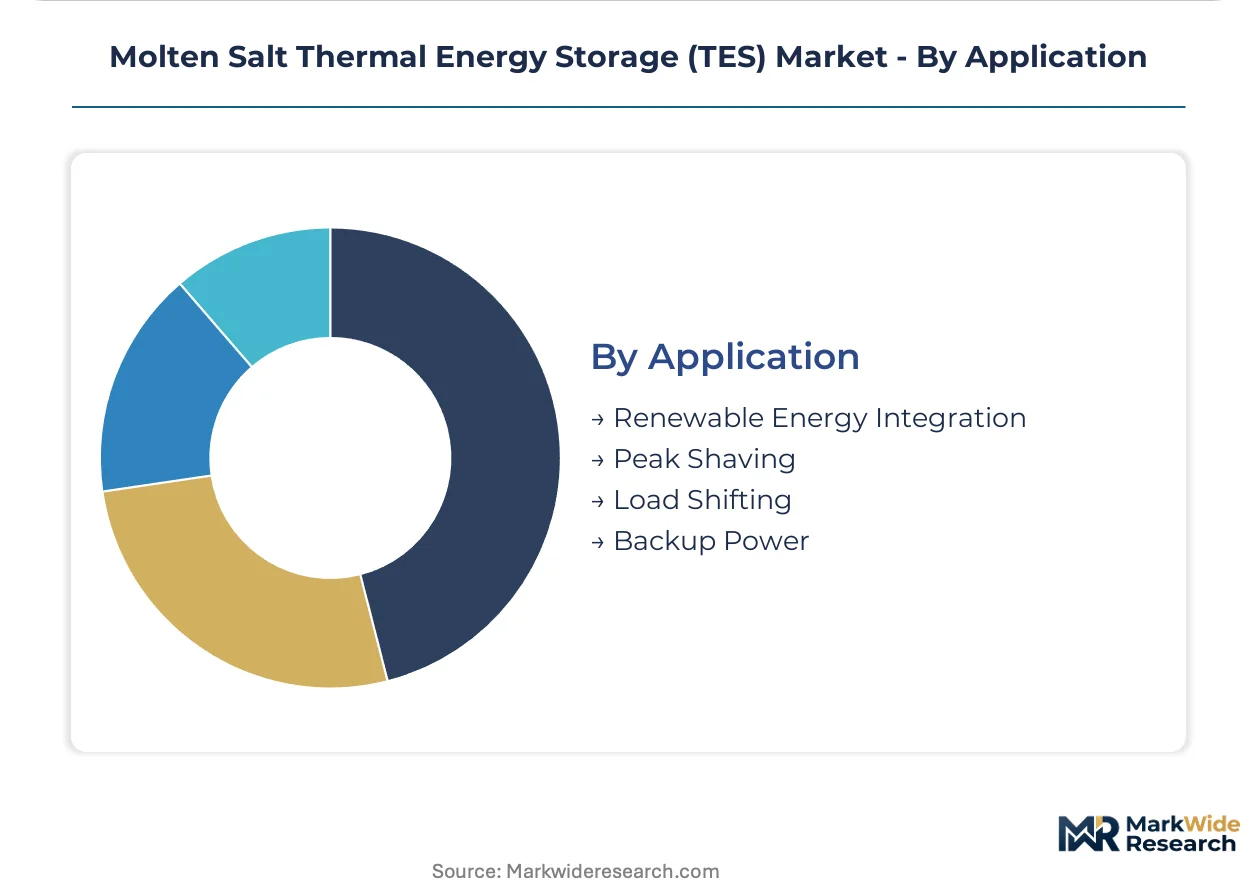
Renewable integration volume competes with load shifting premium economics as time-of-use spreads widen across deregulated power markets.
- Renewable Energy Integration:Co-location with photovoltaic and wind assets enables arbitrage across generation profiles and capacity market participation. Hybrid configurations are consolidating technical preference for grid-scale deployment.
- Load Shifting:Extended-duration storage captures peak-to-off-peak price spreads where time-of-use tariffs justify 8+ hour discharge configurations. Premium margins attract developer attention in deregulated European and Middle Eastern markets.
- Peak Shaving:Short-duration discharge reduces maximum demand charges for industrial and commercial consumers.
- Backup Power:Critical facility resilience applications serve niche markets with high reliability requirements.
Renewable Energy Integration absorbs largest capacity share. Load Shifting is gaining share fastest where market design rewards duration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized thermal systems engineers cluster around legacy concentrated solar power corridors in Spain and emerging gigawatt-scale deployment zones in Saudi Arabia and China. These talent concentrations anchor project execution capability for high-temperature salt systems.
Saudi Arabia
Vision 2030 procurement mandates salt-based TES at multiple solar sites to enable overnight generation and grid stability services. The Saudi Electricity Company coordinates interconnection standards for dispatchable renewable assets under the national renewable energy program. ACWA Power anchors gigawatt-scale tower deployment at sites across the kingdom, transferring operational risk through availability-based contracting structures.
China
Dual carbon goals and feed-in tariff reforms are accelerating domestic project approvals for tower systems with integrated molten salt storage. The National Energy Administration and MIIT coordinate manufacturing scale-up and grid interconnection protocols for high-temperature systems. Project pipelines concentrate in the western provinces where solar irradiance and available land support utility-scale development.
Spain
Legacy parabolic trough engineering expertise sustains European project pipelines and export market participation. The CNMC and EU F-Gas Regulation shape equipment standards and working fluid compliance for molten salt systems deployed across member states. Abengoa SA leverages decades of trough experience to maintain engineering leadership from its Seville operational base.
United States
Sandia National Laboratories validates advanced salt chemistries including chloride and carbonate formulations above 700°C for next-generation system design. The Department of Energy funds demonstration programs for extended-duration thermal storage configurations. BrightSource Energy and SolarReserve occupy positions within the domestic technology development ecosystem, though commercial deployment lags Middle Eastern and Chinese markets.
Morocco
Noor Ouarzazate complex experience has established local EPC capability and regulatory familiarity for salt-based TES integration. The Moroccan Agency for Sustainable Energy manages procurement frameworks that prioritize dispatchable renewable capacity. Emerging developers negotiate long-term service agreements that unbundle O&M from initial construction, following Saudi contracting evolution.
Molten Salt Thermal Energy Storage (TES) Market Competitive Landscape
Capital-heavy EPC integrators compete with technology licensors and project developers across divergent risk allocation models. The vendor base stratifies between full-service construction firms, specialized salt systems engineers, and hybrid renewable developers seeking dispatchable capacity additions. Three archetypes dominate: integrated EPC operators with captive technology, technology licensors partnering with regional constructors, and utility-affiliated developers securing long-term offtake. Competitive moves center on availability-based contracting adoption and strategic partnerships to access restricted geographies.
Among Spanish-integrated EPC specialists, Abengoa SA and SENER Grupo de Ingenieria exemplify the full-service archetype with decades of parabolic trough and tower execution experience. ACWA Power anchors the developer-led model from its Saudi base, structuring procurement that transfers operational risk to technology providers through unbundled O&M agreements. These three occupy positions that reflect the market's bifurcation between European engineering heritage and Middle Eastern deployment scale.
| Leading Market Players |
|---|
| Acciona SA |
| Abengoa SA |
| BrightSource Energy |
| SolarReserve |
| SUPCON |
| ACWA Power |
| ESolar |
| SENER Grupo de Ingenieria |
| Torresol Energy |
| Others |
Supply & Pricing Matrix
Sovereign-backed developers and utility-affiliated EPC consortia dominate project ownership across Saudi Arabia and China, anchoring long-term offtake pricing discipline while concentrating procurement leverage over nitrate salt suppliers and high-temperature alloy fabricators. This ownership pattern feeds into supply chain behavior through multi-year framework agreements that buffer input cost volatility, yet pricing power remains asymmetric—buyers extract availability guarantees while suppliers struggle to pass through fertilizer-market-driven nitrate fluctuations.
Pricing Analysis
The bundled-versus-unbundled service split is restructuring contract economics across the molten salt TES market. Availability-based contracting with energy-only settlement now dominates Saudi gigawatt-scale procurement, transferring operational risk to EPC integrators and compressing upfront capital margins. Price differentiation centers on discharge duration guarantees and steam turbine inlet conditions rather than equipment tiers. Cost compression in parabolic trough retrofits is intensifying because EU F-Gas Regulation compliance adds working fluid conversion expenses. Industrial heat substitution buyers in Germany and Japan exhibit lowest price sensitivity due to carbon border mechanism compliance premiums, while emerging market utilities face acute budget constraints.
Supply Chain Analysis
Workforce availability for high-temperature heat exchanger fabrication concentrates in Spain's Seville-Toledo corridor and China's western manufacturing zones, creating geographic chokepoints for tower system deployment. Supply draws from Chilean and Israeli sodium nitrate mining operations, German nickel-based alloy foundries, and Chinese steel structural component producers. Single-source vulnerability runs through chloride salt chemistry validation currently concentrated at Sandia National Laboratories. Distribution runs through EPC-led turnkey delivery with captive construction crews rather than modular component shipping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Saudi project developers capture cost advantages from streamlined land access and sovereign credit backing unavailable to European competitors facing extended CNMC permitting timelines.
For Market Incumbents: Extend tower configuration standardization efforts to capture procurement scale effects against emerging Chinese EPC competitors. Defend position by deepening backward integration into nitrate salt supply through offtake partnerships with Chilean mining operators, neutralizing fertilizer market cycle exposure that threatens project returns. Prioritize certification investment for 700°C chloride salt systems to maintain technology differentiation.
For New Entrants and Emerging Players: Chloride salt chemistry validation partnerships offer a technology-first wedge into next-generation system supply without requiring decades of trough engineering heritage. Target industrial heat decarbonization pilots in Japanese steel and cement sectors as the most penetrable application segment, where premium margins offset smaller contract scale. Pursue joint development agreements with German aerospace research centers as the primary go-to-market angle for high-temperature validation credibility.
For Investors and Strategic Acquirers: Integrated utility developers are the most active acquirer in this space, seeking captive EPC capability to secure dispatchable renewable pipelines. Long-term viability hinges on duration storage economics proving competitive against lithium-ion alternatives in 8+ hour applications. Acquisition target archetype: Spanish trough engineering specialists with transferable high-temperature expertise and established CNMC regulatory relationships. Monitor EU capacity market design treatment of thermal storage assets as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Chloride Salt Chemistry Scale-Up | Sandia National Laboratories validation enables 700°C operation and improved turbine efficiency. |
| Availability-Based Contracting Adoption | ACWA Power procurement structures transfer operational risk from developers to EPC integrators. |
| Industrial Heat Pilot Expansion | German cement producers pilot molten salt substitution for process decarbonization compliance. |
| EU F-Gas Regulation Retrofit | Spanish trough operators face forced working fluid conversion to salt-based alternatives. |
| Hybrid Renewable Co-location | Saudi Vision 2030 sites combine photovoltaic generation with molten salt storage dispatch. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CSP project developers, EPC procurement leads, utility planning officers, and molten salt chemistry researchers with secondary validation from IEA deployment databases, FERC interconnection filings, EIA technology cost estimates, and EU ETS carbon price series. Bottom-up project pipeline aggregation and top-down regulatory scenario modeling provided cross-checks on capacity and revenue forecasts.
Historical reference periods anchored the forecast window through verified installation data and operational performance metrics from commissioned plants. The analysis modeled segmentation across power tower versus parabolic trough configurations, storage duration tiers, utility versus industrial end-use applications, and regional regulatory frameworks including EU Green Deal implementation, China's dual carbon framework, and Saudi Vision 2030 procurement schedules. CAGRs derived from regression analysis of announced project pipelines against interconnection approval timelines and equipment delivery lead times.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nitrate salt commodity cycles, chloride chemistry validation timelines, and EU capacity market rulemaking for thermal storage assets. Material deviation in Saudi procurement pace, Chinese manufacturing scale-up execution, or EU carbon border mechanism enforcement stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Thermal Energy Storage
China Thermal Power Plant Market
Thermal Energy Storage
Solar Thermal Fuel Market
Thermal Energy Storage
United States Thermal Power Market
Thermal Energy Storage
Europe District Heating Market
Thermal Energy Storage
Russia Thermal Power Market
Thermal Energy Storage
Middle-East and Africa Thermal Power Market
Thermal Energy Storage
Asia-Pacific Thermal Energy Storage Market
Thermal Energy Storage
Thermal Recovery Market
Thermal Energy Storage
Ice Thermal Storage Systems Market
Thermal Energy Storage
North America Thermal Power Market
Thermal Energy Storage
Europe Thermal Energy Storage Market
Thermal Energy Storage
North America Thermal Energy Storage Market
Thermal Energy Storage
Thermal Energy Storage (TES) Market
Thermal Energy Storage
Southeast Asia Thermal Power Market
Thermal Energy Storage
Africa Thermal Energy Storage Market