
 Power Tool Batteries Market | 2026-2036
Power Tool Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Power Tool Batteries Market Outlook
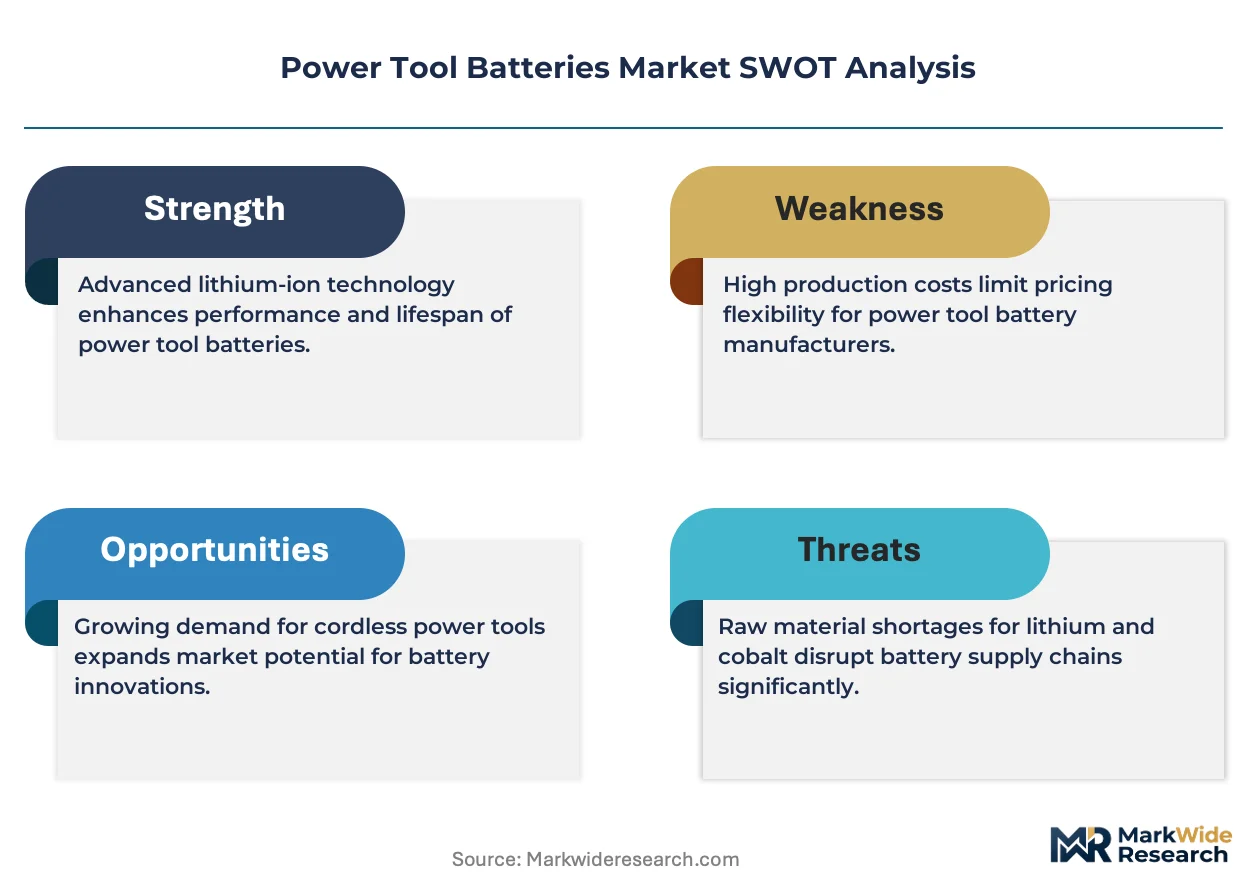
The EU Green Deal is consolidating demand around circular-economy-compliant battery platforms across European professional tool fleets. Robert Bosch GmbH leverages its in-house cell production and recycling partnerships to anchor supply security for industrial-grade 18 V and 36 V systems. Makita Corporation competes through dense dealer networks and proprietary battery interoperability across its cordless ecosystem. Samsung SDI Co. Ltd. extends its position by supplying high-discharge cylindrical cells to multiple power tool OEMs, controlling a critical upstream node in the value chain.
Power tool batteries are electrochemical energy storage devices engineered to deliver sustained high-current output in portable, shock-resistant housings, typically employing lithium-ion cells with nickel-manganese-cobalt or lithium iron phosphate cathode formulations and integrated battery management systems for thermal protection. These units enable cord-free operation of drills, impact drivers, and cutting equipment across construction, manufacturing, and facility maintenance environments. Lithium-ion chemistry dominates installed base and revenue contribution due to superior energy density and cycle life versus legacy nickel-cadmium alternatives. The 18 V and 36 V voltage ratings capture the majority of professional-grade demand, with 48 V platforms gaining traction in heavy-duty concrete and metalworking applications where torque requirements escalate.
FCC certification governs radio-frequency-enabled battery diagnostics in the US market, while REACH and RoHS frameworks in Europe restrict hazardous substances in cell chemistries and mandate disclosure of conflict minerals across supply chains. ECHA substance evaluations are accelerating phase-outs of cobalt-intensive formulations, redirecting R&D toward lithium iron phosphate and solid-state architectures. Battery management system firmware updates, second-life recycling program economics, and regional cell manufacturing subsidies represent the decisive variables stakeholders must track to preserve margin and access through the forecast horizon.
Market Dynamics
Professional contractors are consolidating cordless tool fleets around standardized voltage platforms, forcing manufacturers to prioritize backward-compatible battery architectures over proprietary ecosystems. This fleet rationalization is compressing switching costs and amplifying supplier concentration.
Growth Catalysts
- EU Green Deal battery mandates:ECHA substance evaluations are accelerating phase-outs of cobalt-intensive cathodes, redirecting R&D investment toward recyclable lithium iron phosphate chemistries that qualify for circular-economy procurement tenders.
- Automotive assembly plant electrification:German industrial maintenance crews are replacing pneumatic fastening systems with high-voltage cordless platforms, creating pull-through demand for 36 V and 48 V battery systems with extended cycle ratings.
- Cell manufacturing subsidies:Production tax credits under the US Inflation Reduction Act are incentivizing domestic cylindrical cell assembly, reducing import dependency for power tool OEMs sourcing nickel-manganese-cobalt formulations.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings are compressing gross margins for battery pack assemblers unable to pass through cost spikes to locked-in professional fleet contracts.
- Upstream cell supply concentration:Cylindrical high-discharge cell production clusters in East Asian manufacturing hubs, creating geographic single-point-of-failure risk for European and North American power tool brands.
- REACH compliance timeline friction:ECHA's evolving substance restriction lists are extending new product qualification cycles, delaying platform refreshes by 12-18 months versus legacy nickel-cadmium transition eras.
Strategic Opportunities
- Second-life stationary storage:Degraded power tool battery packs retain 60-70% capacity for residential solar buffering, opening circular-economy revenue streams through refurbishment partnerships with German energy cooperatives.
- 48 V heavy-duty concrete applications:Underpenetrated metalworking and masonry segments are migrating from corded rotary hammers to high-torque cordless platforms requiring advanced thermal management systems.
- FCC-certified diagnostic firmware:Radio-frequency-enabled battery management systems enable predictive maintenance contracts, creating recurring revenue attachment for fleet management software vendors.
Industry Challenges
- Battery management system firmware integration:Legacy tool platforms require backward-compatible firmware architectures, complicating thermal protection algorithm updates across multi-generational product lines.
- Conflict mineral disclosure complexity:RoHS and REACH mandates demand granular cobalt and lithium supply chain documentation, straining procurement systems at mid-tier battery pack assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Tool Batteries Market |
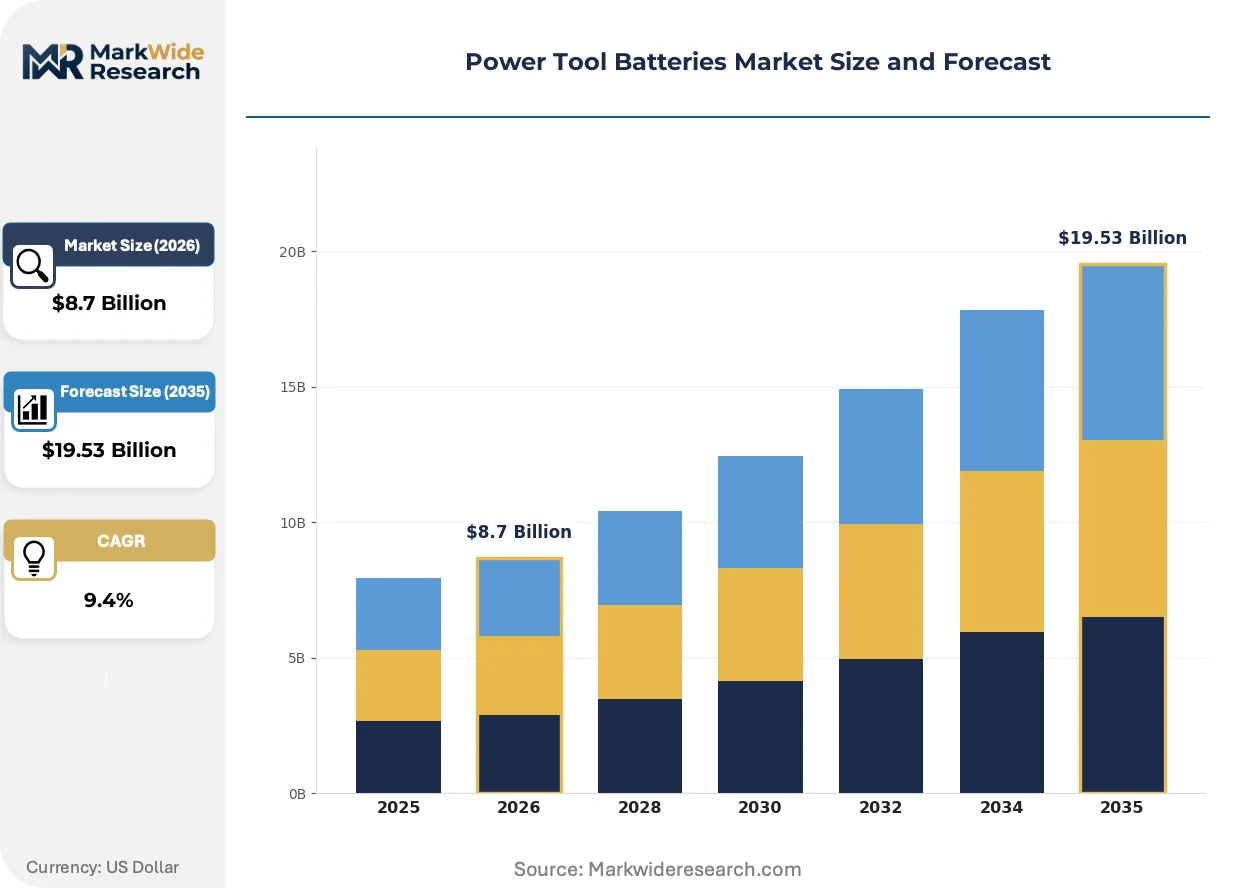
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Chemistry: Lithium-Ion, Nickel-Cadmium, Nickel-Metal Hydride, Lead-Acid, Lithium Polymer Voltage Rating: 12 V, 18 V, 24 V, 36 V, 48 V Application: Construction Equipment, Gardening Tools, Assembly Lines, Repair Workshops End User: DIY Enthusiasts, Industrial Technicians, Maintenance Crews, Professional Contractors |
| Companies Covered | Robert Bosch GmbH, Stanley Black & Decker Inc., Makita Corporation, Techtronic Industries Company Limited, Samsung SDI Co. Ltd., Panasonic Holdings Corp., Hilti AG, Milwaukee Tool, DeWalt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Tool Batteries Market Strategic Shifts
Solid-state and silicon-anode architectures are absorbing the bulk of materials R&D investment, promising energy density improvements that could reshape voltage platform segmentation. These chemistries are approaching pilot-scale validation for professional-grade discharge rates.
Silicon-dominant anode formulations are absorbing volume expansion challenges through advanced electrolyte additives and nanostructured particle designs. German automotive assembly plants are piloting 48 V prototypes for high-torque fastening applications. This chemistry is absorbing the performance gap between existing lithium-ion platforms and future solid-state architectures, compressing the timeline for heavy-duty cordless migration.
REACH substance restrictions are forcing cobalt content reductions in nickel-manganese-cobalt cathodes ahead of ECHA's 2027 evaluation deadlines. Battery pack assemblers are qualifying lithium iron phosphate alternatives for 18 V platforms previously optimized for energy density. European professional fleets are responding by extending qualification timelines and demanding dual-chemistry supplier portfolios to hedge against formulation obsolescence.
Commercial construction buyers are consolidating vendor relationships around fleet-wide battery interoperability, displacing single-brand procurement. Independent tool rental chains in Germany are expanding multi-brand battery lending pools, fragmenting OEM attachment rates. This concentration is most visible in commercial concrete and framing verticals where contractor mobility between job sites demands standardized charging infrastructure.
Power Tool Batteries Market Segmentation
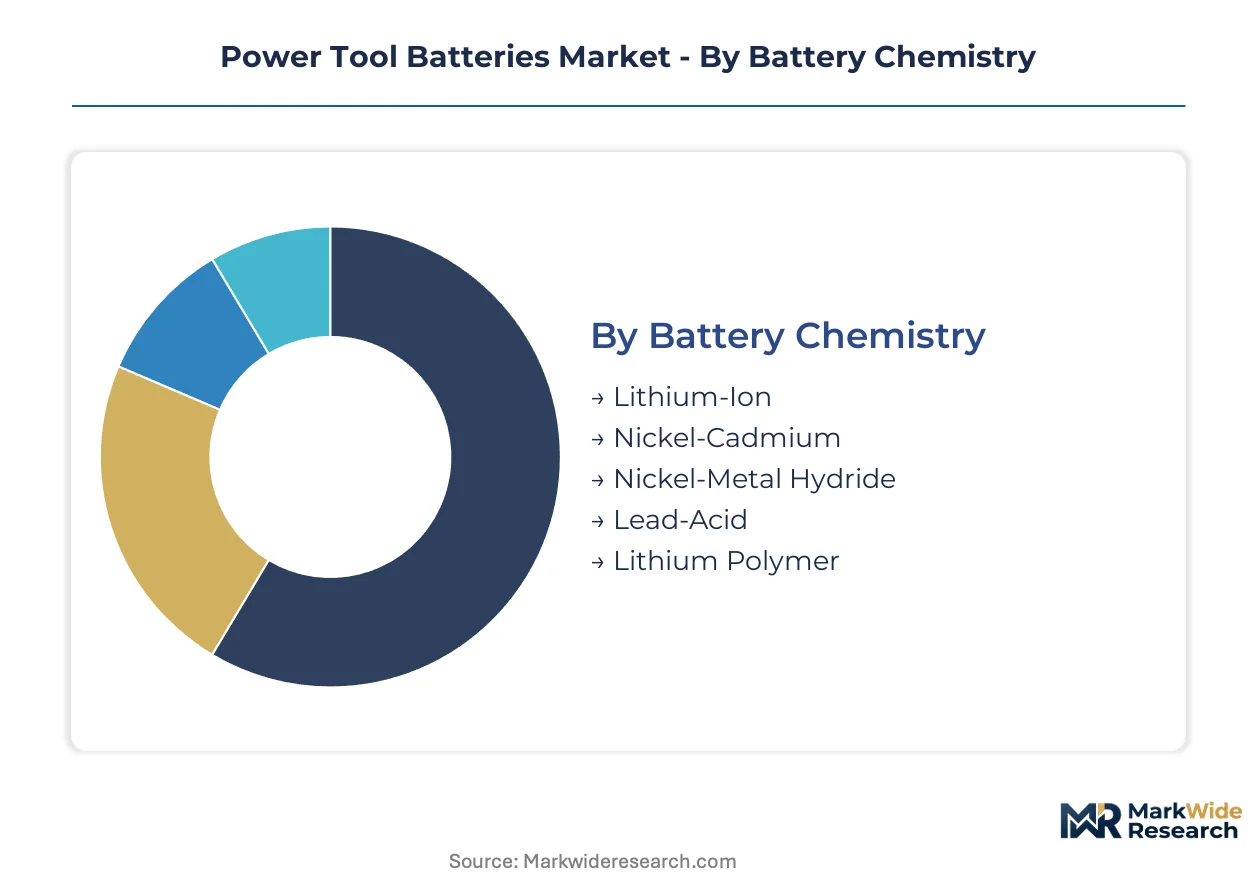
Segmentation in power tool batteries reveals how capital deployment, chemistry selection, and voltage architecture determine supplier profitability across divergent use cases. Fleet standardization pressures and regulatory chemistry mandates are compressing viable segment strategies.
Battery Chemistry:
Lithium-ion platforms demand the steepest upfront capital, requiring precision cell assembly lines and integrated battery management system firmware development.
- Lithium-Ion:Nickel-manganese-cobalt and lithium iron phosphate cathode formulations dominate professional-grade platforms. German automotive assembly plants and commercial construction fleets in the United States are consolidating procurement around this chemistry to meet EU Green Deal circular-economy mandates and IRA domestic content requirements.
- Nickel-Cadmium:Legacy chemistry retains foothold in price-sensitive replacement markets and hazardous-environment applications where thermal stability outweighs energy density. REACH substance restrictions are accelerating phase-outs across European professional fleets.
- Nickel-Metal Hydride:Intermediate chemistry serves gardening tool segments where moderate discharge rates suffice and cost positioning sits between lithium-ion and legacy alternatives.
- Lead-Acid:Stationary backup and low-cycle applications in repair workshops exploit mature recycling infrastructure and minimal cell management complexity.
- Lithium Polymer:Pouch-cell configurations enable form-factor flexibility for compact handheld tools, though cylindrical formats retain cost advantage at scale.
Lithium-ion absorbs the bulk of installed capacity; lithium iron phosphate variants within this chemistry are expanding most quickly.
Voltage Rating:
Voltage platform selection dictates thermal management investment, with higher ratings requiring advanced cell balancing and discharge protection systems.
- 18 V:The workhorse platform for cordless drills, impact drivers, and circular saws balances portability with sufficient torque for framing and finish carpentry. Professional contractors in Germany and the United States have standardized fleet procurement around this rating, compressing switching costs for multi-brand battery interoperability.
- 36 V:High-torque applications in metalworking and concrete fastening demand this architecture. Industrial maintenance crews at German automotive plants are replacing pneumatic systems with 36 V cordless platforms, pulling through demand for extended-cycle battery configurations.
- 12 V:Compact screwdriver and light-duty drilling applications favor this rating for weight minimization in overhead installation work.
- 24 V:Intermediate positioning serves specialty cutting and grinding tools where 18 V torque proves insufficient but 36 V bulk is prohibitive.
- 48 V:Heavy-duty rotary hammers and large-diameter core drills are migrating to this emerging platform. Underpenetrated concrete and masonry segments are driving pilot deployments with advanced thermal management requirements.
Eighteen-volt platforms anchor the installed base; forty-eight-volt systems are climbing the fastest as heavy-duty cordless migration accelerates.
Application:
Application segmentation maps directly to duty cycle intensity and battery replacement frequency, with construction equipment generating the highest annual throughput per tool.
- Construction Equipment:Drills, impact drivers, and saws operating across commercial job sites subject batteries to shock, vibration, and rapid cycling. Fleet standardization around interoperable charging infrastructure is concentrating demand in Germany and the United States.
- Assembly Lines:German automotive plants and aerospace manufacturing facilities deploy cordless fastening systems for ergonomic flexibility, prioritizing consistent torque output and minimal downtime.
- Gardening Tools:Chainsaws, trimmers, and blowers favor energy density for extended runtime in landscaping operations with limited charging access.
- Repair Workshops:Lower cycle intensity and intermittent use patterns extend battery service life, reducing replacement frequency versus continuous-duty construction applications.
Construction equipment absorbs the bulk of installed capacity; assembly line applications are gaining share fastest as industrial electrification displaces pneumatic systems.
End User:
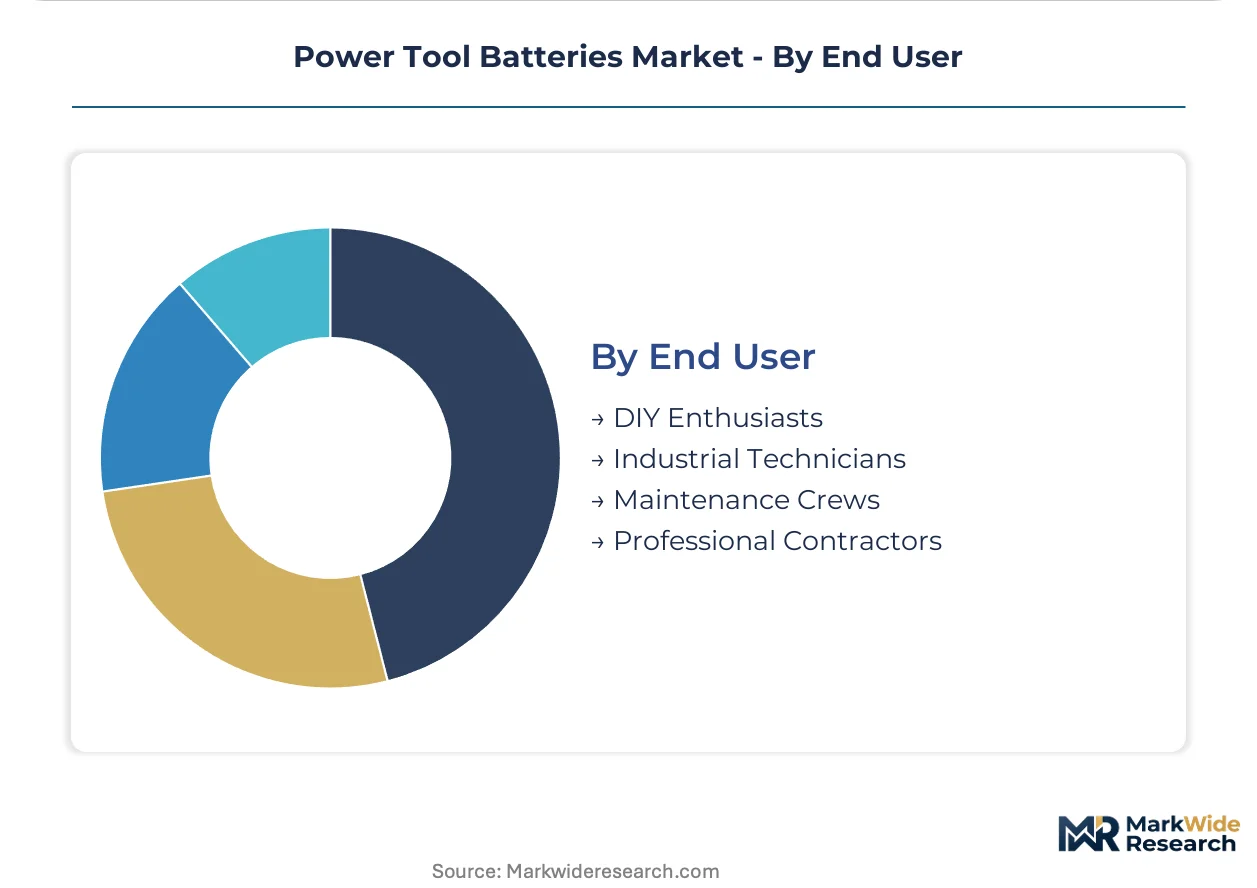
End user type determines price sensitivity, warranty expectations, and brand loyalty intensity, with professional contractors commanding the most sophisticated procurement organizations.
- Professional Contractors:Commercial construction and renovation specialists operate multi-vendor fleets requiring standardized voltage platforms and interoperable charging infrastructure. REACH compliance documentation and conflict mineral disclosure are standard procurement requirements.
- Industrial Technicians:Manufacturing facility maintenance personnel prioritize reliability metrics and predictive maintenance integration through FCC-certified diagnostic firmware.
- Maintenance Crews:Facility and infrastructure repair operations balance acquisition cost with replacement parts availability, often extending product qualification timelines.
- DIY Enthusiasts:Residential users exhibit highest price elasticity and lowest platform loyalty, fragmenting across retail channels and promotional pricing cycles.
Professional contractors absorb the bulk of installed capacity; industrial technicians are expanding most quickly as manufacturing electrification accelerates cordless tool adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturing concentrates in East Asian industrial corridors while consumption gravitates toward German automotive assembly plants and United States commercial construction sites. This geographic asymmetry shapes supply security strategies across the value chain.
Germany
Industrial maintenance crews at automotive assembly plants in Stuttgart and Wolfsburg are replacing pneumatic fastening systems with 36 V cordless platforms. EU Green Deal battery sustainability mandates under ECHA substance evaluations are accelerating cobalt phase-outs. Bavaria's industrial clusters anchor demand for high-voltage lithium-ion systems with extended cycle ratings.
United States
Professional contractors operating commercial construction fleets in Texas and California are standardizing procurement around interoperable 18 V charging infrastructure. Production tax credits under the Inflation Reduction Act are incentivizing domestic cylindrical cell assembly. The Southeast manufacturing corridor is absorbing new battery pack assembly capacity to reduce import dependency.
China
GB standards enforcement and dual carbon goals are redirecting cell production toward lithium iron phosphate formulations for export markets. Shenzhen and Dongguan manufacturing hubs control upstream cylindrical high-discharge cell output. Domestic power tool OEMs are qualifying alternative cathode chemistries ahead of anticipated REACH-equivalent substance restrictions.
Japan
METI industrial standards and JIS certification requirements are preserving premium positioning for high-discharge cylindrical cell exports. Nagoya and Osaka industrial zones maintain specialized production lines for professional-grade thermal management systems. Japanese cell suppliers are extending qualification support to European OEMs navigating ECHA compliance timelines.
South Korea
MFDS-equivalent quality frameworks and national battery R&D consortia are accelerating silicon-anode pilot programs for future 48 V platforms. Busan-Ulsan chemical industrial complexes supply electrolyte additives for high-discharge formulations. Korean cell manufacturers are securing long-term offtake agreements with German power tool brands facing REACH compliance deadlines.
Power Tool Batteries Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with captive cell supply and specialized power tool manufacturers with dense distribution networks. Tier-one positions cluster around entities combining in-house battery management system firmware development with multi-voltage platform portfolios. Two strategic archetypes dominate: vertically integrated industrial technology groups controlling upstream cell production, and cordless ecosystem specialists leveraging proprietary battery interoperability. Capacity expansion in cylindrical cell assembly and strategic recycling partnerships constitute the dominant competitive moves across both archetypes.
Among diversified industrial technology groups, Robert Bosch GmbH and Panasonic Holdings Corp. occupy positions anchored by upstream manufacturing capabilities and integrated supply chain control. Makita Corporation exemplifies the cordless ecosystem specialist archetype, representing the dealer-network-intensive competitive vector where proprietary battery platforms drive fleet attachment. Samsung SDI Co. Ltd. sits within the upstream cell supplier tier, controlling critical nodes in the value chain through high-discharge cylindrical cell output to multiple OEMs.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Stanley Black & Decker Inc. |
| Makita Corporation |
| Techtronic Industries Company Limited |
| Samsung SDI Co. Ltd. |
| Panasonic Holdings Corp. |
| Hilti AG |
| Milwaukee Tool |
| DeWalt |
| Others |
Value Chain & Pricing Dynamics
Performance-grade certification divergence between UL-listed industrial packs and uncertified consumer alternatives manifests in both procurement premiums and supplier qualification depth, with REACH-compliant cobalt-reduced formulations commanding longer lead times from qualified European assemblers.
Pricing Analysis
Cost-down pressure on standard 18 V platforms accelerates as Chinese cylindrical cell exports undercut Korean and Japanese alternatives by fifteen to twenty percent at equivalent discharge specifications. Three-tier pricing structure across premium, standard, and economy levels separates Bosch and Makita fleet contracts from mid-tier private-label packs and unbranded replacement cells. Price differentiation traces to ECHA compliance documentation and FCC-certified diagnostic firmware integration. DIY enthusiasts exhibit highest price elasticity, while German automotive maintenance crews absorb premiums for extended-cycle 36 V configurations.
Supply Chain Analysis
Skilled technician shortages in Shenzhen and Dongguan assembly corridors constrain cylindrical cell output expansion despite automated winding equipment deployment. Upstream production concentrates in China, South Korea, and Japan, with electrolyte additive synthesis anchored in Busan-Ulsan chemical complexes. Raw material flows draw from Chilean lithium carbonate, Indonesian nickel matte, and DRC cobalt hydroxide. Single-source vulnerability concentrates in high-discharge separator films sourced from Japanese specialty manufacturers. Distribution runs through authorized dealer networks for professional-grade platforms, while retail channels fragment consumer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal chemistry mandates and IRA domestic content rules are consolidating supplier tiers, eliminating pack assemblers lacking backward-compatible firmware architectures or qualified recycling partnerships.
For Market Incumbents: Anchor fleet retention through proprietary battery interoperability investments that lock professional contractors into multi-voltage charging ecosystems. Defend against emerging silicon-anode specialists by accelerating 48 V thermal management qualifications ahead of solid-state pilot scale. Prioritize captive recycling partnerships with German energy cooperatives to secure circular-economy procurement tender access.
For New Entrants and Emerging Players: Enter via 48 V heavy-duty concrete applications where incumbent firmware legacy burdens delay platform refreshes. Target German commercial construction rental chains expanding multi-brand battery lending pools with standardized cell form factors. Pursue white-label supply agreements with mid-tier OEMs seeking dual-chemistry portfolios to hedge REACH formulation obsolescence.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated industrial technology groups given Inflation Reduction Act production tax credit eligibility and upstream cell manufacturing scarcity. Long-term viability favors entities combining in-house battery management system development with multi-regional assembly footprints. Monitor ECHA substance evaluation timelines as inflection indicators for lithium iron phosphate chemistry acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward-Compatible Firmware Architecture Investment | Preserves fleet attachment rates across multi-generational professional tool platforms. |
| Circular-Economy Recycling Partnership | Qualifies suppliers for EU Green Deal procurement tenders in German automotive clusters. |
| Domestic Cylindrical Cell Assembly Scale-Up | Captures Inflation Reduction Act production tax credits for US power tool OEMs. |
| Silicon-Anode Qualification Program | Positions suppliers for 48 V heavy-duty platform migration ahead of solid-state timelines. |
| Multi-Brand Charging Infrastructure Deployment | Fragments OEM attachment rates through German rental chain standardization. |
Study Parameters
Multi-period observation of cell chemistry transitions, voltage platform adoption curves, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with battery pack engineering directors, procurement leads at German automotive OEMs, power tool dealer network managers, and ECHA regulatory affairs specialists. Secondary validation drew from customs trade data, SEC 10-K filings, EU battery regulation implementation documents, and production tax credit disclosure filings. Bottom-up cell shipment estimates triangulated against top-down power tool OEM revenue attribution.
Segment-weighting across chemistry type, voltage rating, and end-user archetype informed volume and value allocation through the projection horizon. CAGRs were derived from fitted growth curves calibrated to observed fleet replacement cycles and industrial electrification adoption rates. Forecast inputs incorporated lithium carbonate price elasticity coefficients and REACH compliance timeline friction factors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium raw material supply disruptions or accelerated ECHA cobalt restriction schedules. Projections reflect assumptions around cell manufacturing subsidy continuity and professional contractor fleet standardization momentum. Material deviation in IRA production tax credit renewal or solid-state chemistry commercialization timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
FORTELION Battery Module Market
Batteries
Grid-Scale Battery Market
Batteries
India Alkaline Battery Market
Batteries
Forklift Battery Market
Batteries
Industrial Backup Battery Market
Batteries
48 Volt Battery System Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
South America Battery Cell Market
Batteries
Nickel Cadmium Battery Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
Custom Battery Pack Market
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
South Africa Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
Zinc-Manganese Oxide Printed Battery Market