
 United States Thermal Power Market | 2026-2036
United States Thermal Power Market Size, Share, and Industry Trends Forecast 2026-2036
United States Thermal Power Market Analytics
Ultra-supercritical steam conditions above 600°C and 30 MPa is redrawing competitive benchmarks for heat rate efficiency and emissions intensity. Southern Company sustains technology leadership through integrated gasification and carbon capture development at its Mississippi power plant. Duke Energy anchors Southeast market share through regulated utility scale and nuclear-thermal hybrid operations. NextEra Energy navigates the Florida and Texas markets with combined-cycle natural gas fleets that compete directly against renewable entrants.
United States thermal power encompasses combustion-based electricity generation from fossil and biomass fuels, utilizing steam turbines, gas turbines, or combined-cycle configurations operating at thermal efficiencies ranging from 33 percent for subcritical coal to over 60 percent for advanced combined-cycle natural gas plants. Natural gas technology leads new capacity additions due to low fuel costs and flexible dispatch, while coal-fired units above 1000 MW face accelerated retirement pressure under tightening environmental rules. The utilities end user segment commands the largest revenue pool through regulated rate-base expansion, though industrial cogeneration applications represent the fastest-growing application category as refineries and chemical plants seek thermal efficiency.
EPA Clean Air Act enforcement and FERC grid reliability standards shape plant retrofit timelines and retirement decisions across the national fleet. NERC mandatory reliability standards impose operational constraints that preserve certain baseload units even where economics favor closure. State-level public utility commissions in Texas, California, and New York layer additional siting and emissions requirements that fragment permitting timelines. Stakeholders must weigh stranded asset risk against reliability premiums as dispatch economics shift with renewable penetration and battery duration limits.
Market Dynamics
Ultra-supercritical steam conditions above 600°C and 30 MPa are compressing heat rate benchmarks across the national fleet, forcing operators to choose between costly retrofits and accelerated retirement timelines under tightening EPA emissions enforcement.
Growth Catalysts
- Data Center Load Expansion:Hyperscale facilities in Northern Virginia and Texas are pulling baseload demand upward, creating firm capacity requirements that renewable-plus-storage configurations cannot yet satisfy.
- IRA Tax Credits:The Inflation Reduction Act's clean hydrogen production incentives are enabling coal-to-gas switching with carbon capture retrofits at existing thermal sites.
- Combined-Cycle Efficiency:Advanced natural gas turbines achieving thermal efficiencies above 60 percent are outcompeting older coal units on dispatch economics alone.
Market Restraints
- Natural Gas Price Volatility:Henry Hub fluctuations compress operating margins for gas-fired baseload operators, exposing merchant plants to negative spark spreads during shoulder months.
- EPA Cross-State Air Pollution Rule:The updated CSAPR ozone season NOx trading program imposes compliance costs that accelerate retirement timelines for unscrubbed coal units in the Midwest and Southeast.
- Renewable Substitution:Utility-scale solar-plus-battery hybrids in ERCOT and CAISO are capturing peak pricing hours that historically sustained combined-cycle economics.
Strategic Opportunities
- Industrial Cogeneration:Refineries and chemical plants along the Gulf Coast are deploying combined heat and power systems to capture thermal efficiency premiums under state energy intensity mandates.
- Hydrogen Co-Firing:Gas turbine OEMs are certifying frames for 30 percent hydrogen blends, opening retrofit pathways for existing combined-cycle assets seeking carbon intensity reductions.
- Carbon Capture Retrofits:Section 45Q credits are financing post-combustion capture installations at coal and gas units in the Permian Basin, where CO2 offtake agreements with enhanced oil recovery operators provide revenue certainty.
Industry Challenges
- Control Systems Integration:Retrofitting digital turbine controls into 1980s-era analog plants requires specialized commissioning expertise that has aged out of the workforce in the Midwest manufacturing belt.
- NERC CIP Compliance:Mandatory cybersecurity standards for bulk electric system assets impose documentation and audit burdens that strain operational budgets at smaller municipal utilities.
- Welding Certification Bottlenecks:ASME Section IX-qualified welders for high-pressure steam piping are in short supply, extending outage durations and compressing availability factors during peak demand periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Thermal Power Market |
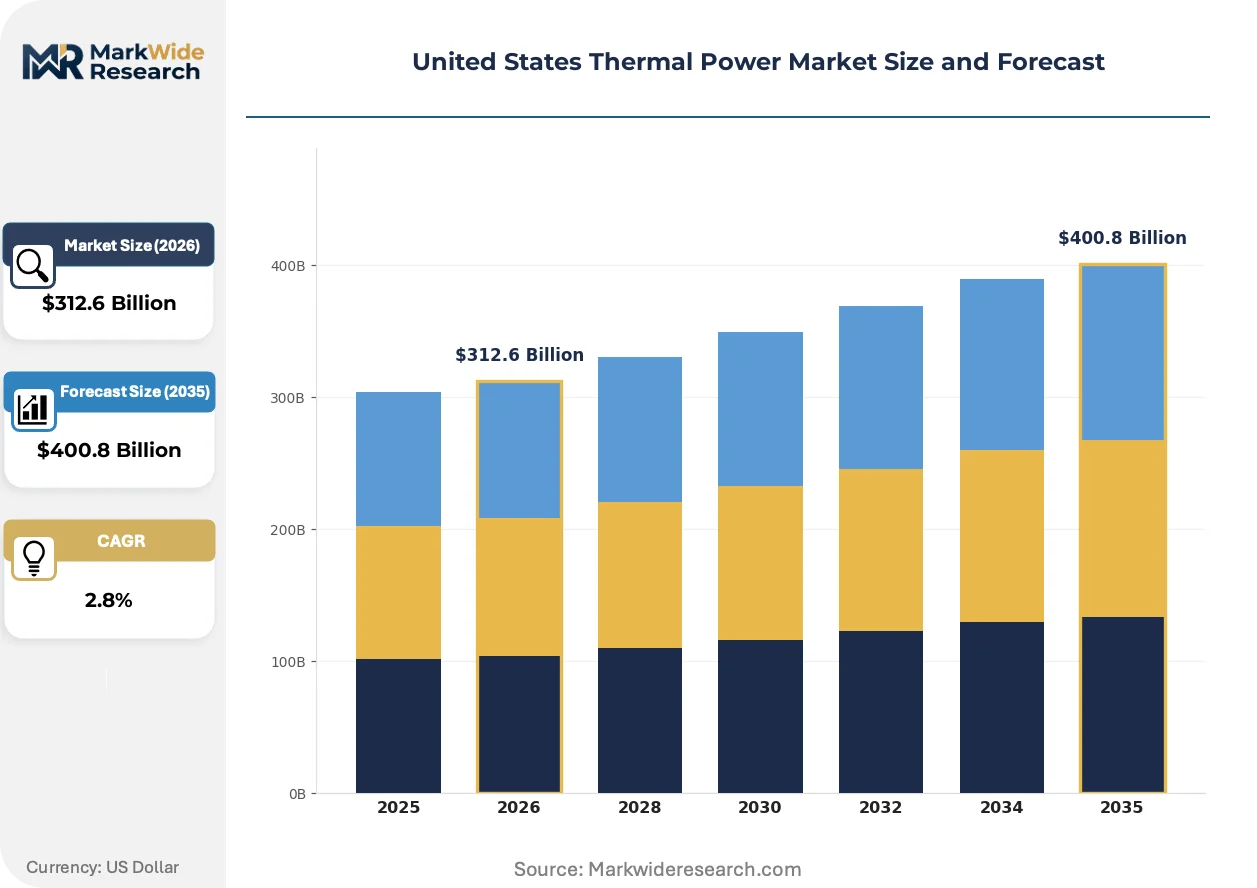
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $400.8 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Coal, Natural Gas, Oil, Biomass End User: Industrial, Commercial, Residential, Utilities Application: Electricity Generation, Heating, District Energy, Cogeneration Capacity: Up to 100 MW, 101-500 MW, 501-1000 MW, Above 1000 MW |
| Companies Covered | Southern Company, Exelon Corporation, NextEra Energy, Inc., Public Service Enterprise Group Inc., Xcel Energy Inc., Dominion Energy, Inc., American Electric Power Company Inc., Contura Energy, Inc., Duke Energy Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Thermal Power Market Evolving Landscape
Dispatch economics are fragmenting across interconnection zones as renewable penetration compresses capacity factors for thermal assets, forcing operators to pivot from baseload to flexible cycling roles.
Advanced ultra-supercritical steam cycles operating at 620°C and 31 MPa are supplanting subcritical coal units in the Southeast, where Southern Company and Duke Energy are deploying A-USC technology to extend regulated rate-base life while meeting state carbon reduction mandates. These plants achieve heat rates below 8,500 Btu per kWh, enabling dispatch competitiveness against combined-cycle gas even at elevated coal prices. The technology is compressing the economic window for unscrubbed coal retirement by a decade in regulated jurisdictions.
EPA's proposed Good Neighbor Plan for ozone transport is tightening NOx emission limits across 23 states, forcing coal and gas operators to install selective catalytic reduction systems or face seasonal operating restrictions. The rule's 2026 compliance timeline is accelerating retrofit procurement cycles for catalyst and ammonia handling infrastructure. Merchant generators in PJM are responding by filing for capacity market exemptions while negotiating reliability-must-run agreements with grid operators.
Data center operators are contracting directly for firm thermal capacity through virtual power purchase agreements that bypass traditional utility intermediaries. This channel disintermediation is visible in Northern Virginia, where Amazon Web Services and Microsoft have secured dedicated combined-cycle output from Dominion Energy and Calpine facilities. The model transfers dispatch risk to hyperscale buyers while securing revenue certainty for plant developers facing renewable competition.
United States Thermal Power Market Segmentation
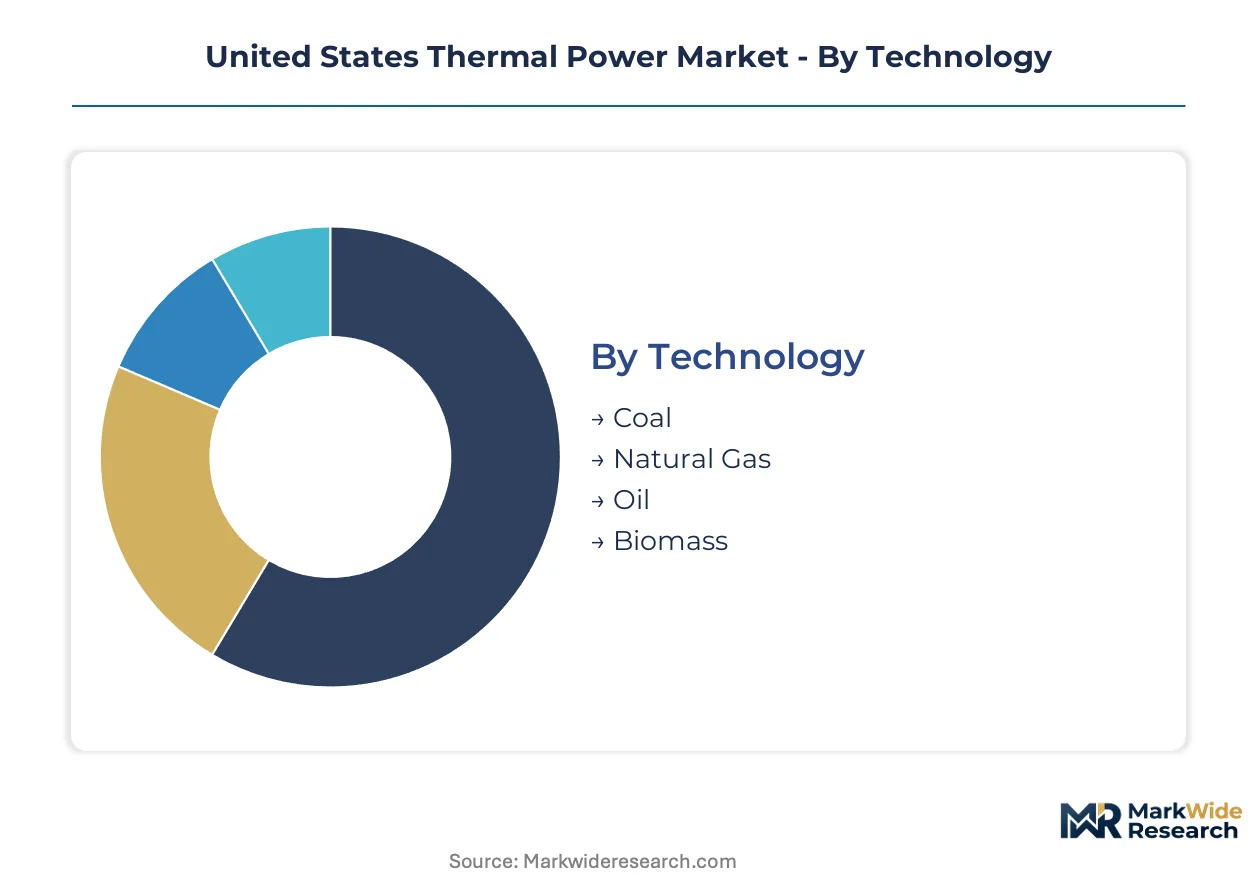
Thermal power market segmentation reveals divergent fates across technology and scale categories. EPA emissions enforcement and renewable substitution pressures hit each segment asymmetrically, reshaping investment priorities and retirement timelines.
Technology:
Natural gas technology faces the most intense substitution pressure from solar-plus-battery hybrids, while coal confronts regulatory-driven obsolescence.
- Natural Gas:Combined-cycle configurations achieve thermal efficiencies exceeding 60 percent through advanced turbine aerodynamics and heat recovery steam generation. Demand concentrates in Texas ERCOT and PJM Interconnection zones where data center load growth outpaces renewable firming capabilities.
- Coal:Subcritical and supercritical steam cycles operate at 540-600°C with heat rates of 8,500-10,000 Btu per kWh, requiring expensive scrubber retrofits for EPA compliance. Midwest and Southeast utilities are accelerating retirement timelines for unscrubbed units above 500 MW.
- Oil:Distillate and residual fuel turbines serve peaking roles in ISO-NE and NYISO where gas pipeline constraints create winter reliability premiums.
- Biomass:Wood pellet and agricultural waste cofiring operates at smaller scale in Maine and the Pacific Northwest under state renewable portfolio carve-outs.
Natural gas anchors the volume base while biomass gains share at the steepest rate through state-level decarbonization mandates.
End User:
Cost tier differentiation separates regulated utilities with rate-base certainty from merchant generators exposed to wholesale price volatility.
- Utilities:Investor-owned and public power entities deploy thermal assets under cost-of-service regulation, recovering capital through approved rate-base mechanisms. PJM and ERCOT utilities dominate new combined-cycle procurement to serve data center load growth.
- Industrial:Refineries and chemical plants along the Gulf Coast operate captive cogeneration systems capturing steam and electricity output for process heat applications. Texas and Louisiana facilities lead capacity additions under state energy efficiency mandates.
- Commercial:Universities and hospital systems deploy district heating plants in urban cores where thermal load density justifies centralized generation over distributed alternatives.
- Residential:Small-scale oil and gas heating systems serve backup and remote applications in rural New England and Alaska where grid extension costs exceed distributed thermal economics.
Utilities command the largest revenue pool while industrial end users expand most quickly through Gulf Coast petrochemical buildout.
Application:
Geographic clustering shapes application viability, with electricity generation concentrated in transmission-constrained regions and cogeneration following industrial corridor development.
- Electricity Generation:Baseload and intermediate dispatch services operate across all major interconnections, with capacity factors compressing under renewable penetration in CAISO and ERCOT.
- Cogeneration:Combined heat and power systems achieve 70-80 percent total system efficiency by capturing waste heat for industrial processes or district heating loops. Gulf Coast refineries and Northeast urban centers anchor deployment.
- Heating:Direct combustion for space and process heat serves seasonal loads in northern climates where electrification costs remain prohibitive.
- District Energy:Centralized thermal distribution networks operate in Minneapolis, Boston, and Seattle where dense building stock and legacy infrastructure support steam loop economics.
Electricity generation retains the dominant share while cogeneration climbs fastest through industrial decarbonization incentives.
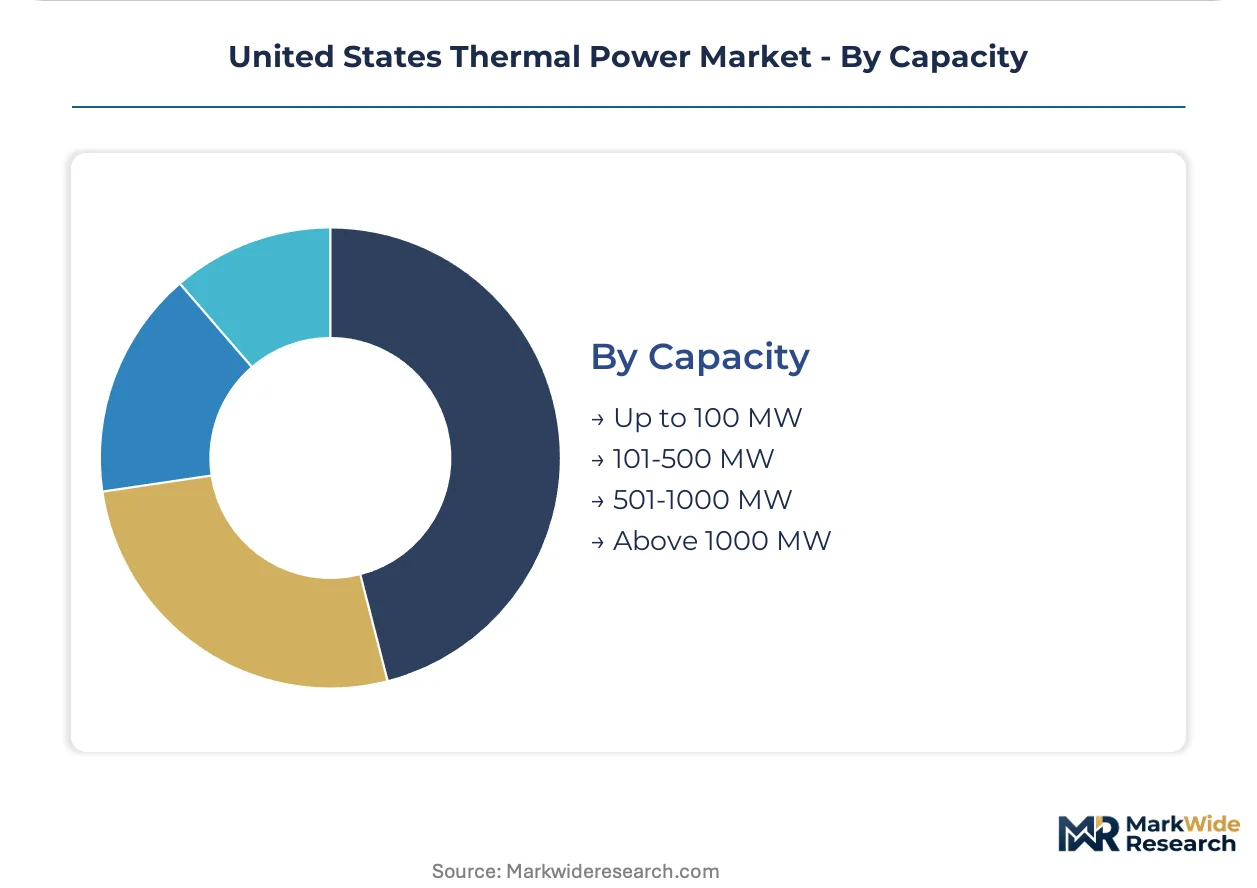
Capacity:
Scale economies and unit flexibility create distinct competitive positions across the megawatt spectrum, with mid-scale units facing the most acute margin pressure.
- Above 1000 MW:Supercritical and ultra-supercritical coal units face accelerated retirement under EPA Good Neighbor Plan enforcement despite sunk capital costs.
- 501-1000 MW:Large combined-cycle blocks dominate new build programs in Texas and Virginia, optimized for baseload data center contracts.
- 101-500 MW:Mid-scale gas turbines and coal units serve cycling roles but face margin compression from renewable peak shaving.
- Up to 100 MW:Aeroderivative turbines and reciprocating engines provide fast-start flexibility for grid balancing in renewable-heavy zones.
501-1000 MW units anchor the volume base while up to 100 MW systems gain share fastest through distributed energy resource integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States thermal power market operates as a largely self-contained system with minimal cross-border electricity trade, though equipment and fuel supply chains draw from international sources. Domestic generation capacity expansion concentrates in states with favorable siting regulations and proximity to demand centers.
Texas
ERCOT's isolated grid attracts merchant developers seeking price volatility exposure. The Inflation Reduction Act's hydrogen production credits support coal-to-gas switching with carbon capture retrofits along the Gulf Coast. Houston and the Permian Basin anchor industrial cogeneration buildout serving refineries and chemical plants.
Virginia
Northern Virginia's data center corridor drives baseload demand growth exceeding renewable firming capabilities. Dominion Energy deploys combined-cycle capacity under state-approved rate-base mechanisms. Loudoun County and Prince William County concentrate hyperscale facility development requiring dedicated thermal capacity contracts.
Pennsylvania
PJM Interconnection reserve margin tightening preserves coal and gas units despite environmental compliance costs. EPA Cross-State Air Pollution Rule enforcement accelerates selective catalytic reduction installations at legacy plants. Pittsburgh and Philadelphia metropolitan areas sustain district heating networks from centralized thermal infrastructure.
Florida
NextEra Energy's regulated utility scale anchors Southeast market share through nuclear-thermal hybrid operations. State public utility commission approvals enable rate-base recovery for efficiency retrofits. Tampa and Orlando urban cores maintain combined-cycle gas turbines optimized for cooling-dominated load profiles.
Illinois
Exelon Corporation's nuclear-thermal fleet operates under FERC grid reliability standards preserving certain baseload units. NERC mandatory reliability standards impose operational constraints where economics favor closure. Chicago's district energy system and Rockford industrial corridor sustain cogeneration applications under state energy intensity mandates.
United States Thermal Power Market Competitive Landscape
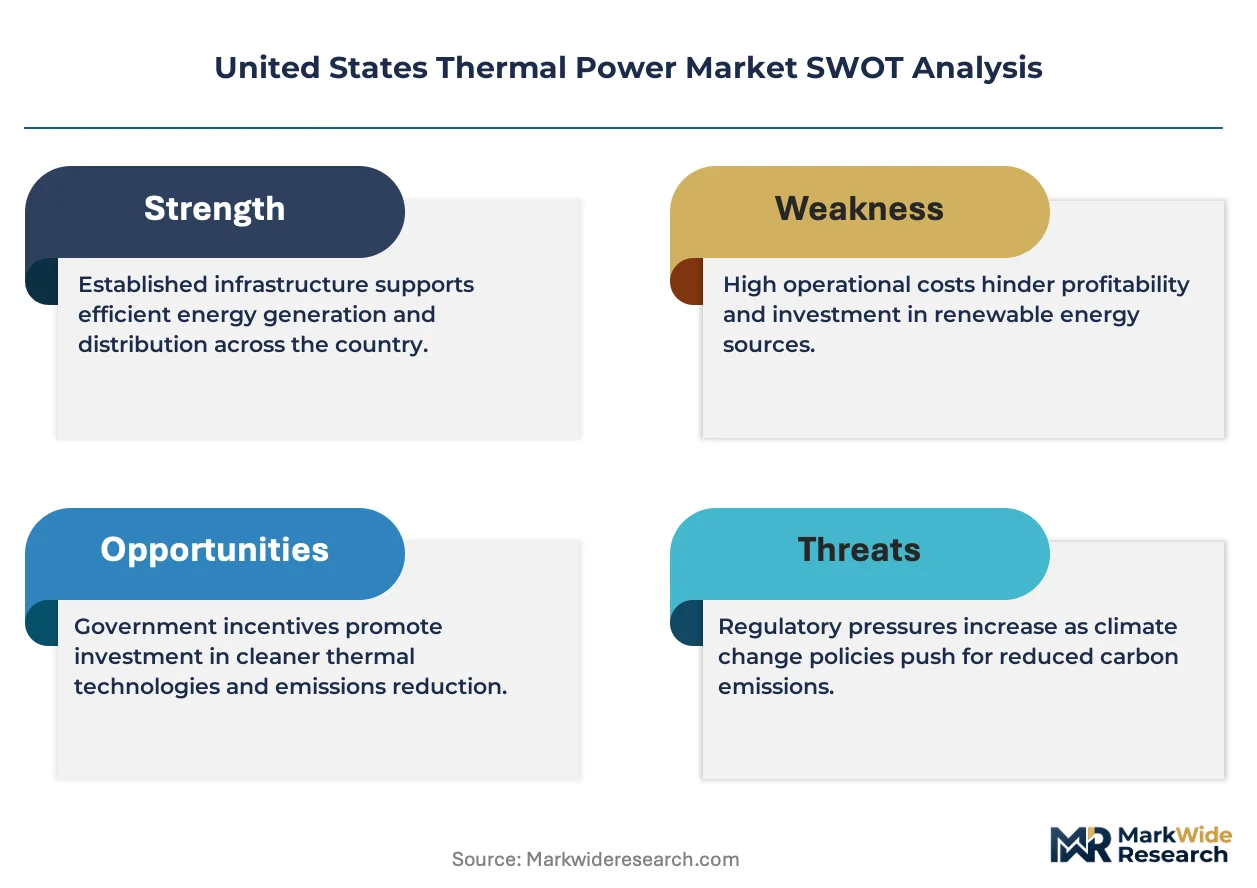
Concentration sits with regulated investor-owned utilities possessing rate-base certainty and scale economies in combined-cycle procurement. The competitive structure divides between vertically integrated utilities with captive generation and merchant generators exposed to wholesale price volatility. Strategic archetypes include regulated rate-base expanders, renewable-thermal hybrid operators, and industrial cogeneration specialists. Dominant competitive moves center on portfolio diversification into carbon capture retrofits and direct power purchase agreements with data center operators.
Among regulated utility holding companies, Southern Company, Duke Energy Corporation, and NextEra Energy, Inc. exemplify the rate-base expansion archetype. Southern Company occupies a position within the integrated gasification technology tier. Duke Energy Corporation sits within the nuclear-thermal hybrid operator category. NextEra Energy, Inc. represents the renewable-thermal balancing strategy in Florida and Texas markets. These three entities anchor competitive positioning through scale-driven procurement and state regulatory relationships.
| Leading Market Players |
|---|
| Southern Company |
| Exelon Corporation |
| NextEra Energy, Inc. |
| Public Service Enterprise Group Inc. |
| Xcel Energy Inc. |
| Dominion Energy, Inc. |
| American Electric Power Company Inc. |
| Contura Energy, Inc. |
| Duke Energy Corporation |
| Others |
Value Network & Pricing Analysis
Natural gas displacement of coal feedstock simultaneously redraws fuel sourcing geography and compresses dispatch pricing differentials across ISO interconnection zones. Henry Hub price volatility transmits directly into merchant generator margins while regulated utilities recover fuel costs through rate-base mechanisms.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for turbine and boiler equipment, with pricing stratifying across ultra-supercritical, supercritical, and subcritical performance tiers. Price differentiation rests on ASME certification grade and heat rate efficiency guarantees. Cost compression in mid-scale combined-cycle segments intensifies because renewable-plus-battery hybrids capture peak pricing hours. Merchant generators exhibit highest price sensitivity due to exposed spark spreads, while regulated utilities with approved fuel adjustment clauses maintain lowest sensitivity.
Supply Chain Analysis
Germany, Japan, and the United States anchor gas turbine manufacturing and high-pressure steam component fabrication. Raw material dependencies draw from specialty steel alloys, precision castings, and advanced ceramic coatings. Single-source vulnerability concentrates in superalloy forging capacity for turbine blades. Distribution runs through original equipment manufacturer direct sales for utility-scale projects and specialized EPC integrators for industrial cogeneration deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASME Section IX-qualified welding expertise for high-pressure steam piping has aged out of the Midwest workforce, creating execution risk for outage schedules and retrofit timelines. This capability gap constrains fleet modernization velocity regardless of capital availability.
For Market Incumbents: Consolidate control over specialized commissioning expertise through captive training programs or exclusive contractor relationships. Secure rate-base approval for carbon capture retrofits before EPA Good Neighbor Plan compliance deadlines tighten. Vertical integration into ammonia handling infrastructure for selective catalytic reduction systems defends margin position against merchant generator cost pass-through limitations. For New Entrants and Emerging Players: Differentiate on fast-start aeroderivative turbine packages for ERCOT grid balancing services. Target industrial cogeneration white space along the Texas and Louisiana Gulf Coast petrochemical corridor. Pursue direct power purchase agreement structures with hyperscale data center operators that bypass traditional utility intermediaries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed merchant generators holding stranded coal capacity in PJM and MISO. Long-term viability hinges on successful coal-to-gas switching with carbon capture retrofit execution. Watch FERC capacity market rulemaking as the inflection signal for stranded asset risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Deployment | Section 45Q credit monetization with Permian Basin CO2 offtake agreements anchors project finance. |
| Hydrogen Co-Firing Certification | Gas turbine OEM blend limits determine residual asset life under state decarbonization mandates. |
| Data Center Direct PPA Structuring | Virtual power purchase agreements with Amazon Web Services and Microsoft transfer dispatch risk. |
| Industrial Cogeneration Expansion | Gulf Coast refinery steam demand captures thermal efficiency premiums under Louisiana energy intensity rules. |
| NERC CIP Compliance Automation | Cybersecurity documentation burdens strain municipal utility operational budgets without scale economies. |
Research Methodology
Desk research of EIA generation statistics, FERC interconnection queue filings, and EPA enforcement records preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork captured plant-level retirement and retrofit timelines across PJM, ERCOT, and CAISO zones. Secondary validation drew from NERC reliability assessments, state public utility commission dockets, and equipment manufacturer technical specifications. Bottom-up unit-level capacity modeling triangulated against top-down interconnection demand forecasts.
Variance decomposition across fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type shaped the analytical framework. CAGRs were derived from segmented unit economics modeling and interconnection queue velocity analysis across the projection horizon. Forecast inputs incorporated IRA tax credit phase-out schedules and EPA emissions rule compliance timelines without year-specific anchoring.
The analysis sits within stated boundaries; outcomes outside sustained natural gas price stability or accelerated renewable storage duration improvements would require recalibration. Forecasts reflect assumptions about state renewable portfolio standard stringency and FERC capacity market design evolution. Recalibration cycles align with material shifts in EPA enforcement posture and data center load growth trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Thermal Energy Storage
China Thermal Power Plant Market
Thermal Energy Storage
Europe Thermal Energy Storage Market
Thermal Energy Storage
Thermal Energy Storage (TES) Market
Thermal Energy Storage
North America Thermal Energy Storage Market
Thermal Energy Storage
Africa Thermal Energy Storage Market
Thermal Energy Storage
Middle-East and Africa Thermal Power Market
Thermal Energy Storage
Molten Salt Thermal Energy Storage (TES) Market
Thermal Energy Storage
North America Thermal Power Market
Thermal Energy Storage
Southeast Asia Thermal Power Market
Thermal Energy Storage
Thermal Recovery Market
Thermal Energy Storage
Asia-Pacific Thermal Energy Storage Market
Thermal Energy Storage
Solar Thermal Fuel Market
Thermal Energy Storage
Europe District Heating Market
Thermal Energy Storage
Russia Thermal Power Market
Thermal Energy Storage
Ice Thermal Storage Systems Market