
 Europe Thermal Energy Storage Market | 2026-2036
Europe Thermal Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Thermal Energy Storage Market Analytics
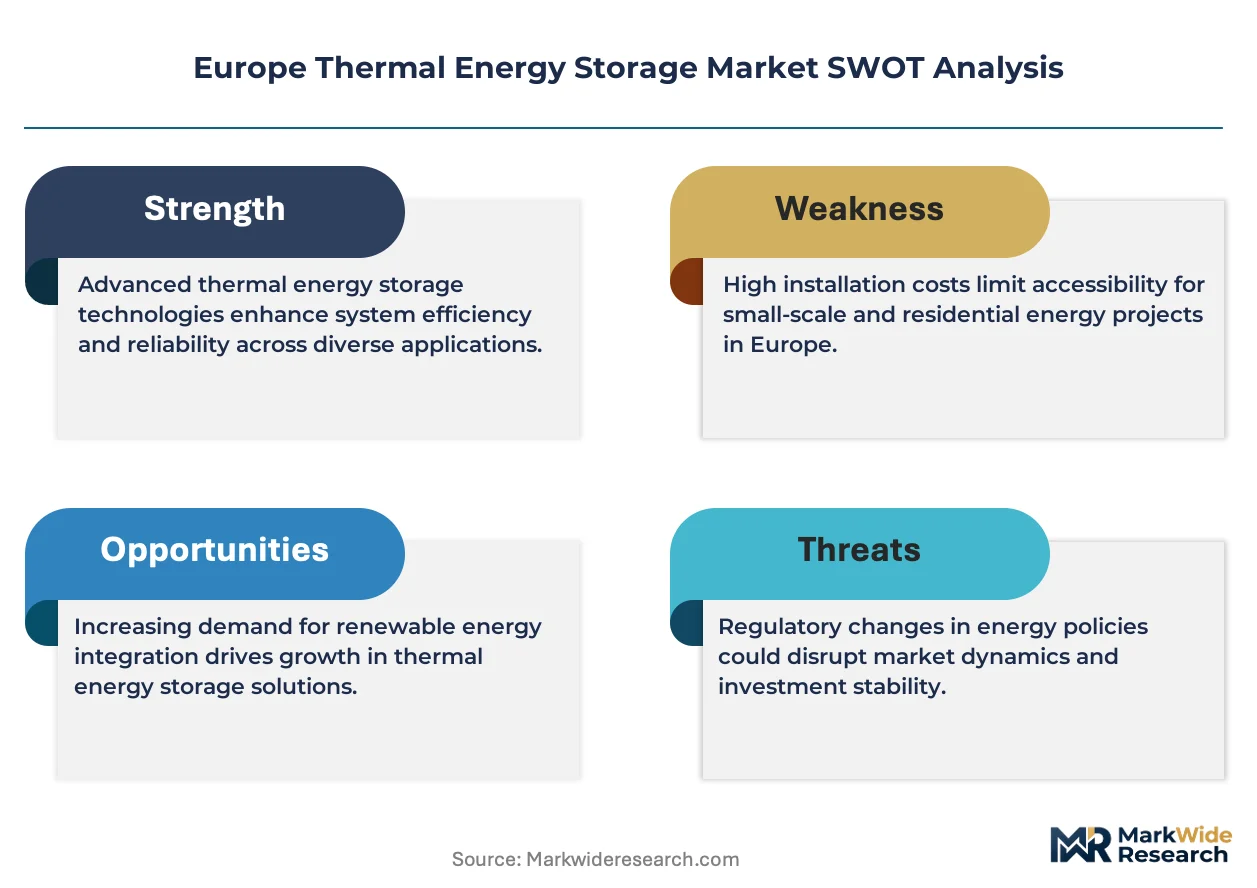
The EU Green Deal is pivoting the cost-of-entry calculus for thermal storage developers across Europe. Abengoa leverages its concentrated solar power heritage to dominate molten salt project pipelines in Spain. EnergyNest anchors its position through patented concrete-based storage modules designed for industrial heat recovery. Baltimore Aircoil Company competes in the commercial segment with advanced ice-based thermal batteries for peak shaving applications.
Thermal energy storage encompasses systems that capture heat or cold in a medium—molten salt at 220–550°C, phase change materials with defined fusion enthalpies, or pressurized water tanks—and discharge it on demand to balance supply-load mismatches. These systems decouple energy generation from consumption, enabling renewable integration and grid stabilization. Molten salt technology leads in utility-scale installations due to proven cycling stability above 500°C, while latent heat storage via phase change materials is expanding fastest in residential retrofits where space constraints favor compact enthalpy density. Sensible heat storage in water tanks remains the mature baseline for district heating networks across Northern Europe.
EMA guidelines on industrial emissions, REACH chemical safety protocols for PCM formulations, and the EU F-Gas Regulation restricting synthetic refrigerants collectively shape product standards and market access for thermal storage suppliers. The EU AI Act's emerging energy efficiency reporting requirements will further tighten compliance for smart-controlled storage systems. Stakeholders must monitor how the CSRD's scope-three disclosure rules reshape procurement criteria for large industrial heat users sourcing storage equipment.
Market Dynamics
The EU Green Deal's building renovation mandates are compressing payback periods for thermal storage retrofits, forcing developers to reengineer phase change material formulations for tighter spatial envelopes in existing building stock.
Growth Catalysts
- EU Green Deal renovation mandates:The directive accelerates latent heat storage deployment in residential retrofits across Germany, Spain, and Italy.
- District heating network expansion:Scandinavian utilities are adding molten salt buffer capacity to balance wind and solar intermittency in Copenhagen, Stockholm, and Helsinki.
- F-Gas Regulation phase-down:Synthetic refrigerant restrictions are pushing commercial cooling toward ice-based thermal batteries for peak shaving.
Market Restraints
- PCM raw material concentration:Paraffin and salt hydrate supply chains concentrate in German and Dutch chemical clusters, creating input cost volatility.
- REACH compliance burden:ECHA registration requirements for novel phase change material formulations extend commercialization timelines.
- Natural gas price arbitrage:Compressed European gas pricing post-crisis reduces the operating cost advantage of thermal storage against direct combustion heating.
Strategic Opportunities
- Eastern European district heating:Poland and Czech Republic networks remain underpenetrated by large-scale sensible heat storage.
- Industrial waste heat recovery:Steel and cement plants in Spain and Italy are piloting concrete-based storage modules for process heat recapture.
- CSRD scope-three disclosure:The mandate is reshaping procurement criteria for industrial heat users sourcing storage equipment.
Industry Challenges
- Thermal systems engineering talent:Expertise in high-temperature molten salt system design concentrates in Spanish and German research institutes.
- Legacy building integration:Retrofitting phase change materials into pre-1990 building envelopes requires structural assessment protocols that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Thermal Energy Storage Market |
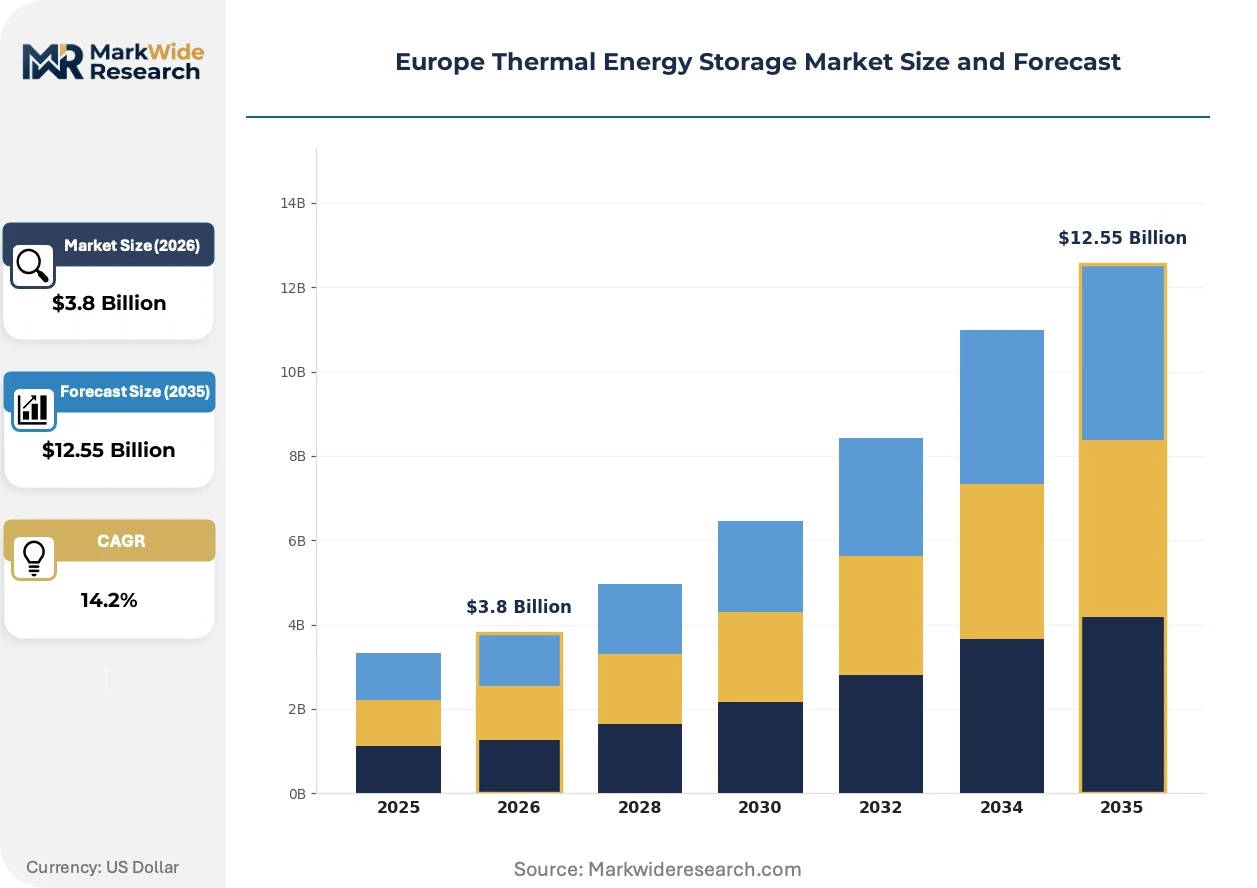
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Molten Salt, Phase Change Materials, Water Tank, Aggregated Thermal Storage Technology: Thermal Batteries, Sensible Heat Storage, Latent Heat Storage, Thermochemical Storage End User: Industrial, Residential, Commercial, Utilities Installation: On-Premises, Centralized, Decentralized, Hybrid Systems |
| Companies Covered | Abengoa, Baltimore Aircoil Company, Steffes, Evapco, Caldwell Energy Company, BrightSource Energy, Terrafore Technologies, Dunham Bush, EnergyNest, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Thermal Energy Storage Market Evolving Landscape
Materials science advances and digital control architectures are converging to expand the operating temperature envelope and discharge precision of thermal storage systems deployed across European industrial and built environments.
Phase change materials with engineered fusion enthalpies are integrating into compact residential storage units. German and Austrian housing associations are specifying these systems for multi-family retrofits where floor space constraints exclude water tanks. The technology is integrating latent heat density with conventional hydronic distribution, compressing equipment footprints by half against sensible heat alternatives.
The EU AI Act's emerging energy efficiency reporting requirements are tightening compliance for smart-controlled storage systems. Manufacturers must now document algorithmic decision-making in demand-response dispatch protocols. Spanish and Italian utilities deploying grid-interactive thermal storage face the steepest adaptation costs due to legacy control system architectures.
Industrial heat buyers are consolidating supplier relationships around turnkey performance contracts rather than equipment-only procurement. German chemical processors and Nordic pulp mills are leading this shift, bundling storage system design with guaranteed heat delivery metrics. Eastern European manufacturing clusters lag in this transition, retaining fragmented equipment sourcing patterns.
Europe Thermal Energy Storage Market Segmentation
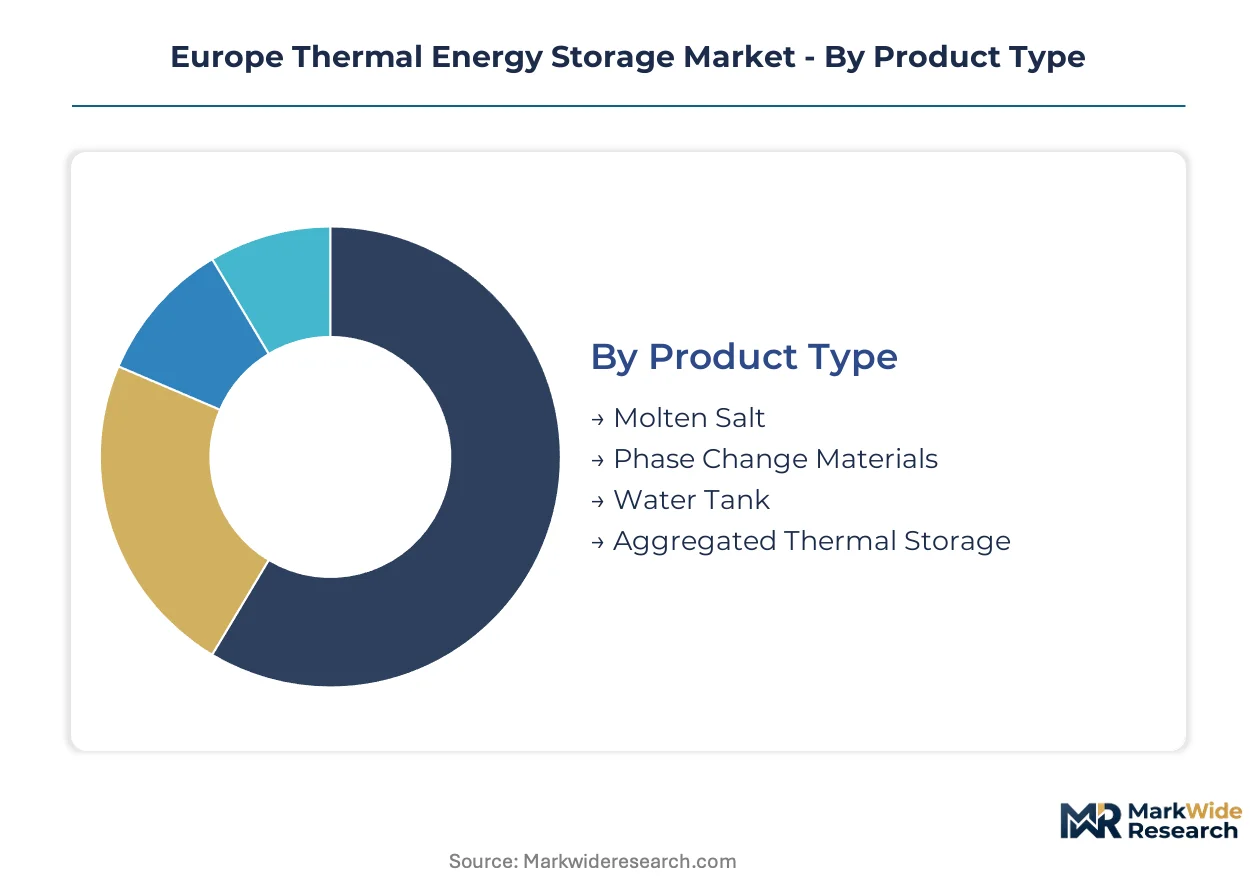
Thermal storage deployments diverge sharply between standalone installations and embedded building systems across Europe. Product selection hinges on temperature requirements, spatial constraints, and integration complexity with existing infrastructure.
Product Type:
Molten salt systems dominate utility-scale standalone installations, while phase change materials embed directly into building envelopes for space-constrained retrofits.
- Molten Salt:Composed of sodium nitrate and potassium nitrate blends operating between 220–550°C. Danish and Spanish utilities concentrate procurement for concentrated solar power plants and district heating buffers, driven by cycling stability above 500°C and proven 30-year operational lifespans.
- Phase Change Materials:Paraffin and salt hydrate formulations with defined fusion enthalpies enabling compact energy density. German and Austrian housing associations specify these for multi-family retrofits where floor space constraints exclude water tanks, compressed by EU Green Deal renovation mandates tightening spatial envelopes.
- Water Tank:Pressurized sensible heat storage remains the baseline for Scandinavian district heating networks.
- Aggregated Thermal Storage:Distributed node networks pooling multiple small units for grid-scale dispatch.
Volume placements concentrate in water tank systems across Nordic district heating; the faster expansion belongs to phase change materials in German and Italian residential retrofits.
Technology:
Technology selection maps to discharge duration requirements, with short-cycle systems serving peak shaving and long-duration storage addressing renewable intermittency.
- Thermal Batteries:Solid-state storage media with integrated heat exchangers enabling rapid charge-discharge cycles. Spanish industrial facilities deploy these for process heat recovery, constrained by limited domestic manufacturing capacity and dependence on German component imports.
- Sensible Heat Storage:Temperature change in solid or liquid media without phase transition. Mature water and rock-based systems anchor Scandinavian district heating networks in Copenhagen, Stockholm, and Helsinki, facing margin pressure from standardized designs.
- Latent Heat Storage:Phase transition at constant temperature yielding higher energy density per volume.
- Thermochemical Storage:Reversible chemical reactions enabling seasonal storage with minimal heat loss.
Revenue concentrates in sensible heat storage across Northern European district heating; thermochemical systems are climbing the fastest as seasonal storage pilots expand in Spain and Italy.
End User:
End-use segmentation reveals divergent procurement patterns, with industrial buyers favoring performance contracts and residential demand driven by retrofit mandates.
- Industrial:Steel, cement, and chemical processors sourcing turnkey heat delivery contracts. German chemical clusters and Nordic pulp mills lead this shift, bundling storage design with guaranteed output metrics rather than equipment-only procurement.
- Residential:Single and multi-family building retrofits specifying compact latent heat systems. Italian and Spanish housing associations accelerate deployment under EU Green Deal building renovation mandates compressing payback period thresholds.
- Commercial:Office and retail cooling applications favoring ice-based thermal batteries for peak shaving.
- Utilities:Grid-scale operators balancing renewable intermittency through centralized molten salt buffers.
Contract value concentrates in industrial performance agreements; residential installations are gaining share fastest as renovation mandates activate across Germany, Spain, and Italy.
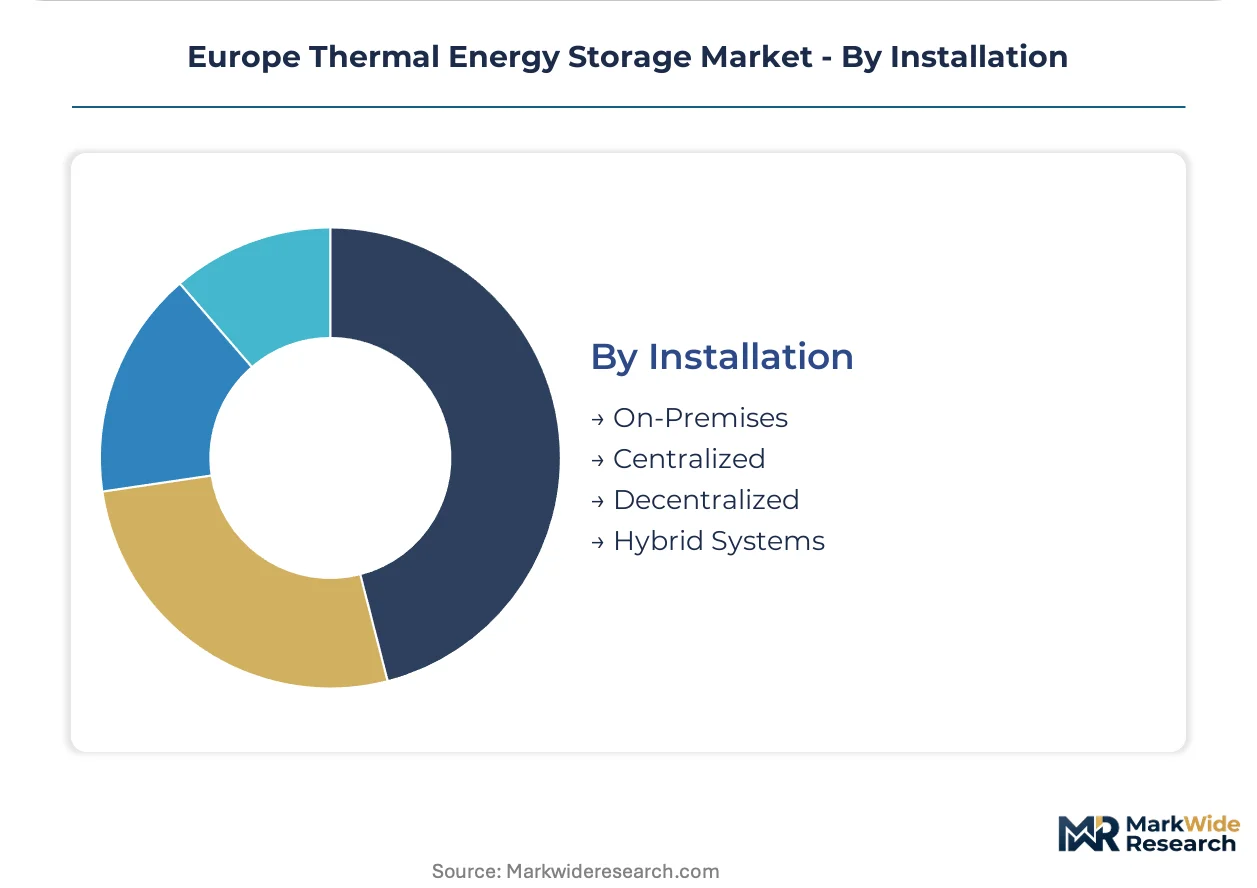
Installation:
Installation architecture determines system scalability and regulatory treatment, with centralized facilities facing stricter emissions oversight than distributed assets.
- On-Premises:Building-integrated systems serving single-site thermal loads. German manufacturing plants and Austrian commercial complexes favor these for operational autonomy, constrained by site-specific engineering requirements extending commissioning timelines.
- Centralized:Large-scale facilities feeding district heating networks or industrial parks. Copenhagen, Madrid, and Berlin host the largest molten salt installations, shaped by EMA industrial emissions guidelines and local utility procurement frameworks.
- Decentralized:Distributed node networks without central control infrastructure.
- Hybrid Systems:Configurations combining multiple storage technologies for flexible discharge profiles.
Capital deployment concentrates in centralized district heating buffers; hybrid configurations are expanding most quickly as Spanish and Italian utilities pilot multi-technology integration for renewable balancing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Spanish utilities concentrate the largest molten salt procurement volumes, while Scandinavian district heating operators anchor sensible heat storage deployment across Northern Europe.
Germany
Berlin hosts Europe's largest molten salt installations serving district heating buffers, while chemical processors in the Ruhr region pilot concrete-based storage for industrial waste heat recovery. The EU Green Deal's building renovation mandates accelerate latent heat storage deployment in multi-family retrofits across Bavaria and North Rhine-Westphalia. ECHA REACH compliance requirements extend commercialization timelines for novel phase change material formulations developed in Frankfurt chemical clusters.
Spain
Madrid concentrates utility-scale molten salt capacity balancing concentrated solar power intermittency, with Abengoa leveraging its CSP heritage to dominate project pipelines. Steel and cement plants in Catalonia pilot concrete-based storage modules for process heat recapture under EU Green Deal industrial decarbonization timelines. Spanish utilities deploying grid-interactive thermal storage face steep adaptation costs from legacy control architectures under emerging EU AI Act energy efficiency reporting requirements.
Denmark
Copenhagen's district heating network anchors Scandinavian sensible heat storage deployment, with utilities adding molten salt buffer capacity to balance wind power intermittency. Danish procurement frameworks prioritize cycling stability above 500°C for centralized installations feeding industrial parks. The EU F-Gas Regulation phase-down pushes commercial cooling applications toward ice-based thermal batteries for peak shaving in Aarhus and Odense retail complexes.
Italy
Italian housing associations accelerate compact latent heat system deployment under EU Green Deal renovation mandates compressing payback thresholds in Milan and Rome multi-family stock. Cement processors in the Po Valley pilot thermochemical storage for seasonal heat retention. EMA industrial emissions guidelines shape product standards for centralized facilities feeding district heating networks in Turin and Bologna.
Sweden
Stockholm's district heating operators expand water tank sensible heat storage as the mature baseline for renewable balancing, while pulp mills in Norrland lead industrial performance contracting bundling storage design with guaranteed heat delivery metrics. The CSRD scope-three disclosure mandate reshapes procurement criteria for manufacturing clusters sourcing storage equipment in Gothenburg. Scandinavian thermal systems engineering talent concentrates in research institutes linking Stockholm to German technical universities.
Europe Thermal Energy Storage Market Competitive Landscape
Spanish producers anchor one tier concentrated in concentrated solar power heritage and molten salt project development; German specialists hold another tier focused on phase change material formulations and industrial heat recovery systems. The vendor base splits between utility-scale standalone installers and building-integrated retrofit specialists. Three archetypes dominate: legacy CSP developers pivoting toward district heating, materials science firms commercializing novel PCM blends, and industrial equipment manufacturers bundling storage with performance contracts. Competitive moves center on strategic partnerships with utilities and technology licensing agreements for high-temperature system designs.
Within the CSP heritage tier, Abengoa occupies a position exemplifying the molten salt utility-scale developer archetype. Baltimore Aircoil Company and EnergyNest represent contrasting specialization vectors—one anchored in commercial cooling equipment structures, the other in patented concrete-based modules for industrial applications. These three firms illustrate the geographic and technological bifurcation shaping competitive positioning across the European thermal storage landscape.
| Leading Market Players |
|---|
| Abengoa |
| Baltimore Aircoil Company |
| Steffes |
| Evapco |
| Caldwell Energy Company |
| BrightSource Energy |
| Terrafore Technologies |
| Dunham Bush |
| EnergyNest |
| Others |
Value Network & Pricing Analysis
Sovereign-backed utilities and family-owned mid-cap engineering houses anchor ownership structures across the European thermal storage supply base, compressing pricing discipline through long-term offtake contracting rather than spot-market competition. This financing pattern feeds into molten salt procurement where Spanish and German utilities leverage state-backed credit lines to lock in decade-long supply agreements, while smaller PCM developers in Austria and Italy absorb input volatility through captive chemical processing.
Pricing Analysis
Premium pricing for sub-12-week lead times separates utility-scale molten salt projects from standardized water tank installations serving Scandinavian district heating networks. Project-based long-term contracting dominates, with price differentiation hinging on EMA emissions certification tier and volume scale of sodium nitrate procurement. Cost compression in paraffin-based PCM formulations is intensifying because REACH registration timelines extend commercialization cycles for novel salt hydrate blends. Residential retrofit buyers exhibit highest price sensitivity, while industrial performance-contract clients prioritize guaranteed heat delivery metrics over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for molten salt component flows into Spanish and German project sites. Supply concentrates in German chemical clusters for PCM precursors and Danish fabrication yards for pressurized water tanks. Raw material dependencies draw from Chilean sodium nitrate, German paraffin refineries, and Norwegian steel for containment vessels. Single-source vulnerability runs through Spanish CSP engineering talent for high-temperature system design. Distribution runs through utility procurement frameworks rather than merchant inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European thermal storage sector is consolidating around vertical-integration races, with upstream control over molten salt chemistry and downstream heat delivery contracting emerging as the decisive leverage points for margin defense.
For Market Incumbents: Extend performance-contract bundling into Eastern European district heating networks before EU Green Deal renovation mandates activate Polish and Czech procurement cycles. Cement captive supply of sodium nitrate through backward integration into German chemical processing to offset paraffin price volatility from Rotterdam traders. Incumbent molten salt developers face substitution threat from thermochemical storage pilots in Italian cement plants.
For New Entrants and Emerging Players: AI-optimized dispatch algorithms offer a technology-first wedge into Spanish and Italian grid-interactive thermal storage, where legacy control architectures face EU AI Act compliance costs. White-space targets concentrate in Eastern European district heating buffer capacity and industrial waste heat recovery for steel plants in Catalonia. Go-to-market execution should anchor on turnkey heat delivery contracts rather than equipment-only procurement to bypass entrenched utility vendor lists.
For Investors and Strategic Acquirers: Distressed-cycle entries favor concrete-based storage module specialists in Norway and Austria where EnergyNest's patent position has compressed competitor margins. Long-term viability over a decade-plus horizon rests on CSRD scope-three disclosure compliance capabilities reshaping industrial procurement criteria. Acquisition target archetype: mid-cap PCM formulators with REACH-registered salt hydrate portfolios. Watch thermochemical storage pilot scale-up in Italian Po Valley cement plants as inflection indicator for seasonal storage economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molten Salt Chemistry | German chemical processors secure sodium nitrate supply chains against Chilean export volatility. |
| Performance Contracting Expansion | Nordic pulp mills bundle storage design with guaranteed heat delivery metrics under CSRD disclosure rules. |
| AI-Act Compliance System Development | Spanish utilities retrofit legacy control architectures to meet emerging EU energy efficiency reporting requirements. |
| Eastern European District Heating Entry | Polish and Czech networks add sensible heat storage capacity under EU Green Deal renovation timelines. |
| Thermochemical Storage Pilot Scale-Up | Italian cement plants in Po Valley test seasonal heat retention for industrial decarbonization pathways. |
Research Methodology
IEA technology roadmaps, ECHA chemical registration databases, and EU project development registries formed the secondary backbone for market sizing and technology trend identification. Primary interviews with utility planning officers, EPC contractors for district heating infrastructure, molten salt procurement leads at Spanish CSP developers, and phase change material R&D directors at German chemical clusters combined with secondary validation through bottom-up installation tracking and top-down policy impact modeling. Triangulation across these sources anchored segmentation splits by technology type, end-use sector, and installation architecture.
Historical trendline analysis of deployment volumes across Nordic district heating networks, Spanish concentrated solar power installations, and German residential retrofit programs established baseline growth trajectories. The analytical framework modeled product type, technology category, end-user segment, and installation architecture dimensions across the projection horizon. CAGRs derived from technology-specific adoption curves weighted by EU Green Deal mandate implementation schedules and F-Gas Regulation phase-down timelines. Forecast inputs incorporated REACH registration pipeline status for novel PCM formulations and molten salt cycling stability data from Danish utility operational records.
Several conditions sit outside the modeled scope, including unannounced national subsidy program revisions, breakthrough thermochemical storage commercialization timelines, and geopolitical disruptions to Chilean sodium nitrate export flows. Forecasts reflect documented assumptions around EU AI Act implementation pacing and CSRD disclosure enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Thermal Energy Storage
Africa Thermal Energy Storage Market
Thermal Energy Storage
Southeast Asia Thermal Power Market
Thermal Energy Storage
North America Thermal Power Market
Thermal Energy Storage
Ice Thermal Storage Systems Market
Thermal Energy Storage
United States Thermal Power Market
Thermal Energy Storage
Asia-Pacific Thermal Energy Storage Market
Thermal Energy Storage
Middle-East and Africa Thermal Power Market
Thermal Energy Storage
Thermal Recovery Market
Thermal Energy Storage
Solar Thermal Fuel Market
Thermal Energy Storage
North America Thermal Energy Storage Market
Thermal Energy Storage
Russia Thermal Power Market
Thermal Energy Storage
Europe District Heating Market
Thermal Energy Storage
China Thermal Power Plant Market
Thermal Energy Storage
Molten Salt Thermal Energy Storage (TES) Market
Thermal Energy Storage
Thermal Energy Storage (TES) Market