
 Asia-Pacific Distributed Solar Power Generation Market | 2026-2036
Asia-Pacific Distributed Solar Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Distributed Solar Power Generation Market Outlook
Project finance and third-party leasing is rewriting competitive entry barriers across the Asia-Pacific distributed solar landscape. JinkoSolar Holding Co. Ltd. leverages vertically integrated cell-to-module capacity to anchor utility-scale and commercial rooftop portfolios simultaneously. Waaree Energies dominates domestic Indian module supply while extending its project development footprint across Southeast Asian markets. Tata Power Solar sustains a dual revenue stream through EPC execution and long-term power purchase agreements with industrial offtakers.
Asia-Pacific distributed solar power generation refers to photovoltaic systems typically below 10 MW capacity installed at or near the point of consumption, utilizing crystalline silicon or thin-film modules with string or micro-inverters to convert DC output to grid-synchronous AC power for commercial, industrial, or residential loads. These systems reduce transmission losses and defer distribution network upgrades while providing behind-the-meter energy cost stabilization. Photovoltaic technology leads installed capacity across all end-user segments, though hybrid systems pairing solar with battery storage represent the fastest-growing configuration as lithium-ion costs decline and grid reliability concerns persist. The residential application segment remains price-sensitive with thinner margins, while large enterprise and industrial offtakers concentrate value capture through captive power structures and open access wheeling arrangements.
India's Ministry of New and Renewable Energy, China's National Energy Administration, and Australia's Clean Energy Regulator collectively shape market access through divergent subsidy mechanisms, grid interconnection standards, and renewable purchase obligation enforcement. India's PLI scheme and China's dual carbon goals are forcing module localization, while Australia's Small-scale Renewable Energy Scheme directly subsidizes rooftop deployment through tradable certificates. Stakeholders must monitor evolving net metering caps and distribution network hosting capacity constraints as distributed penetration rises beyond distribution transformer limits across high-growth states and provinces.
Market Dynamics
India's PLI scheme and China's dual carbon goals are forcing module localization across the Asia-Pacific distributed solar value chain, compressing import-dependent supply models while accelerating captive manufacturing buildout.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for solar module manufacturing are pulling polysilicon-to-module capacity into Gujarat and Tamil Nadu, reducing import exposure for domestic project developers.
- Commercial rooftop demand:Manufacturing clusters across Vietnam and Thailand are deploying behind-the-meter systems to hedge volatile grid tariffs and secure power quality for precision assembly lines.
- Lithium-ion cost compression:Battery storage pairing with distributed solar is crossing economic thresholds in Australian C&I segments, enabling 24/7 renewable offtake structures previously restricted to utility-scale projects.
Market Restraints
- Polysilicon supply concentration:Xinjiang-based polysilicon refining dominates global feedstock, exposing module assemblers in India and Southeast Asia to forced labor scrutiny and supply disruption risks.
- Distribution network hosting limits:High distributed penetration in Tamil Nadu and Gujarat is saturating rural 11kV transformers, triggering technical rejection of new interconnection applications.
- Net metering policy reversals:Several Indian states are capping or eliminating net metering tariffs for commercial consumers, undermining project finance assumptions for rooftop portfolios.
Strategic Opportunities
- Philippines archipelago deployment:Island grids with diesel-dependent generation economics support hybrid solar-plus-storage microgrids for mining and resort loads currently unserved by reliable transmission.
- Green hydrogen offtake integration:Electrolyzer projects in Australia's Pilbara and Queensland are contracting dedicated renewable supply, creating anchor demand for utility-scale and large distributed solar arrays.
- Corporate renewable energy procurement mandates:RE100 commitments by Japanese and South Korean manufacturing conglomerates are driving direct PPA structures with distributed asset owners, bypassing traditional utility intermediation.
Industry Challenges
- Skilled EPC workforce scarcity:Rapid capacity expansion in India and Vietnam has outpaced training pipelines for DC cable routing, inverter commissioning, and grid synchronization protocols.
- Distribution utility coordination friction:Legacy billing systems and interconnection queues in Indonesian and Philippine utilities impose 6-18 month project delays despite technical readiness.
- Module quality assurance complexity:Proliferation of tier-2 and tier-3 suppliers under PLI-driven capacity expansion is elevating degradation risk and warranty claim exposure for long-dated project finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Distributed Solar Power Generation Market |
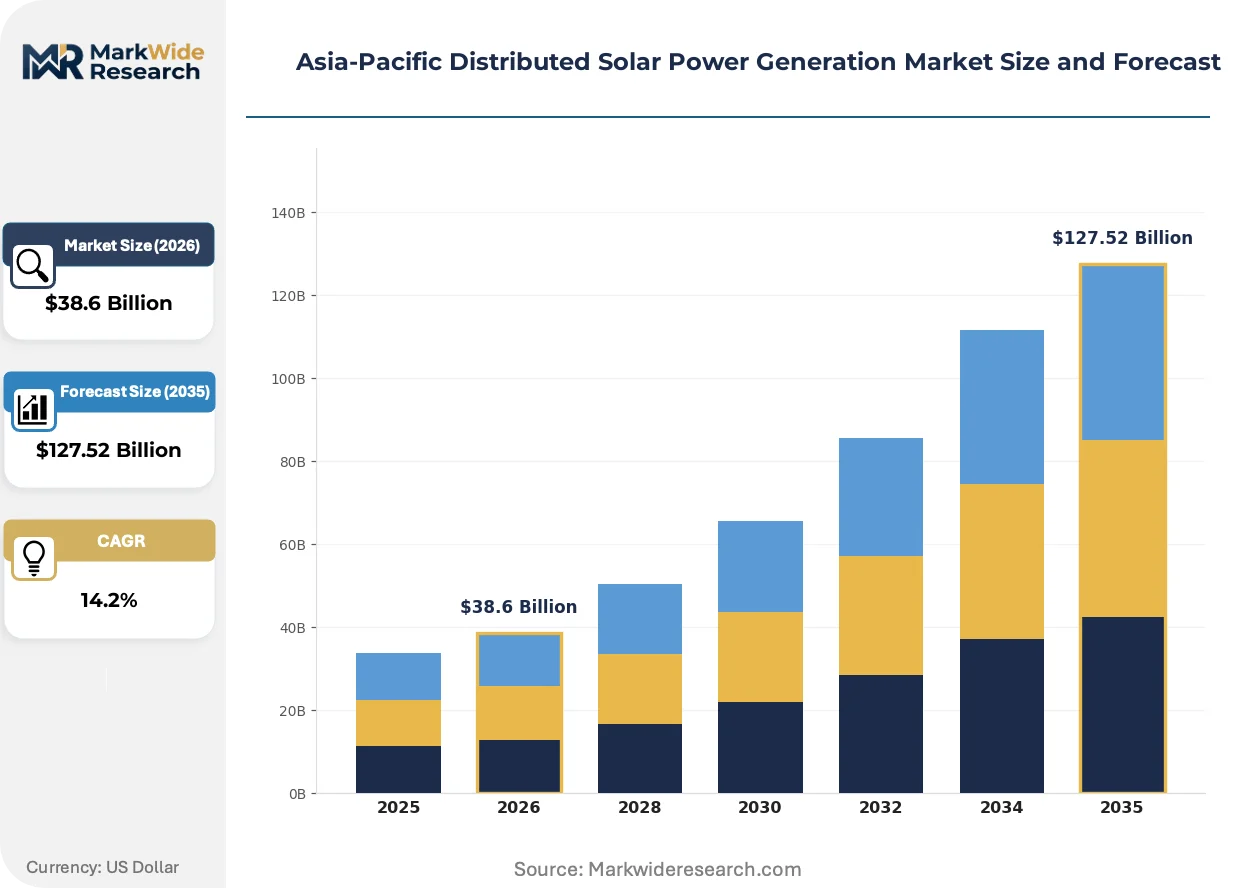
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Inverters, Batteries, Monitoring Systems Application: Residential, Commercial, Industrial, Agricultural Technology: Photovoltaic, Concentrated Solar Power, Hybrid Systems, BIPV End User: Households, SMEs, Large Enterprises, Government |
| Companies Covered | JinkoSolar Holding Co. Ltd., Waaree Energies, Tata Power Solar, Azure Power, Vikram Solar, Adani Green Energy, Trina Solar Co. Ltd., Amplus Solar, LONGi Solar, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Distributed Solar Power Generation Market Strategic Shifts
Module efficiency trajectories and inverter topology choices are restructuring competitive economics across the Asia-Pacific distributed solar landscape, with technology migration compressing balance-of-system costs and enabling new ownership models.
TOPCon cell architecture is migrating from utility-scale procurement into commercial rooftop specifications as module suppliers extend n-type passivated contact production lines originally scaled for ground-mount demand. Large industrial offtakers in India's automotive and textile clusters are specifying TOPCon modules for 25-year degradation warranties that match their captive power contract tenors. This technology migration from utility-scale to distributed applications is compressing the historical efficiency premium that mono-PERC held in the sub-10MW segment.
Australia's Small-scale Renewable Energy Scheme is tightening certificate eligibility thresholds for module efficiency and inverter power quality, forcing suppliers to recertify product portfolios or exit the residential and small commercial channel. The Clean Energy Regulator's 2024 updates to AS/NZS 4777 grid interconnection standards are mandating enhanced ride-through capabilities that favor string inverter architectures over micro-inverter alternatives. C&I project developers in New South Wales and Victoria are responding by consolidating procurement around a narrower supplier base with pre-certified compliance packages.
Third-party leasing and energy-as-a-service contracts are displacing direct equipment ownership among Southeast Asian manufacturing SMEs lacking balance-sheet capacity for upfront solar capex. Singapore-based financing platforms are underwriting 10-15 year power purchase agreements with embedded operations and maintenance, transferring technology and performance risk from industrial hosts to specialized asset owners. This financing innovation is most visible in Vietnam's northern industrial zones, where foreign-invested electronics manufacturers prefer off-balance-sheet structures that preserve debt capacity for core production equipment.
Asia-Pacific Distributed Solar Power Generation Market Segmentation
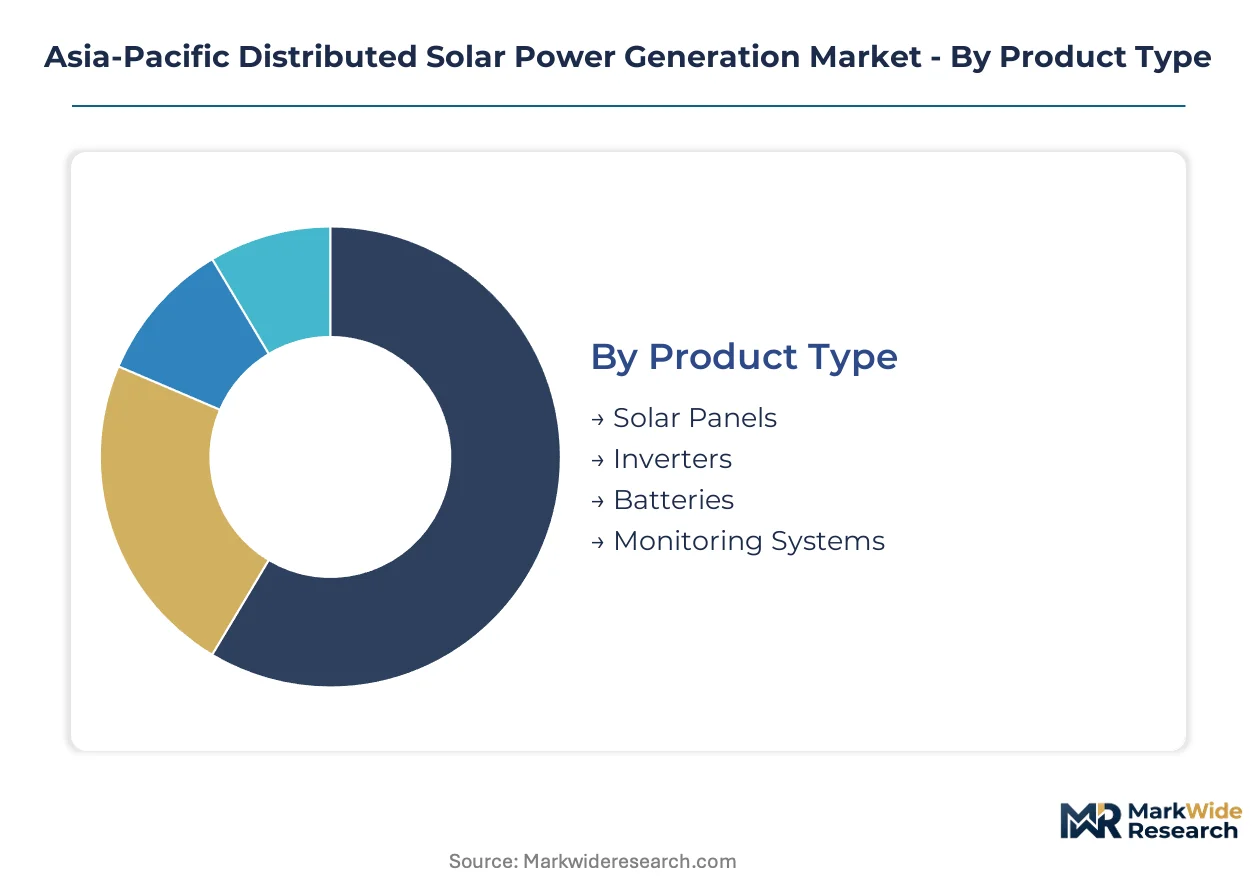
Distributed solar deployment across the Asia-Pacific region fragments across equipment types, customer scale, and integration complexity. Each segmentation axis reveals distinct procurement patterns, financing structures, and regulatory exposure that shape vendor strategy and project economics.
Product Type:
Mature hardware categories dominate installed capacity while emerging components capture incremental value through intelligence and storage integration.
- Solar Panels:Crystalline silicon modules, primarily mono-PERC and migrating n-type TOPCon architectures, constitute the primary capital expenditure for rooftop and ground-mount distributed systems. Manufacturing clusters in Gujarat and Tamil Nadu under India's PLI scheme are pulling cell-to-module capacity away from import-dependent models, though Xinjiang-origin polysilicon feedstock remains a supply chain vulnerability for quality-assured procurement.
- Inverters:String and hybrid inverter topologies convert DC module output to grid-synchronous AC power, with power electronics manufacturers differentiating through MPPT channel density and grid support functionality. Australia's Clean Energy Regulator has tightened AS/NZS 4777 certification requirements, forcing recertification of product portfolios and consolidating procurement around pre-compliant supplier bases in New South Wales and Victoria.
- Batteries:Lithium-ion storage pairing enables behind-the-meter dispatch and backup power for C&I segments with grid reliability concerns.
- Monitoring Systems:IoT-enabled performance analytics and predictive maintenance platforms are penetrating large enterprise portfolios seeking operational transparency across multi-site solar assets.
Solar Panels retain volume leadership; Batteries hold the steepest expansion curve as lithium-ion cost compression accelerates hybrid system deployment.
Application:
Customer scale determines financing access, contract structure, and regulatory exposure across the distributed solar value chain.
- Residential:Small-scale rooftop systems below 10kW capacity serve household electricity loads, with deployment concentrated in Australian suburbs under the Small-scale Renewable Energy Scheme and Indian urban centers with favorable net metering policies. Price sensitivity and thin installer margins characterize this segment, with third-party leasing models gaining traction among capital-constrained households.
- Commercial:Behind-the-meter systems for retail, office, and hospitality loads leverage accelerated depreciation and open access wheeling where permitted. Manufacturing clusters across Vietnam and Thailand are deploying commercial rooftop arrays to hedge volatile grid tariffs and secure power quality for precision assembly lines, with Singapore-based financing platforms underwriting 10-15 year power purchase agreements.
- Industrial:Captive power structures for automotive, textile, and electronics manufacturing in India's Gujarat and Tamil Nadu states exploit state-level net metering policies and industrial zone electrification targets.
- Agricultural:Solar-powered irrigation and cold chain applications address rural electrification gaps, though distribution transformer saturation in high-penetration districts is triggering technical rejection of new interconnection applications.
Industrial applications command the largest average project scale; Commercial deployment is climbing the fastest as energy-as-a-service models proliferate across Southeast Asian manufacturing SMEs.
Technology:
Technology selection tracks efficiency requirements, integration complexity, and architectural constraints across building types.
- Photovoltaic:Crystalline silicon dominates installed capacity across all end-user segments, with module efficiency trajectories compressing balance-of-system costs and enabling new ownership models for distributed deployment.
- Concentrated Solar Power:Dish Stirling and parabolic trough configurations find limited application in distributed contexts due to tracking infrastructure requirements and land constraints, remaining concentrated in utility-scale desert installations.
- Hybrid Systems:Solar-plus-storage configurations pairing photovoltaic generation with lithium-ion batteries represent the fastest-growing technology category as battery costs decline and grid reliability concerns persist across the Asia-Pacific region.
- BIPV:Building-integrated photovoltaic systems substitute conventional construction materials with solar-generating surfaces, penetrating premium commercial and institutional projects where architectural integration commands value capture.
Photovoltaic retains volume leadership; Hybrid Systems are gaining share fastest as battery economics cross commercial thresholds.
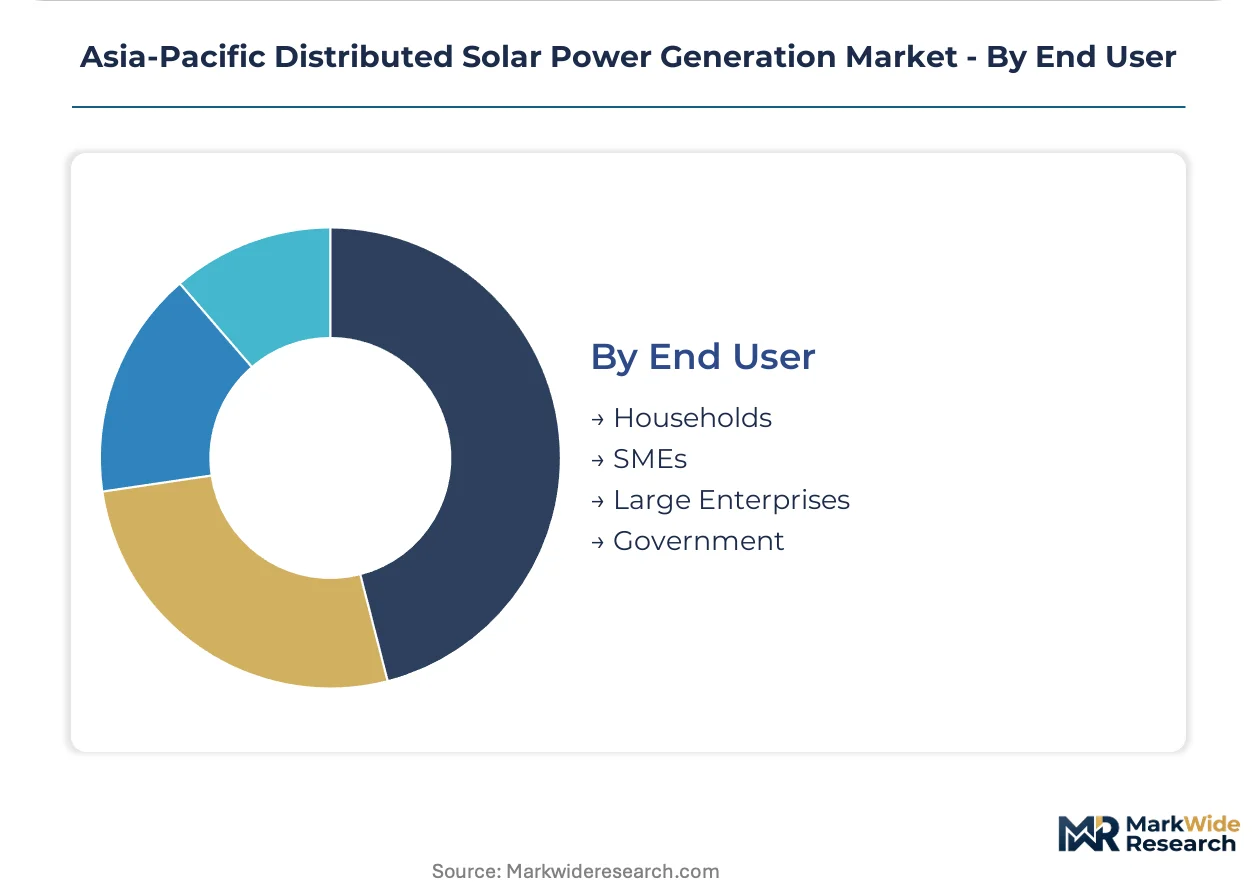
End User:
Balance sheet capacity and procurement sophistication stratify end-user segments across direct ownership, third-party leasing, and utility-intermediated structures.
- Households:Individual residential consumers deploy small-scale rooftop systems through cash purchase, green financing, or third-party lease arrangements, with policy support varying sharply across Indian states and Australian territories.
- SMEs:Small and medium enterprises lack capital reserves for upfront solar capex, driving preference for energy-as-a-service contracts that transfer technology and performance risk to specialized asset owners.
- Large Enterprises:Automotive, textile, and electronics conglomerates in India, Japan, and South Korea are executing direct power purchase agreements with distributed asset owners, bypassing traditional utility intermediation to meet RE100 commitments and secure renewable energy procurement mandates.
- Government:Public sector deployment spans municipal buildings, defense installations, and rural electrification programs, with procurement constrained by bureaucratic tendering cycles and fiscal allocation timelines.
Large Enterprises retain volume leadership; SMEs are expanding most quickly as off-balance-sheet financing structures democratize access to distributed solar assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme and China's dual carbon goals are reshaping module supply chains across Asia-Pacific, pulling polysilicon-to-module capacity into domestic manufacturing clusters while compressing import-dependent models.
India
Gujarat and Tamil Nadu anchor project pipelines through state-level net metering policies and industrial zone electrification targets. The Ministry of New and Renewable Energy enforces renewable purchase obligations that mandate distribution utilities procure specified shares from solar generators. Manufacturing clusters in Mundra and Sri City are deploying captive rooftop arrays for automotive and textile offtakers seeking behind-the-meter cost stabilization.
China
Dual carbon goals accelerate distributed deployment across manufacturing provinces seeking to displace coal-intensive grid power. The National Energy Administration streamlines interconnection standards for commercial and industrial rooftop systems below 10 MW capacity. Yangtze River Delta industrial zones are integrating distributed solar with provincial carbon intensity targets to satisfy export market compliance requirements.
Australia
The Small-scale Renewable Energy Scheme directly subsidizes residential and small commercial rooftop deployment through tradable certificate mechanisms. The Clean Energy Regulator tightened AS/NZS 4777 grid interconnection standards in 2024, mandating enhanced ride-through capabilities that favor string inverter architectures. New South Wales and Victoria concentrate C&I project development around pre-certified supplier bases with compliant equipment packages.
Vietnam
Northern industrial zones host foreign-invested electronics manufacturers deploying behind-the-meter systems to hedge volatile grid tariffs and secure power quality for precision assembly lines. Singapore-based financing platforms underwrite 10-15 year power purchase agreements with embedded operations and maintenance, transferring technology risk to specialized asset owners. Bac Ninh and Hai Phong provinces concentrate manufacturing load centers with distributed solar penetration.
Thailand
Eastern Economic Corridor manufacturing clusters deploy commercial rooftop arrays to meet corporate renewable energy procurement mandates from Japanese and South Korean conglomerates. The country's national energy regulator maintains open access wheeling arrangements that enable direct power purchase agreements bypassing traditional utility intermediation. Rayong and Chonburi provinces anchor automotive and electronics assembly operations with captive solar structures.
Asia-Pacific Distributed Solar Power Generation Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated cell-to-module manufacturers and specialized project developers with captive EPC capabilities. Tier-1 module suppliers leverage polysilicon refining and wafer slicing integration to compress production costs and warranty exposure. Three strategic archetypes dominate: integrated manufacturers controlling upstream feedstock, domestic champions capturing PLI-driven capacity buildout, and energy-as-a-service platforms underwriting long-dated power purchase agreements. Competitive positioning hinges on backward integration into polysilicon supply and geographic diversification of manufacturing footprints to mitigate forced labor scrutiny risks.
Among China-based integrated manufacturers, JinkoSolar Holding Co. Ltd., Trina Solar Co. Ltd., and LONGi Solar occupy positions anchoring both utility-scale and distributed commercial rooftop procurement. Indian domestic champions including Waaree Energies and Tata Power Solar exemplify the PLI-scheme archetype, with module assembly capacity concentrated in Gujarat and Tamil Nadu to serve state-level project pipelines. These named entities represent the tiered competitive structure where integrated Chinese suppliers compete on cell efficiency and scale economics while Indian fabricators capture policy-protected domestic demand.
| Leading Market Players |
|---|
| JinkoSolar Holding Co. Ltd. |
| Waaree Energies |
| Tata Power Solar |
| Azure Power |
| Vikram Solar |
| Adani Green Energy |
| Trina Solar Co. Ltd. |
| Amplus Solar |
| LONGi Solar |
| Others |
Value Chain & Pricing Dynamics
Xinjiang-based polysilicon refining concentration anchors upstream margin capture, forcing module assemblers in India and Southeast Asia to absorb feedstock volatility or surrender pricing power to integrated Chinese cell-to-module suppliers. Downstream margin pools concentrate with asset owners underwriting long-dated power purchase agreements, while EPC contractors and tier-2 module suppliers face sustained compression.
Pricing Analysis
Module efficiency tier and certification grade under AS/NZS 4777 standards create the primary spread between premium and economy pricing. Three-tier pricing structure across premium TOPCon, standard mono-PERC, and economy poly-crystalline modules stratifies procurement across residential, commercial, and industrial segments. Cost compression in economy tiers is intensifying because PLI-driven capacity expansion in India and Vietnam is flooding tier-2 supply. Residential households exhibit highest price sensitivity, while large industrial offtakers with RE100 mandates demonstrate lowest sensitivity.
Supply Chain Analysis
Longi Solar, Trina Solar, and JinkoSolar dominate contract-manufacturing capacity for n-type cell architectures. Polysilicon sourcing concentrates in Xinjiang, wafer slicing in Jiangsu and Zhejiang provinces, and module assembly in Gujarat and Tamil Nadu under India's PLI scheme. The supply chain draws from lithium-ion battery cells produced in South Korea and China for hybrid system integration. Single-source vulnerability in Xinjiang-origin polysilicon exposes assemblers to forced labor scrutiny and supply disruption. Distribution runs through EPC contractors with captive project development arms and Singapore-based financing platforms underwriting energy-as-a-service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from polysilicon price cyclicality, with lithium-ion cost compression and module efficiency migration providing cyclical uplift through the analysis window.
For Market Incumbents: Harden module quality assurance protocols against degradation risk from PLI-driven tier-2 capacity expansion. Secure backward integration into polysilicon supply or diversify manufacturing footprints beyond Xinjiang-dependent feedstock to mitigate forced labor scrutiny. Anchor utility-scale procurement relationships while defending commercial rooftop share against emerging energy-as-a-service platforms. For New Entrants and Emerging Players: Philippine island grids with diesel-dependent generation economics offer the most penetrable white-space for hybrid solar-plus-storage microgrids targeting mining and resort loads. Vietnam's northern industrial zones present secondary opportunity for off-balance-sheet financing structures serving foreign-invested electronics manufacturers lacking solar capex capacity. Lead with Singapore-based platform underwriting to bypass balance-sheet constraints among SME manufacturing hosts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed EPC contractors holding captive project development pipelines in Gujarat and Tamil Nadu. Five-to-ten year viability hinges on regulatory durability of net metering policies and distribution network hosting capacity expansion. Acquisition targets should demonstrate pre-certified AS/NZS 4777 compliance and long-dated PPA backlogs with industrial offtakers. Watch for state-level net metering cap adjustments as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Module Efficiency Migration | TOPCon cell architecture adoption compresses balance-of-system costs for 25-year commercial rooftops in Indian automotive clusters. |
| Polysilicon Supply Diversification | Non-Xinjiang feedstock sourcing mitigates forced labor scrutiny risks for module assemblers serving European export markets. |
| Energy-as-a-Service Platform Buildout | Singapore-based financing structures democratize distributed solar access among Vietnamese SME manufacturers lacking upfront capex. |
| Grid Interconnection Pre-Certification | AS/NZS 4777 compliance consolidation around string inverter architectures accelerates C&I deployment in New South Wales and Victoria. |
| Hybrid Storage Integration | Lithium-ion cost compression enables 24/7 renewable offtake structures for Australian C&I segments previously restricted to utility-scale. |
Study Parameters
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators across India, China, Australia, Vietnam, and Thailand, and refined through secondary validation. Bottom-up and top-down triangulation combined regulatory filings from India's Ministry of New and Renewable Energy, China's National Energy Administration, and Australia's Clean Energy Regulator with project development databases and customs/trade data tracking module shipments. Field interviews with industrial offtakers in Gujarat and Tamil Nadu manufacturing clusters informed captive power structure economics.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling capacity additions against renewable purchase obligation enforcement and net metering policy durability. Segmentation dimensions included generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from project pipeline visibility and module procurement trajectories. Forecast inputs incorporated lithium-ion battery cost curves and polysilicon spot price volatility assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by tier-2 module suppliers under India's PLI scheme or abrupt net metering policy reversals would shift outcomes. Quarterly review of state-level interconnection application rejection rates and distribution transformer saturation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Japan Solar Energy Market
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
Mexico Rooftop Solar Market
Solar Power Systems
Chile Solar Energy Market
Solar Power Systems
Indonesia Solar Energy Market
Solar Power Systems
APAC Solar Micro Inverters Market
Solar Power Systems
Bifacial Solar Panels Market