
 Grid Connected PV Systems Market | 2026-2036
Grid Connected PV Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Grid Connected PV Systems Market Foresight
Photovoltaic engineer shortages across installation and grid integration disciplines is redrawing competitive boundaries in the Grid Connected PV Systems Market. LONGi Green Energy leverages its fully integrated wafer-to-module production footprint to control cost curves in monocrystalline supply. JinkoSolar anchors its position through aggressive capacity deployment across multiple continents. Sungrow competes in the power electronics layer, specializing in string and central inverter platforms that interface with high-voltage transmission networks.
Grid connected PV systems comprise photovoltaic arrays, inverters, and balance-of-system components engineered to synchronize with utility frequency and voltage parameters, typically operating at 600–1500 V DC string voltages before AC conversion for distribution or transmission injection. These installations serve commercial and industrial load centers, utility-scale generation portfolios, and residential prosumers seeking net metering or power purchase agreement structures. Monocrystalline technology dominates module supply due to superior conversion efficiency and declining wafer costs, while bifacial architectures capture incremental rear-side albedo gains in utility and commercial ground-mount deployments. Inverters represent a concentrated margin pool where component reliability and grid-support functionality determine procurement decisions across utility and industrial application segments.
Grid codes from Germany's KBA-relevant network agencies, India's CEA technical standards for connectivity, and the US FERC interconnection protocols shape inverter compliance, reactive power capability, and fault ride-through requirements that filter market access. The EU Green Deal and national renewable auctions in Spain, Italy, and Poland accelerate utility-scale procurement timelines while tightening domestic content and sustainability disclosure rules. Stakeholders must monitor evolving grid stability mandates and storage co-location requirements as penetration thresholds rise across major interconnected systems.
Market Dynamics
Utility-scale solar procurement in high-irradiance markets is compressing inverter lead times and forcing module suppliers to synchronize wafer capacity with interconnection queue velocities. String inverter architectures are capturing share from central inverters as project developers prioritize granular MPPT and reduced DC cabling losses.
Growth Catalysts
- Feed-in tariff revisions:Germany's KBA-relevant network agencies and India's CEA technical standards are restructuring power purchase economics to favor rapid grid-tied deployment timelines.
- Bifacial module technology:Rear-side albedo capture is expanding addressable capacity factors in ground-mount installations across desert and high-reflectivity terrains.
- Renewable portfolio standards:State-level mandates in the United States are hardening procurement obligations for utilities, creating guaranteed offtake channels for photovoltaic developers.
Market Restraints
- Polysilicon supply concentration:Wafer production clustering in specific manufacturing geographies exposes module assemblers to input cost volatility and trade policy disruptions.
- Interconnection queue congestion:FERC interconnection protocols and regional transmission organization study backlogs are extending project energization timelines by multiple years.
- Grid stability thresholds:Rising photovoltaic penetration in California, Germany, and South Australia is triggering curtailment mandates and reactive power capability requirements that increase balance-of-system costs.
Strategic Opportunities
- Storage co-location mandates:Spain, Italy, and Poland are embedding battery pairing requirements in renewable auction frameworks, creating integrated system demand.
- Agricultural photovoltaic convergence:Dual-use agrivoltaic installations in France and Japan are unlocking land-constrained deployment channels with differentiated permitting pathways.
- String inverter retrofit cycles:First-generation utility-scale installations in Germany and the United States are approaching end-of-design-life replacement windows.
Industry Challenges
- Photovoltaic engineer scarcity:Installation and grid integration disciplines face acute talent gaps that extend project commissioning timelines and inflate labor costs.
- Domestic content compliance:EU Green Deal sustainability disclosure rules and India's PLI scheme localization thresholds are complicating procurement strategies for multinational developers.
- Inverter firmware certification:Grid code harmonization across multiple jurisdictions is fragmenting testing protocols and delaying product market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grid Connected PV Systems Market |
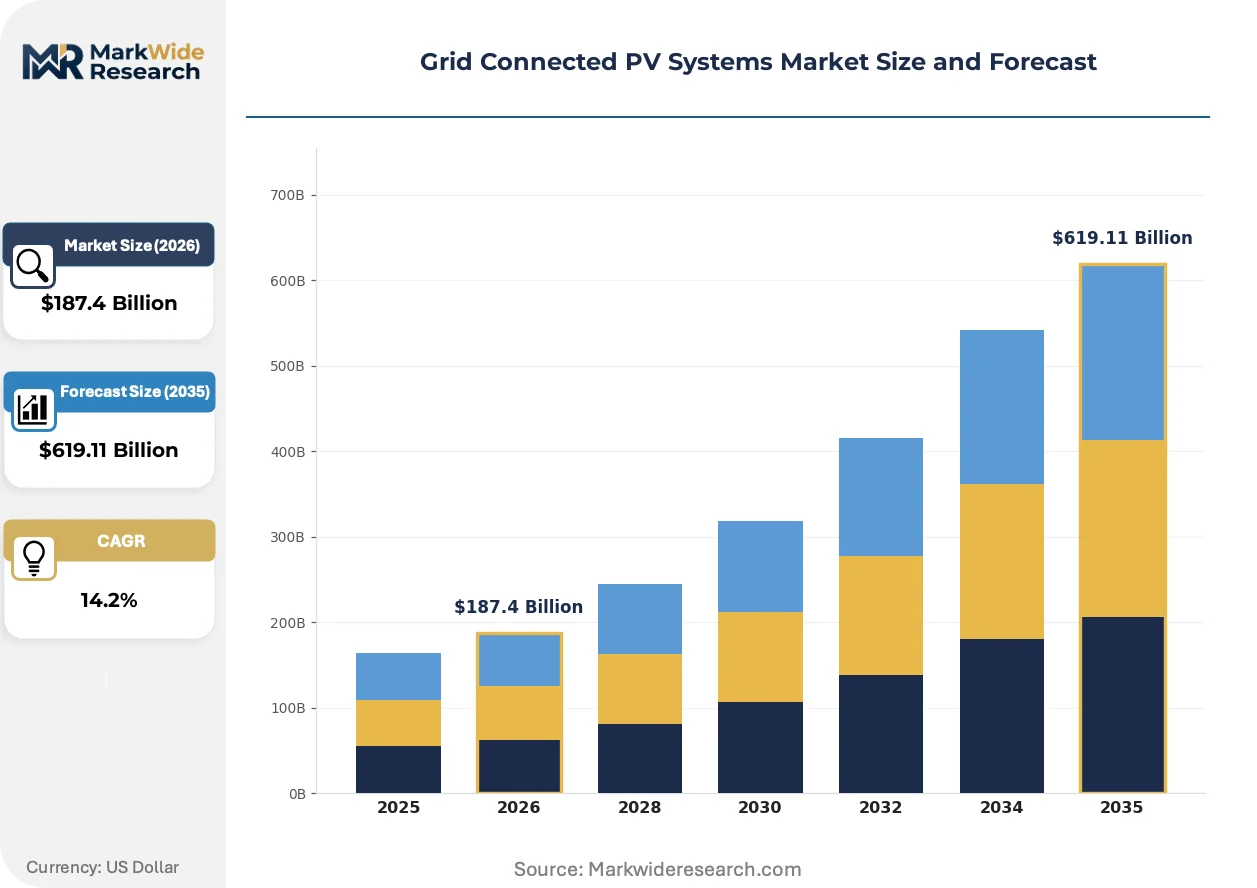
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $619.11 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Monocrystalline, Polycrystalline, Thin Film, Bifacial System Type: On-Grid, Hybrid, Off-Grid, Storage Application: Residential, Commercial, Industrial, Utility Component: Inverters, Mounting Structures, Cables, Monitoring Systems |
| Companies Covered | First Solar, Canadian Solar, Trina Solar, JinkoSolar, LONGi Green Energy, JA Solar, Hanwha Q CELLS, Sungrow, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grid Connected PV Systems Market Shifts & Advancements
Module-level power electronics and high-voltage string architectures are fragmenting the traditional central inverter value chain. Bifacial cell metallization advances and heterojunction processes are compressing levelized cost trajectories faster than incumbent roadmap assumptions.
TOPCon cell architecture is decomposing the historical efficiency gap between monocrystalline and thin-film alternatives. Utility-scale developers in India and the Middle East are specifying n-type bifacial configurations for new procurement tranches. This technology transition is decomposing legacy PERC capacity planning and forcing retooling decisions across wafer-fab networks.
EU Green Deal carbon border adjustment mechanisms are tightening embodied emissions disclosure requirements for imported photovoltaic components. Module suppliers must now document supply chain carbon intensity from polysilicon refining through cell fabrication. European utility procurement teams are prioritizing low-carbon certification tiers, compressing market access for unverified Asian manufacturing.
Power purchase agreement structures are migrating from fixed-price tenors to merchant-plus-hedge hybrids that transfer wholesale price risk to project equity. Independent power producers in Texas and Australia are pioneering this contracting evolution to secure financing without full revenue certainty. This shift is compressing developer margins while expanding addressable offtaker pools beyond credit-rated utilities.
Grid Connected PV Systems Market Segmentation
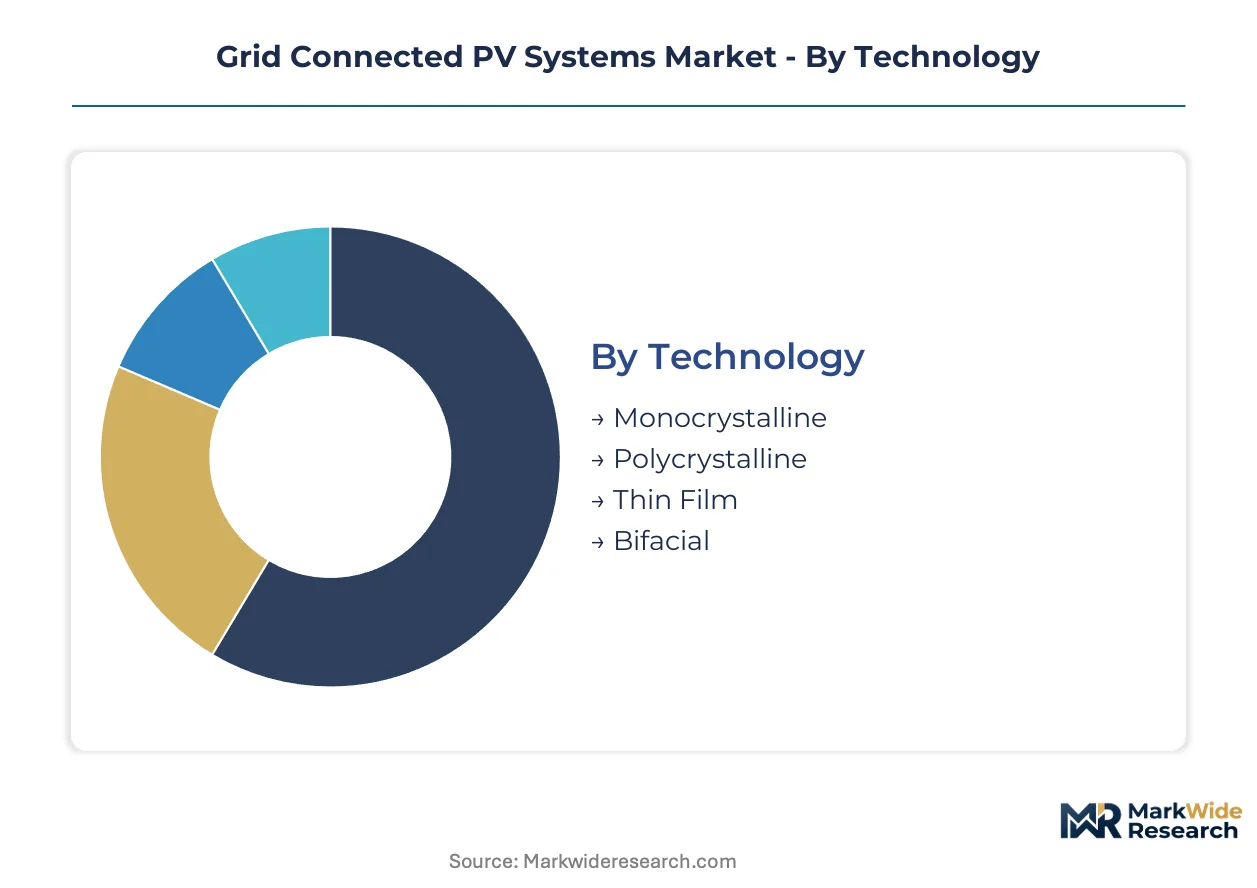
Technology choices in grid-connected PV systems determine project economics across irradiance regimes and grid stability requirements. Segment boundaries shift as cell metallization advances and inverter architectures evolve.
Technology:
Thin-film and polycrystalline formats face accelerating substitution pressure from higher-efficiency alternatives as land costs and balance-of-system expenses rise.
- Monocrystalline:Single-crystal silicon wafers deliver conversion efficiencies above 21% in standard test conditions. Utility-scale developers in India and the United States specify monocrystalline modules for high-irradiance sites where capacity factor optimization drives returns. PERC and TOPCon cell architectures are displacing legacy designs.
- Bifacial:Dual-sided cell construction captures rear-side albedo gains of 5-20% depending on ground reflectivity. Desert installations in the Middle East and agrivoltaic projects in France exploit this technology where land use efficiency commands premium pricing.
- Polycrystalline:Multi-crystal silicon construction offers lower manufacturing energy intensity but declining efficiency competitiveness. Emerging market residential installers in Southeast Asia continue procurement for price-sensitive segments.
- Thin Film:Cadmium-telluride and CIGS architectures retain niche applicability in building-integrated applications and extreme temperature environments where silicon degradation accelerates.
Monocrystalline retains volume leadership; bifacial holds the steepest expansion curve.
System Type:
Cost tier stratification separates utility-scale capital deployment from distributed commercial and residential configurations.
- On-Grid:Direct utility interconnection without energy storage represents the dominant configuration for utility-scale solar farms. Germany's KBA-relevant network agencies and India's CEA technical standards mandate specific reactive power capabilities for these installations.
- Hybrid:Grid-tied systems with battery co-location are capturing share as Spain, Italy, and Poland embed storage requirements in renewable auction frameworks. Dispatchable capacity commands premium offtake pricing.
- Storage:Standalone battery systems paired with existing PV assets address grid stability thresholds in California and South Australia where curtailment mandates intensify.
- Off-Grid:Islanded systems with diesel or battery backup retain relevance in remote industrial sites and rural electrification programs beyond transmission infrastructure reach.
On-Grid dominates installed capacity; Hybrid is climbing the fastest as auction designs evolve.
Application:
Customer type segmentation aligns procurement scale with financing structure and regulatory treatment.
- Utility:Centralized solar farms exceeding 50 MW capacity feed transmission networks under power purchase agreements or merchant structures. FERC interconnection protocols and regional transmission organization queue management determine project timelines.
- Commercial:Rooftop and carport installations serving retail, logistics, and manufacturing load centers exploit net metering and behind-the-meter savings. String inverter architectures reduce DC cabling losses across fragmented roof geometries.
- Industrial:Large manufacturing facilities with predictable load profiles procure direct PV supply to hedge wholesale electricity exposure. Corporate renewable energy buyers in Texas and Australia pioneer merchant-plus-hedge contracting.
- Residential:Single-family and multi-family rooftop systems depend on net metering policy stability and installer network density. Photovoltaic engineer scarcity extends commissioning timelines in high-growth markets.
Utility commands revenue concentration; Commercial is expanding most quickly as distributed generation economics improve.
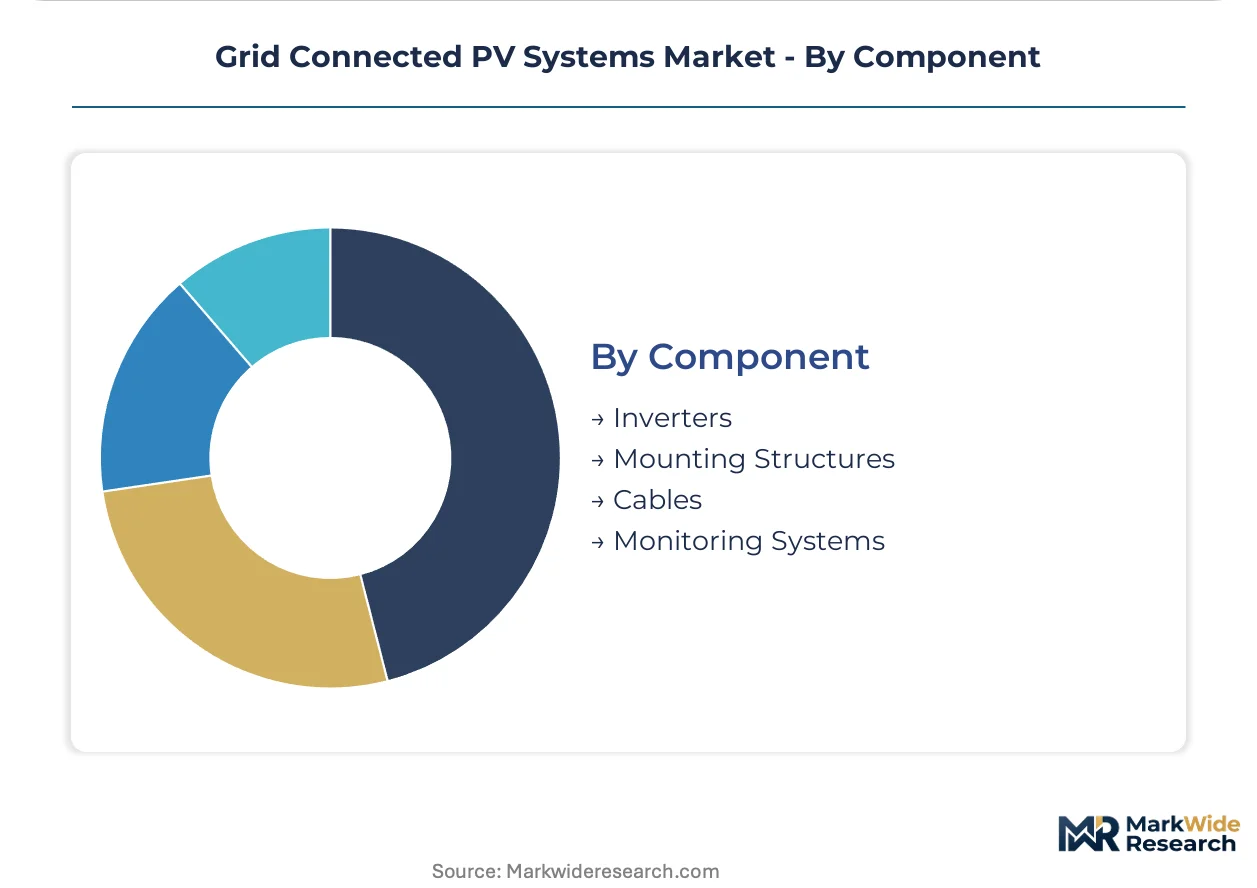
Component:
Margin distribution concentrates in power electronics and monitoring layers where differentiation determines procurement decisions.
- Inverters:String and central architectures convert 600–1500 V DC to grid-synchronous AC. Grid code harmonization across Germany, India, and the United States fragments firmware certification requirements.
- Monitoring Systems:Module-level power electronics and SCADA platforms enable granular performance optimization and predictive maintenance. Asset managers prioritize data granularity for utility-scale portfolio management.
- Mounting Structures:Fixed-tilt and tracking systems determine land use efficiency and construction labor requirements. Agrivoltaic configurations in France and Japan demand elevated structures compatible with agricultural machinery.
- Cables:DC and AC conductor sizing responds to string voltage evolution and installation code requirements. Copper price volatility and trade policy exposure complicate procurement planning.
Inverters capture the highest margin pool; Monitoring Systems are gaining share fastest as digitalization penetrates asset management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC interconnection protocols in the United States anchor the dominant geography, where utility-scale procurement velocities and grid code harmonization efforts reshape deployment timelines across major interconnected systems.
United States
Utility-scale solar farms in Texas and California drive procurement volumes as independent power producers pioneer merchant-plus-hedge contracting structures. FERC Order 2023 reforms interconnection queue management to accelerate study timelines. The Electric Reliability Council of Texas coordinates transmission expansion to absorb photovoltaic penetration growth.
Germany
Agrivoltaic installations and rooftop retrofits sustain deployment momentum as feed-in tariff revisions stabilize project economics. KBA-relevant network agencies enforce reactive power capability mandates for new grid-tied arrays. Bavaria and Baden-Württemberg concentrate engineering talent for inverter firmware certification.
India
Ultra-mega solar parks in Rajasthan and Gujarat scale procurement under PLI scheme localization thresholds. CEA technical standards mandate fault ride-through capabilities for transmission-connected projects. Tamil Nadu and Karnataka host module assembly clusters serving domestic auction pipelines.
China
Dual carbon goals accelerate utility-scale deployment in Inner Mongolia and Xinjiang high-irradiance zones. MIIT coordinates wafer capacity planning with grid absorption constraints. Yangtze River Delta manufacturing hubs supply monocrystalline and bifacial modules to international markets.
Australia
Grid stability thresholds in South Australia trigger storage co-location requirements for new utility-scale permits. AEMO interconnection standards evolve to manage distributed photovoltaic penetration. Queensland and New South Wales concentrate commercial rooftop installations behind volatile wholesale price exposure.
Grid Connected PV Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with wafer-to-module producers controlling cost curves while power electronics firms capture concentrated margin pools in inverter architectures. The market structure fragments across technology layers rather than consolidating around end-to-end system supply. Three archetypes dominate: vertically integrated cell-module producers, specialist inverter manufacturers, and project development platforms. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms synchronize manufacturing footprints with interconnection queue velocities.
Within the integrated production tier, LONGi Green Energy and JinkoSolar exemplify scale-driven positioning through captive wafer supply and multi-continental deployment footprints. Sungrow occupies a specialist position in power electronics, representing the inverter-focused archetype that interfaces with high-voltage transmission networks. These three anchors illustrate how competitive boundaries redraw around technology-layer control rather than geographic coverage alone.
| Leading Market Players |
|---|
| First Solar |
| Canadian Solar |
| Trina Solar |
| JinkoSolar |
| LONGi Green Energy |
| JA Solar |
| Hanwha Q CELLS |
| Sungrow |
| Huawei Technologies |
| Others |
Supply & Pricing Matrix
TOPCon cell architecture substitution for legacy PERC designs is redrawing manufacturing geography toward n-type wafer hubs in China and Southeast Asia while compressing module price premiums that previously rewarded efficiency leaders. This technology migration simultaneously concentrates polysilicon demand on higher-purity grades and erodes pricing power for incumbent PERC-optimized capacity.
Pricing Analysis
Module price spreads between Chinese export benchmarks and EU-delivered landed costs have widened as carbon border adjustment mechanisms and domestic content rules layer compliance premiums onto European procurement. Pricing stratifies across premium low-carbon certified tiers, standard utility-grade volumes, and economy-oriented polycrystalline residual supply. Cost compression in standard monocrystalline modules is intensifying as wafer capacity expansion outpaces interconnection queue velocity. Utility-scale developers exhibit lowest price sensitivity due to long-term power purchase agreement structures, while emerging market residential installers face acute budget constraints.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and port congestion at Rotterdam and Hamburg are inflating inbound logistics costs for module imports into the European Union. Manufacturing concentrates in China, Vietnam, and Malaysia for cell and module assembly, with polysilicon refining anchored in Xinjiang and Inner Mongolia. The supply chain draws from metallurgical-grade silicon, high-purity polysilicon, and silver paste for cell metallization. Single-source vulnerability in wafer slicing equipment exposes assemblers to tooling delivery delays. Distribution runs through EPC contractors and direct utility procurement channels with limited distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid-connected PV deployment sits in early-cycle expansion as renewable portfolio standards and storage co-location mandates in Spain, Italy, and Poland accelerate utility-scale procurement beyond historical penetration ceilings.
For Market Incumbents: Compound cost leadership through captive wafer supply and multi-continental module assembly footprints. Defend against heterojunction and perovskite-tandem substitution threats by accelerating TOPCon capacity conversion in Yangtze River Delta facilities. Prioritize inverter firmware certification investment for FERC Order 2023 compliance and KBA-relevant reactive power mandates. For New Entrants and Emerging Players: Grid code fast-track certification for string inverter architectures offers entry into retrofit replacement cycles across Germany and the United States. Target agrivoltaic deployment channels in France and Japan where dual-use permitting creates white-space with limited incumbent saturation. Pursue direct EPC partnerships rather than module-only supply to capture balance-of-system margin pools. For Investors and Strategic Acquirers: The market sits at a capacity-rationalization phase that favors integrated producers with polysilicon-to-module control and established utility offtake relationships. Long-term viability rests on technology transition execution and grid stability service capabilities beyond pure generation. Monitor inverter firmware harmonization progress across FERC, CEA, and EU network codes as inflection indicator for power electronics consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Wafer-fab expansion in Vietnam and Malaysia diversifies supply geography beyond China concentration. |
| Power Purchase Agreement | Merchant-plus-hedge structures in Texas and Australia transfer wholesale price risk to project equity. |
| Technology Licensing | TOPCon cell process licensing accelerates retooling decisions across legacy PERC-optimized networks. |
| Vertical Integration into Storage | Battery co-location capabilities address Spain and Italy auction mandates for dispatchable capacity. |
| Green Certification Program | EU Green Deal carbon intensity documentation secures procurement access for European utility buyers. |
Research Methodology
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base for this analysis. Primary interviews across these stakeholder categories combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity and deployment tallies triangulated against top-down renewable auction pipeline assessments.
Sensitivity analysis around interconnection queue velocity, polysilicon price trajectories, and module efficiency evolution shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, system configuration, application scale, and regional regulatory framework. CAGRs were derived from installed capacity build rates and average selling price evolution assumptions. Forecast inputs incorporated grid stability threshold penetration levels and storage co-location mandate adoption curves.
Decision-makers should treat outputs as directional under base assumptions of sustained renewable portfolio standard enforcement and moderate polysilicon supply expansion; material deviation in trade policy or grid code harmonization timelines would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Brazil Solar Energy Market
Solar Power Systems
Off-Grid Solar Lighting Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
High-Efficiency Solar Modules Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
North America Solar Photovoltaic (PV) Market