
 Solar Power Market | 2026-2036
Solar Power Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Power Market Intelligence
Software-as-a-service platforms for predictive maintenance and energy yield optimization is broadening the scope of solar project offerings beyond hardware installation. This shift favors integrated players like First Solar, which leverages its thin-film technology leadership and domestic manufacturing in the United States. JinkoSolar, in contrast, competes on global manufacturing scale and extensive distribution networks across multiple continents. NextEra Energy operates vast utility-scale solar assets, influencing procurement standards.
Solar power involves the conversion of sunlight into electricity, primarily through the photovoltaic effect in semiconductor materials. Most commercial panels use crystalline silicon wafers, typically doped to create a p-n junction, to generate direct current when exposed to photons. Within the technology landscape, monocrystalline silicon panels dominate new installations due to their higher efficiency ratings. The utility-scale application represents the largest segment by capacity, driven by large-scale power purchase agreements from independent power producers.
Regulatory frameworks are critical in shaping investment, with the EU Green Deal and China's dual carbon goals setting ambitious renewable energy targets. In the United States, regulations from the EPA on power plant emissions indirectly support solar development by pressuring fossil fuel generation. Navigating the evolving landscape of trade policies and local content requirements will be a central strategic challenge for component manufacturers and project developers.
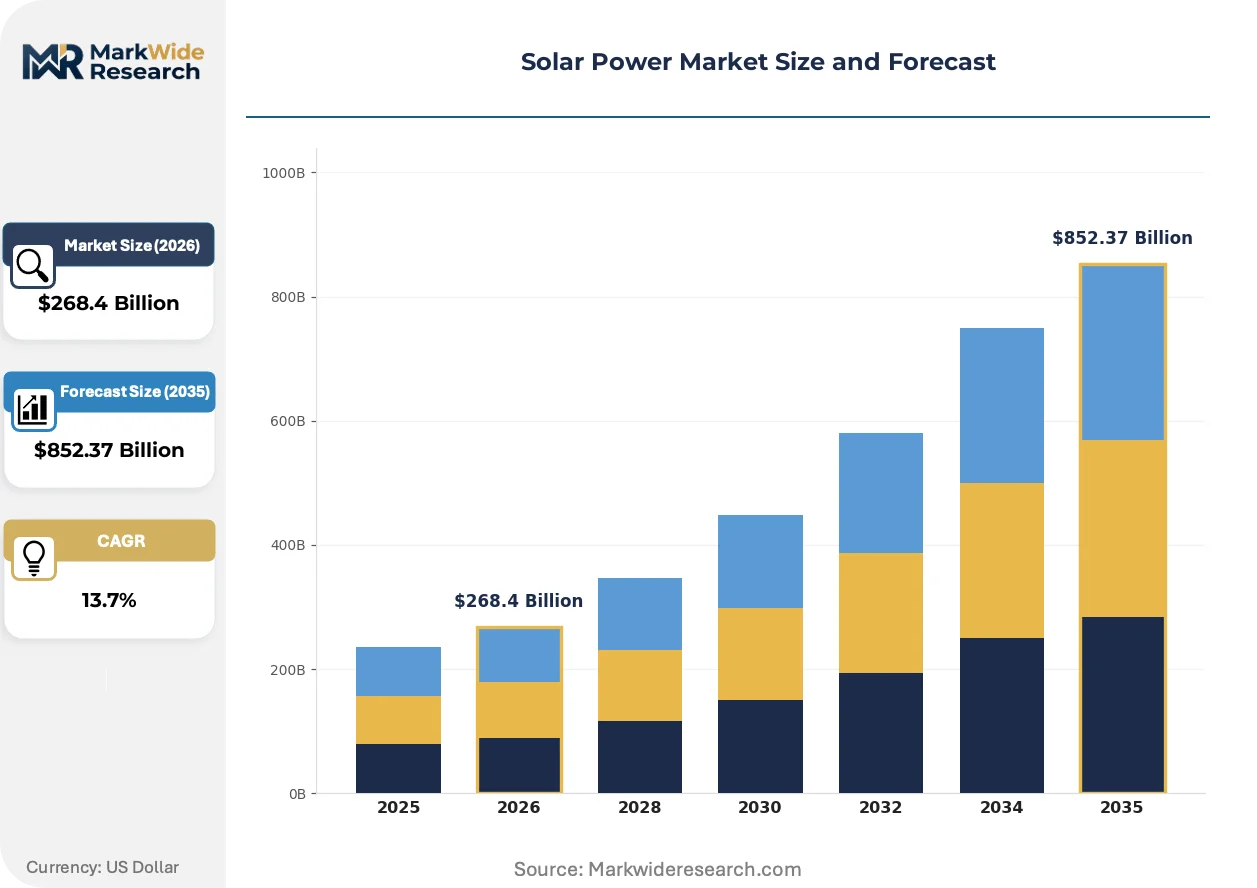
Market Dynamics
Strategic tension between national industrial policies and concentrated global manufacturing defines the market structure. The US Inflation Reduction Act's incentives for domestic production directly challenge the established dominance of China's polysilicon and wafer supply chains, influencing global project economics.
Growth Catalysts
- Policy Mandates:The EU Green Deal establishes ambitious renewable energy targets, compelling member states to accelerate solar capacity deployment through supportive regulatory frameworks and investment incentives for both utility and distributed generation projects.
- Technology Efficiency Gains:The superior energy conversion efficiency of monocrystalline silicon panels continues to drive their adoption, particularly in residential and commercial rooftop applications where spatial constraints make power density a critical factor.
- Utility-Scale Development:Demand for large-scale power purchase agreements from independent power producers and utilities fuels the expansion of massive solar farms, which benefit from economies of scale in construction and operation.
Market Restraints
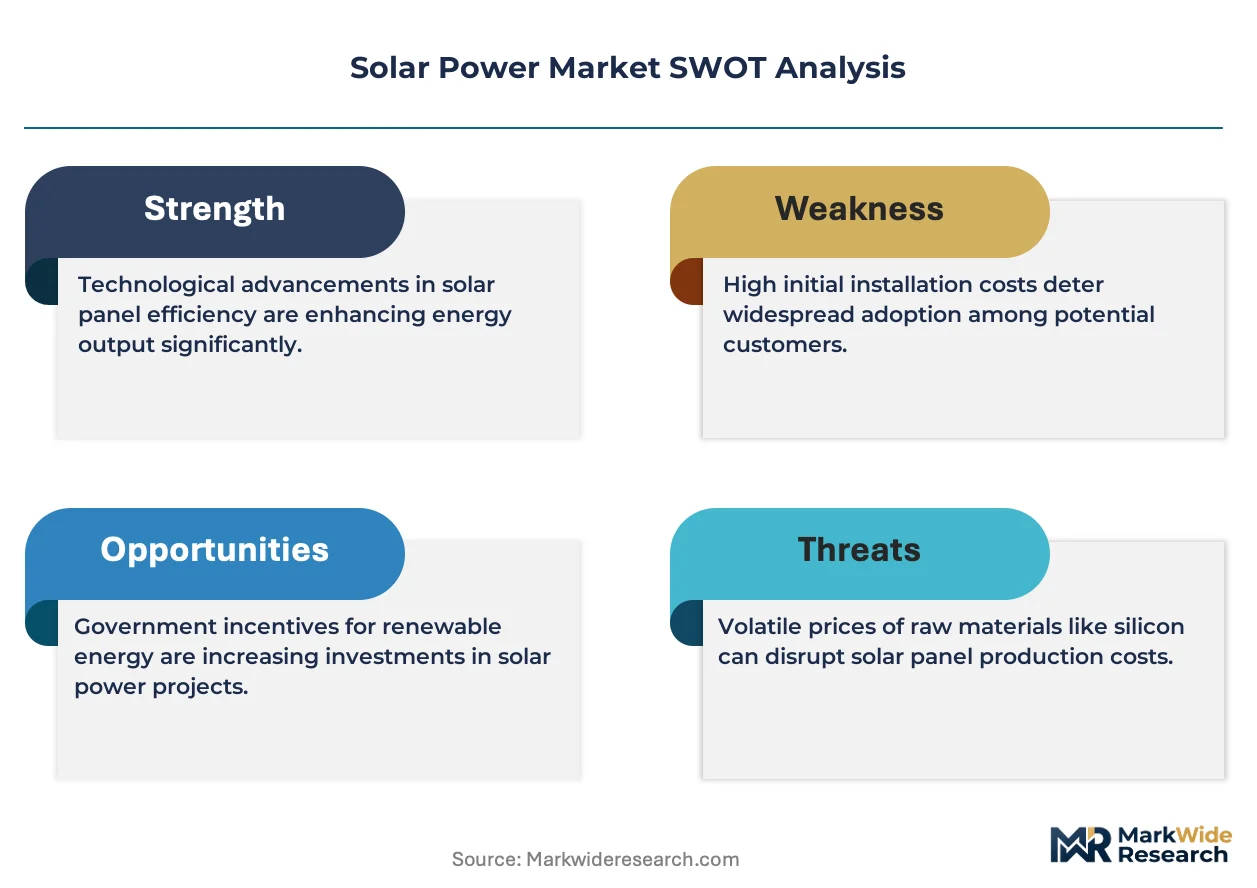
- Supply Chain Concentration:Heavy reliance on a single country for the majority of the world's polysilicon and wafer production creates significant price volatility and supply chain risk for global module manufacturers and project developers.
- Grid Integration Hurdles:The intermittent nature of solar generation necessitates substantial investment in grid modernization and energy storage solutions to maintain system stability, which can delay or increase the cost of new solar interconnections.
- Permitting Timelines:Inconsistent and protracted local permitting and environmental review processes for new solar installations act as a significant administrative barrier, slowing project development timelines and increasing soft costs.
Strategic Opportunities
- Agri-voltaics Implementation:Co-locating solar panels on agricultural land offers a dual-use model that enhances land productivity and creates new revenue streams, an approach gaining traction in land-constrained countries like Japan and Germany.
- Emerging Market Expansion:Rapidly growing economies in Southeast Asia and Africa represent significant untapped markets for solar deployment, driven by rising electricity demand, falling hardware costs, and improving policy support for renewables.
- Solar-Plus-Storage Integration:Coupling solar assets with battery energy storage systems (BESS) creates dispatchable power resources that can provide grid services, enhancing project revenue potential and addressing intermittency concerns for grid operators.
Industry Challenges
- Skilled Labor Deficits:A shortage of technicians trained in advanced diagnostics, software-based performance optimization, and the maintenance of complex utility-scale solar assets constrains the operational efficiency of the growing installed base.
- Trade Policy Navigation:Component manufacturers and developers must navigate an evolving landscape of trade tariffs, sanctions, and local content requirements, which complicates global sourcing strategies and can disrupt supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Power Market |
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $852.37 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Concentrated Solar Power, Thin-Film Modules, Bifacial Modules, Solar Trackers Technology: Monocrystalline, Polycrystalline, Cadmium Telluride, Copper Indium Gallium Selenide, Perovskite Application: Residential, Commercial, Utility-Scale, Agricultural, Telecommunications End User: Independent Power Producers, Commercial Enterprises, Government Agencies, Rural Electrification Providers, Energy Cooperatives |
| Companies Covered | JinkoSolar, Trinasolar, JA Solar, LONGi, First Solar, Canadian Solar, Hanwha Qcells, NextEra Energy, Tongwei Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Power Market Strategic Shifts & Innovations
The solar power sector is transitioning from a focus on component manufacturing and installation to a more sophisticated model. This evolution prioritizes asset performance optimization, grid integration, and the digitalization of energy production and management systems to maximize long-term value.
Perovskite-on-silicon tandem cells are an emerging technology that layers a perovskite film over a traditional silicon base to capture a wider spectrum of light. Research institutions and leading manufacturers are accelerating pilot production to validate long-term durability. This approach is unifying the high-efficiency potential of novel materials with the established, scaled manufacturing infrastructure of silicon, promising a significant leap in panel power density without overhauling production lines.
China's dual carbon goals provide a powerful top-down mandate for massive renewable energy deployment across the country. This policy framework directly stimulates investment in both large-scale solar farms in western provinces and distributed generation projects in eastern industrial hubs. The policy most affects state-owned energy enterprises, which are accelerating procurement of high-efficiency modules to meet aggressive government-set capacity targets and decarbonization timelines.
Corporate procurement of renewable energy is moving beyond simple power purchase agreements toward more complex virtual power purchase agreements and direct equity investments in new projects. This model disintermediates some traditional utility sales channels, allowing large corporations to directly finance the construction of new solar capacity. This trend is most prominent in the United States and Europe, led by major technology and retail companies seeking to meet sustainability goals.
Solar Power Market Segmentation
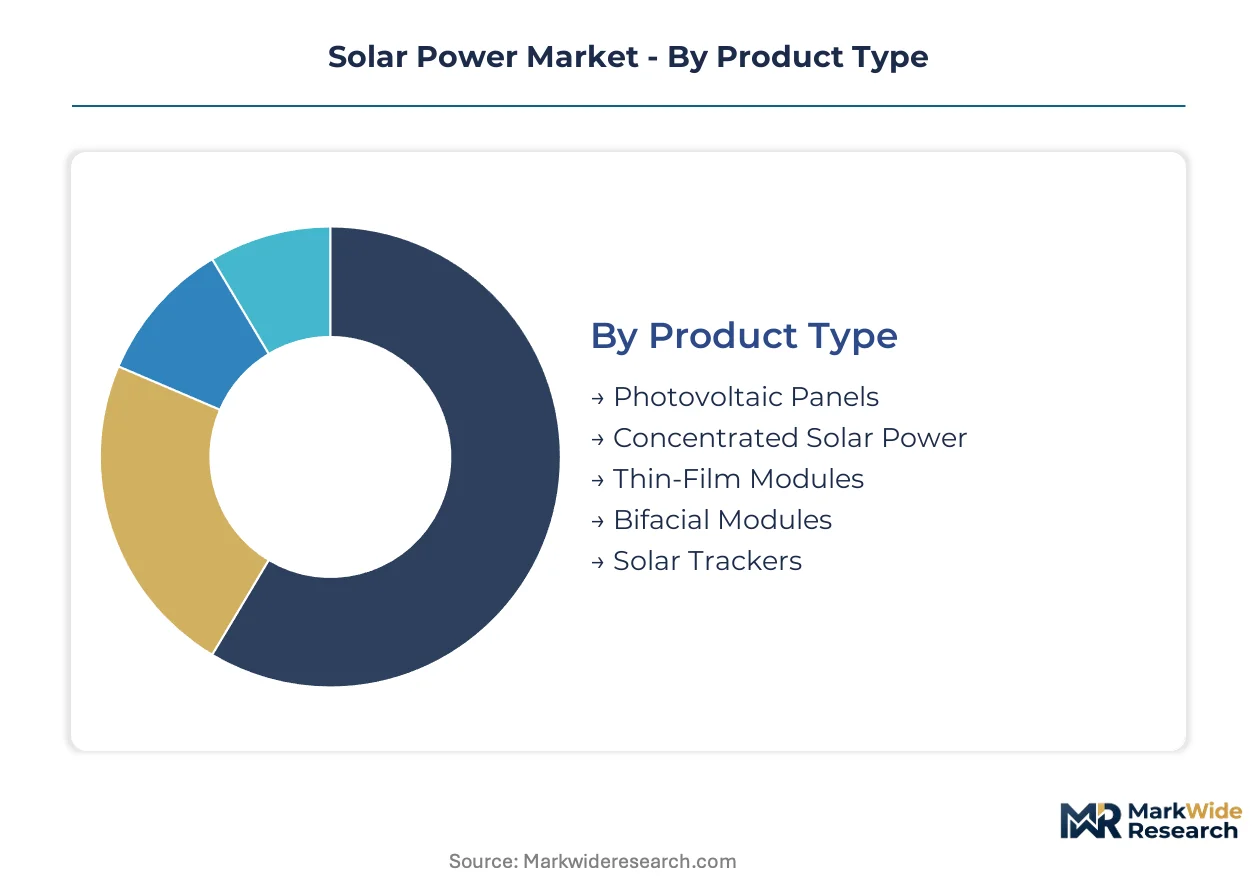
The Solar Power Market's structure reflects diverse technological approaches and varied end-user requirements. Understanding these distinct segments is critical for assessing market dynamics, identifying specific growth pockets, and tailoring project development strategies across different regions.
Product Type:
The choice of product type often differentiates buyers based on efficiency demands, land availability, and specific project scale requirements.
- Photovoltaic Panels:These convert sunlight directly into electricity using the photovoltaic effect, primarily through crystalline silicon wafers. Demand concentrates in large utility-scale projects and residential rooftop installations due to their proven reliability and efficiency.
- Bifacial Modules:These panels capture sunlight from both their front and rear surfaces, increasing total energy yield by up to 30% compared to monofacial modules. Projects in arid regions and ground-mounted utility sites in China and the United States favor these for enhanced power density.
- Concentrated Solar Power:This technology focuses sunlight onto a receiver to convert solar energy into heat, often using mirrors.
- Thin-Film Modules:Thin layers of semiconductor material deposited on a substrate form these panels, offering flexibility and lower manufacturing costs.
- Solar Trackers:Mechanical devices that orient solar panels towards the sun throughout the day optimize energy capture and system output.
Volume sits with Photovoltaic Panels; growth tilts toward Bifacial Modules.
Technology:
Technological choices are often driven by project application, available space, and the desired energy conversion efficiency of the solar system.
- Monocrystalline:These panels utilize single-crystal silicon, providing high efficiency ratings and a uniform dark appearance. Residential and commercial rooftop installations in Germany and Japan prefer monocrystalline for maximizing power output in limited spaces.
- Perovskite:This emerging technology layers a perovskite film over a traditional silicon base, allowing for a wider spectrum of light capture and higher theoretical efficiencies. Research institutions and manufacturers in South Korea and the United States are accelerating pilot production.
- Polycrystalline:Multi-crystal silicon forms these panels, providing a cost-effective option with slightly lower efficiency than monocrystalline.
- Cadmium Telluride:Cadmium Telluride thin-film panels perform well in hot climates and require less energy for manufacturing.
- Copper Indium Gallium Selenide:This flexible thin-film technology performs well in low-light and offers aesthetic versatility for building-integrated photovoltaics.
Monocrystalline technology currently dominates; Perovskite technology is expanding most quickly.
Application:
Different applications cater to distinct customer types, each with unique energy demands, regulatory frameworks, and installation complexities.
- Utility-Scale:These are large, centralized solar farms that generate electricity for the grid, often involving extensive land use and power purchase agreements. Independent power producers and state-owned energy enterprises in China and the United States heavily invest in utility-scale projects.
- Residential:This segment includes solar panel installations on individual homes, primarily for self-consumption and reducing household electricity bills. Homeowners in Australia and California increasingly adopt residential systems due to favorable net metering policies.
- Commercial:Solar installations on business premises, including offices and factories, offset operational costs and meet sustainability targets.
- Agricultural:Agri-voltaics co-locates solar panels on agricultural land, enabling dual use for crop cultivation and energy generation.
- Telecommunications:Solar power provides reliable off-grid electricity for remote cell towers and communication infrastructure.
Utility-scale projects command the largest share of capacity, while residential applications show significant distributed growth.
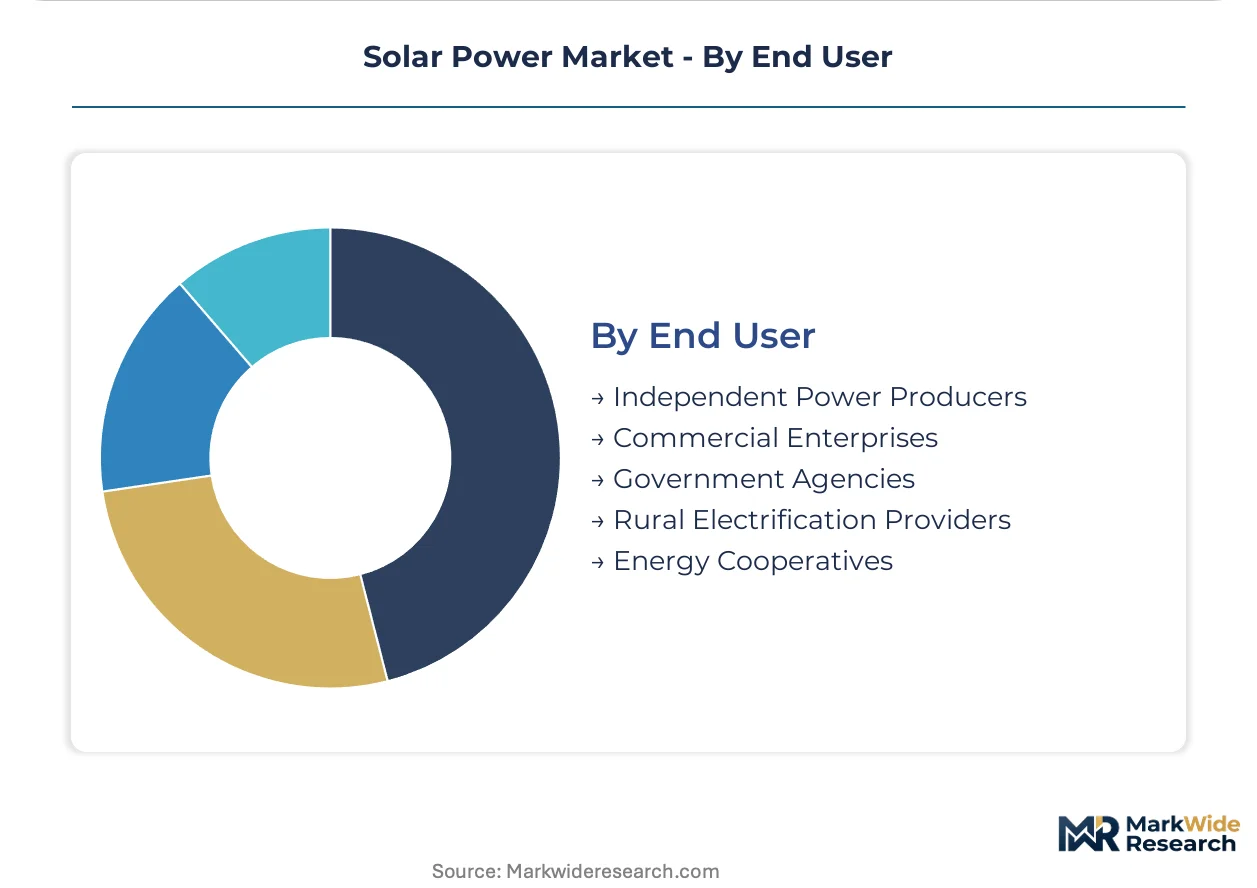
End User:
End-user segments are differentiated by the volume of electricity procured, their investment motivations, and their operational scale.
- Independent Power Producers:These entities specialize in developing, owning, and operating power generation facilities, selling electricity to utilities or directly to large consumers. IPPs are the primary drivers of large-scale solar farm development, particularly in India and Brazil.
- Commercial Enterprises:Businesses of various sizes procure solar energy to reduce operating expenses, enhance corporate sustainability profiles, and ensure energy independence. Major technology and retail companies in Europe and the United States frequently engage in corporate power purchase agreements.
- Government Agencies:Public sector bodies use solar power for government buildings, public infrastructure, and national renewable energy mandates.
- Rural Electrification Providers:These organizations bring electricity to underserved or off-grid communities, often relying on distributed solar solutions.
- Energy Cooperatives:Member-owned organizations invest in solar projects to provide affordable, clean energy and enhance local resilience.
Independent Power Producers represent the largest procurement segment, with Commercial Enterprises rapidly increasing their solar investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The solar power market exhibits a distinct production-versus-consumption dynamic, with manufacturing heavily concentrated in a few Asian countries while deployment and project development span diverse global economies. This structural divide influences trade flows and investment patterns across continents. Policy frameworks and energy demand drive regional expansion, shaping local market characteristics.
China
China leads global solar installations, driven by aggressive renewable energy targets and expanding utility-scale demand. The nation's dual carbon goals mandate significant investment in solar capacity, particularly for state-owned energy enterprises. Western provinces host massive solar farms, while eastern industrial hubs focus on distributed generation projects.
United States
Utility-scale projects and corporate procurement propel solar demand across the United States. The Inflation Reduction Act (IRA) provides substantial incentives for domestic manufacturing and project development. California leads in residential installations due to favorable net metering policies, while Texas expands large-scale solar farms.
Germany
Germany prioritizes monocrystalline silicon panels for residential and commercial rooftop applications, maximizing power output in limited urban spaces. The EU Green Deal and national feed-in tariffs support extensive solar deployment. Bavaria exhibits high rooftop installation rates, and agricultural regions increasingly adopt agri-voltaics.
Japan
Japan focuses on high-efficiency monocrystalline panels and innovative land-use models like agri-voltaics in its land-constrained environment. Policies from METI encourage renewable energy adoption and grid integration. The Kanto region sees significant rooftop and commercial solar development, with agri-voltaics gaining traction in rural areas.
Brazil
Brazil experiences strong demand for large-scale solar farm development, primarily driven by independent power producers. Regulations from ANEEL and renewable energy auctions stimulate investment in utility-scale projects. Minas Gerais stands out for its numerous solar farms, leveraging high solar irradiance in the Northeast region.
Solar Power Market Key Industry Players
Top-tier vendors anchor the global manufacturing segment, while a diverse array of regional developers and specialized service providers address local market needs. The competitive landscape features global scale manufacturers, integrated technology leaders, and utility-scale asset operators as primary archetypes. Companies pursue capacity expansion and strategic partnerships to secure market share and optimize supply chains.
Within the global manufacturing archetype, JinkoSolar and Trinasolar exemplify companies leveraging extensive global manufacturing scale and broad distribution networks across multiple continents. First Solar, in contrast, represents an integrated technology leader, emphasizing thin-film technology leadership and domestic manufacturing capabilities in the United States. NextEra Energy occupies a unique position as a vast utility-scale solar asset operator, influencing procurement standards and driving large-scale project development.
| Leading Market Players |
|---|
| JinkoSolar |
| Trinasolar |
| JA Solar |
| LONGi |
| First Solar |
| Canadian Solar |
| Hanwha Qcells |
| NextEra Energy |
| Tongwei Co. Ltd |
| Others |
Cost & Logistics Intelligence
Independent Power Producers, often financed by institutional capital, heavily influence solar project economics, driving demand for cost-effective modules and predictable long-term pricing. Their project-based financing structures prioritize supply stability.
Pricing Analysis
Price erosion across photovoltaic modules traces to manufacturing overcapacity in China and continuous efficiency gains. The dominant pricing model for utility-scale projects remains contract-based long-term power purchase agreements, emphasizing predictable levelized cost of energy. Differentiation drivers include module efficiency ratings, brand reputation, and geographic delivery logistics. Independent Power Producers exhibit high price sensitivity, while residential customers prioritize overall system performance and aesthetic integration.
Supply Chain Analysis
Domestic content requirements, such as those within the US Inflation Reduction Act, are reshaping global solar sourcing strategies. The supply chain heavily concentrates in China for polysilicon, wafers, and module manufacturing, creating single-source vulnerability. Key raw material dependencies include high-purity polysilicon and processed silicon wafers. Distribution runs through direct channels for large utility-scale developers and extensive networks of installers for residential and commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar power market is evolving into a vertical-integration race, as key players pursue control over module manufacturing and downstream project development. This strategy aims to capture greater value across the entire asset lifecycle.
For Market Incumbents: Lock in long-term raw material supply agreements, particularly for polysilicon, to mitigate commodity price volatility. Invest in advanced manufacturing capabilities for high-efficiency technologies like perovskite-on-silicon tandem cells to counter emerging low-cost competitors. Leverage robust software platforms for predictive maintenance and energy yield optimization to enhance asset performance. Expanding domestic manufacturing in strategic regions, supported by incentives like the IRA, secures market access.
For New Entrants and Emerging Players: Begin with niche applications such as agri-voltaics or integrated solar-plus-storage solutions, offering distinct value propositions. Target rapidly growing economies in Southeast Asia and Africa, where electricity demand is rising and policy support for renewables is improving. Focus on delivering comprehensive solutions that combine high-efficiency hardware with advanced energy management software. Emphasize localized supply chains and project development expertise to gain market traction.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated project developers with strong permitting pipelines in the United States and Europe. The long-term viability of solar assets remains compelling over the next decade, driven by decarbonization mandates. Identify specialized software providers focused on asset performance optimization or grid integration as strategic acquisition targets. The signal to watch is sustained investment in grid modernization and energy storage infrastructure, indicating improved dispatchability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Enhances supply chain resilience and capitalizes on domestic content incentives. |
| Vertical Integration into Storage | Creates dispatchable power resources, addressing solar intermittency for grid operators. |
| Technology Licensing | Accelerates adoption of next-generation high-efficiency photovoltaic materials. |
| Software Platform Development | Optimizes energy yield and predictive maintenance for large-scale solar farms. |
| Agri-voltaics Project Development | Unlocks new land-use models, increasing land productivity in constrained regions. |
Research Approach
Independent corroboration across industry reports, government publications, and company filings underwrites the qualitative findings. Primary interviews with Independent Power Producer executives, module manufacturers, EPC contractors, and utility planning officers provided critical market insights. Secondary data sources included EIA, IEA, and FERC filings, combined with project development databases. This approach ensured robust bottom-up and top-down triangulation of market intelligence.
Rate-of-change decomposition formed the analytical framework to project market evolution across the analysis window. The study modeled segmentation dimensions including product type, technology, application, end-user, and regional policy frameworks. Compound Annual Growth Rates were derived from historical trends and projected market drivers, such as policy support from the IRA and continuous technology efficiency gains. This framework provided a comprehensive outlook.
Underlying measurement precision varies by segment; utility-scale and monocrystalline technology carry tighter precision than emerging perovskite or agri-voltaics. Forecasts reflect assumptions regarding current policy environments and technology adoption rates; trade policy shifts or grid integration challenges represent key risk factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Europe Solar Charging Station Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Global Photovoltaic Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
Canada Distributed Solar Power Generation Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
PERC Solar Panels Market
Solar Power Systems
Ground Mount PV Utility Market
Solar Power Systems
Global Solar PV Balance of System Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Polycrystalline Solar Cell Market
Solar Power Systems
Portugal Solar Energy Market