
 Optical Solar Reflectors Market | 2026-2036
Optical Solar Reflectors Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Solar Reflectors Market Insights
Buyer concentration among satellite prime contractors is shifting as commercial constellation operators fragment procurement across specialized suppliers. Excelitas Technologies Corp. leverages its heritage in aerospace photonics to sustain long-term contracts with defense integrators. Qioptiq Space Technology anchors European supply chains through precision optical manufacturing capabilities. RUAG Group competes by extending its satellite component portfolio across multiple thermal management subsystems.
Optical solar reflectors are precision-engineered surfaces, typically comprising silvered or aluminized thin films deposited on glass, metal, or polymer substrates, designed to reject incident solar radiation while maintaining stable thermal emissivity in vacuum environments. Their primary purpose is passive thermal control of spacecraft, instruments, and solar energy collection systems operating under extreme orbital temperature differentials. Glass-based reflective substrates dominate mission-critical space applications where outgassing resistance and radiation hardness command premium positioning, while coated metal alternatives gain traction in terrestrial concentrated solar power installations where cost scalability matters. The technology dimension splits between reflective films, which occupy established satellite heritage programs, and textured surfaces, where emerging fabrication methods are displacing legacy approaches in next-generation collector designs.
NASA technical standards, ESA ECSS specifications, and ISO 15388 space systems protocols collectively govern material qualification, coating adhesion, and thermal cycling endurance for flight-qualified optical solar reflectors. These frameworks create barriers for unqualified suppliers while channeling R&D investment toward radiation-resistant coating chemistries and substrate lightweighting. Stakeholders must monitor evolving debris mitigation rules and green propulsion transitions that will reshape satellite bus thermal budgets and reflector specification requirements.
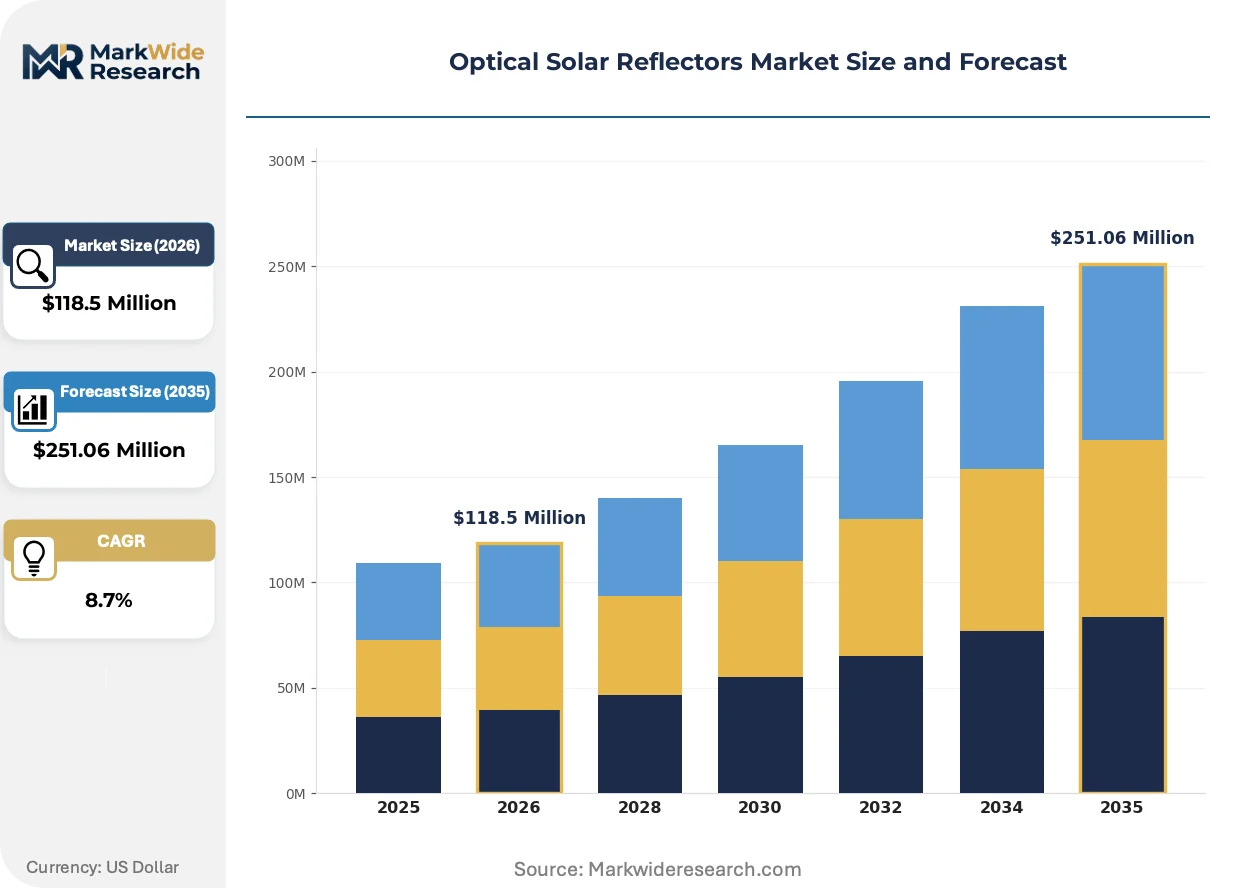
Market Dynamics
Commercial constellation operators are fragmenting procurement across specialized suppliers, breaking the historical lock that satellite prime contractors held over thermal control component sourcing. This demand-side dispersion is forcing reflector manufacturers to recalibrate qualification investments and volume pricing structures.
Growth Catalysts
- ESA ECSS cleanliness standards:Tightening material qualification protocols across European space agency programs are elevating technical barriers that heritage-qualified suppliers exploit to secure multi-year thermal control contracts.
- Thin-film coating innovations:Advances in sputtered silver-aluminum multilayers are reducing substrate mass while preserving optical performance, enabling payload capacity gains for low Earth orbit satellite operators.
- Germany:Concentrated prime contractor activity around Munich and Bremen is anchoring specialized supply chains for precision optical manufacturing serving institutional and commercial missions.
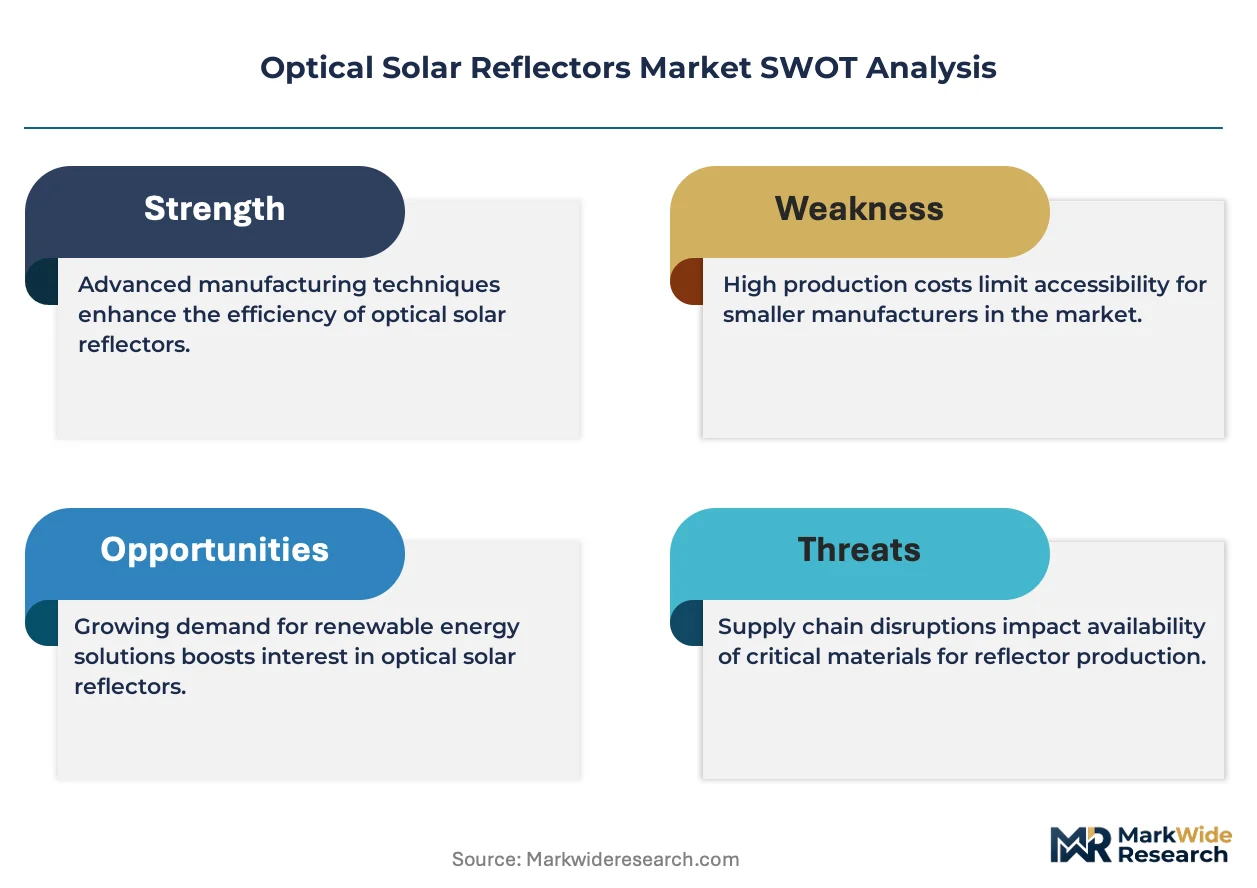
Market Restraints
- Silver price volatility:Primary reflective coating material costs fluctuate with commodity markets, compressing margins for fixed-price satellite component contracts.
- Heritage supplier concentration:Decades-long qualification timelines have entrenched a small cohort of flight-proven vendors, limiting competitive entry regardless of technical capability.
- Glass substrate mass penalty:Radiation-hardened borosilicate alternatives remain heavier than polymer options, constraining adoption in mass-constrained small satellite platforms.
Strategic Opportunities
- Japan:Underdeveloped commercial reflector supply chains relative to institutional space agency demand create openings for qualified European and North American entrants.
- Terrestrial concentrated solar power:Cost-tolerant ground-based thermal collection systems offer volume scaling absent the qualification overhead of spaceflight applications.
- Dual-use thermal management:Convergence of satellite bus architectures with high-altitude platform station designs is creating cross-application component standards.
Industry Challenges
- Cleanroom technician scarcity:Specialized thin-film deposition expertise resides with aging workforces in Germany and the United States, constraining production scaling.
- ISO 15388 certification timelines:Thermal cycling and radiation exposure testing protocols extend qualification cycles to 18-24 months, delaying revenue recognition for new product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Solar Reflectors Market |
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $251.06 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Metal, Coatings Application: Solar Thermal Systems, Photovoltaic Panels, Concentrated Solar Power, Heat Collection Technology: Reflective Films, Coated Panels, Textured Surfaces, Specialized Fabrics End User: Residential, Commercial, Industrial, Government |
| Companies Covered | Excelitas Technologies Corp., Rayotek Scientific, Qioptiq Space Technology, Optiforms, Surface Optics Corporation, RUAG Group, AZ Technology Corporation, AccuCoat Inc., Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Solar Reflectors Market Trends and Innovations
Reflective surface engineering is pivoting from heritage glass substrates toward multifunctional material systems that integrate thermal control with structural load-bearing. Fabrication methods and qualification frameworks are simultaneously evolving to accommodate these hybrid architectures.
Textured surface micromachining is converging with additive manufacturing workflows to produce integrated reflector-heat spreader assemblies. Small satellite bus manufacturers in the United States are adopting these consolidated components to reduce part count and assembly labor. The technology is converging with legacy thin-film deposition equipment, forcing capital equipment suppliers to develop hybrid process chambers.
REACH substance restrictions are phasing out legacy chromate conversion coatings used in aluminum substrate preparation. European reflector manufacturers must reformulate surface pretreatment chemistries or shift to stainless steel alternatives. German precision optics clusters are responding fastest, with Bremen-based suppliers already certifying replacement coating systems.
Constellation operators are unbundling thermal control procurement from prime satellite contracts, establishing direct supplier relationships for standardized reflector assemblies. This disintermediation compresses pricing transparency but extends payment terms. The pattern is most pronounced among United States-based commercial low Earth orbit ventures with vertically integrated satellite manufacturing facilities.
Optical Solar Reflectors Market Segmentation
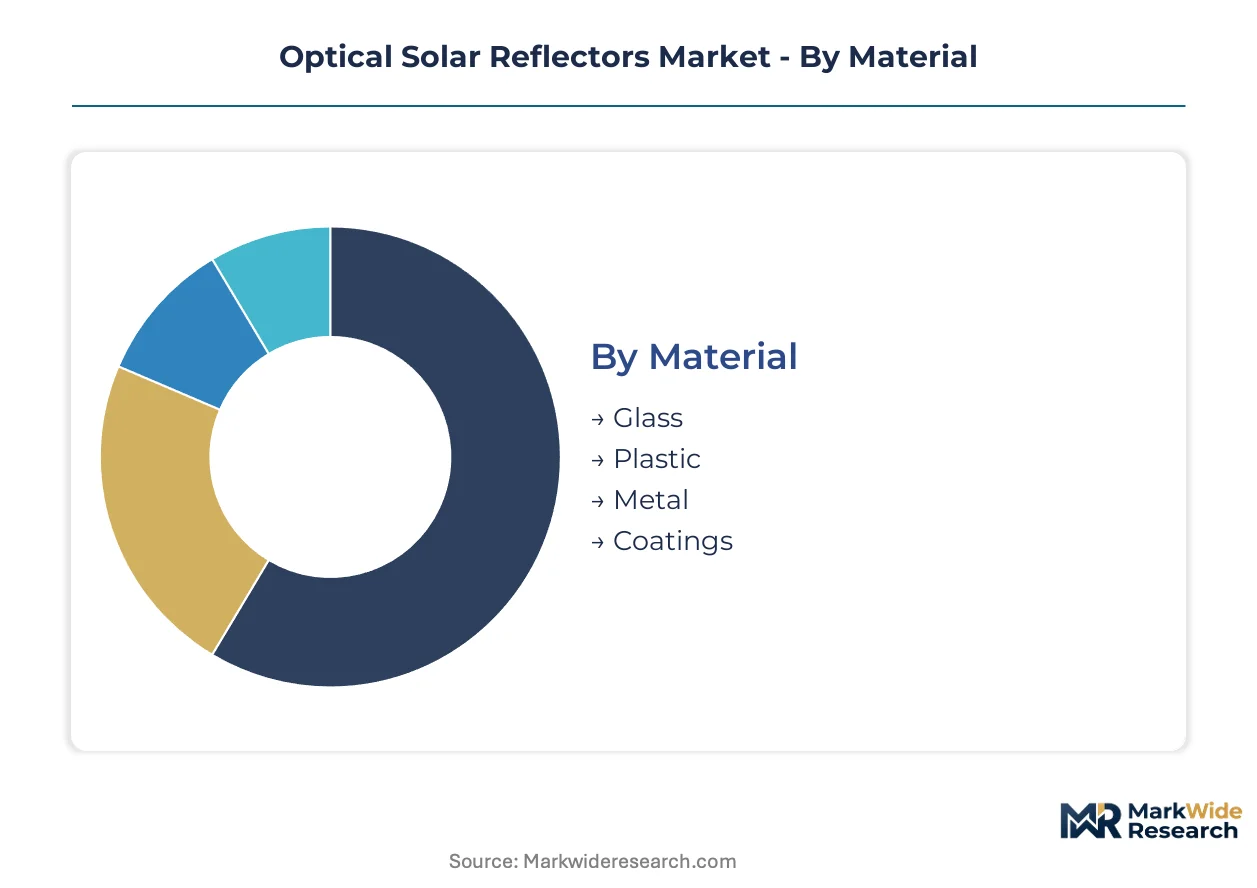
Optical solar reflector procurement splits across material heritage, application thermal budgets, and qualification requirements. Satellite prime contractors and concentrated solar power developers prioritize different performance thresholds, creating parallel demand tracks with minimal supplier overlap.
Material:
Upgrade cycles in space-qualified thermal control are extending substrate replacement timelines, forcing manufacturers to balance radiation hardness against mass penalties in new designs.
- Glass:Borosilicate and fused silica substrates carry flight heritage across ESA and NASA missions, with silvered or aluminized thin-film stacks delivering stable emissivity across extreme orbital temperature differentials. Procurement concentrates in Germany and the United States where cleanroom deposition facilities cluster around Bremen and Denver aerospace corridors; ESA ECSS cleanliness standards tighten qualification barriers that entrench incumbent suppliers.
- Metal:Aluminum and stainless steel substrates with sputtered reflective coatings offer mass reductions critical for small satellite constellations, though radiation-induced optical degradation limits mission duration. Demand is climbing fastest among United States-based commercial low Earth orbit operators retrofitting thermal control onto standardized bus designs; silver price volatility compresses margins on fixed-price component contracts.
- Plastic:Polymer substrates with vapor-deposited metallic films serve terrestrial concentrated solar power installations where cost scalability outweighs space-grade durability requirements.
- Coatings:Standalone reflective chemistries—silver-aluminum multilayers, dielectric stacks, and protective overcoats—enable substrate-agnostic procurement for hybrid thermal control architectures.
Volume placements concentrate in Glass; the faster expansion belongs to Metal.
Application:
Cost tier differentiation separates mission-critical spaceflight contracts from price-sensitive terrestrial energy installations, with thermal budget specifications diverging by an order of magnitude.
- Concentrated Solar Power:Utility-scale thermal collection fields in Spain and the United States deploy silvered glass reflector assemblies with automated washing systems, prioritizing optical efficiency degradation curves over decades-long operational life. Procurement runs through engineering-procurement-construction contractors with captive supply agreements; ground-based qualification overhead is negligible compared to spaceflight applications.
- Solar Thermal Systems:Residential and commercial water heating installations across Japan and Germany utilize lower-specification reflective surfaces where polymer-metal laminates displace glass for weight and handling advantages. Demand clusters in municipal district heating retrofits and industrial process heat applications; REACH substance restrictions are phasing legacy chromate conversion coatings from European supply chains.
- Photovoltaic Panels:Bifacial solar module manufacturers incorporate reflective backsheet materials to boost energy yield through albedo capture, though this competes with dedicated reflector procurement.
- Heat Collection:Industrial waste heat recovery and process thermal management systems employ customized reflector geometries with limited standardization across end-use verticals.
Revenue concentration sits with Concentrated Solar Power; Solar Thermal Systems are climbing the fastest.
Technology:
Customer type fragmentation—institutional space agencies versus commercial constellation operators—drives divergent technology maturation timelines and qualification investment thresholds.
- Reflective Films:Thin-film deposition of silver, aluminum, and dielectric multilayers onto flexible or rigid substrates dominates established satellite heritage programs, with sputtering and evaporation processes governed by ISO 15388 thermal cycling protocols. Supply concentrates in German precision optics clusters serving ESA institutional missions; cleanroom technician scarcity constrains production scaling.
- Textured Surfaces:Micromachined and additive-manufactured reflector-heat spreader assemblies integrate thermal control with structural load-bearing, reducing part count for small satellite bus manufacturers. Adoption is accelerating among United States-based vertically integrated constellation operators; hybrid process chambers merge legacy thin-film equipment with directed energy deposition workflows.
- Coated Panels:Pre-fabricated reflective assemblies with standardized dimensions serve terrestrial solar thermal and concentrated solar power installations with minimal customization.
- Specialized Fabrics:Metallized polymer textiles deploy in deployable space structures and temporary terrestrial installations where conformability and packaging efficiency override optical precision.
Heritage procurement favors Reflective Films; Textured Surfaces gain share fastest.
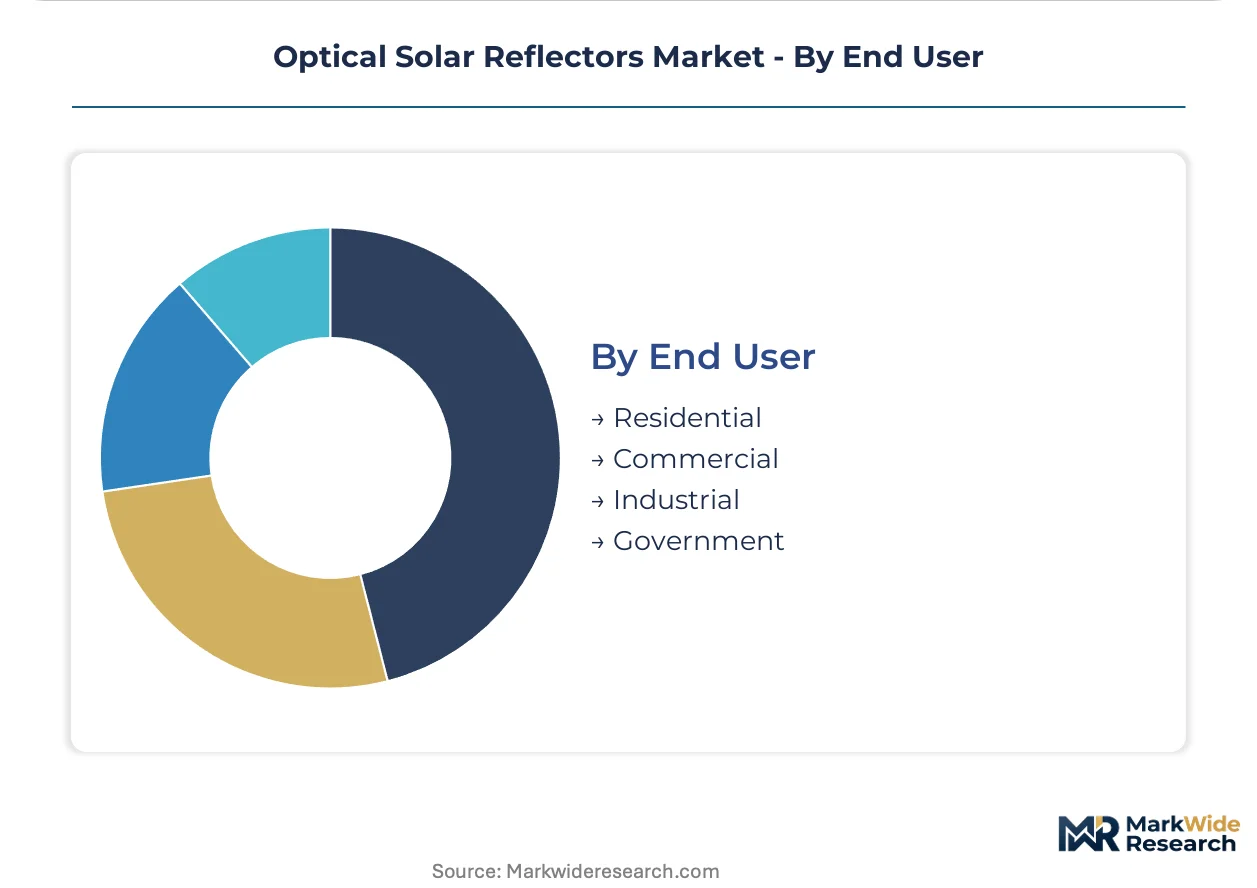
End User:
Margin structures vary dramatically across customer categories, with government space agency contracts commanding premium pricing for qualification documentation and commercial industrial buyers driving standardization.
- Government:National space agencies and defense integrators in the United States, Germany, and Japan specify flight-qualified optical solar reflectors with complete material pedigree and radiation test documentation. Procurement cycles extend 18-24 months through ISO 15388 certification timelines; NASA technical standards and ESA ECSS specifications create vendor lock-in for heritage-qualified suppliers.
- Industrial:Process heat and concentrated solar power developers in Spain, the United States, and China prioritize cost-per-unit-area metrics and field-replaceability over optical precision tolerances. Volume procurement runs through engineering contractors with multi-site installation portfolios; pricing transparency compresses as constellation operators disintermediate prime satellite contractors.
- Commercial:Distributed solar thermal and building-integrated applications generate fragmented demand with limited supplier consolidation opportunities.
- Residential:Small-scale water heating and architectural reflector applications represent marginal revenue with high customer acquisition costs.
Contract value concentrates in Government; Industrial placements are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prime contractor procurement in Germany, the United States, and Japan anchors thermal control component demand, while satellite constellation operators fragment sourcing across specialized regional suppliers.
United States
Commercial low Earth orbit ventures and defense integrators drive reflector procurement through Denver and California aerospace corridors. NASA technical standards govern flight qualification timelines extending 18-24 months. Vertically integrated constellation operators in the Pacific Northwest and Southwest are disintermediating traditional prime contractors to establish direct supplier relationships.
Germany
ESA institutional missions and precision optics manufacturing concentrate demand around Bremen and Munich industrial clusters. REACH substance restrictions are phasing legacy chromate conversion coatings from aluminum substrate preparation. Bremen-based suppliers are certifying replacement coating systems ahead of European competitors.
Japan
Underdeveloped commercial reflector supply chains relative to institutional space agency demand create market openings. METI industrial policy supports domestic satellite component manufacturing capabilities. Tokyo and Nagoya precision manufacturing bases anchor thermal control system integration for JAXA missions.
United Kingdom
Defense and scientific satellite programs sustain procurement through established supply relationships with European reflector manufacturers. UK Space Agency funding for small satellite initiatives is diversifying component sourcing. Harwell and Glasgow space clusters are developing local thermal control assembly capabilities.
Switzerland
High-precision optics heritage and neutrality positioning attract dual-use thermal control contracts from institutional and commercial satellite operators. Swissmedic-equivalent space material standards align with ESA ECSS specifications. Zurich and Geneva precision manufacturing regions supply specialized coating services to German prime contractors.
Optical Solar Reflectors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue textured surface manufacturing and terrestrial solar thermal applications. The vendor base stratifies across heritage-qualified spaceflight suppliers and cost-optimized ground-system fabricators. Three archetypes dominate: precision optics specialists with ESA/NASA qualification heritage, diversified aerospace conglomerates extending satellite component portfolios, and thin-film deposition houses pivoting from terrestrial optical coatings. Capacity expansion and strategic partnerships represent the dominant competitive moves, as qualification timelines constrain rapid market entry.
Among North American heritage-qualified suppliers, Excelitas Technologies Corp. and AZ Technology Corporation exemplify the precision optics archetype with established defense integrator relationships. Qioptiq Space Technology anchors the European tier through its German manufacturing base and ESA program heritage. RUAG Group occupies a diversified aerospace position spanning multiple thermal management subsystems. These three entities represent distinct strategic postures: photonics heritage, regional supply chain anchoring, and portfolio breadth across satellite bus components.
| Leading Market Players |
|---|
| Excelitas Technologies Corp. |
| Rayotek Scientific |
| Qioptiq Space Technology |
| Optiforms |
| Surface Optics Corporation |
| RUAG Group |
| AZ Technology Corporation |
| AccuCoat Inc. |
| Northrop Grumman Corporation |
| Others |
Pricing and Supply Chain Analysis
Satellite prime contractors in Germany, the United States, and Japan concentrate procurement authority, anchoring contract-based long-term offtake pricing that locks in multi-year thermal control component supply. This buyer concentration enables heritage-qualified suppliers to command premium positioning for flight-proven reflective assemblies while compressing margins for unqualified entrants seeking initial certification.
Pricing Analysis
High-volume terrestrial concentrated solar power installations trade margin for scale, while low-volume space-qualified reflectors sustain premium-mid-economy pricing differentiation anchored in ISO 15388 certification tiers. Price differentiation hinges on radiation test documentation completeness and ESA ECSS cleanliness compliance grade. Pricing pressure stems from silver commodity volatility feeding into fixed-price satellite component contracts. Commercial constellation operators exhibit highest price sensitivity as they disintermediate traditional prime contractors; government space agencies show lowest sensitivity due to mission-critical reliability requirements.
Supply Chain Analysis
ISO 15388 and ESA ECSS qualification protocols gate supply chain entry, entrenching production in Germany, the United States, and Switzerland where cleanroom deposition facilities cluster around Bremen, Denver, and Zurich precision manufacturing corridors. Raw material dependencies center on silver sputtering targets, borosilicate glass substrates, and specialized aluminum alloys. Single-source vulnerability concentrates in aging cleanroom technician workforces with thin-film deposition expertise. Distribution runs through prime contractor procurement offices for space applications and engineering-procurement-construction contractors for terrestrial solar thermal installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optical solar reflector market sits at a technology-transition inflection as textured surface micromachining displaces legacy thin-film deposition for small satellite thermal control applications. Fabrication convergence with additive manufacturing workflows is compressing part counts and reshaping competitive entry barriers.
For Market Incumbents: Anticipate constellation operator disintermediation by deepening direct supplier relationships with vertically integrated commercial low Earth orbit ventures in the United States. Prioritize backward integration into sputtering target supply to buffer silver price volatility. Accelerate certification of replacement coating systems ahead of REACH substance restriction deadlines to defend ESA program positioning against German competitors.
For New Entrants and Emerging Players: Direct-to-satellite-manufacturer digital procurement platforms bypass heritage prime contractor gatekeeping for standardized reflector assemblies. Target Japan's underdeveloped commercial reflector supply chains where METI industrial policy supports domestic capability buildout. Pursue terrestrial concentrated solar power as a volume scaling entry point absent spaceflight qualification overhead.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precision optics specialists with dormant ESA qualification heritage in German manufacturing clusters. Long-term viability hinges on dual-use thermal management positioning spanning satellite buses and high-altitude platform stations. Monitor constellation operator procurement unbundling velocity as inflection signal for supplier margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Acceleration | Shortening ISO 15388 thermal cycling timelines captures constellation operator procurement windows before competitors. |
| Dual-Use Technology Development | Converging satellite bus architectures with high-altitude platform stations expands addressable thermal control markets. |
| Raw Material Integration | Captive silver sputtering target production insulates margins from commodity volatility in fixed-price contracts. |
| Terrestrial Market Pivot | Concentrated solar power installations offer volume scaling absent 18-24 month space qualification cycles. |
| Workforce Capability Building | Cleanroom technician training programs in Bremen and Denver address production scaling constraints. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with satellite thermal control engineers, ESA procurement officers, thin-film deposition technicians, and concentrated solar power project developers. Secondary sources encompassed NASA technical standards documentation, ESA ECSS specifications, ISO 15388 protocols, and customs records tracking silver sputtering target imports. Bottom-up segment sizing triangulated against top-down aerospace component spending estimates.
Granularity-level modeling operated at material substrate, application thermal budget, and qualification tier dimensions across the projection horizon. Segment-level CAGRs derived from satellite launch manifest projections and terrestrial solar thermal deployment pipelines. Industry-specific forecast inputs incorporated constellation operator fleet expansion schedules and REACH substance restriction implementation timelines.
The model holds under stable qualification protocol regimes; deviation in debris mitigation rule tightening or green propulsion thermal budget shifts would revise satellite bus reflector specifications. Forecasts reflect assumptions regarding silver price bands and cleanroom technician workforce availability. A model refresh is warranted upon material change in ESA institutional mission procurement cycles or commercial constellation operator vertical integration depth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
Belgium Solar Energy Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
High Concentration Photovoltaics Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Ecuador Solar Energy Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
Grid Connected PV Systems Market