
 Software Market | 2026-2036
Software Market Size, Share, and Industry Trends Forecast 2026-2036
Software Market Intelligence
The acute shortage of cloud-native DevOps engineers is redrawing competitive boundaries across the software industry. Microsoft leverages its Azure ecosystem to anchor enterprise workloads, while Amazon Web Services sustains infrastructure dominance through hyperscale data center expansion. Oracle differentiates its database-to-cloud migration portfolio for regulated industries.
Software comprises executable programs, data structures, and documentation that instruct computing hardware to perform specific tasks, typically distributed via compiled binaries or interpreted scripts with version-controlled release cycles. Its primary commercial purpose is automating business processes, enabling data-driven decision-making, and mediating digital transactions across organizational boundaries. Cloud-Based deployment captures the fastest expansion as enterprises retire on-premise data centers, while SaaS pricing models concentrate recurring revenue pools and reduce customer acquisition friction. Enterprise Resource Planning applications retain the largest installed base, though Customer Relationship Management segments show steeper growth curves in mid-market penetration.
FDA oversight of software-as-a-medical-device shapes product validation requirements for health-tech vendors, while EU AI Act risk classifications force algorithmic transparency disclosures across European deployments. FCC net-neutrality frameworks influence how cloud delivery networks architect bandwidth allocation. Stakeholders must monitor how NIST cybersecurity guidelines and emerging state-level privacy statutes in the US redefine liability for software supply chain breaches.
Market Dynamics
Cloud-native architecture migration is compressing enterprise software procurement cycles while EU AI Act compliance deadlines force algorithmic transparency investments across European deployments.
Growth Catalysts
- EU AI Act:Risk classification mandates for high-stakes algorithmic systems accelerate investment in explainable AI tooling and audit infrastructure across healthcare and financial services deployments.
- Healthcare digitization:Patient data management requirements drive software procurement for electronic health records, clinical decision support, and interoperability platforms in hospital systems.
- Edge computing architectures:Latency-sensitive applications in manufacturing and autonomous systems push workload distribution toward distributed cloud-edge nodes.
Market Restraints
- Cloud-native talent scarcity:Acute shortages of DevOps engineers with Kubernetes and container orchestration expertise inflate wage costs and extend implementation timelines.
- Supply concentration:Hyperscale cloud infrastructure depends on three dominant providers, creating single-source vulnerability for compute and storage capacity.
- Technical debt:Monolithic legacy applications resist modular decomposition, trapping enterprises in maintenance-heavy on-premise environments.
Strategic Opportunities
- Brazil:Underpenetrated mid-market ERP and CRM segments offer expansion paths for SaaS vendors with localized payment and tax compliance features.
- Generative AI integration:Convergence of large language models with enterprise workflow automation creates new product categories for code generation and document processing.
- Outcome-based pricing:Subscription metrics tied to measurable business KPIs replace seat-based licensing, reducing customer acquisition friction in procurement cycles.
Industry Challenges
- Algorithmic audit expertise:Shortage of professionals capable of conducting bias assessments and conformity evaluations under EU AI Act technical documentation requirements.
- Legacy system integration:SOAP-based enterprise service buses and COBOL mainframes resist API-first connectivity patterns, forcing expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Market |
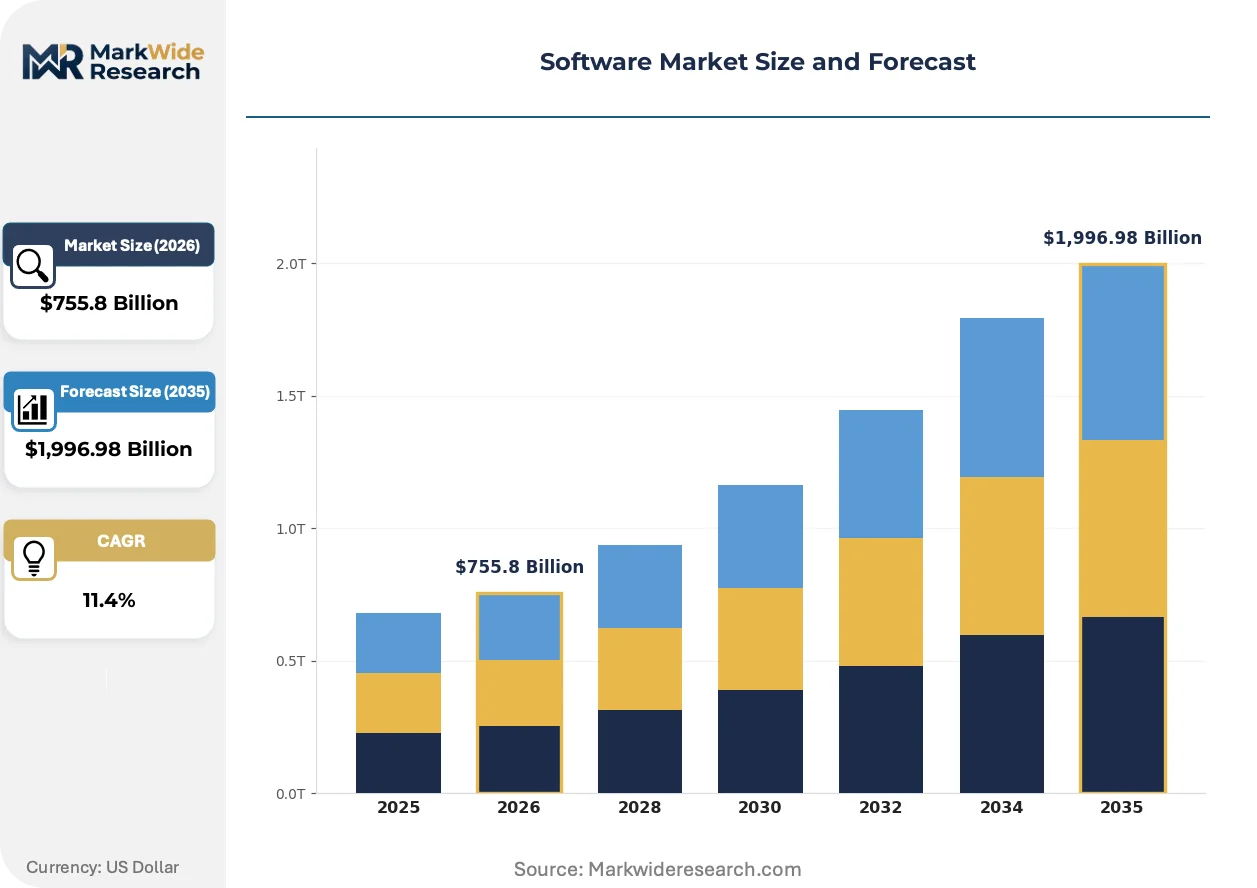
| Market Size in 2026 | $755.8 Billion |
| Market Size in 2035 | $1,996.98 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Application: Enterprise Resource Planning, Customer Relationship Management, Human Resource Management, Content Management End User: Small Businesses, Large Enterprises, Government Agencies, Non-Profit Organizations Pricing Model: Subscription, One-Time Purchase, Freemium, Value-Based Pricing |
| Companies Covered | Amazon Web Services, Adobe, Microsoft, Meta, Broadcom, Apple, Oracle, Intuit, Alphabet Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Market Strategic Shifts & Innovations
Software delivery models are fragmenting across containerized microservices, serverless functions, and AI-augmented development pipelines, compressing release cycles from quarterly to daily deployment rhythms.
Function-as-a-service platforms are miniaturizing application components into event-triggered code fragments. Retail and logistics operators adopt these architectures for inventory synchronization and payment processing. This compression eliminates server provisioning overhead and reduces idle compute costs.
FDA software-as-a-medical-device guidance imposes premarket validation requirements on diagnostic algorithms and clinical decision support tools. Health-tech vendors must document intended use, validation protocols, and risk mitigation measures. European health software deployments face parallel EU AI Act high-risk system obligations.
Enterprise buyers now mandate API-first architecture and multi-cloud portability in RFP specifications, displacing vendor-locked proprietary stacks. Procurement teams evaluate interoperability through OpenAPI conformance and Kubernetes distribution neutrality. German automotive and industrial equipment manufacturers lead this specification shift.
Software Market Segmentation
Deployment architecture determines procurement cycles, compliance obligations, and margin structures across software procurement. Application type dictates integration complexity and customer lifetime value profiles. End user scale and pricing model selection reshape vendor go-to-market economics and retention engineering priorities.
Deployment:
Substitution pressure runs strongest against on-premise installations as enterprises accelerate cloud migration timelines and retire owned data center assets.
- Cloud-Based:Multi-tenant architectures with elastic compute provisioning eliminate capital expenditure requirements for hardware procurement. Demand concentrates in German automotive manufacturers and Indian IT services exporters replacing legacy data center footprints with managed infrastructure. EU AI Act compliance deadlines force European deployments toward auditable cloud environments with transparent data residency controls.
- SaaS:Browser-delivered applications with continuous deployment pipelines reduce version fragmentation and patch management overhead. Brazilian mid-market enterprises and US healthcare providers drive procurement volume for vertical-specific solutions with pre-configured regulatory templates. Recurring revenue concentration attracts private equity roll-up strategies across vertical SaaS categories.
- On-Premise:Licensed software installed on customer-managed hardware persists in classified government environments and financial services with data sovereignty mandates.
- Hybrid:Workload splitting between private infrastructure and public cloud addresses latency-sensitive operations with burst capacity requirements.
On-Premise deployments anchor the volume base in regulated industries while Cloud-Based configurations gain share at the steepest rate across commercial enterprises.
Application:
Cost tier stratification separates monolithic suites with implementation services from modular point solutions with self-service onboarding.
- Enterprise Resource Planning:Integrated modules spanning finance, procurement, and supply chain operations require extensive configuration and change management. Manufacturing clusters in Stuttgart and São Paulo sustain demand for production planning and inventory optimization capabilities. Technical debt in legacy SAP and Oracle installations creates displacement opportunity for cloud-native alternatives.
- Customer Relationship Management:Sales force automation, marketing orchestration, and service desk functionality consolidate customer interaction data across touchpoints. Mid-market penetration in India and Southeast Asia drives expansion as distributed sales organizations require mobile-first engagement tools. API-first architectures enable embedded finance and commerce integrations.
- Human Resource Management:Payroll processing, benefits administration, and talent acquisition workflows with localized compliance for labor regulations.
- Content Management:Document repositories, digital asset workflows, and web experience platforms with headless delivery architectures.
Enterprise Resource Planning retains the largest installed base across industrial end users while Customer Relationship Management expands most quickly in services-dominated economies.
End User:
Customer type determines sales cycle length, support intensity, and expansion revenue potential across vendor portfolios.
- Large Enterprises:Procurement teams mandate security certifications, disaster recovery guarantees, and custom development roadmaps with dedicated customer success resources. German automotive conglomerates and US hospital systems drive demand for industry-specific configurations with multi-year contractual commitments. Consolidation of vendor relationships reduces integration complexity and support fragmentation.
- Small Businesses:Self-service adoption with credit card procurement and community support channels minimizes customer acquisition costs for standardized product tiers. Indian micro-enterprises and Brazilian professional services firms require localized payment methods and tax reporting automation. Freemium conversion metrics and product-led growth motions dominate go-to-market design.
- Government Agencies:FedRAMP, ISO 27001, and national security clearance requirements with competitive bidding statutes and protest procedures.
- Non-Profit Organizations:Donor management and grant compliance functionality with discounted pricing programs and board reporting tools.
Large Enterprises anchor contract value concentration while Small Businesses drive seat expansion through viral adoption patterns.
Pricing Model:
Margin structure varies dramatically between perpetual license maintenance streams and consumption-metered utility pricing.
- Subscription:Recurring revenue recognition with annual or monthly billing cycles reduces customer acquisition payback periods and improves valuation multiples for software vendors. SaaS providers across Germany, India, and Brazil standardize on seat-based or usage-tiered structures with automatic renewal provisions. Churn prediction algorithms and expansion revenue forecasting dominate financial planning.
- Value-Based Pricing:Contractual terms tied to measurable business outcomes such as cost reduction, revenue lift, or risk mitigation shift performance risk to vendors. Healthcare technology vendors align fees with patient throughput improvements or claims denial rate reductions. Procurement friction diminishes when expenditure correlates directly with demonstrated impact.
- One-Time Purchase:Perpetual licenses with optional maintenance agreements for on-premise installations in capital budget-favorable environments.
- Freemium:Feature-limited entry tiers with conversion triggers to paid functionality for user acquisition at scale.
Subscription models anchor recurring revenue concentration while Value-Based Pricing climbs the fastest in outcome-sensitive verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software consumption patterns diverge sharply across geographies. German automotive manufacturers prioritize on-premise ERP with cloud-edge extensions, while Indian IT services exporters favor multi-tenant SaaS for client delivery. Brazilian mid-market enterprises demand localized payment integrations absent in North American templates.
United States
Healthcare systems and defense contractors drive demand for FedRAMP-authorized cloud environments with sovereign data controls. FDA software-as-a-medical-device guidance imposes premarket validation requirements on diagnostic algorithms deployed in hospital networks. The Boston-Cambridge corridor concentrates health-tech vendors building clinical decision support tools under these frameworks.
Germany
Automotive OEMs and industrial equipment manufacturers procure ERP systems with shop-floor connectivity and predictive maintenance modules. EU AI Act high-risk system classifications force algorithmic transparency investments across Stuttgart and Munich production facilities. Bavaria's manufacturing clusters anchor demand for cloud-native MES platforms with audit-ready data lineage.
India
IT services exporters and domestic mid-market enterprises replace legacy data center footprints with managed cloud infrastructure. RBI data localization guidelines and SEBI cybersecurity circulars shape procurement specifications for financial services software. Bangalore and Hyderabad host development centers building SaaS products for Southeast Asian export markets.
Brazil
Underpenetrated mid-market segments in professional services and retail drive SaaS adoption with Pix-integrated payment workflows. ANVISA digital health regulations and Receita Federal tax reporting mandates create compliance software demand. São Paulo's financial services corridor concentrates procurement for ERP systems with localized fiscal modules.
Japan
Manufacturing conglomerates and aging-care providers invest in workflow automation with Japanese-language NLP interfaces. METI data-free flow with trust guidelines and PMDA software medical device oversight shape vendor selection criteria. Tokyo-Osaka industrial corridors anchor demand for hybrid cloud architectures bridging mainframe legacy and containerized microservices.
Software Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with hyperscale cloud providers controlling infrastructure layers while vertical SaaS vendors capture application-specific revenue pools. The upper tier combines platform ecosystems with direct sales forces serving Fortune 500 procurement teams. Specialist players concentrate on compliance-heavy verticals with embedded regulatory knowledge. Competitive moves center on API-first architecture investments and outcome-based pricing experiments that shift performance risk onto vendors.
Among hyperscale infrastructure providers, Amazon Web Services, Microsoft, and Oracle occupy distinct positioning vectors. Amazon Web Services exemplifies the infrastructure-dominant archetype with data center expansion anchoring enterprise workload migration. Microsoft represents the platform-integrated model, leveraging productivity software ecosystems to capture cloud consumption. Oracle sits within the database-migration specialist tier, targeting regulated industries with compliance-certified cloud portfolios.
| Leading Market Players |
|---|
| Amazon Web Services |
| Adobe |
| Microsoft |
| Meta |
| Broadcom |
| Apple |
| Oracle |
| Intuit |
| Alphabet Inc. |
| Others |
Cost & Logistics Intelligence
Hyperscale data center utilization rates above 75 percent in Northern Virginia, Frankfurt, and Mumbai anchor unit economics that compress price floors for cloud compute and storage services. These concentration nodes simultaneously concentrate procurement leverage among three infrastructure providers and enforce margin discipline across downstream SaaS vendors who bundle these services into vertical applications.
Pricing Analysis
Contract structures stratify across multi-year enterprise commitments with volume discounts, consumption-metered utility pricing with burst premiums, and spot-market compute auctions for batch workloads. Pricing stratifies across premium managed Kubernetes tiers, standard serverless configurations, and economy reserved-instance pools differentiated by uptime SLAs and support response guarantees. Cost compression in mid-market SaaS tiers intensifies as private equity roll-ups consolidate vendor relationships and demand outcome-based fee structures. Small businesses exhibit acute price sensitivity with freemium conversion thresholds, while large enterprises trade price premiums for dedicated customer success resources and custom development roadmaps.
Supply Chain Analysis
Taiwan Strait transit lanes for advanced semiconductor fabrication equipment underpin hyperscale server deployment timelines and create chokepoint vulnerability for AI training clusters. Cloud infrastructure draws from concentrated server assembly in Taiwan, China, and Mexico, with NVIDIA GPU supply and custom ASIC development from South Korea and USA forming critical input dependencies. Single-source vulnerability for specialized AI accelerators and high-bandwidth memory modules exposes procurement timelines to foundry capacity allocation decisions. Distribution runs through direct hyperscaler sales forces for enterprise workloads and tier-1 systems integrators for regulated industry deployments requiring compliance certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
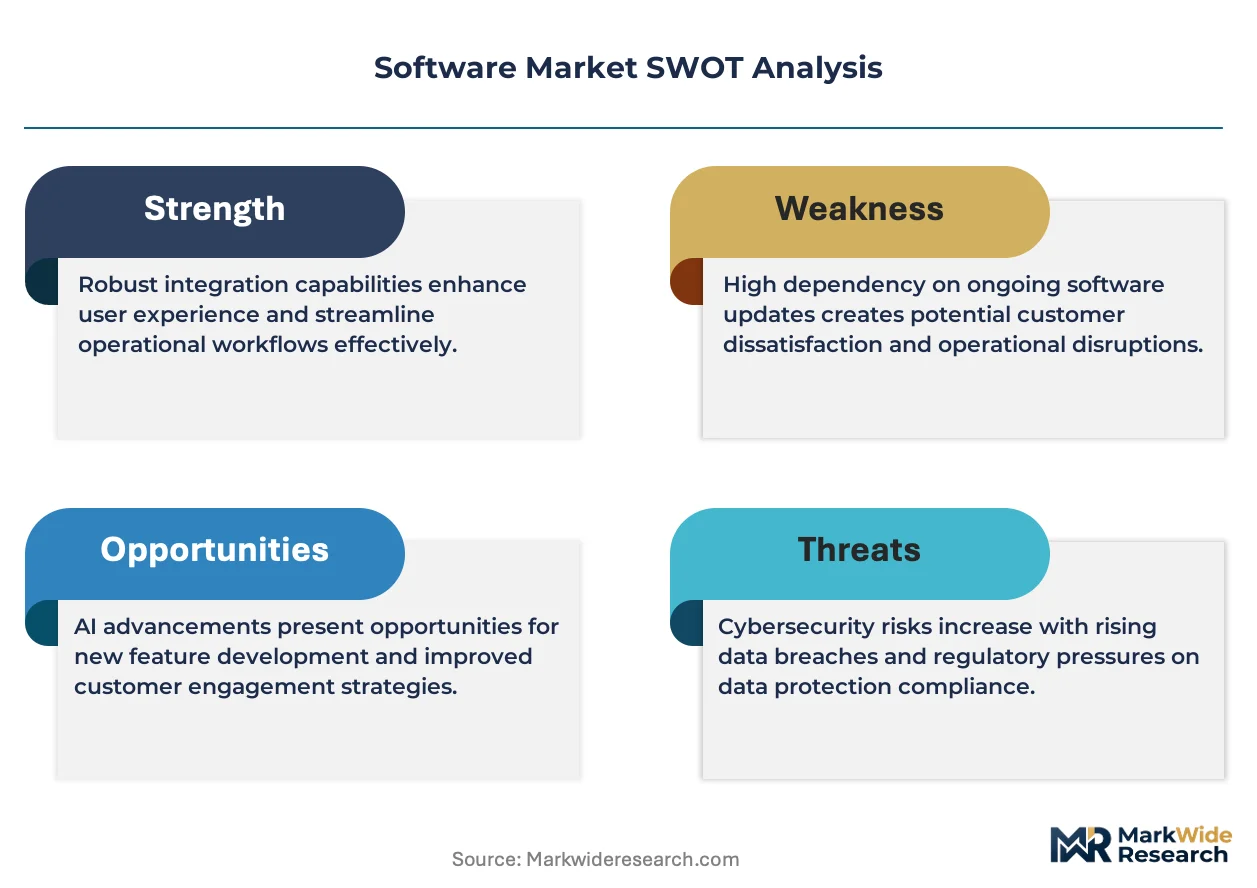
Open-source foundation models and API-accessible generative AI services threaten incumbent software margins by commoditizing functionality previously locked behind proprietary codebases. Incumbents must architect substitution defenses that embed workflow-specific data and regulatory compliance into defensible moats.
For Market Incumbents: Secure cloud-native DevOps talent pools through acquisition of boutique Kubernetes consultancies in Bangalore and São Paulo, insulating implementation timelines from wage inflation. Anchor enterprise relationships with EU AI Act audit-ready documentation and pre-validated compliance templates that open-source alternatives cannot replicate.
For New Entrants and Emerging Players: Differentiate on algorithmic transparency tooling for EU AI Act high-risk system deployments, targeting healthcare and financial services procurement teams with mandatory conformity assessment requirements. Penetrate Brazil's mid-market ERP segment with Pix-integrated payment workflows and Receita Federal tax automation absent in North American templates.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertical SaaS vendors with embedded regulatory knowledge and outcome-based pricing experiments that shift performance risk onto vendors. Long-term viability concentrates in platforms demonstrating net revenue retention above 110 percent and expansion revenue from existing customer bases. Monitor EU AI Act enforcement patterns and FDA software-as-a-medical-device clearance timelines as inflection indicators for compliance-heavy verticals.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure ecosystem captures enterprise workloads through productivity software bundling with cloud consumption. |
| Acquisition of Specialist Firm | Oracle's database-to-cloud migration portfolio targets regulated industries with compliance-certified infrastructure. |
| Geographic Expansion | AWS hyperscale data center expansion in Frankfurt and Mumbai anchors regional latency requirements and data residency mandates. |
| Strategic Partnership | Healthcare technology vendors align with hospital systems under FDA software-as-a-medical-device validation frameworks. |
| Product Launch | Generative AI code generation tools compress development cycles and create new pricing tiers for developer productivity. |
Research Approach
Desk research of hyperscaler capex disclosures, SEC 10-K filings, and EU regulatory databases preceded structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners across German automotive, US healthcare, and Indian IT services sectors. Secondary validation drew from App Annie mobile deployment metrics, hospital procurement databases, and GPO contract repositories. Bottom-up deployment modeling triangulated against top-down market sizing from trade association aggregates.
Variance decomposition across deployment architecture, organization scale, vertical industry, and regional adoption pattern shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate distributions weighted by base-year revenue concentration. Cloud-native migration velocity, EU AI Act compliance investment curves, and generative AI integration adoption rates served as industry-specific forecast inputs.
Material uncertainties — regulatory enforcement intensity, hyperscaler capacity allocation decisions, and open-source model capability trajectories — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EU AI Act technical documentation requirements and FDA software-as-a-medical-device guidance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Microscope Software Market
Software & Services
General Ledger Accounting Software Market
Software & Services
Coaching Management Software Market
Software & Services
Global Customer Communications Management (CCM) Software Market
Software & Services
Construction Jobsite Management Software Market
Software & Services
Account-Based Advertising Software Market
Software & Services
Global Storm Tracking Apps Market
Software & Services
Lighting Control Software Market
Software & Services
Data Conversion Services Market
Software & Services
Global User Interface Service Market
Software & Services
Global Animation Software Market
Software & Services
Global Building Information Modeling (BIM) Software Market
Software & Services
Simulation Software Market
Software & Services
Global ITSM Software Market
Software & Services
Australia HR Payroll Software Market
Software & Services
Solar Rooftop Design Software Market