
 Coaching Management Software Market | 2026-2036
Coaching Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Coaching Management Software Market Analysis
Fragmentation across new buyer segments is realigning vendor priorities as individual coaches and boutique training firms multiply faster than enterprise accounts. Simply.Coach specializes in solo-practitioner workflows with lightweight scheduling and billing modules. BetterUp dominates corporate deployments through its employer-sponsored coaching marketplace. CoachHub extends its footprint across European mid-market firms with localized language support and regional data residency.
Coaching management software orchestrates session logistics, client progress documentation, and outcome measurement for professional coaching relationships, typically delivered through web dashboards and native mobile applications with real-time synchronization. Cloud-based deployment leads the product type dimension because subscription economics and remote accessibility eliminate capital expenditure barriers for small practices. Performance tracking features within the feature dimension command premium pricing as organizations demand quantified return on coaching investments.
FDA oversight applies where coaching platforms integrate biometric data or mental health screening tools, while HIPAA compliance shapes data architecture decisions for health-adjacent deployments. The EU AI Act introduces algorithmic transparency requirements for automated coach-matching and sentiment analysis functions. Stakeholders must monitor evolving jurisdictional data-localization rules before committing to single-tenant versus multi-tenant infrastructure strategies.
Market Dynamics
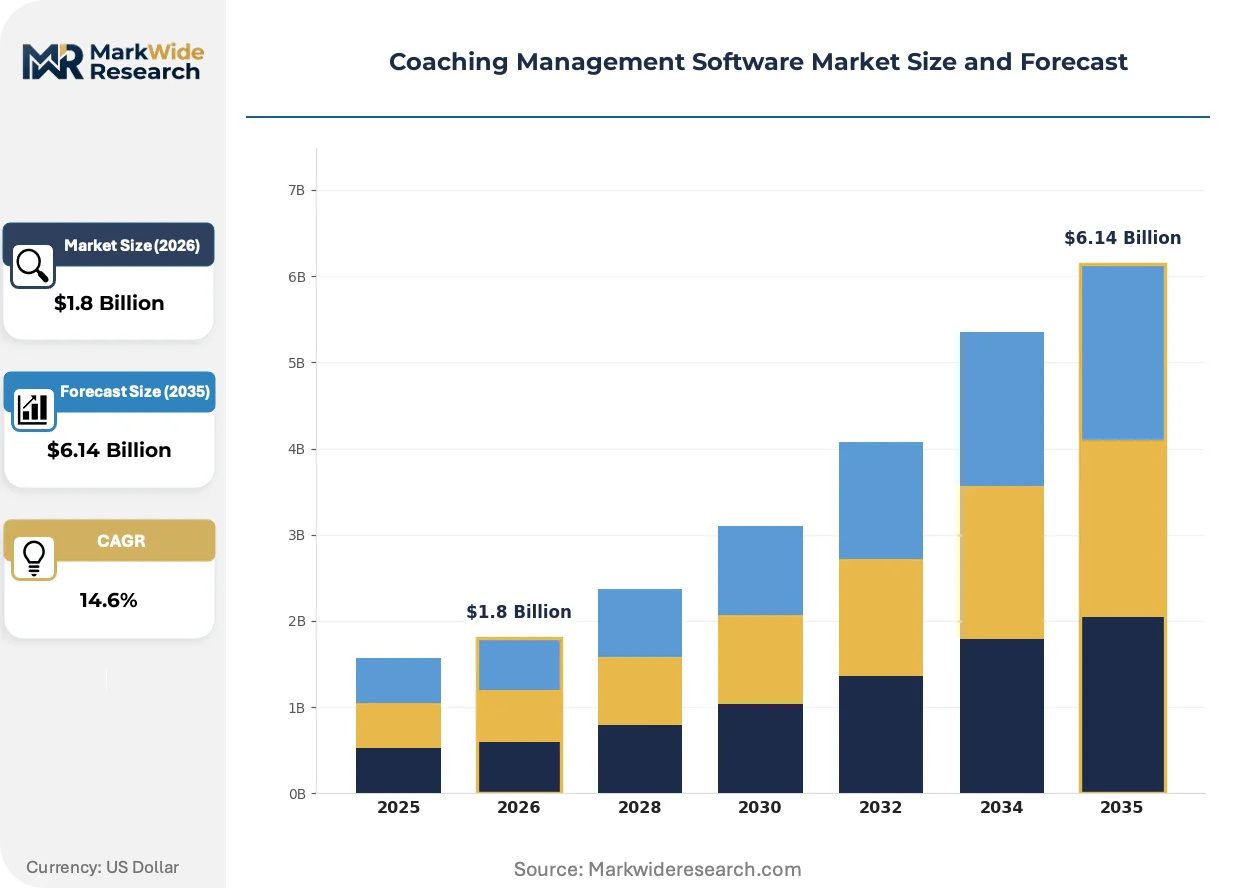
Cloud migration and API-first architectures are compressing vendor consolidation timelines as enterprise buyers demand composable stacks that integrate with existing HRIS and learning management systems.
Growth Catalysts
- Employer wellness mandates:United States enterprises face expanding regulatory pressure to document employee mental health support investments, accelerating procurement of coaching platforms with outcome-tracking capabilities.
- API-first architectures:RESTful and GraphQL interfaces enable coaching software to embed directly into Slack, Microsoft Teams, and Salesforce workflows, reducing friction for distributed workforce adoption.
- Biometric integration:Wearable data streams from Apple Watch and Fitbit devices create new coaching intervention triggers for stress and sleep management, opening reimbursement pathways through employer health plans.
Market Restraints
- Data residency fragmentation:The EU AI Act and GDPR require algorithmic transparency for automated coach-matching, forcing vendors to maintain separate inference engines across European jurisdictions.
- Specialized talent scarcity:Platform engineering roles combining coaching domain expertise with HIPAA-compliant architecture skills command premium compensation, constraining vendor R&D velocity.
- Substitution by generic tools:Calendly, Stripe, and Notion bundles satisfy solo practitioners at fraction of dedicated platform cost, capping price elasticity in the long tail.
Strategic Opportunities
- German Mittelstand penetration:Mid-market manufacturing and engineering firms in Baden-Württemberg and Bavaria remain underserved by English-first platforms, creating whitespace for localized deployments.
- CSRD-aligned ESG reporting:European corporate sustainability directives now require documented employee development investments, positioning coaching spend as compliance-adjacent procurement.
- Convergence of NLP and video analytics:Real-time sentiment extraction from coaching session transcripts combined with facial emotion recognition enables automated progress scoring, differentiating premium tiers.
Industry Challenges
- ISO 27001 and SOC 2 certification timelines:Enterprise security reviews now demand completed audits before pilot contracts, extending sales cycles by four to six months for emerging vendors.
- Legacy HRIS integration complexity:SAP SuccessFactors and Workday implementations require custom middleware development, consuming implementation resources and eroding gross margins on mid-market deals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coaching Management Software Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Mobile Application, Hybrid Solution End User: Educational Institutions, Sports Teams, Corporate Trainers, Individual Coaches Feature: Scheduling, Performance Tracking, Communication Tools, Billing & Invoicing Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Local Server |
| Companies Covered | Simply.Coach, Satori, CoachAccountable, TrueCoach, CoachHub, BetterUp, Practice Better, Healthie, CoachVantage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coaching Management Software Market Emerging Trajectories
Artificial intelligence is compressing the coaching value chain by automating session transcription, progress synthesis, and goal-tracking workflows that previously required human administrative support.
Microservices-based coaching platforms are modularizing core functions—scheduling, billing, content delivery, and analytics—into independently deployable components. Boutique training firms and internal corporate programs adopt these building blocks to assemble custom stacks without vendor lock-in. This architecture is modularizing competitive moats, as switching costs plummet when data portability becomes standard.
The EU AI Act mandates algorithmic transparency for automated coach-client matching and sentiment analysis functions deployed in European Economic Area jurisdictions. Vendors must now document training data provenance and inference logic for regulatory inspection. Coaching platforms serving German and French enterprise accounts are responding by segregating AI features into opt-in modules with explicit consent workflows.
Enterprise procurement teams now unbundle coaching software selection from coach talent sourcing, reversing the bundled marketplace model that dominated early corporate adoption. Buyers separately evaluate platform infrastructure and coach network quality, pressuring vendors to demonstrate standalone technology value. This pattern is most visible in United States technology and financial services sectors, where procurement functions have matured dedicated vendor management capabilities for people-tech categories.
Coaching Management Software Market Segmentation
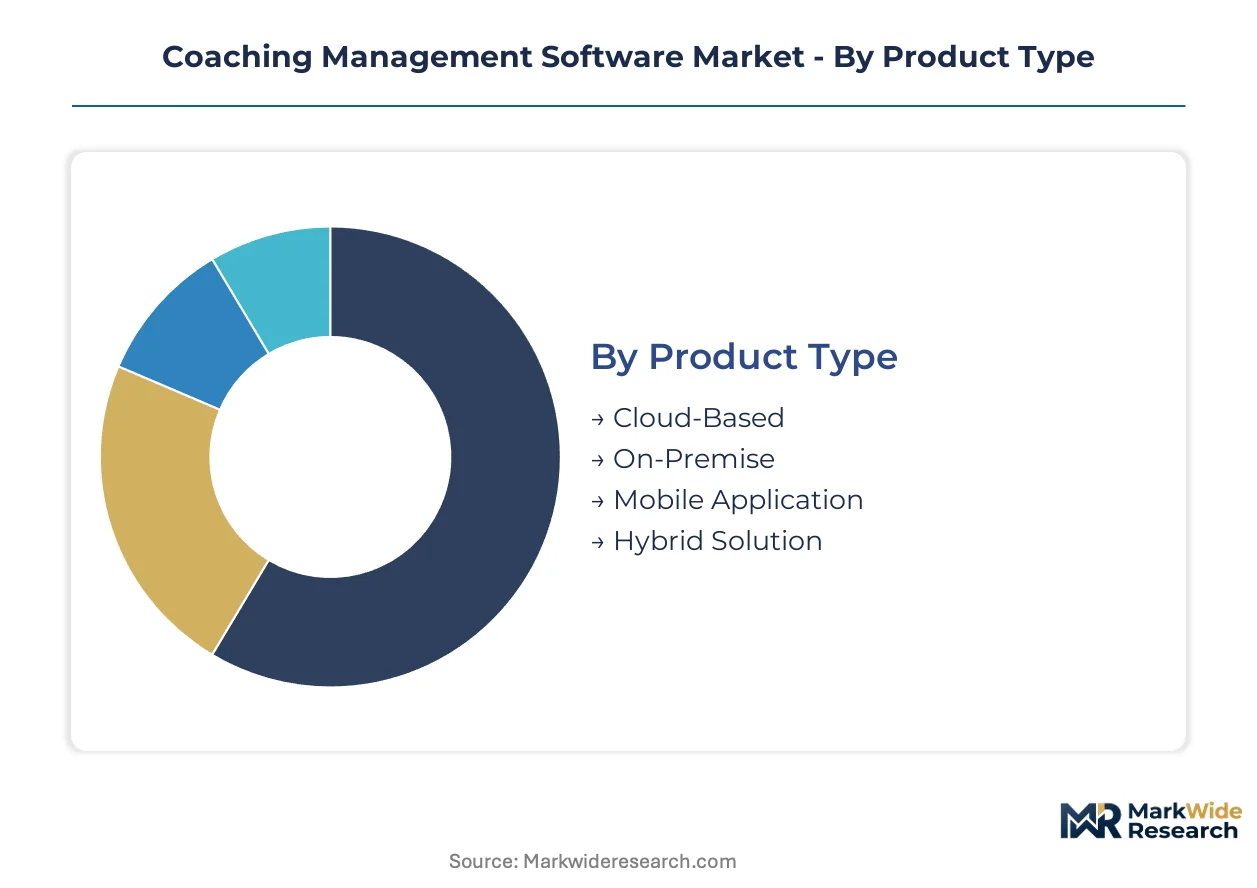
Segmentation in coaching management software reveals distinct capital requirements and buyer sophistication levels. Cloud-native architectures demand continuous infrastructure investment, while on-premise deployments concentrate capital in upfront licensing and server procurement.
Product Type:
Capital intensity varies sharply across deployment models, with cloud infrastructure requiring sustained operational expenditure versus one-time capital outlays for self-hosted alternatives.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server procurement for buyers while vendors absorb continuous compute, storage, and security scaling costs. Demand concentrates among individual coaches and boutique firms in the United States, where subscription economics align with variable revenue streams and remote accessibility mandates.
- On-Premise:Single-tenant installations on client-owned servers demand substantial upfront hardware investment and dedicated IT maintenance staff. Financial services and healthcare enterprises in Germany favor this model to satisfy Bundesdatenschutzgesetz data localization requirements and maintain direct control over encryption key management.
- Mobile Application:Native iOS and Android clients with offline synchronization capabilities require parallel development tracks and ongoing OS compatibility testing.
- Hybrid Solution:Split architectures combining cloud dashboards with local data caching address intermittent connectivity scenarios in field coaching deployments.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Mobile Application as coach-client interaction shifts to smartphone-first workflows.
End User:
Buyer sophistication and procurement scale diverge across user categories, from enterprise compliance-driven purchasing to individual credit-card transactions.
- Corporate Trainers:Enterprise learning and development departments procure multi-seat licenses with mandatory SOC 2 and ISO 27001 certification, integrating coaching platforms into existing Workday or SAP SuccessFactors stacks. Procurement teams in United States technology and financial services sectors now unbundle platform selection from coach sourcing.
- Individual Coaches:Solo practitioners prioritize low-friction onboarding and Stripe-integrated billing over advanced analytics, driving demand toward lightweight scheduling-first tools. This segment shows fastest adoption growth in the United Kingdom and Australia as independent coaching credentials proliferate.
- Educational Institutions:University career services and executive education programs require FERPA-compliant data handling with semester-aligned licensing terms.
- Sports Teams:Professional and collegiate athletic organizations demand biometric data integration with wearable APIs and HIPAA-adjacent health record protections.
Revenue concentration sits with Corporate Trainers. Individual Coaches are climbing the fastest as platform accessibility lowers market entry barriers.
Feature:
Functional modules command differentiated pricing power based on quantifiable ROI demonstration and integration complexity.
- Performance Tracking:Outcome measurement dashboards with goal attainment scaling and progress visualization justify premium pricing tiers. United States enterprises facing expanding wellness documentation mandates prioritize these capabilities to demonstrate measurable employee development returns.
- Scheduling:Calendar synchronization across Google, Outlook, and Apple ecosystems with automated timezone handling represents table-stakes functionality. Demand spreads evenly across all geographies as remote coaching normalizes cross-border session booking.
- Communication Tools:In-platform video conferencing, asynchronous messaging, and session note repositories reduce external tool fragmentation.
- Billing & Invoicing:Automated invoice generation, payment collection, and tax compliance reporting address solo practitioner administrative pain points.
Platform stickiness depends most heavily on Performance Tracking. Billing & Invoicing is gaining share fastest as revenue operations automation becomes non-negotiable for scaling practices.
Deployment:
Infrastructure topology decisions reflect regulatory jurisdiction, data sensitivity, and existing cloud vendor relationships.
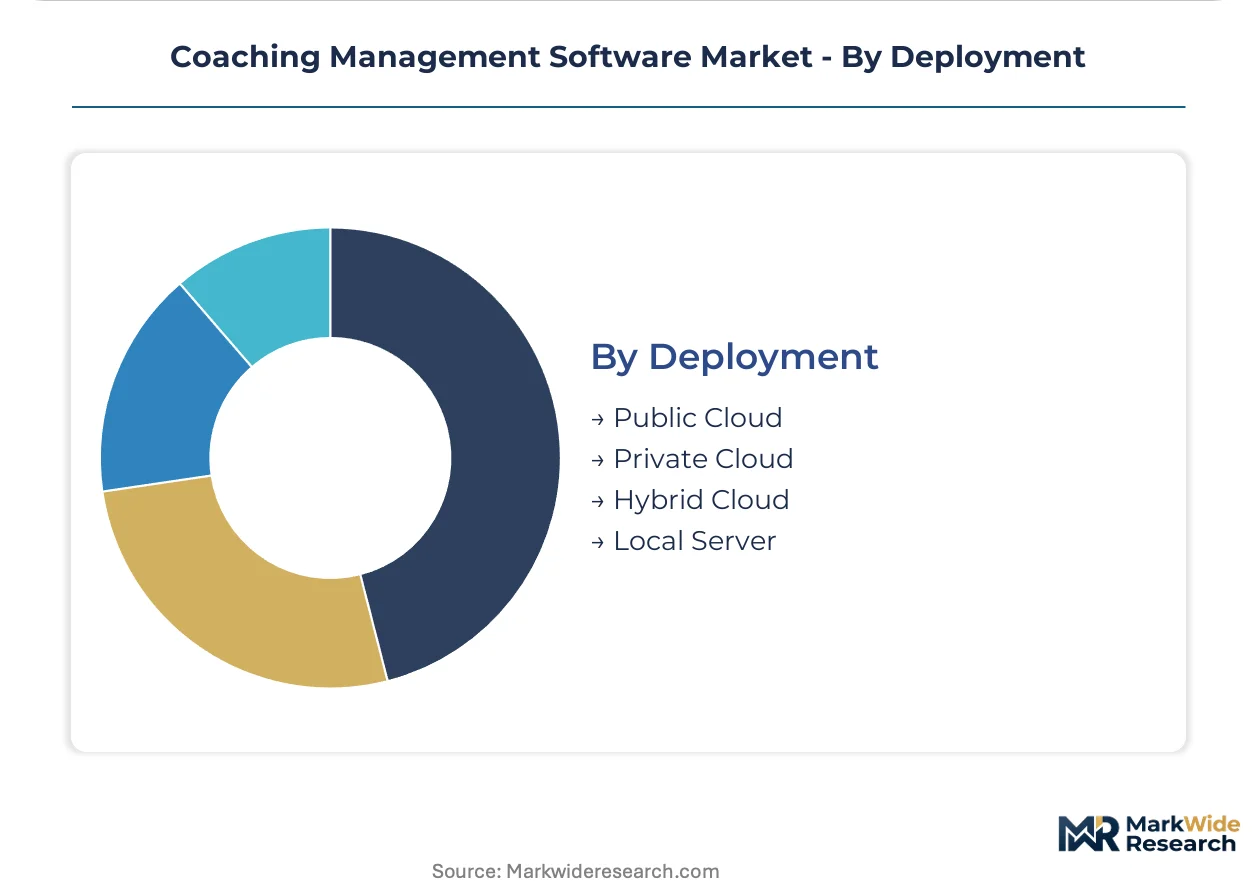
- Public Cloud:Shared AWS, Azure, or Google Cloud infrastructure delivers lowest unit economics through resource pooling. Small and mid-market buyers across India and Southeast Asia default to this model given limited internal infrastructure expertise.
- Private Cloud:Dedicated single-tenant environments within hyperscaler facilities satisfy data residency requirements without full on-premise burden. French and German enterprises responding to EU AI Act algorithmic transparency mandates favor this architecture for segregated AI inference workloads.
- Hybrid Cloud:Workload splitting between public burst capacity and private core databases addresses variable compute demands.
- Local Server:Air-gapped installations in physical client facilities serve defense contractors and classified government coaching programs.
Compute volume runs predominantly through Public Cloud. Private Cloud is expanding most quickly as European regulatory fragmentation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate wellness mandates in the United States generate procurement velocity that German data residency requirements cannot match, while India's independent coaching credential proliferation creates volume without equivalent per-seat value.
United States
Employer-sponsored coaching marketplaces dominate enterprise procurement as technology and financial services sectors mature dedicated people-tech vendor management functions. HIPAA compliance shapes architecture decisions for health-adjacent deployments with biometric data integration. Boston and San Francisco Bay Area clusters concentrate platform engineering talent combining coaching domain expertise with security certification skills.
Germany
Baden-Württemberg and Bavaria manufacturing mid-market firms remain underserved by English-first platforms, creating whitespace for localized deployments with Bundesdatenschutzgesetz-aligned data localization. EU AI Act algorithmic transparency mandates force segregation of automated coach-matching into opt-in modules with explicit consent workflows. Berlin-Brandenburg hosts emerging vendors responding to CSRD-aligned ESG reporting requirements for documented employee development investments.
United Kingdom
Independent coaching credentials proliferate fastest among solo practitioners prioritizing low-friction onboarding and Stripe-integrated billing over advanced analytics. GDPR enforcement through the Information Commissioner's Office shapes consent architecture for cross-border session data flows. London's financial services procurement functions increasingly unbundle platform selection from coach talent sourcing, reversing earlier bundled marketplace adoption patterns.
India
Small and mid-market buyers default to public cloud deployments given limited internal infrastructure expertise, with subscription economics aligning with variable revenue streams of independent practitioners. The Digital Personal Data Protection Act introduces consent-layer requirements for client progress documentation systems. Bangalore and Hyderabad clusters concentrate mobile-first development talent for smartphone-native coach-client interaction workflows.
Australia
Executive education programs at university career services drive FERPA-compliant data handling requirements with semester-aligned licensing terms. The Therapeutic Goods Administration oversees platforms integrating mental health screening tools into coaching workflows. Sydney and Melbourne metropolitan areas concentrate boutique training firms adopting microservices-based modular stacks to assemble custom configurations without vendor lock-in.
Coaching Management Software Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment models, with cloud-native architectures demanding continuous infrastructure investment while on-premise alternatives concentrate capital in upfront licensing. The vendor base separates into three strategic archetypes: employer-sponsored marketplace operators, solo-practitioner workflow specialists, and modular microservices platform assemblers. M&A activity targets API-first architecture capabilities, while geographic expansion concentrates on German Mittelstand penetration and India mobile-first development.
Among employer-sponsored marketplace operators, BetterUp occupies a position exemplifying corporate deployment scale, while CoachHub represents European mid-market localization strategies. Simply.Coach anchors the solo-practitioner workflow tier with lightweight scheduling-first positioning. These three companies collectively illustrate the segmentation divergence between enterprise compliance-driven procurement and independent practitioner accessibility demands reshaping competitive positioning across the analysis window.
| Leading Market Players |
|---|
| Simply.Coach |
| Satori |
| CoachAccountable |
| TrueCoach |
| CoachHub |
| BetterUp |
| Practice Better |
| Healthie |
| CoachVantage |
| Others |
Supply Flow & Price Mechanics
AWS compute pricing indices cascade through coaching management software supply chains, compressing margins for vendors dependent on hyperscaler infrastructure while enabling aggressive SaaS pricing tiers that undercut on-premise alternatives in Germany and the United States.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for development talent, enabling mid-tier vendors to reduce subscription rates by fifteen to twenty percent without sacrificing feature parity. Pricing stratifies across enterprise compliance tiers, mid-market integration bundles, and solo-practitioner essentials, with HIPAA certification and SOC 2 audit status commanding substantial premiums in United States healthcare-adjacent deployments. Cost compression in the independent coach segment intensifies as Calendly-Stripe-Notion bundles satisfy administrative needs at fractional cost. Corporate trainers exhibit lowest price sensitivity due to procurement budgets tied to wellness mandate compliance, while individual coaches maximize platform churn chasing promotional rates.
Supply Chain Analysis
Dual-sourcing requirements from United States enterprise procurement teams mandate qualified secondary infrastructure providers, forcing vendors to maintain active relationships with both AWS and Azure for failover assurance. Engineering talent concentrates in India, Poland, and Vietnam, with platform development costs anchored in Bangalore and Hyderabad wage arbitrage. Cloud compute, API middleware licenses, and biometric wearable integration SDKs constitute primary input dependencies. Single-source vulnerability runs through Apple HealthKit and Google Fit API access terms, where platform policy changes could disable core wellness features. Distribution runs through direct sales teams for enterprise accounts and self-service onboarding portals for individual practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German data residency requirements create a thirty to forty percent cost premium over United States public cloud deployments, positioning arbitrage plays for vendors able to segment infrastructure by jurisdiction without duplicating codebases.
For Market Incumbents: Deploy API-first architecture consolidation to defend against modular microservices assemblers eroding switching costs. Acquire boutique scheduling specialists in United Kingdom and Australian markets to capture fastest-growing independent coach segments before platform commoditization accelerates. Counter substitution threat from generic productivity tools by embedding outcome measurement dashboards that demonstrate quantified ROI unavailable in Calendly-Notion bundles. For New Entrants and Emerging Players: Begin with German Mittelstand manufacturing clusters in Baden-Württemberg and Bavaria, where localized language support and Bundesdatenschutzgesetz-compliant data residency remain underserved by English-first incumbents. Target mid-market engineering firms with CSRD-aligned ESG reporting requirements, positioning coaching spend as compliance-adjacent procurement with documented employee development investment trails. Pursue channel partnerships with regional HR consultancies possessing existing relationships with works councils and employee representation bodies. For Investors and Strategic Acquirers: Asymmetric upside sits with European vendors possessing pre-built EU AI Act algorithmic transparency documentation and segregated inference engine architectures for automated coach-matching features. Long-term viability favors platforms demonstrating standalone technology value independent of bundled coach network quality, reflecting procurement team unbundling trends in United States technology and financial services sectors. Monitor FDA guidance evolution on mental health screening tool classifications as inflection indicator for reimbursement pathway expansion through employer health plans.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Migration | Enables seamless embedding into Slack, Microsoft Teams, and Salesforce workflows for distributed workforce adoption. |
| EU AI Act Compliance Modularization | Segregates automated coach-matching into opt-in modules with explicit consent workflows for German and French enterprise accounts. |
| Biometric Data Integration Partnership | Opens reimbursement pathways through employer health plans via Apple Watch and Fitbit wearable API connections. |
| German Mittelstand Localization | Captures whitespace in Baden-Württemberg and Bavaria manufacturing mid-market with Bundesdatenschutzgesetz-aligned deployments. |
| Microservices Platform Unbundling | Reduces vendor lock-in concerns for boutique training firms assembling custom stacks from independently deployable components. |
Methodological Framework
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with chief technology officers at coaching platform vendors, enterprise learning and development procurement officers, independent coaching practitioners, and API integration specialists informed demand-side and supply-side perspectives. Secondary sources include SEC filings for publicly traded coaching technology companies, hyperscaler infrastructure capex disclosures, EU regulatory documentation on algorithmic transparency requirements, and hospital procurement database records for wellness program spending. Bottom-up segment sizing triangulates against top-down market aggregate estimates.
Granularity-level modeling addresses deployment model, organization size, vertical industry, integration complexity with existing HRIS stacks, and regional regulatory adoption patterns across the projection horizon. CAGRs derive from segment-level growth rate synthesis rather than single-point extrapolation. Forecast inputs incorporate cloud infrastructure cost trajectories, coaching credential proliferation rates by geography, and enterprise wellness mandate expansion timelines without specific year anchoring.
Several conditions sit outside the modeled scope, including abrupt changes to FDA oversight of mental health screening tools, unilateral API policy revisions by Apple or Google affecting biometric data access, and accelerated consolidation among hyperscaler infrastructure providers altering compute pricing dynamics. Deviation in EU AI Act enforcement intensity or GDPR penalty escalation would shift the outlook materially for European vendor competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Camp Management Software Market
Software & Services
Global Apparel Management Software Market
Software & Services
Metal Fabrication Software Market
Software & Services
UI Design Software Market
Software & Services
Bridge Analysis Software Market
Software & Services
Live Chat Software Market
Software & Services
Global Email Management Software Market
Software & Services
Performing Arts Software Market
Software & Services
Website Builder Tool Market
Software & Services
MES Software Market
Software & Services
Global Architecture Design Software Market
Software & Services
Poland IT Software and Service Market
Software & Services
Know Your Customer Software Market
Software & Services
Global IVR Software Market
Software & Services
Language Translation Software Market
Software & Services
Co-Browsing Software Market