
 Construction Jobsite Management Software Market | 2026-2036
Construction Jobsite Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Jobsite Management Software Market Insights
Subscription-based SaaS financing is reconfiguring capital requirements for mid-tier contractors, allowing smaller firms to access enterprise-grade tools without heavy infrastructure investment. Procore Technologies Inc. leverages cloud-native architecture to dominate North American general contractor accounts. Autodesk Inc. anchors its position through deep BIM integration that extends design data into field execution workflows. Trimble Inc. competes via hardware-software bundling in geospatial and equipment tracking segments.
Construction jobsite management software encompasses digital platforms that coordinate scheduling, resource allocation, safety compliance, and quality assurance across active building sites through real-time data capture and mobile connectivity. These systems typically operate via cloud-hosted architectures with API interoperability to ERP and accounting systems, serving the core purpose of reducing project delays and cost overruns through centralized visibility. Project Scheduling modules currently occupy the largest share of module spending as general contractors prioritize timeline risk mitigation. Cloud-Based deployment is displacing on-premises installations fastest among specialty contractors seeking lower IT overhead. Customer Type concentration favors general contractors, though facility managers represent an emerging margin pool as operational handoff requirements expand.
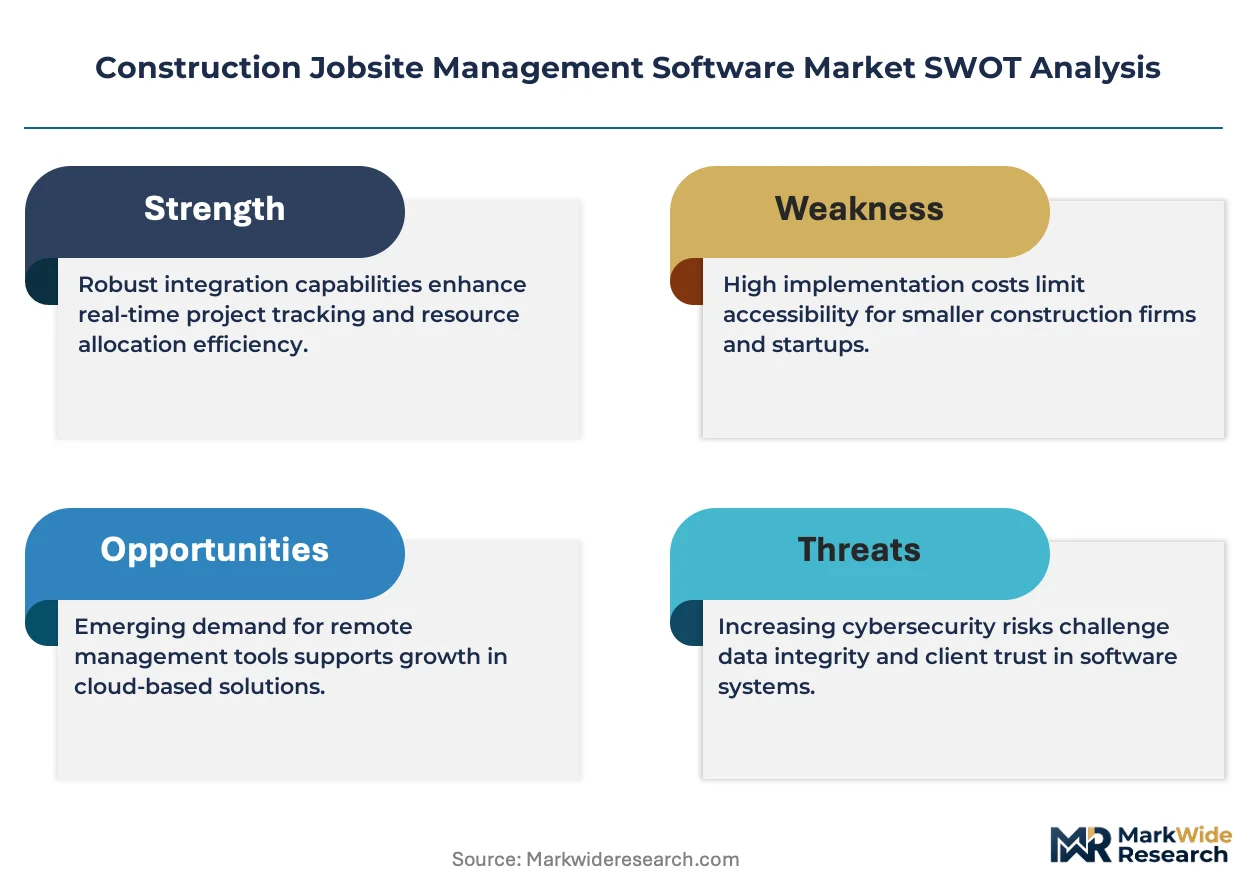
OSHA recordkeeping digitization rules in the United States are pressuring contractors to adopt automated safety incident reporting. The EU Green Deal building performance standards are mandating material traceability that jobsite software must document from delivery through installation. ISO 19650 information management protocols are shaping data structure requirements for cross-border project collaboration. Stakeholders must evaluate whether their current platforms can absorb emerging carbon accounting modules without fragmenting existing workflow architectures.
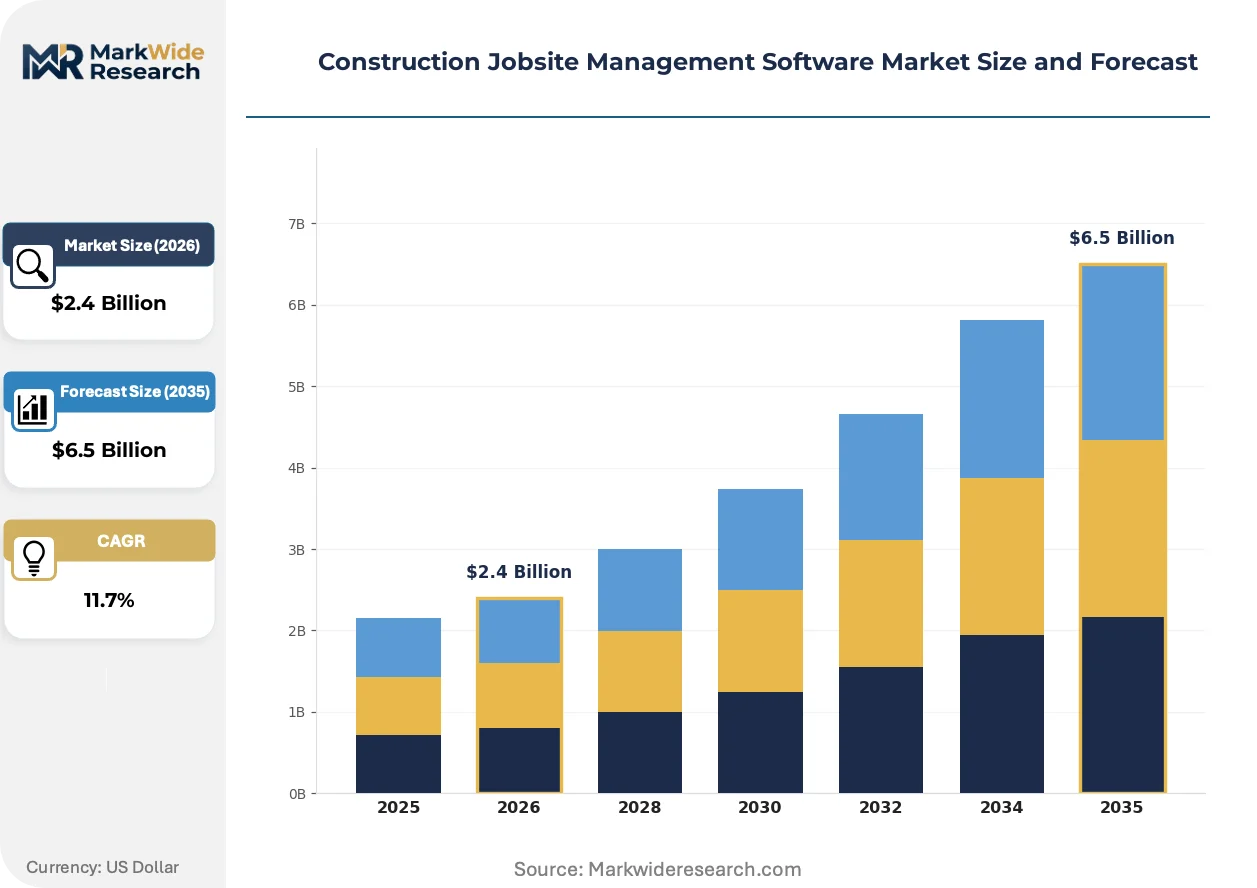
Market Dynamics
Cloud-native architecture is virtualizing jobsite coordination by collapsing the distinction between field data capture and back-office planning, forcing incumbent vendors to rebuild core platforms around API-first interoperability rather than monolithic legacy stacks.
Growth Catalysts
- OSHA workplace safety digitization:Automated incident reporting mandates in the United States are compelling contractors to integrate compliance modules that connect wearable sensors directly to centralized dashboards.
- EU Green Deal building performance standards:Material traceability requirements from delivery through installation are expanding software scope to capture carbon accounting documentation across supply chains.
- United Arab Emirates mega-project concentration:Centralized jobsite visibility requirements from sovereign wealth-backed developments are accelerating adoption of unified coordination platforms.
Market Restraints
- High IT infrastructure transition costs:Mid-tier contractors face stranded asset risk from on-premises server investments that resist cloud migration without complete workflow redesign.
- Specialized labor scarcity:Shortage of construction technologists capable of configuring BIM-to-field data pipelines limits deployment velocity for complex integrations.
- Data sovereignty fragmentation:Cross-border project data residency requirements in Germany, China, and Saudi Arabia force redundant hosting architectures that inflate operational overhead.
Strategic Opportunities
- Facility manager operational handoff:Post-construction digital twin maintenance contracts represent an emerging revenue stream as owners demand continuous building performance monitoring.
- AI-powered predictive scheduling:Machine learning convergence with historical project databases enables automated delay risk scoring that general contractors will pay premium rates to access.
- India infrastructure buildout:National highway and urban metro expansion is creating first-mover advantage for vendors establishing localized cloud infrastructure and Hindi-language support.
Industry Challenges
- ISO 19650 certification complexity:Information management protocol compliance requires 12-18 month implementation timelines that delay revenue recognition for new platform deployments.
- Multi-vendor integration fragility:ERP and accounting system API mismatches consume 40% of implementation resources, eroding project margins for systems integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Jobsite Management Software Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Module: Project Scheduling, Resource Allocation, Budget Tracking, Safety Management, Compliance Reporting, Quality Control Deployment Model: Cloud-Based, On-Premises, Hybrid, Mobile-First, SaaS, API-Integrated Use Case: Equipment Tracking, Labor Management, Document Control, Progress Monitoring, Risk Assessment, Subcontractor Coordination Customer Type: General Contractors, Specialty Contractors, Project Owners, Construction Managers, Engineering Firms, Facility Managers |
| Companies Covered | Procore Technologies Inc., Autodesk Inc., Trimble Inc., Bentley Systems Incorporated, Oracle Corporation, Fieldwire Ltd., Viewpoint Inc., PlanGrid Inc., Buildertrend Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Jobsite Management Software Market Trends and Innovations
Digitization is compressing the feedback loop between design intent and field execution, creating pressure for software architectures that dissolve traditional boundaries between planning, procurement, and quality assurance.
Digital twin technology is virtualizing physical jobsite conditions through real-time sensor fusion and 3D spatial mapping. Specialty contractors in concrete and MEP trades are deploying these systems fastest to preempt rework costs. The technology is virtualizing quality assurance workflows by enabling remote inspection protocols that reduce on-site supervisor headcount requirements.
The EU Green Deal building performance standards are mandating embodied carbon disclosure across construction material supply chains. Jobsite management platforms must now capture lot-level traceability data from delivery through installation to generate compliance documentation. General contractors operating across Germany, France, and the Netherlands face the steepest adaptation curves as national building codes integrate these requirements.
Subscription financing is displacing perpetual license purchasing among mid-tier contractors seeking to preserve working capital. Vendor revenue models are pivoting toward usage-based pricing tied to project count rather than seat licenses. This shift is most pronounced in the United States and United Kingdom where private equity-backed contractors prioritize cash flow flexibility over long-term cost optimization.
Construction Jobsite Management Software Market Segmentation
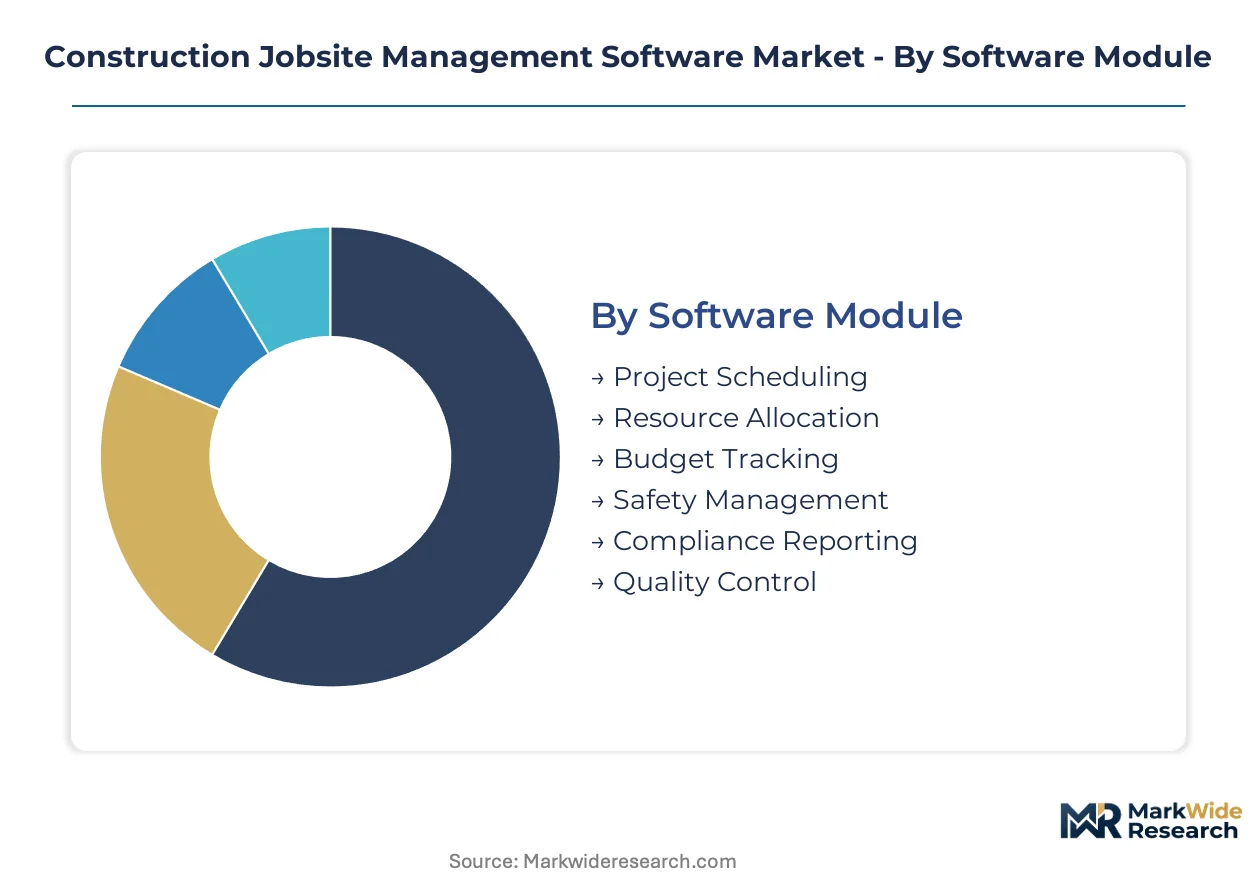
Construction jobsite management software vendors configure product architecture around distinct operational workflows. Module selection and deployment topology determine integration complexity and recurring revenue potential.
Software Module:
Cost tier differentiation separates basic scheduling tools from premium compliance suites with sensor integration.
- Project Scheduling:Critical path methodology and Gantt visualization anchor general contractor procurement decisions. Timeline risk mitigation drives premium pricing in the United States where delay penalties escalate project costs.
- Safety Management:Wearable sensor integration and automated incident logging satisfy OSHA digitization mandates. Contractors in the United Arab Emirates deploy these modules fastest on sovereign wealth-backed mega-projects.
- Resource Allocation:Equipment and labor optimization algorithms reduce idle time across multi-site portfolios.
- Budget Tracking:Real-time cost code aggregation connects field operations to ERP systems.
- Compliance Reporting:Automated documentation generation addresses EU Green Deal material traceability requirements.
- Quality Control:Inspection checklists and defect tracking standardize handoff protocols.
Project Scheduling holds installed capacity. Safety Management is rotating up the share rankings.
Deployment Model:
Application topology determines data sovereignty compliance and IT overhead burden for contractor finance teams.
- Cloud-Based:Multi-tenant SaaS architecture eliminates server maintenance and enables mobile field access. Specialty contractors in Germany and France migrate fastest to satisfy data residency requirements under GDPR and national building codes.
- API-Integrated:Middleware connectivity bridges jobsite platforms with ERP, accounting, and BIM systems. Systems integrators command premium implementation fees where multi-vendor stacks predominate.
- On-Premises:Legacy server installations persist where data control outweighs scalability needs.
- Hybrid:Split processing keeps sensitive financial data local while pushing field operations to cloud.
- Mobile-First:Native smartphone applications prioritize superintendent workflows over back-office functionality.
- SaaS:Subscription financing preserves working capital for private equity-backed contractors.
Cloud-Based deployments dominate new installations. API-Integrated configurations are climbing the fastest as BIM-to-field pipelines mature.
Use Case:
Volume concentration follows trade specialization, with concrete and MEP contractors driving sensor-heavy implementations.
- Equipment Tracking:Telematics integration and geofencing reduce theft and unauthorized usage. Heavy civil contractors on India's national highway buildout deploy these systems to monitor fleet utilization across dispersed sites.
- Progress Monitoring:Photogrammetry and drone capture accelerate payment certification cycles. General contractors in the Netherlands leverage automated quantity verification to satisfy strict building performance standards.
- Labor Management:Time-and-attendance systems with biometric verification control payroll leakage.
- Document Control:Centralized drawing distribution eliminates version confusion during RFI cycles.
- Risk Assessment:Predictive analytics flag schedule and safety exposures before escalation.
- Subcontractor Coordination:Portal-based communication reduces email fragmentation across tiered supply chains.
Equipment Tracking commands the largest implementation spend. Progress Monitoring is gaining share fastest as payment automation becomes critical.
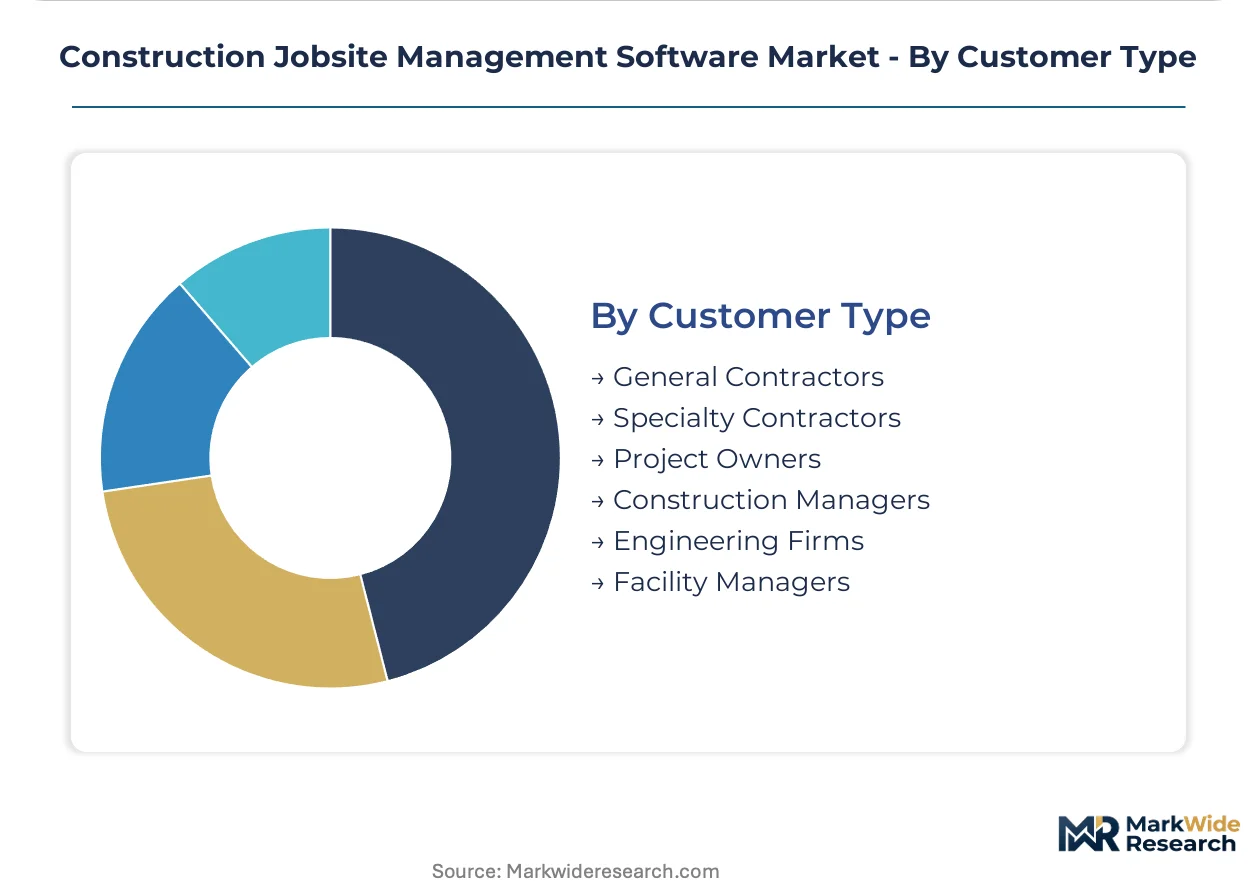
Customer Type:
Margin structure varies sharply by procurement sophistication and post-construction service potential.
- General Contractors:Enterprise-scale deployments across multiple simultaneous projects require unified dashboards. North American firms with $500M+ annual revenue represent the core installed base for tier-one vendors.
- Facility Managers:Post-construction digital twin maintenance contracts extend software value into operational phases. Commercial real estate owners in the United Kingdom increasingly mandate continuous building performance monitoring.
- Specialty Contractors:Trade-specific modules address concrete, steel, and MEP workflow requirements.
- Project Owners:Capital program visibility tools aggregate data across general contractor portfolios.
- Construction Managers:Agent-based fee structures prioritize cost control over schedule acceleration.
- Engineering Firms:Design-to-field handoff requirements drive BIM integration priorities.
General Contractors anchor current revenue. Facility Managers are expanding fastest as operational handoff requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA digitization mandates and sovereign wealth infrastructure commitments are concentrating software procurement across four distinct national markets. Cloud migration velocity varies sharply by data residency requirements and contractor capital structure.
United States
General contractors with $500M+ annual revenue drive enterprise SaaS adoption to mitigate delay penalty exposure. OSHA workplace safety digitization rules compel automated incident reporting module integration. Dallas-Fort Worth and Phoenix construction corridors anchor the largest domestic deployments of sensor-integrated platforms.
United Arab Emirates
Sovereign wealth-backed mega-projects generate centralized jobsite visibility requirements that favor unified coordination platforms. MOHAP building performance standards intersect with international contractor procurement protocols. Dubai South and Abu Dhabi Reem Island developments concentrate demand for real-time progress monitoring with payment automation.
Germany
GDPR data residency requirements accelerate cloud migration among specialty contractors seeking compliant hosting architectures. EU Green Deal material traceability mandates expand software scope to embodied carbon documentation. Munich and Stuttgart industrial clusters lead BIM-to-field integration adoption for automotive facility construction.
India
National highway and urban metro expansion creates first-mover advantage for vendors establishing localized cloud infrastructure. PLI scheme incentives for construction technology adoption reduce procurement friction for domestic contractors. Mumbai-Ahmedabad high-speed rail corridor and Bangalore metro extensions drive equipment tracking implementations across dispersed sites.
United Kingdom
Private equity-backed contractors prioritize subscription financing to preserve working capital flexibility. Commercial real estate owners mandate continuous building performance monitoring through post-construction digital twin contracts. London Canary Wharf and Manchester MediaCity developments anchor facility manager software adoption for operational handoff requirements.
Construction Jobsite Management Software Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers defined by integration depth and capital scale. Cloud-native specialists compete against legacy design software incumbents and hardware-software bundlers. Dominant competitive moves include API-first platform rebuilding to replace monolithic stacks and vertical integration into sensor hardware for field data capture. Geographic expansion through localized hosting partnerships addresses data sovereignty fragmentation.
Within the cloud-native tier, Procore Technologies Inc. and Fieldwire Ltd. exemplify mobile-first architectures that prioritize superintendent workflows over back-office functionality. Autodesk Inc. occupies a position bridging design-to-field data pipelines through BIM integration. Trimble Inc. anchors the hardware-software bundling archetype in geospatial and equipment tracking segments. Bentley Systems Incorporated and Oracle Corporation sit within the enterprise infrastructure tier, leveraging legacy customer relationships for complex multi-project deployments.
| Leading Market Players |
|---|
| Procore Technologies Inc. |
| Autodesk Inc. |
| Trimble Inc. |
| Bentley Systems Incorporated |
| Oracle Corporation |
| Fieldwire Ltd. |
| Viewpoint Inc. |
| PlanGrid Inc. |
| Buildertrend Solutions Inc. |
| Others |
Pricing and Supply Chain Analysis
GDPR data residency requirements and cross-border data transfer restrictions determine both the spread between compliant and non-compliant SaaS tiers and the geographic fragmentation of cloud hosting infrastructure. Contractors in Germany and France face steeper pricing for localized server deployments while vendors absorb redundant operational overhead to satisfy divergent national regulations.
Pricing Analysis
Certification level (ISO 19650 compliance) creates the primary spread between premium enterprise suites and basic scheduling tools. Three-tier pricing structure across premium, standard, and economy levels dominates the market, with subscription financing displacing perpetual licenses fastest among mid-tier contractors. Pricing pressure stems from private equity-backed buyers prioritizing cash flow flexibility over long-term cost optimization. Specialty contractors show highest price sensitivity due to thin project margins, while sovereign wealth-backed developers in the United Arab Emirates demonstrate lowest sensitivity.
Supply Chain Analysis
Export control regimes on geospatial positioning and sensor fusion technologies limit hardware-software bundling flows between the United States and China. Cloud infrastructure concentrates in the United States, Ireland, and Singapore for primary hosting, with secondary nodes in Germany and the United Arab Emirates for data sovereignty compliance. Raw material dependencies span semiconductor chips for wearable sensors, lithium-ion cells for field devices, and rare earth elements for precision positioning hardware. Single-source vulnerability runs through Taiwan-based semiconductor foundries. Distribution runs through direct enterprise sales teams for large contractors and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction jobsite management software sits in early-cycle expansion as OSHA digitization mandates and EU Green Deal traceability requirements force first-time adoption among legacy paper-based contractors.
For Market Incumbents: Pre-empt API-first platform fragmentation by consolidating middleware capabilities before systems integrators capture implementation margins. Defend against cloud-native specialists through backward integration into sensor hardware for field data capture. ISO 19650 certification investment represents the priority defensive lever as compliance timelines extend sales cycles.
For New Entrants and Emerging Players: Build out localized cloud infrastructure in India to capture national highway and urban metro expansion before established vendors establish Hindi-language support. Facility manager operational handoff contracts in the United Kingdom offer the most penetrable white-space segment. Channel partnerships with construction technology consultants provide the strongest go-to-market angle for bypassing entrenched procurement relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertical capability acquisition over horizontal platform rollups. Long-term viability hinges on BIM-to-field data pipeline ownership extending through operational phases. Acquisition targets should demonstrate embedded sensor integration and post-construction digital twin maintenance contracts. The signal to watch is sovereign wealth fund infrastructure commitment announcements in the United Arab Emirates and Saudi Arabia.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Rebuild | Replaces monolithic legacy stacks to satisfy Procore and Autodesk interoperability demands. |
| Sensor Hardware Integration | Captures wearable safety data streams required by OSHA digitization mandates. |
| Localized Cloud Infrastructure | Addresses GDPR and MOHAP data residency requirements in Germany and the United Arab Emirates. |
| Digital Twin Maintenance Contracts | Extends revenue into operational phases for United Kingdom commercial real estate owners. |
| ISO 19650 Certification Pathway | Unlocks cross-border project collaboration in EU Green Deal compliant developments. |
Research Methodology
A spread of perspectives from general contractor IT directors, specialty trade superintendents, facility manager procurement leads, and construction technology consultants converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings, hyperscaler capex disclosures, OSHA regulatory dockets, and EU Green Deal implementation guidance. Bottom-up project pipeline enumeration triangulated against top-down vendor revenue aggregation across the analysis window.
Demand-supply balance framing anchored the forecast framework, modeling deployment model transitions, customer type concentration shifts, and module adoption velocity across the projection horizon. Segmentation dimensions spanned software module, deployment topology, use case intensity, and customer procurement sophistication. CAGRs derived from historical vendor growth trajectories, project backlog analysis, and regulatory compliance deadline clustering. BIM-to-field integration maturity and carbon accounting module attach rates served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sovereign wealth-backed developers or hyperscaler platform entrants would shift outcomes. Material shifts in OSHA enforcement intensity, EU Green Deal building code acceleration, or India PLI scheme construction technology incentives would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Construction Suites Software Market
Software & Services
Automotive Operating Systems Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
Animation Design Software Market
Software & Services
North America Workforce Management Software Market
Software & Services
Global Jewelry Store Management Software Market
Software & Services
Software Release Management Tools Market
Software & Services
File Sharing Software Market
Software & Services
Drone Mapping Software Market
Software & Services
Global Desktop As a Service Market
Software & Services
Global Brand Management Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
Global AB Testing Software Market
Software & Services
Admission Management Software Market
Software & Services
Global Third-Party Logistics Software Market