
 Account-Based Advertising Software Market | 2026-2036
Account-Based Advertising Software Market Size, Share, and Industry Trends Forecast 2026-2036
Account-Based Advertising Software Market Outlook
Multi-source data integration is hardening as the dominant sourcing pattern among enterprise buyers evaluating account-based advertising platforms. Demandbase One leverages its proprietary intent data graph to sustain competitive differentiation in the identity resolution layer. 6sense anchors its position through AI-driven predictive scoring that competes with traditional lead-generation workflows. Madison Logic specializes in content syndication tied to account-level engagement, occupying a distinct niche in the mid-market segment.
Account-based advertising software orchestrates targeted media delivery and message personalization across known and anonymous stakeholders at prioritized accounts, typically integrating customer data platforms, demand-side interfaces, and measurement dashboards into unified execution layers. Cloud-based deployment leads structural adoption due to elastic infrastructure requirements for real-time bidding and cross-channel frequency management, while data analytics solutions capture expanding margin pools as advertisers prioritize outcome attribution over impression volume. Email marketing maintains mature utility for direct nurture sequences, though social media advertising accelerates fastest as platform identity graphs partially offset signal loss from browser-level tracking restrictions.
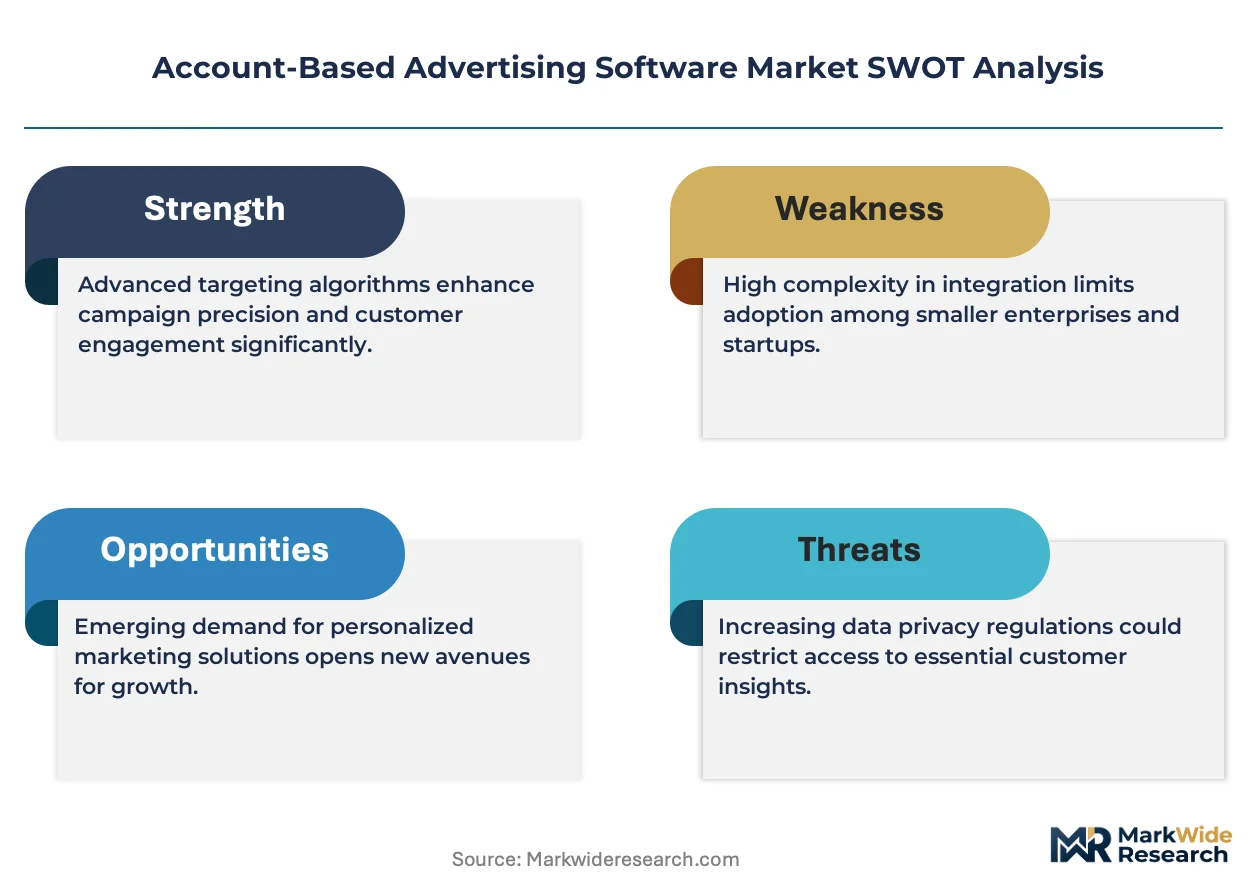
The Federal Trade Commission scrutinizes data broker practices and cross-site tracking disclosures, pressuring vendors to engineer consent-forward collection architectures, while the California Consumer Privacy Act and emerging state-level frameworks in Virginia and Colorado fragment compliance obligations for nationally deployed platforms. The European Union's General Data Protection Regulation and Digital Markets Act collectively restrict behavioral profiling without explicit legal basis, shaping product roadmaps toward contextual and first-party data methodologies. Stakeholders must monitor regulatory divergence between federal privacy legislation prospects and patchwork state enforcement to calibrate investment in identity infrastructure versus contextual targeting capabilities.
Market Dynamics
First-party data infrastructure investments are compressing competitive differentiation timelines as B2B enterprises abandon third-party cookie dependency ahead of browser-level enforcement. Cloud-native deployment architectures now determine vendor selection criteria more than feature breadth alone.
Growth Catalysts
- GDPR Article 7 Consent Framework:European enforcement of explicit legal basis requirements accelerates migration toward publisher-direct data partnerships and contextual targeting methodologies.
- Predictive Intent Signal Processing:Machine learning models analyzing anonymous web behavior enable precision targeting without personal identifiers, attracting technology sector procurement.
- Mid-Market Content Syndication:Specialized agencies bundle account-level engagement tracking with media execution, expanding addressable demand among professional services firms.
Market Restraints
- Identity Graph Fragmentation:Platform-specific identifier systems from LinkedIn, Google, and proprietary publishers create interoperability costs and media planning complexity.
- Cross-Border Data Transfer Friction:Schrems II rulings invalidate EU-US Privacy Shield mechanisms, forcing infrastructure duplication for transatlantic campaign execution.
- Technical Talent Scarcity:Shortage of engineers skilled in differential privacy and federated learning constrains product roadmap velocity across vendor tiers.
Strategic Opportunities
- Clean Room Infrastructure:Privacy-preserving computation environments enable secure data collaboration between advertisers and publishers without raw data exchange.
- Vertical-Specific Intent Models:Custom scoring algorithms for healthcare and financial services verticals capture premium pricing through regulatory-compliant precision.
- Connected TV Integration:Household-level IP targeting bridges B2C and B2B media planning as professional viewing patterns fragment across streaming platforms.
Industry Challenges
- Legacy CRM Integration Complexity:Enterprise Salesforce and Microsoft Dynamics deployments require custom API development for real-time account scoring synchronization.
- Attribution Model Standardization Delays:Absence of industry consensus on multi-touch credit allocation creates measurement disputes between marketing and finance stakeholders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Account-Based Advertising Software Market |
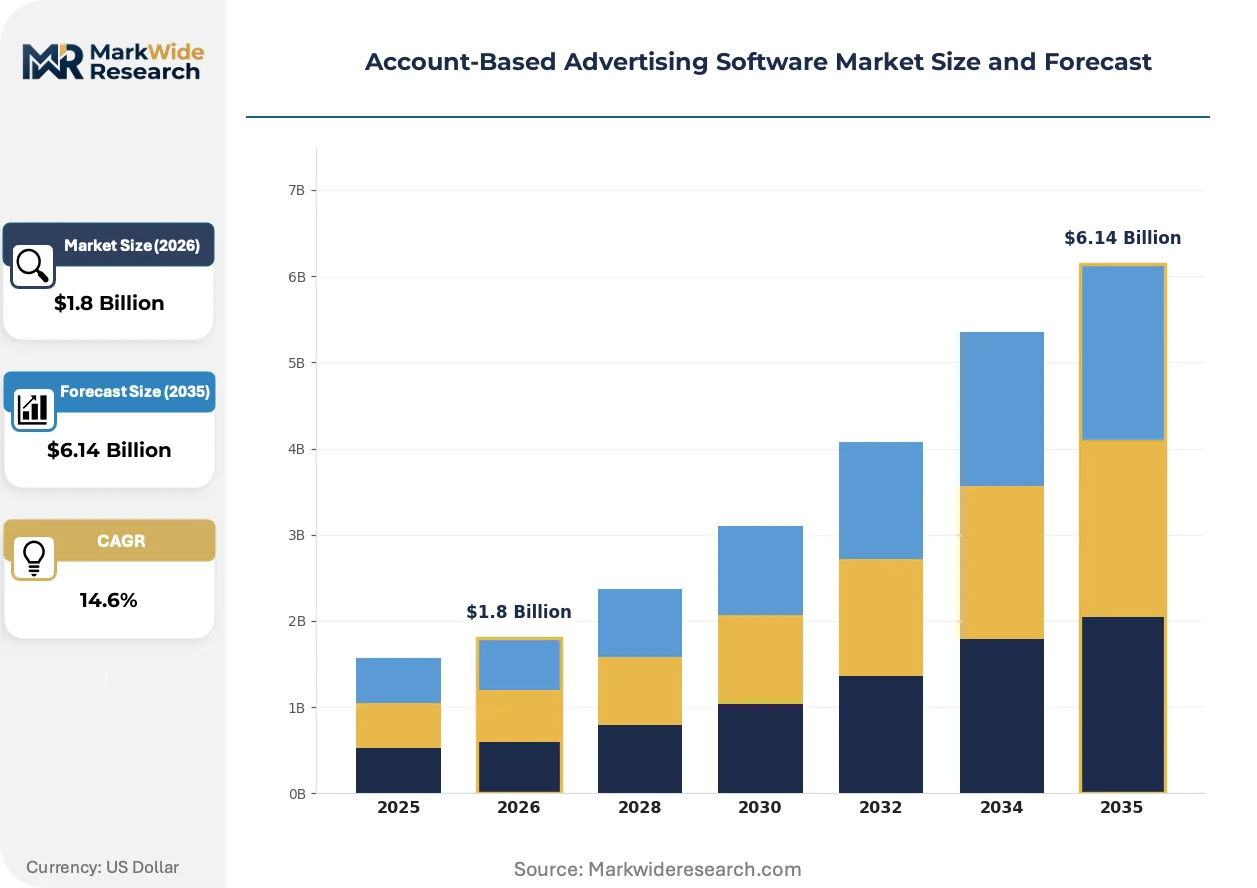
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Solution: Email Marketing, Social Media Advertising, Content Personalization, Data Analytics End User: B2B Enterprises, Marketing Agencies, E-Commerce, Technology Firms Customer Type: Small Businesses, Medium Enterprises, Large Corporations, Startups |
| Companies Covered | ZoomInfo Marketing, Demandbase One, 6sense, RollWorks, Terminus, AdRoll ABM, pharosIQ, N.Rich, Madison Logic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Account-Based Advertising Software Market Strategic Shifts
Artificial intelligence is compressing the latency between intent signal detection and media activation, collapsing traditional planning cycles from weeks to hours. This acceleration demands fundamental reconfiguration of organizational workflows and vendor capability stacks.
AI-powered predictive scoring is consolidating vendor competitive positions around proprietary data assets rather than software features alone. Technology firms and marketing agencies with first-mover investments in training data acquisition now capture disproportionate margin from campaign execution. The technology is consolidating market structure toward platforms with captive intent graphs and away from point solutions dependent on third-party data feeds.
The European Union's Digital Markets Act imposes interoperability mandates on designated gatekeeper platforms, forcing identity system openness that challenges proprietary targeting advantages. Industrial consequence includes mandatory API access for smaller advertising technology vendors to platform data. European-headquartered B2B software vendors face accelerated compliance investment while gaining potential data portability benefits against dominant US platforms.
Enterprise procurement patterns are rotating from perpetual licensing toward consumption-based pricing tied to qualified account engagement outcomes. Marketing operations teams displace traditional media buying relationships with direct platform contracts and in-house trading desk capabilities. This behavioral shift concentrates most visibly among North American technology sector enterprises with mature marketing operations functions and centralized data infrastructure.
Account-Based Advertising Software Market Segmentation
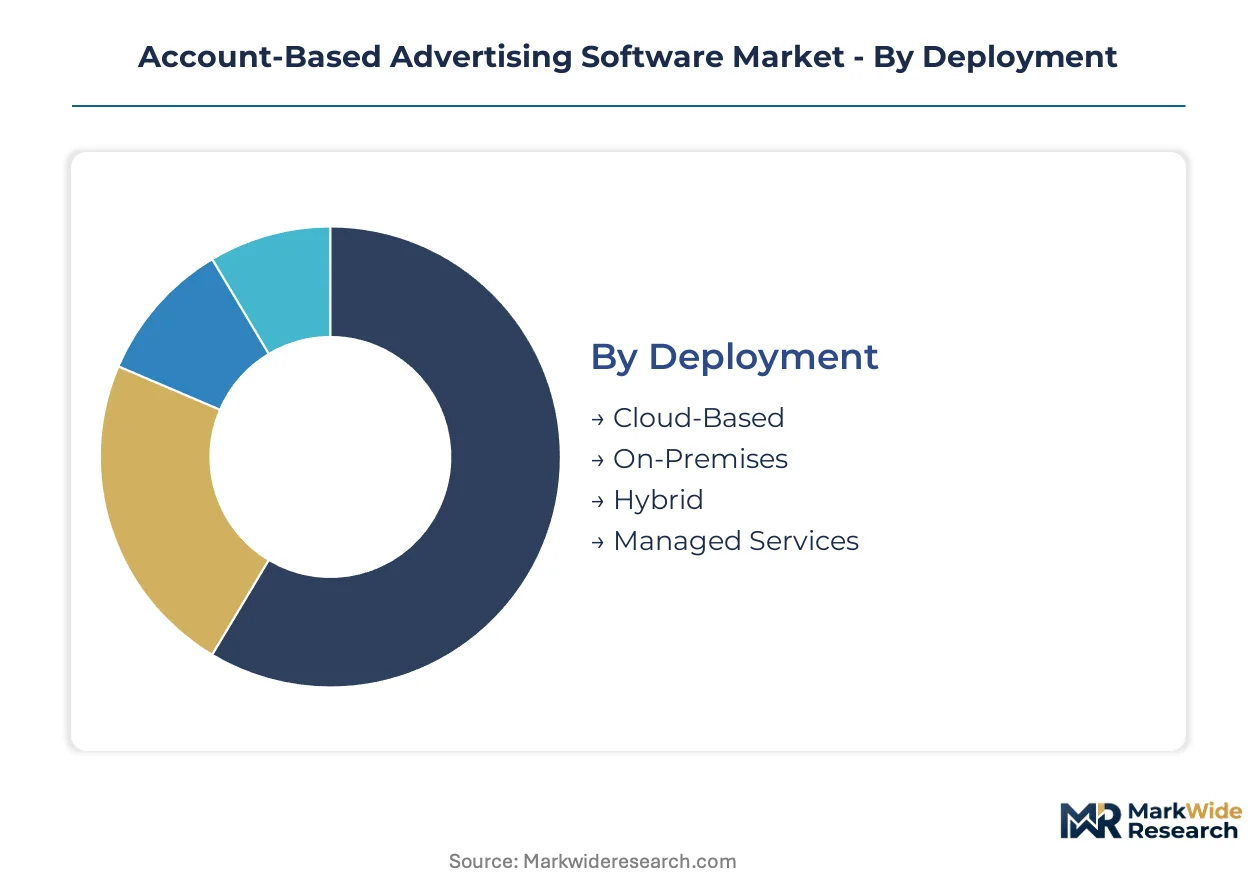
Segmentation in account-based advertising software reveals how infrastructure choices, solution architectures, and buyer profiles allocate value across the technology stack. Deployment models determine scalability constraints, while solution types reflect shifting priorities between reach and precision.
Deployment:
Cloud infrastructure concentration among hyperscale providers is compressing vendor margin structures and accelerating consolidation among platform operators.
- Cloud-Based:Elastic compute resources enable real-time bidding and cross-channel frequency management without capital expenditure. North American technology firms concentrate procurement here, driven by API-native integration requirements with existing martech stacks.
- On-Premises:Self-managed installations retain sensitive account data within organizational firewalls, serving financial services and healthcare verticals with stringent data residency mandates. European-headquartered enterprises favor this model given GDPR enforcement patterns and Schrems II transfer restrictions.
- Hybrid:Split architectures process anonymous signals in cloud environments while retaining identified account records on local infrastructure. Germany's industrial manufacturing sector shows particular appetite for this configuration.
- Managed Services:Outsourced platform operation transfers operational complexity to specialized service providers. Mid-market professional services firms in the United Kingdom adopt this model to bypass internal technical talent constraints.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Solution:
Functional specialization across the advertising workflow is fragmenting procurement patterns, with buyers assembling best-of-breed stacks rather than accepting bundled suites.
- Email Marketing:Direct nurture sequences sustain mature utility for account penetration and stakeholder relationship development. B2B enterprises with established marketing operations functions in the United States leverage this for post-engagement conversion acceleration.
- Social Media Advertising:Platform identity graphs from LinkedIn and specialized B2B networks partially offset signal loss from browser-level tracking restrictions. Technology sector procurement is climbing the fastest as professional audience concentration justifies premium media costs.
- Content Personalization:Dynamic creative optimization tailors messaging to account-level firmographic and behavioral attributes. Marketing agencies bundle this capability with strategic services for mid-market clients.
- Data Analytics:Outcome attribution and multi-touch credit allocation capture expanding margin pools as advertisers prioritize measurement over impression volume. Large corporations with centralized data science functions drive premium pricing here.
Email Marketing commands current spend. Social Media Advertising is gaining share fastest.
End User:
Organizational sophistication and data maturity determine solution complexity thresholds, creating distinct service tiers across buyer categories.
- B2B Enterprises:Complex account hierarchies and extended sales cycles demand orchestrated media delivery across buying committees. First-party data infrastructure investments by North American manufacturers are compressing competitive differentiation timelines for vendors serving this segment.
- Marketing Agencies:Multi-client management requirements drive demand for cross-account benchmarking and reusable audience segmentation. Independent agencies in the United Kingdom specialize in vertical-specific intent models for professional services clients.
- E-Commerce:Transaction velocity and SKU diversity create unique targeting challenges distinct from traditional B2B workflows. Direct-to-consumer brands with B2B wholesale channels in Germany adopt hybrid approaches.
- Technology Firms:Native digital sophistication enables in-house trading desk capabilities and direct platform relationships. Silicon Valley-headquartered SaaS providers concentrate most visibly here.
B2B Enterprises anchor current revenue. Technology Firms show steepest expansion trajectory.
Customer Type:
Organizational scale dictates pricing model acceptance and implementation complexity tolerance, shaping vendor go-to-market architectures.
- Small Businesses:Simplified self-service interfaces and outcome-based pricing reduce barrier to entry. Regional marketing consultancies in France serve this segment through bundled platform access.
- Medium Enterprises:Growing marketing operations functions seek configurability without enterprise integration overhead. Professional services firms in Canada represent concentrated demand here.
- Large Corporations:Custom API development and dedicated customer success resources justify substantial contract values. Fortune 500 industrials in the United States drive requirements for legacy CRM synchronization.
- Startups:Rapid scaling needs and limited historical data create demand for predictive intent signal processing. Venture-backed B2B software companies in Israel adopt early to establish competitive positioning.
Large Corporations dominate vendor pipelines. Medium Enterprises are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of B2B SaaS enterprises generates disproportionate procurement volume for account-based advertising platforms, with technology sector marketing operations driving cloud-native adoption ahead of other verticals.
United States
Fortune 500 manufacturers in Michigan and Ohio are consolidating first-party data infrastructure investments, compressing vendor evaluation cycles. The FTC scrutinizes data broker disclosure practices, pressuring platforms toward consent-forward collection architectures. Chicago's professional services cluster demonstrates concentrated demand for predictive intent signal processing among mid-market agencies.
Germany
Industrial manufacturing headquarters in Bavaria favor hybrid deployment models that process anonymous signals in cloud environments while retaining identified account records locally. GDPR Article 7 enforcement accelerates migration toward publisher-direct data partnerships. Frankfurt's financial services sector maintains stringent data residency mandates, sustaining on-premises installation demand.
United Kingdom
London's independent marketing agencies specialize in vertical-specific intent models for professional services clients, bundling account-level engagement tracking with strategic execution. The Information Commissioner's Office enforces explicit consent requirements for behavioral profiling. Manchester's mid-market consultancies adopt managed services configurations to bypass internal technical talent constraints.
Japan
Tokyo-headquartered electronics conglomerates prioritize legacy CRM synchronization capabilities, driving requirements for custom API development with Salesforce and Microsoft Dynamics deployments. METI guidelines shape data governance expectations for cross-border campaign execution. Osaka's precision manufacturing sector shows emerging appetite for connected TV integration bridging B2C and B2B media planning.
Israel
Venture-backed B2B software companies in Tel Aviv adopt predictive intent signal processing early to establish competitive positioning in crowded SaaS categories. The Privacy Protection Authority enforces alignment with GDPR-equivalent standards for European market access. Herzliya's cybersecurity cluster generates specialized demand for privacy-preserving computation environments enabling secure advertiser-publisher collaboration.
Account-Based Advertising Software Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue AI-native positioning and vertical specialization as differentiation vectors. The vendor landscape stratifies between comprehensive platforms with captive intent graphs and point solutions dependent on third-party data feeds. Three archetypes dominate: data asset consolidators, workflow automation specialists, and measurement-centric analytics providers. Competitive dynamics center on M&A activity targeting intent data assets and strategic partnerships with cloud infrastructure hyperscalers.
Within the data asset consolidator tier, Demandbase and 6sense exemplify platforms competing through proprietary signal infrastructure rather than software features alone. Madison Logic occupies a position among workflow specialists, bundling content syndication with account-level engagement tracking for mid-market penetration. ZoomInfo Marketing represents the scale-driven archetype, leveraging existing contact database dominance to extend into advertising execution layers. These three companies anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| ZoomInfo Marketing |
| Demandbase One |
| 6sense |
| RollWorks |
| Terminus |
| AdRoll ABM |
| pharosIQ |
| N.Rich |
| Madison Logic |
| Others |
Value Chain & Pricing Dynamics
Platform-native intent data access separates premium-tier vendors from commodity competitors, with that capability gap widening as first-party data infrastructure investments concentrate among North American technology firms and compress margin structures for point-solution providers dependent on third-party feeds.
Pricing Analysis
Input-cost pass-through from cloud infrastructure hyperscalers shapes vendor margin structures more than feature development expenses, with elastic compute pricing for real-time bidding engines consuming disproportionate operational expenditure. Three-tier pricing structure across premium, standard, and economy levels aligns with intent data graph exclusivity and API integration depth. Pricing pressure stems from mid-market procurement rotation toward consumption-based models tied to qualified account engagement outcomes. Small businesses exhibit highest price sensitivity, while large corporations with centralized data science functions accept substantial contract values for custom attribution development.
Supply Chain Analysis
Dual-sourcing requirements from enterprise procurement teams mandate redundant data partnerships with both proprietary intent graph operators and publisher-direct collection networks, complicating vendor qualification. Supply concentrates in the United States for cloud-native platform development, Israel for predictive signal processing engineering, and the United Kingdom for managed services configuration. Raw material dependencies span differential privacy computation frameworks, federated learning infrastructure, and cross-channel identity resolution protocols. Single-source vulnerability concentrates around hyperscale cloud provider concentration for elastic compute. Distribution runs through direct platform contracts displacing traditional media buying relationships among North American technology sector enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate between the United States and Germany, where GDPR Article 7 enforcement accelerates publisher-direct data partnership premiums that US-based vendors can capture through consent-forward architecture investments without equivalent compliance overhead.
For Market Incumbents: Anticipate margin compression from AI-native entrants with proprietary training data assets by accelerating first-party intent graph expansion through strategic publisher partnerships. Defensive consolidation moves should prioritize vertical-specific scoring algorithm acquisition for healthcare and financial services. Channel control through embedded CRM synchronization capabilities with Salesforce and Microsoft Dynamics deployments anchors retention against workflow automation specialists. For New Entrants and Emerging Players: Independent marketing agencies in the United Kingdom represent the most penetrable channel partner type, with bundled platform access and strategic execution services creating white-space entry below comprehensive platform tiers. Target mid-market professional services firms in Canada seeking configurability without enterprise integration overhead. A consumption-based pricing model tied to qualified account engagement outcomes bypasses incumbent perpetual licensing dominance. For Investors and Strategic Acquirers: Consolidation pressure builds where proprietary intent data assets concentrate among fewer platforms with captive signal infrastructure. Long-term viability favors data asset consolidators over workflow automation specialists dependent on third-party feeds. Acquisition target archetype: vertical-specific intent model developers with regulatory-compliant precision for healthcare and financial services. The signal to watch is cross-border data transfer friction escalation forcing infrastructure duplication for transatlantic campaign execution.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Clean Room Infrastructure | Secure advertiser-publisher collaboration without raw data exchange addresses Schrems II transfer restrictions. |
| Vertical-Specific Intent Model Development | Custom scoring algorithms for healthcare capture premium pricing through HIPAA-compliant precision targeting. |
| Connected TV Integration Buildout | Household-level IP targeting bridges B2C and B2B media planning as professional viewing fragments across streaming platforms. |
| Strategic Partnership with Cloud Hyperscalers | Elastic compute resource guarantees reduce operational expenditure volatility for real-time bidding engines. |
| Acquisition of Differential Privacy Engineering Talent | Federated learning capabilities constrain product roadmap velocity across vendor tiers due to technical scarcity. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with marketing operations executives, CTOs at B2B SaaS providers, independent agency principals, and platform integration specialists. Secondary validation draws from SEC filings of publicly traded advertising technology vendors, hyperscaler capex disclosures, GDPR enforcement documentation from European data protection authorities, and trade association reports from the Interactive Advertising Bureau. Bottom-up segmentation modeling triangulates against top-down market sizing from cloud infrastructure deployment metrics and martech stack penetration surveys.
Granularity-level framing applies deployment model, organization size, vertical specialization, and regional regulatory cluster as core segmentation dimensions across the analysis window. CAGRs derive from trend extrapolation of first-party data infrastructure investment trajectories and predictive intent signal processing adoption curves. Industry-specific forecast inputs include cloud-native procurement patterns among North American technology firms and GDPR compliance investment requirements for European-headquartered enterprises.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to browser-level tracking restriction enforcement timelines and federal privacy legislation prospects in the United States. Deviation in cross-border data transfer mechanism rulings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Mobile Application Development Platform (MADP) Market
Software & Services
Middle East and Africa Workforce Management Software Market
Software & Services
Systems Administration Management Tools Market
Software & Services
Global Applicant Tracking Software Market
Software & Services
Saas Based HRM Market
Software & Services
Adaptive Learning Software Market
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Test Management Software Market
Software & Services
Global HMI Software Market
Software & Services
Office Productivity Software Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Stock Media Software Market
Software & Services
Global Chemical Software Market
Software & Services
Telecom IT Services Market