
 Solar Rooftop Design Software Market | 2026-2036
Solar Rooftop Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Rooftop Design Software Market Insights
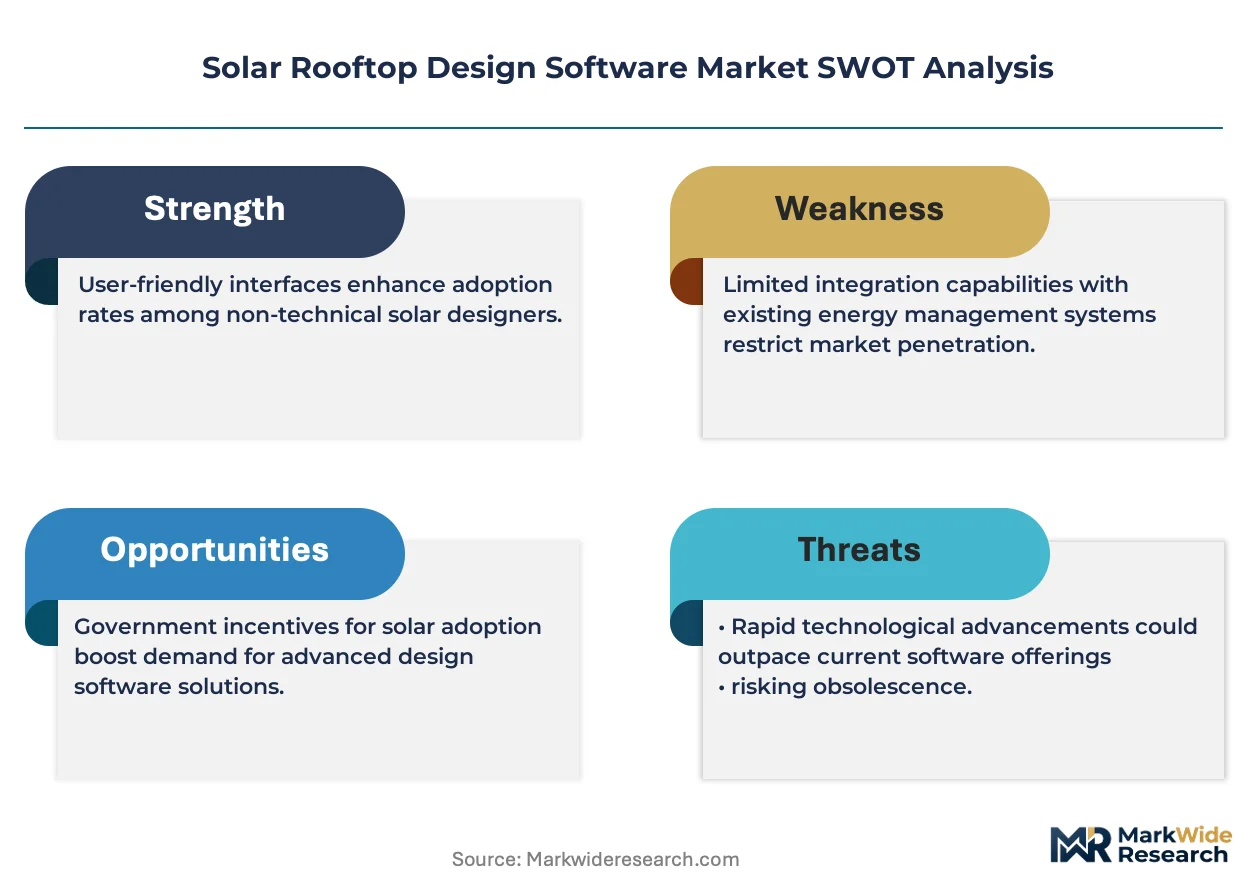
PV system performance-grade design specifications are bifurcating the competitive landscape between precision-engineering specialists and volume-platform providers. Aurora Solar leverages proprietary shading engines and bankability-grade documentation to dominate the North American installer base. OpenSolar sustains a freemium-to-paid conversion model that anchors market share among emerging-market contractors with thin hardware margins.
Solar rooftop design software encompasses computational platforms that model photovoltaic array geometry, irradiance capture, and electrical configuration against structural constraints and local code requirements; these systems integrate satellite imagery, LiDAR data, and weather file interpolation to generate permit-ready engineering documents and production forecasts. Cloud-based deployment models now lead segment growth as distributed installer workforces demand real-time collaboration and mobile site access, while on-premise solutions retain footholds among large EPCs with stringent data sovereignty requirements. Simulation software with bankable energy yield predictions commands premium pricing relative to basic layout tools.
California's Solar Rights Act and the federal Investment Tax Credit framework shape product roadmaps by mandating specific documentation formats and performance disclosures that software must automate. The Federal Housing Administration and state-level contractor licensing boards impose continuing education and design standard requirements that platform vendors encode into compliance modules. Stakeholders must monitor how evolving interconnection standards in key state jurisdictions redefine the feature sets that secure renewals and upsells.
Market Dynamics
NEM 3.0 net metering reforms in California are compressing soft-cost economics and forcing design software vendors to retool around storage-integrated workflows and time-of-use optimization rather than simple production maximization.
Growth Catalysts
- Investment Tax Credit framework:The federal incentive structure mandates specific performance documentation formats that automated design platforms must encode, creating built-in demand for compliance-grade software modules among residential installers.
- LiDAR data integration:High-resolution terrain mapping is reducing site visit requirements and accelerating remote sales cycles for distributed solar contractors operating across high-penetration rooftop markets.
- Germany's EEG renewable energy auctions:The competitive bidding system for distributed generation projects requires bankable yield documentation that only advanced simulation engines can produce, elevating software from layout tool to project finance enabler.
Market Restraints
- Cloud infrastructure cost volatility:Processing-intensive shading simulations and 3D modeling workloads tie vendor margins to hyperscaler pricing, with AWS and Azure rate fluctuations directly compressing SaaS gross margins.
- Data sovereignty requirements:Large European EPCs with defense or critical infrastructure contracts demand on-premise deployments, fragmenting vendor R&D resources across divergent architecture stacks.
- Interconnection standard fragmentation:IEEE 1547 revisions and state-level implementation timelines create compliance mapping complexity that slows feature rollouts and extends sales cycles.
Strategic Opportunities
- India's rooftop solar program:The country's national renewable targets and simplified net metering regulations for sub-10kW systems create a greenfield contractor base lacking legacy software workflows.
- Vehicle-to-grid convergence:Bidirectional EV charging integration with residential solar-plus-storage systems opens new design modules for software platforms to capture.
- Utility-scale distributed generation:Commercial and industrial rooftop portfolios above 500kW require enterprise-grade project management layers that basic residential tools cannot address.
Industry Challenges
- Electrical engineering talent scarcity:Rapid installer workforce expansion outpaces the supply of licensed professional engineers capable of reviewing and stamping permit packages generated by automated platforms.
- AHJ approval timeline variability:Authority Having Jurisdiction interpretation differences across municipal boundaries force software vendors to maintain thousands of jurisdiction-specific rule sets and inspection checklists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Rooftop Design Software Market |
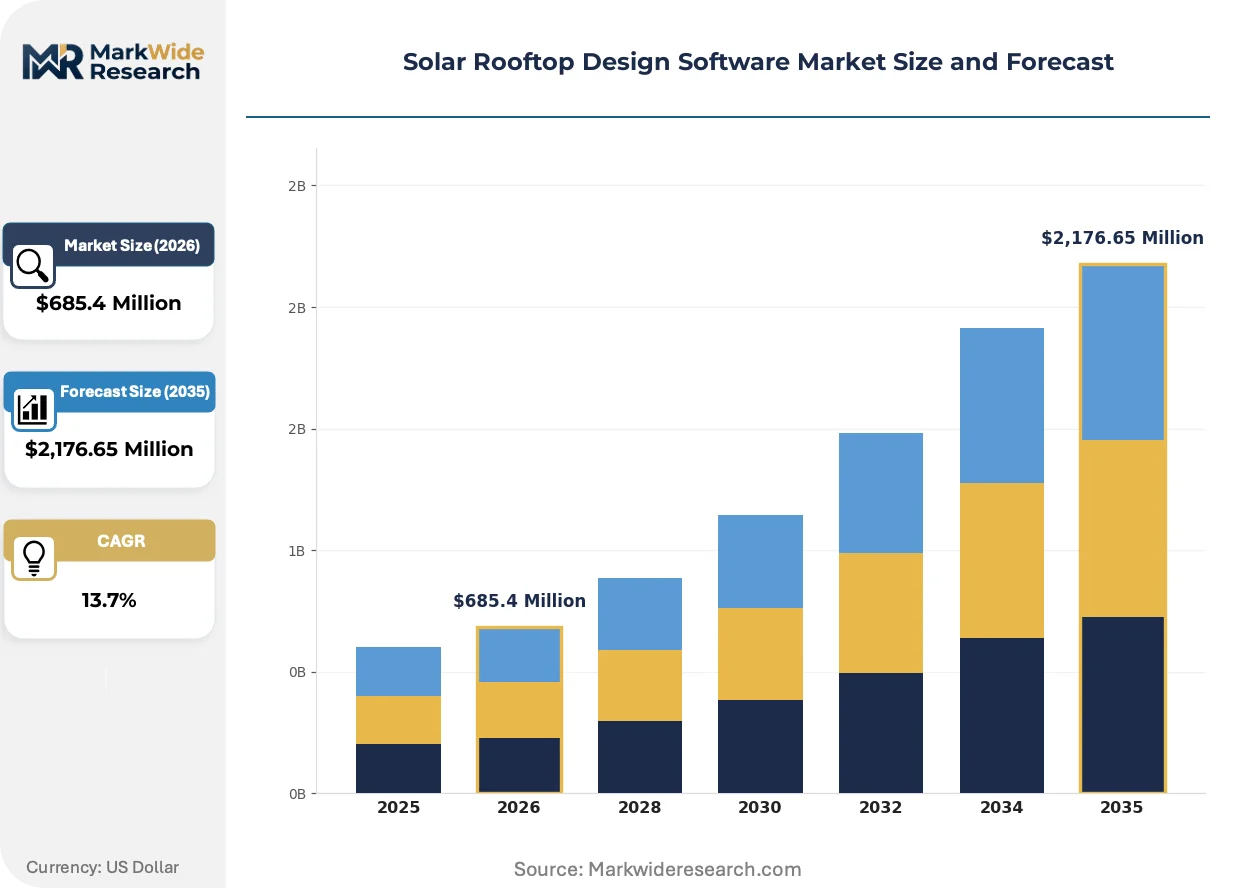
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,176.65 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design Tools, Simulation Software, Monitoring Solutions, Analytical Platforms Deployment Model: On-Premise, Cloud-Based, Hybrid Solutions, SaaS End User: Installers, Contractors, Architects, Homeowners Feature: 3D Modeling, Cost Estimation, Performance Analysis, Customization Options |
| Companies Covered | Aurora Solar, OpenSolar, Solargraf, HelioScope, Sunbase, ARKA 360, PV*SOL, Solo, Pylon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Rooftop Design Software Market Trends and Innovations
Generative AI is compressing the traditional design-to-permit workflow from days to hours, while satellite imagery resolution improvements and regulatory data standardization are converging to reshape how distributed solar projects are engineered and financed.
LiDAR-derived digital surface models are supplanting manual roof measurements and drone-based site surveys as the primary input for shading analysis and structural load calculations. Residential installers in California and Australia have adopted these remote data sources for over 80% of preliminary designs, collapsing customer acquisition costs and compressing the sales cycle from multiple site visits to single virtual consultations. This displacement of physical inspection is compressing the addressable market for traditional site assessment services and elevating software vendors to gatekeeper status in project origination.
The EPA's proposed greenhouse gas disclosure rules for federal contractors are cascading into solar supply chain documentation requirements that design software must automate. Commercial and industrial project developers now face Scope 3 emissions tracking mandates that extend from module manufacturing through installation, forcing platforms to integrate carbon accounting modules alongside traditional performance modeling. EPCs bidding on federal buildings or federally-backed financing are re-platforming to vendors with embedded compliance reporting rather than retrofitting manual processes.
Subscription-based software procurement is displacing perpetual license models among mid-sized installer networks seeking to align technology costs with project volume volatility. Regional dealer networks and franchise operations in the United States are consolidating vendor relationships around usage-based pricing that scales with active project pipelines rather than seat counts. This shift is most visible in the Sunbelt states where seasonal installation swings of 40-60% make fixed software costs a disproportionate burden on margin management.
Solar Rooftop Design Software Market Segmentation
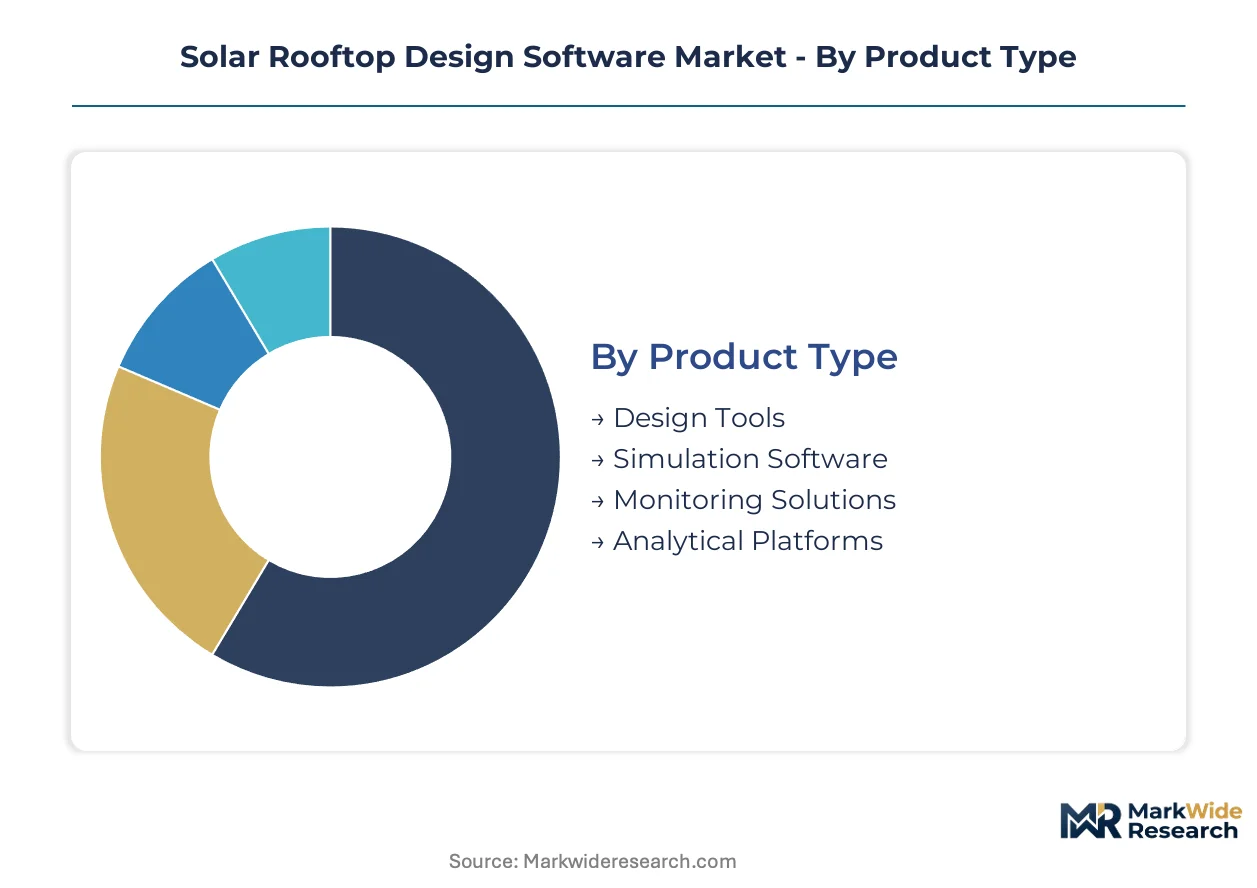
Solar rooftop design software segments fragment along technical capability lines, with precision-engineering modules commanding premium positioning against commoditized layout tools. Understanding substitution pressures across product tiers and deployment architectures reveals where vendor R&D investments concentrate and margin structures diverge.
Product Type:
Simulation software faces acute substitution pressure from generative AI platforms that compress yield forecasting into automated workflows, while basic design tools confront free alternatives that erode entry-level pricing power.
- Design Tools:Core layout platforms model array geometry, string configuration, and structural mounting against local code databases. Demand concentrates among residential contractors in California and Texas where rapid permit turnaround requirements favor automation over manual drafting.
- Simulation Software:Bankable energy yield engines integrate weather file interpolation, degradation modeling, and financial scenario analysis to satisfy project finance due diligence. Installers bidding into Germany's EEG auction system require these modules to secure debt financing, elevating them from optional add-on to mandatory procurement.
- Monitoring Solutions:Post-installation performance tracking platforms with inverter-agnostic data aggregation.
- Analytical Platforms:Portfolio-level benchmarking and predictive maintenance engines for multi-site operators.
Design tools retain volume leadership; simulation software holds the steepest expansion curve.
Deployment Model:
Cost tier stratification separates enterprise-grade on-premise installations from mass-market SaaS subscriptions, with hybrid architectures capturing mid-market contractors seeking data sovereignty without capital intensity.
- On-Premise:Self-hosted deployments with local compute resources for shading analysis and 3D rendering. European EPCs with defense sector contracts or critical infrastructure mandates in Germany and France select these configurations to satisfy national data residency requirements imposed by procurement regulations.
- Cloud-Based:Fully managed SaaS infrastructure with automatic scaling for peak simulation workloads. Distributed installer networks across Australia's Queensland and Victoria states favor this model for mobile site access and real-time collaboration across dispersed sales teams.
- Hybrid Solutions:Split architectures keeping sensitive project data local while leveraging cloud compute for intensive simulations.
- SaaS:Subscription-native platforms with usage-based pricing tied to active project pipelines.
Cloud-based deployments capture the widest installer base; hybrid solutions are climbing fastest among security-conscious mid-market buyers.
End User:
Customer type segmentation maps directly to feature complexity requirements, with homeowner-facing tools experiencing downward price pressure from free consumer applications while professional-grade modules sustain premium positioning.
- Installers:Full-stack platforms integrating lead management, design automation, permit generation, and project handoff. National dealer networks in the United States Sunbelt states consolidate procurement around these systems to standardize output quality across franchise operations.
- Contractors:Specialized electrical and roofing trades requiring structural load calculators and AHJ-specific code checklists. Regional specialists in India's Maharashtra and Gujarat states adopt these modules as rooftop solar targets accelerate contractor certification requirements.
- Architects:Building-integrated photovoltaics design tools with aesthetic rendering and material specification databases.
- Homeowners:Simplified consumer interfaces with instant savings calculators and financing option comparisons.
Installer-facing platforms dominate revenue concentration; contractor modules are expanding most quickly in emerging markets.
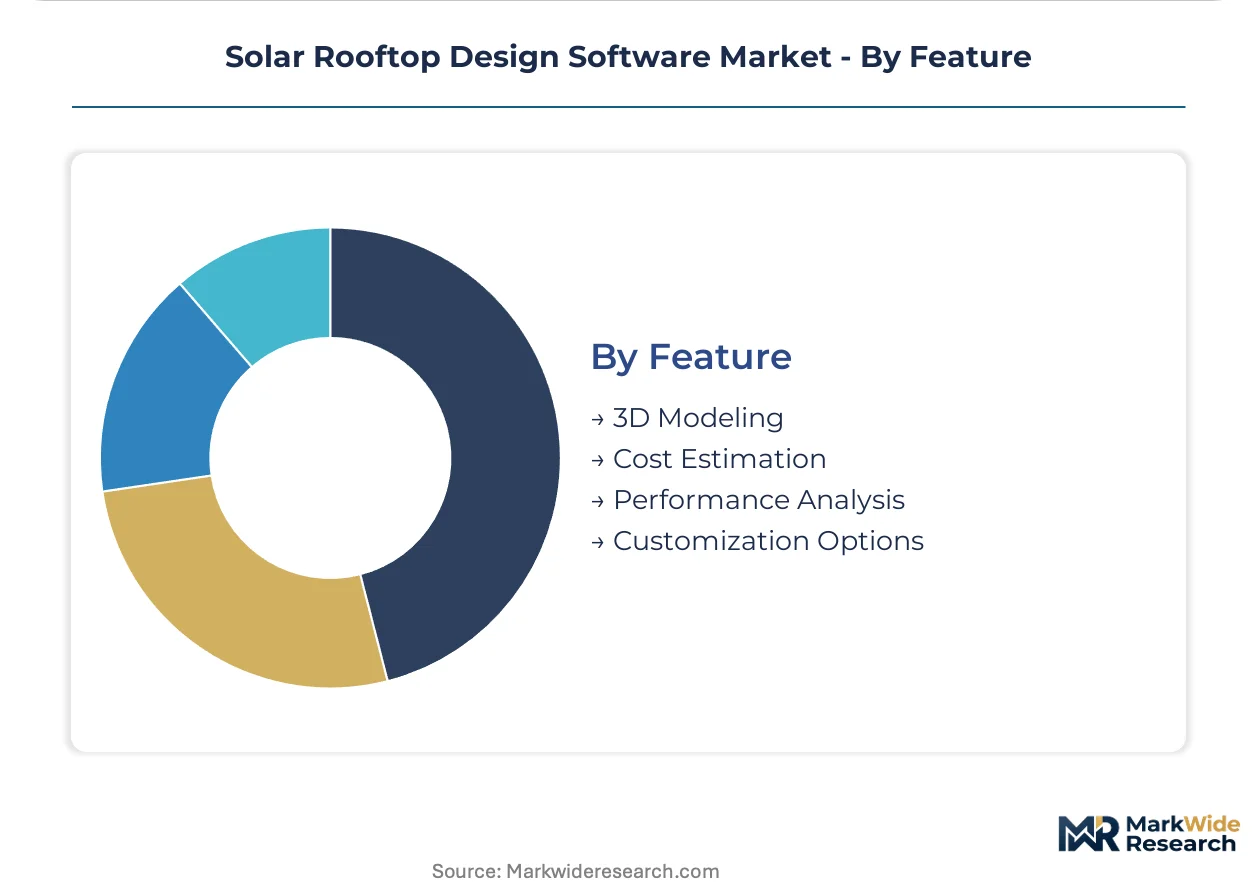
Feature:
Application-driven segmentation reveals which capabilities differentiate premium tiers, with 3D modeling and performance analysis functioning as core competitive battlegrounds while cost estimation faces automation-driven commoditization.
- 3D Modeling:LiDAR-derived digital surface reconstruction with shading simulation and structural visualization. Remote sales teams in California's NEM 3.0 environment depend on these capabilities to replace physical site visits and compress customer acquisition timelines.
- Performance Analysis:Production forecasting engines with bankable uncertainty quantification and degradation modeling. Australia's Clean Energy Council accreditation requirements mandate specific simulation methodologies that only advanced platforms can automate.
- Cost Estimation:Automated bill-of-materials generation with real-time pricing integration from distributor APIs.
- Customization Options:White-label interfaces and API access for large installer networks seeking brand differentiation.
Performance analysis modules anchor premium pricing; 3D modeling capabilities are gaining share fastest as remote sales displace physical inspection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development clusters concentrate in jurisdictions with dense installer networks and stringent permitting requirements. California's regulatory complexity and Germany's bankable yield standards have spawned the most sophisticated vendor ecosystems.
United States
Residential installer networks in California, Texas, and Florida drive demand for NEM 3.0-compliant storage-integrated workflows. The Federal Housing Administration mandates specific documentation formats that automated platforms encode. Los Angeles and San Diego host the highest concentration of vendor sales operations serving distributed generation contractors.
Germany
EEG renewable energy auctions require bankable yield documentation that elevates simulation software to project finance enabler status. The Federal Network Agency enforces interconnection standards that shape feature development roadmaps. Bavaria and North Rhine-Westphalia concentrate the largest EPC user bases with data sovereignty requirements for on-premise deployments.
Australia
Queensland and Victoria installer networks favor cloud-based SaaS models for mobile site access across dispersed sales teams. The Clean Energy Council accreditation mandates specific simulation methodologies. Sydney and Melbourne anchor vendor support operations for the Asia-Pacific contractor base.
India
Maharashtra and Gujarat contractor certification requirements accelerate adoption of structural load calculators and AHJ-specific modules. The Ministry of New and Renewable Energy's rooftop solar targets create greenfield demand lacking legacy software workflows. Mumbai and Ahmedabad concentrate emerging-market vendor expansion efforts.
Solar Rooftop Design Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Precision-engineering specialists command premium positioning through proprietary shading engines and bankability-grade documentation, while volume-platform providers compete on accessibility and rapid deployment. The market consolidates around three strategic archetypes: full-stack enterprise platforms, freemium volume providers, and specialized simulation engines. Dominant competitive moves include geographic expansion into emerging rooftop markets and portfolio diversification into storage-integrated workflows.
Within the precision-engineering tier, Aurora Solar and HelioScope exemplify vendors that have captured North American installer loyalty through technical depth. OpenSolar occupies a distinct position among emerging-market contractors with its freemium-to-paid conversion architecture. These three anchors demonstrate how vendor strategy diverges between bankable documentation requirements and thin-margin hardware ecosystems.
| Leading Market Players |
|---|
| Aurora Solar |
| OpenSolar |
| Solargraf |
| HelioScope |
| Sunbase |
| ARKA 360 |
| PV*SOL |
| Solo |
| Pylon |
| Others |
Pricing and Supply Chain Analysis
Federal Housing Administration documentation mandates gate both vendor qualification and subscription tier differentiation in the solar rooftop design software market, compressing entry-level margins while elevating bankable-grade modules to premium positioning. Installers bidding into federally-backed financing programs face compliance automation requirements that stratify procurement budgets across certification levels.
Pricing Analysis
The Investment Tax Credit framework dictates the pricing tier structure across deployment models, separating bankable documentation engines from basic layout tools. Three-tier pricing structure across premium, standard, and economy levels rests on simulation precision, AHJ coverage breadth, and API integration depth. Cost compression in the entry tier is intensifying because generative AI platforms displace manual design workflows. Residential contractors in high-penetration markets exhibit the sharpest price sensitivity, while commercial EPCs bidding into project finance tolerate premium positioning for yield certainty.
Supply Chain Analysis
The United States and Germany anchor software development clusters, with India and Australia emerging as delivery hubs for implementation support and localization. Cloud infrastructure draws from hyperscaler networks across AWS, Azure, and Google Cloud Platform, while LiDAR data feeds from aerial survey specialists and satellite imagery providers. Single-source vulnerability concentrates in hyperscaler pricing volatility, which directly compresses SaaS vendor margins. Distribution runs through direct sales teams serving national installer networks, with channel partnerships penetrating regional contractor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat, where AHJ-specific rule libraries and bankable documentation formats create switching costs that cement incumbent positions across renewal cycles.
For Market Incumbents: Fortify data sovereignty capabilities through hybrid deployment architectures that capture European EPC procurement requirements. Deepen LiDAR integration partnerships to accelerate remote sales workflows before generative AI platforms commoditize basic shading analysis. Anchor renewal pricing to storage-integrated feature modules that address NEM 3.0 economics. For New Entrants and Emerging Players: Anchor in India's rooftop solar program, where simplified net metering regulations and absent legacy workflows create greenfield contractor demand. Target Maharashtra and Gujarat certification requirements with localized AHJ modules and regional language interfaces. Pursue freemium conversion models that align with thin hardware margins in emerging-market installer ecosystems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native SaaS deployments, reducing barrier-to-entry concerns while elevating customer acquisition efficiency as the critical valuation driver. Acquisition targets should display dense AHJ rule libraries and embedded storage workflow capabilities. Monitor California interconnection standard implementation timelines as the signal for platform consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Storage-Integrated Workflow Launch | NEM 3.0 compliance captures California installer procurement budgets ahead of competitor migration. |
| LiDAR Data Partnership Expansion | Remote sales automation collapses customer acquisition costs for distributed contractor networks. |
| Hybrid Deployment Architecture | Data sovereignty modules unlock European defense and critical infrastructure EPC contracts. |
| AHJ Rule Library Acquisition | Jurisdiction-specific compliance automation accelerates permit turnaround for high-volume installers. |
| Vehicle-to-Grid Module Development | Bidirectional EV integration captures emerging residential solar-plus-storage design demand. |
Research Methodology
A standing panel of solar EPC project managers, residential installer operations directors, AHJ permitting officers, and utility interconnection specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from FERC interconnection filings, EIA distributed generation databases, state-level contractor licensing board records, and IEA renewable energy auction results. Bottom-up project pipeline estimates triangulated against top-down software spend allocations across installer networks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled deployment architecture, end-user scale tier, feature complexity level, and regional regulatory framework cluster. CAGRs derived from installer workforce expansion rates, rooftop penetration trajectories, and software procurement intensity per project. Forecast inputs incorporated LiDAR data cost curves, hyperscaler pricing volatility bands, and net metering policy revision timelines.
Decision-makers should treat outputs as directional under stable interconnection standard implementation and continued Investment Tax Credit extension; material deviation in either would warrant model refresh. Specific risk factors include NEM policy reversals in additional states, hyperscaler rate spikes compressing SaaS margins, and generative AI acceleration displacing traditional simulation tiers. Recalibration cycles align with material shifts in federal incentive structures and state-level distributed generation regulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Data Recovery Software Market
Software & Services
Global Business Software and Service Market
Software & Services
Global Personalisation Software Market
Software & Services
Global HMI Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
User Retention Software Market
Software & Services
Artwork Management Software Market
Software & Services
Global Android Kiosk Software Market
Software & Services
Global Building Information Modeling (BIM) Software Market
Software & Services
Global Process Mining Software Market
Software & Services
Subscription Management Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Ad Creation Software Market
Software & Services
Global Cloud Testing Market
Software & Services
Global Survey Software Market