
 Data Conversion Services Market | 2026-2036
Data Conversion Services Market Size, Share, and Industry Trends Forecast 2026-2036
Data Conversion Services Market Analysis
Healthcare data migration is decoupling from traditional on-premise architectures as hospitals and insurers demand real-time interoperability. Informatica dominates enterprise-grade data integration with extensive connector libraries. Dell Boomi leverages its unified platform to anchor mid-market cloud migrations. Hevo Data specializes in no-code ETL pipelines that compete on deployment speed.
Data conversion services transform unstructured or legacy-formatted information into structured, machine-readable datasets through optical character recognition, schema mapping, and automated validation protocols. These services enable downstream analytics, regulatory reporting, and system interoperability across fragmented IT estates. Cloud-based delivery models are capturing the fastest expansion as organizations exit capital-intensive infrastructure. Document conversion services retain mature, high-margin positions in legal and government verticals where accuracy thresholds exceed 99.5%. Optical character recognition technology leads volume throughput but confronts margin pressure from open-source alternatives.
ISO 27001 certification requirements, HIPAA safeguards for protected health information, and GDPR cross-border data transfer rules collectively elevate compliance costs for service providers. The EU AI Act introduces additional documentation burdens for automated data processing pipelines. Stakeholders must monitor evolving data localization mandates and assess whether captive conversion centers or outsourced partnerships better mitigate jurisdictional exposure.
Market Dynamics
Healthcare data migration is decoupling from traditional on-premise architectures as hospitals and insurers demand real-time interoperability, forcing service providers to reengineer delivery models around cloud-native pipelines and API-first connectivity.
Growth Catalysts
- HIPAA safeguards:US healthcare providers face mandatory digitization timelines for protected health information, creating sustained demand for compliant conversion workflows.
- Cloud migration mandates:Enterprise IT departments are accelerating exit from capital-intensive infrastructure, prioritizing consumption-based data transformation services.
- Optical character recognition:Document-intensive verticals in India and Germany require high-throughput digitization for legacy paper archives.
Market Restraints
- Open-source OCR alternatives:Tesseract and comparable libraries compress margins on volume document conversion engagements.
- Data sovereignty requirements:GDPR cross-border transfer rules and emerging localization mandates fragment service delivery architectures.
- ISO 27001 certification costs:Compliance overhead for information security management systems disproportionately burdens mid-tier providers.
Strategic Opportunities
- EU AI Act documentation:Automated data processing pipelines face new algorithmic accountability requirements, creating advisory service attach rates.
- Real-time interoperability:HL7 FHIR standard adoption in US health systems opens conversion-to-integration bundled offerings.
- Captive conversion centers:Jurisdictional exposure mitigation drives hybrid outsourcing models in India and Germany.
Industry Challenges
- Schema mapping expertise:Shortage of engineers proficient in legacy database taxonomy translation extends project timelines.
- Validation protocol standardization:Absence of universal accuracy benchmarking above 99.5% thresholds complicates service-level agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Conversion Services Market |
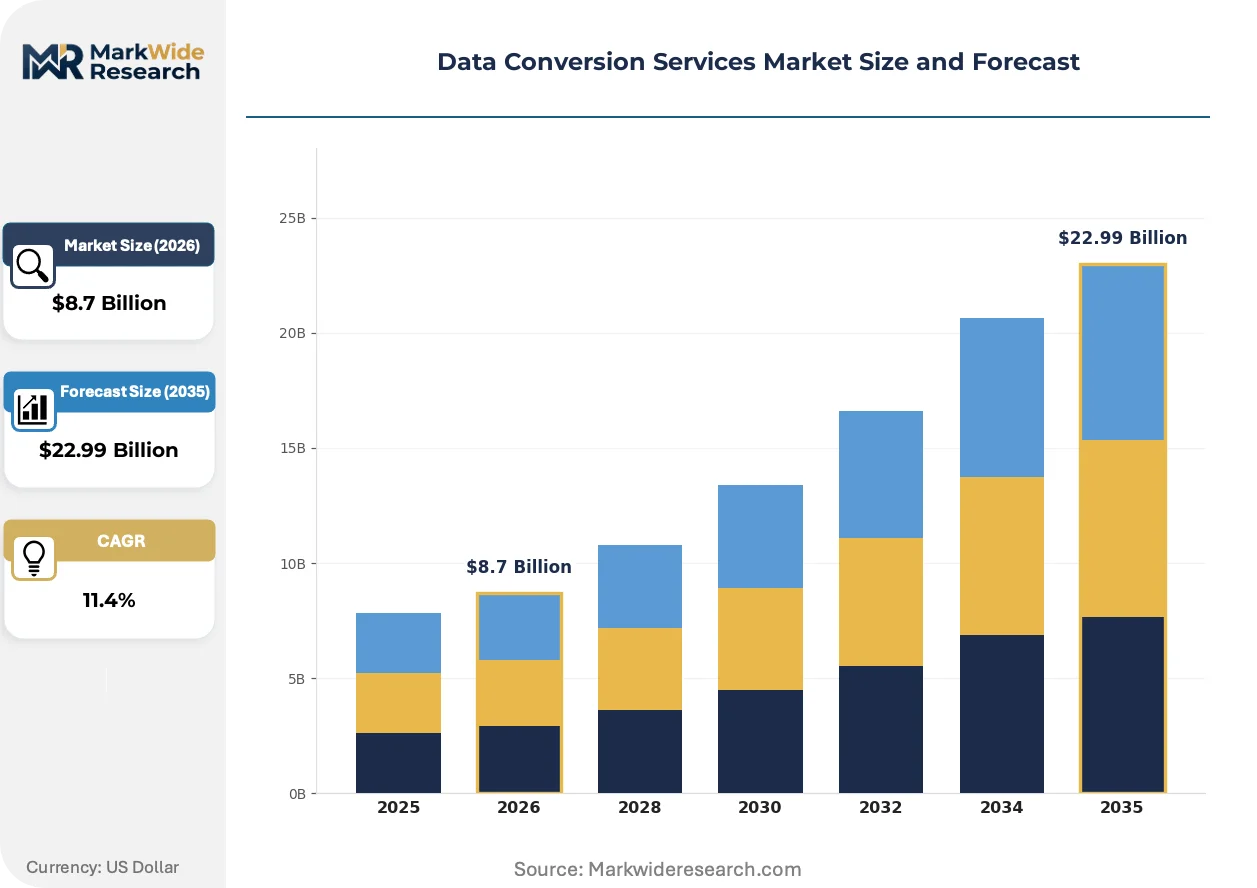
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Digital Data Conversion, XML Conversion, Document Conversion, Image Data Conversion Industry Vertical: Healthcare, Finance, Education, E-Commerce Technology: Optical Character Recognition, Data Entry Automation, Cloud-Based Solutions, Manual Data Processing Delivery Model: On-Premise, Cloud-Based, Hybrid, Outsourced |
| Companies Covered | Qlik Replicate, Dell Boomi, Informatica, Hevo Data, Airbyte, Talend (Qlik), Matillion, Rivery, Fivetran, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Conversion Services Market Emerging Trajectories
Artificial intelligence is embedding into conversion workflows, compressing manual review cycles while elevating accuracy thresholds. Service providers are racing to differentiate through specialized vertical expertise rather than generic throughput.
Intelligent document processing is integrating machine learning models for contextual field extraction beyond template-based OCR. Large hospital networks in the United States are deploying these systems for patient record backlogs. The technology is integrating directly into electronic health record platforms, collapsing standalone conversion project cycles.
GDPR's Article 44-49 transfer mechanisms are forcing EU-headquartered enterprises to reassess cloud conversion vendor selection criteria. Data localization clauses in processor agreements now dominate procurement negotiations. German automotive and industrial firms are prioritizing EU-sovereign infrastructure for sensitive design documentation transformation.
Subscription pricing for conversion capacity is displacing per-page or per-project contracting in mid-market segments. Managed service providers are bundling ongoing schema maintenance with initial migration work. This shift is most visible among US financial services firms modernizing legacy loan documentation systems.
Data Conversion Services Market Segmentation
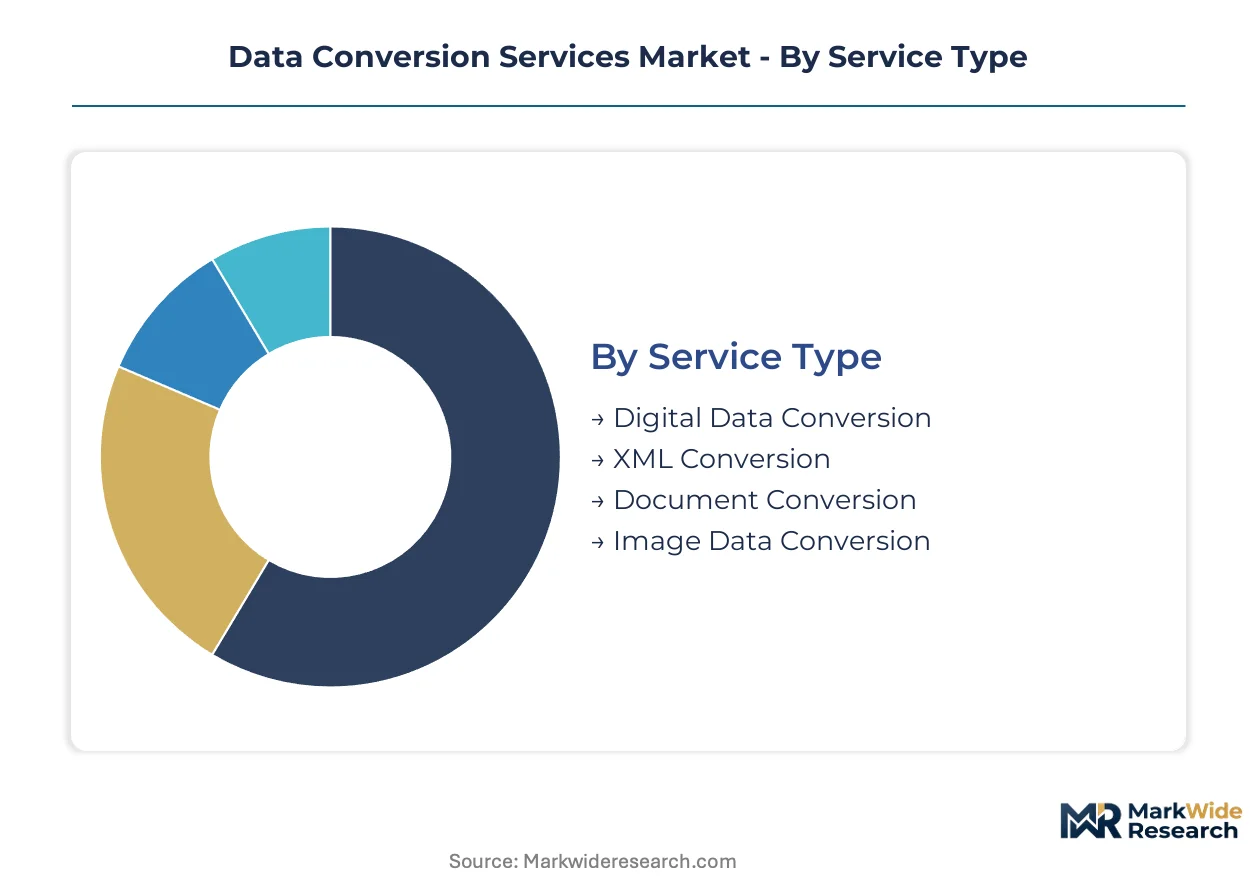
Data conversion services fragment across four structural axes that determine procurement criteria, margin profiles, and vendor selection. Service type dictates technical complexity and pricing models. Industry vertical shapes compliance requirements and accuracy thresholds. Technology choice separates capital-intensive automation from labor-dependent processing. Delivery model determines data sovereignty exposure and operational control.
Service Type:
Technical sophistication varies sharply across conversion methodologies, with machine-readable output formats commanding premium pricing over unstructured digitization.
- Digital Data Conversion:Transforms legacy database schemas and proprietary file formats into modern structured datasets. US healthcare providers deploy this for EHR interoperability mandates, where HL7 FHIR compliance drives specification requirements.
- XML Conversion:Normalizes semi-structured documents into extensible markup for system integration. German automotive suppliers demand this for design documentation exchange, facing tight validation protocols under EU data governance frameworks.
- Document Conversion:Converts static file formats (PDF, scanned images) into editable, searchable documents. Legal and government verticals in India sustain volume demand.
- Image Data Conversion:Processes raster graphics into vector formats or structured metadata. Retail catalog digitization and archival preservation drive niche adoption.
Mature deployment sits with Document Conversion. Newer deployment is concentrated in Digital Data Conversion.
Industry Vertical:
End-use concentration clusters where regulatory digitization deadlines and legacy system burdens intersect most severely.
- Healthcare:HIPAA-mandated protected health information digitization creates sustained demand for compliant workflows. US hospital networks are the primary demand anchor, with real-time interoperability requirements forcing cloud-native delivery models.
- Finance:Loan documentation modernization and regulatory reporting automation drive engagement. US financial services firms are shifting from per-project to subscription pricing for ongoing schema maintenance.
- Education:Student record digitization and credential verification systems sustain mid-market volume. Public university systems in India represent concentrated procurement.
- E-Commerce:Product catalog standardization and marketplace data feed optimization command smaller contract values but faster deployment cycles.
Healthcare anchors established revenue pools. E-Commerce is climbing the fastest as marketplace sellers automate listing workflows.
Technology:
Automation depth determines throughput economics, with AI-embedded solutions compressing manual review cycles while elevating capital requirements.
- Optical Character Recognition:Template-based character recognition dominates volume throughput but confronts margin pressure from open-source alternatives like Tesseract. Document-intensive verticals in Germany and India require high-throughput digitization for legacy paper archives.
- Data Entry Automation:Machine learning models extract contextual fields beyond template matching. Large US hospital networks deploy these for patient record backlogs, integrating directly into EHR platforms.
- Cloud-Based Solutions:Consumption-based transformation services enable enterprise exit from capital-intensive infrastructure. GDPR Article 44-49 transfer mechanisms force EU enterprises to reassess vendor selection criteria.
- Manual Data Processing:Human-in-the-loop validation sustains 99.5%+ accuracy thresholds for legal and government contracts where error tolerance approaches zero.
Manual Data Processing retains highest-margin legacy positions. Cloud-Based Solutions are gaining share fastest as IT departments accelerate infrastructure exit.
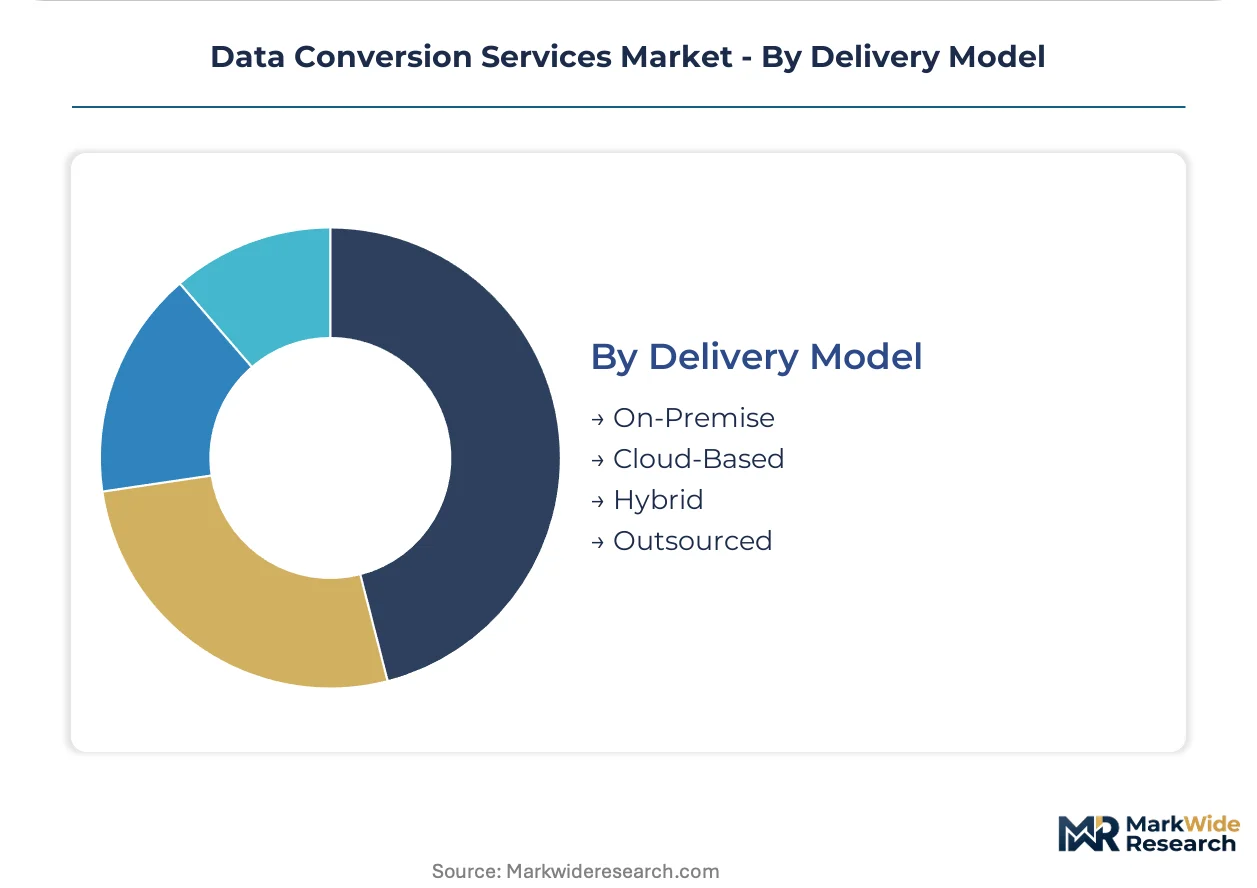
Delivery Model:
Control and risk allocation vary across deployment architectures, with data sovereignty requirements fragmenting service delivery geography.
- On-Premise:Licensed software deployed within client infrastructure. German industrial firms prioritize this for sensitive design documentation under strict data localization clauses.
- Cloud-Based:Fully managed SaaS delivery with consumption pricing. Mid-market segments across the United States are displacing per-page contracting with subscription models.
- Hybrid:Sensitive processing on-premise with burst capacity to cloud. EU-headquartered enterprises favor this architecture to satisfy GDPR processor agreement requirements.
- Outsourced:Third-party service providers manage conversion operations. India and Germany see rising captive conversion center construction to mitigate jurisdictional exposure.
Outsourced delivery holds established procurement share. Hybrid architectures show steepest expansion trajectory as compliance complexity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in India and free-trade corridors in Germany concentrate data conversion capacity as enterprises seek compliant infrastructure for sensitive digitization workloads.
United States
HIPAA-mandated protected health information digitization drives hospital network procurement in Texas and Florida health systems. The Department of Health and Human Services enforces interoperability deadlines through the 21st Century Cures Act. Boston's medical research corridor deploys cloud-native conversion pipelines for clinical trial data standardization.
Germany
Automotive suppliers in Baden-Württemberg demand high-precision design documentation transformation for cross-border engineering collaboration. GDPR Article 44-49 transfer mechanisms compel processor agreement renegotiations with cloud vendors. Munich's industrial cluster favors hybrid architectures to satisfy data localization clauses in sensitive manufacturing documentation.
India
Government digitization programs and insurance sector modernization sustain volume demand for document conversion in Maharashtra and Karnataka. The RBI mandates data localization for financial services customer records under its 2018 circular. Hyderabad's technology corridor hosts captive conversion centers serving European pharmaceutical compliance requirements.
United Kingdom
Financial services firms in the City of London accelerate legacy loan documentation modernization ahead of FCA operational resilience deadlines. The UK GDPR retains EU-equivalent cross-border transfer rules post-Brexit. Edinburgh's fintech cluster adopts subscription-based conversion models for ongoing schema maintenance.
Japan
Manufacturing conglomerates in the Chubu region digitize equipment maintenance archives for predictive analytics integration. METI's Society 5.0 initiative promotes data-driven infrastructure transformation across industrial verticals. Osaka's precision engineering cluster requires sub-99.5% error tolerance validation for quality documentation conversion.
Data Conversion Services Market Vendor Landscape
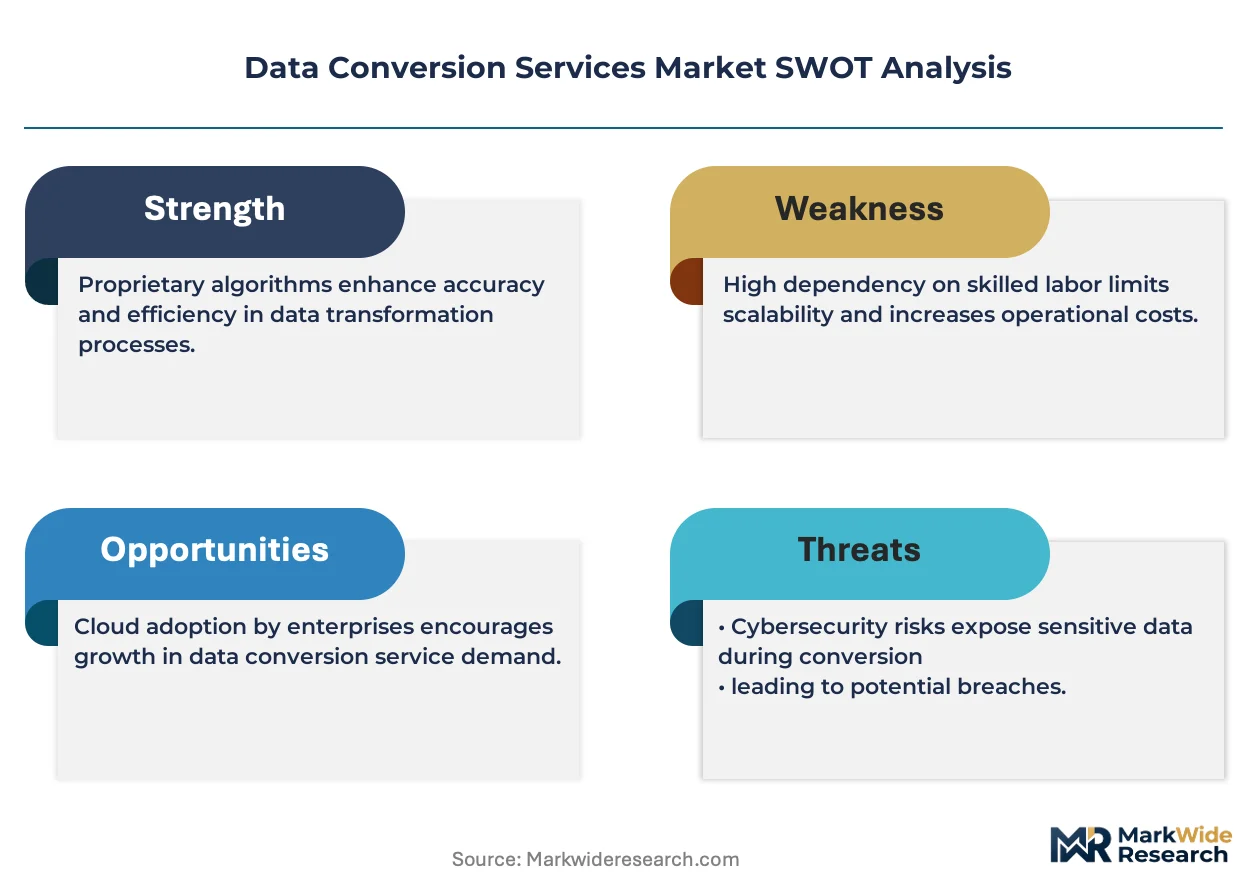
Top-tier vendors anchor enterprise-grade integration, while mid-market specialists compete on deployment velocity and vertical expertise. The vendor base organizes around three strategic tiers: legacy platform incumbents with extensive connector libraries, unified cloud-native platforms, and no-code ETL specialists. Consolidation pressure intensifies as enterprise procurement favors bundled conversion-to-integration offerings over point solutions. Dominant competitive moves include API-first architecture investments and vertical-specific compliance certifications.
Within the enterprise integration tier, Informatica and Dell Boomi occupy positions as archetypal platform incumbents, while Hevo Data exemplifies the no-code velocity specialist segment. Informatica represents legacy market presence through extensive schema mapping capabilities. Dell Boomi anchors mid-market cloud migration demand through unified platform positioning. Hevo Data sits within the deployment-speed competitive vector, competing on pipeline configuration timeframes rather than enterprise feature depth.
| Leading Market Players |
|---|
| Qlik Replicate |
| Dell Boomi |
| Informatica |
| Hevo Data |
| Airbyte |
| Talend (Qlik) |
| Matillion |
| Rivery |
| Fivetran |
| Others |
Supply Flow & Price Mechanics
ISO 27001 certification mandates gate qualified supply access for enterprise data conversion contracts, with certified providers commanding premium-tier pricing while uncertified competitors face exclusion from HIPAA and GDPR-regulated procurement pipelines in the United States, Germany, and India.
Pricing Analysis
Short lead-time premiums dominate pricing architecture for urgent healthcare digitization deadlines, while extended project timelines attract standard-tier discounts. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified providers from uncertified competitors and open-source-dependent operators. Cost compression in document conversion stems from Tesseract and comparable open-source OCR libraries eroding volume-based margins. Mid-market cloud migration buyers exhibit highest price sensitivity, whereas legal and government verticals with 99.5% accuracy thresholds demonstrate lowest sensitivity due to zero-error tolerance requirements.
Supply Chain Analysis
Freight costs for specialized OCR hardware and GPU-accelerated processing equipment concentrate supply dependencies across Taiwan, South Korea, and the United States. Raw material inputs draw from semiconductor fabrication capacity, high-resolution imaging sensors, and enterprise-grade storage infrastructure. Single-source vulnerability in GPU supply chains poses structural risk as cloud-native conversion demand accelerates. Distribution runs through direct vendor-to-enterprise SaaS platforms and systems integrator channels serving hospital networks and financial services firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data conversion services represent a consolidation play as open-source OCR alternatives and compliance certification costs force sub-scale providers toward acquisition or exit.
For Market Incumbents: Cement market position through backward integration into proprietary AI model training infrastructure and captive ISO 27001 certification programs. Dell Boomi and Informatica should expand API-first connector libraries to defend against no-code ETL specialists. Threat from Hevo Data and Airbyte on deployment velocity demands counterinvestment in pre-configured vertical templates for healthcare and finance. For New Entrants and Emerging Players: Launch via subscription-based SaaS delivery targeting mid-market US financial services firms shifting from per-project contracting. White-space opportunity concentrates in HL7 FHIR-compliant conversion-to-integration bundles for regional hospital networks. Go-to-market angle should emphasize sub-24-hour deployment timelines against incumbent implementation cycles. For Investors and Strategic Acquirers: EU AI Act enforcement actions against non-compliant automated processing pipelines are the leading indicator that regulatory technology and documentation advisory services will command premium attach rates. Long-term viability favors platforms with hybrid cloud-on-premise architectures satisfying GDPR Article 44-49 requirements. Acquisition target archetype: vertical specialists with healthcare or automotive compliance certifications and established API marketplaces.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | HL7 FHIR connectivity enables real-time hospital EHR interoperability in Texas and Florida health systems. |
| Vertical Compliance Certification | ISO 27001 and HIPAA dual certification unlocks US healthcare provider procurement pipelines. |
| Hybrid Cloud Architecture Deployment | GDPR Article 44-49 compliance captures German automotive and industrial firm demand. |
| Strategic Partnership with EHR Vendors | Epic and Cerner integration collapses standalone conversion project cycles for hospital networks. |
| Acquisition of No-Code ETL Specialist | Hevo Data deployment velocity capabilities compress mid-market customer acquisition timelines. |
Methodological Framework
Multi-period observation of HIPAA enforcement timelines, GDPR processor agreement renegotiations, and cloud migration capex disclosures anchored the trend analysis, supplemented by interviews with data integration architects, healthcare CIOs, compliance officers, and EHR platform engineers. Secondary validation drew from FDA 21st Century Cures Act guidance documents, EU AI Act draft implementations, SEC filings of publicly traded software vendors, and hospital procurement database extracts. Bottom-up service provider capacity estimates triangulated against top-down enterprise IT spending forecasts.
Segment-weighting across service type, industry vertical, technology choice, and delivery model dimensions structured the analytical framework across the projection horizon. CAGRs derived from weighted average of historical conversion project volumes and forward-looking cloud migration intent surveys. Industry-specific inputs included HL7 FHIR adoption curves in US health systems and RBI data localization compliance timelines for Indian financial services.
Regulatory enforcement delays, open-source OCR capability advances, and cloud vendor pricing volatility are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Quoting Software Market
Software & Services
Global Political Campaign Software Market
Software & Services
Content Marketing Software Market
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
Global Budgeting Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Australia HR Payroll Software Market
Software & Services
Global Custom Software Development Services Market
Software & Services
3D CAD Software Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Global Reference Check Software Market
Software & Services
Global Architecture Software Market
Software & Services
Construction Jobsite Management Software Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Global Church Management Software Market