
 Global Microscope Software Market | 2026-2036
Global Microscope Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microscope Software Market Foresight
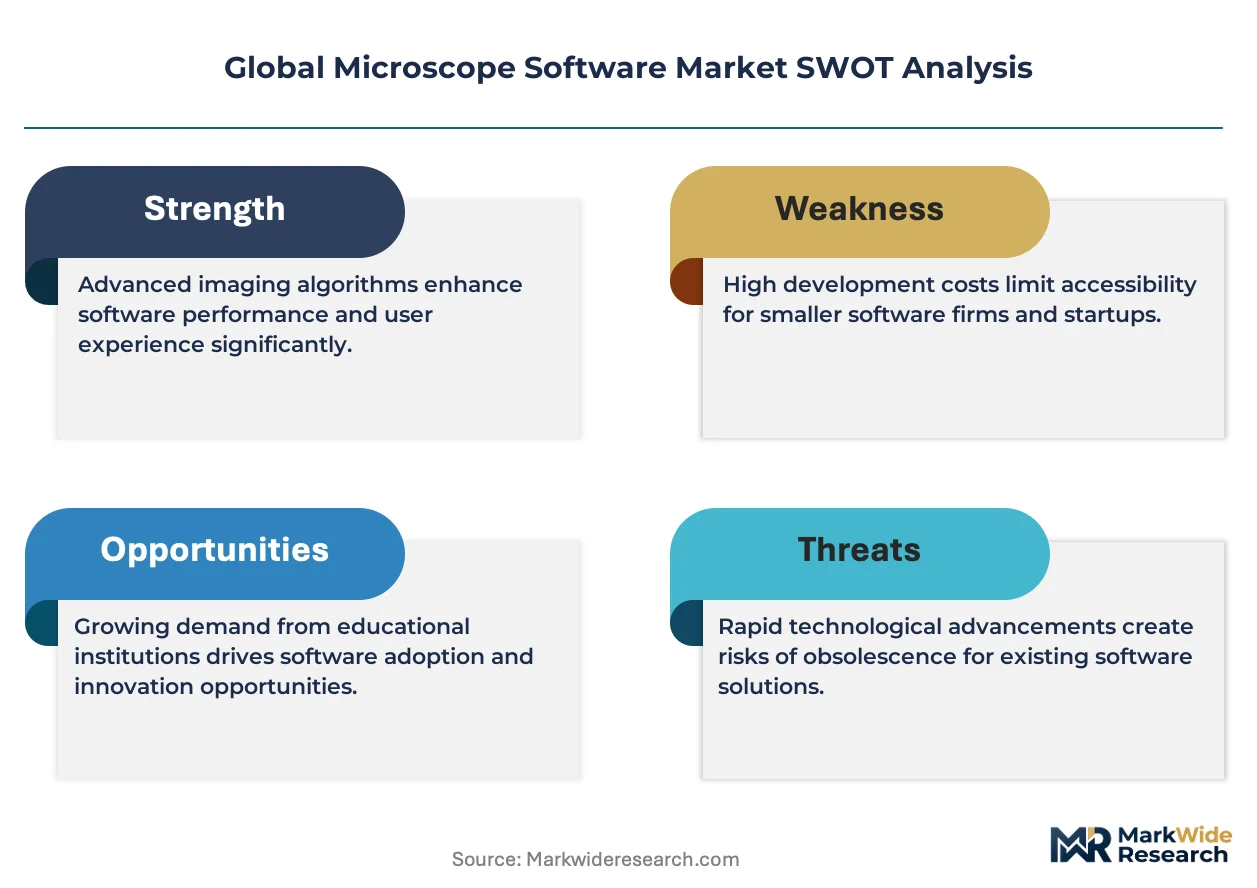
The gap between premium instrument-integrated suites and standalone commodity packages is repositioning vendor strategies across the microscopy value chain. Carl Zeiss AG leverages its embedded software ecosystem to sustain pricing power in high-end life sciences instrumentation. Nikon Corporation competes through specialized semiconductor inspection modules that anchor fab-level procurement decisions. Thermo Fisher Scientific Inc. extends its platform dominance by integrating cloud-based data visualization with its electron microscopy hardware.
Microscope software encompasses computational platforms that control optical and electron microscopes, capture multi-dimensional image data, and execute algorithmic analysis ranging from particle counting to neural-network-based defect classification. These systems process gigapixel-scale datasets through proprietary deconvolution kernels and GPU-accelerated rendering pipelines, serving quality control in electronics manufacturing and diagnostic pathology in clinical laboratories. Image analysis and digital pathology command the deepest margin pools where regulatory validation barriers protect incumbent positions, while cloud-based deployment gains traction among academic institutions seeking to amortize infrastructure costs across distributed research teams. Automation tools represent the fastest-expanding category as semiconductor manufacturers demand closed-loop metrology integration.
The FDA software-as-medical-device framework and the EU MDR digital pathology guidance create divergent compliance burdens that shape product roadmaps and market access timelines. ISO 13485 quality management standards and IEC 62304 software lifecycle requirements impose development discipline that favors established vendors with dedicated regulatory affairs functions. Stakeholders must monitor how NMPA software registration pathways in China and evolving HIPAA data governance in the United States reshape cloud deployment architectures and geographic data residency requirements.
Market Dynamics
The FDA software-as-medical-device framework and EU MDR digital pathology guidance are fragmenting compliance architectures, forcing vendors to maintain parallel development tracks and divergent validation protocols across regulatory jurisdictions.
Growth Catalysts
- AI-powered defect classification:Semiconductor fabs in Taiwan and South Korea are deploying neural-network-based metrology modules for closed-loop quality control, compressing inspection cycle times.
- FDA SaMD pathway:The United States regulatory clarity for software-as-medical-device is accelerating digital pathology platform commercialization in diagnostic laboratories.
- German precision optics clusters:Concentrated R&D infrastructure around Jena and Wetzlar is sustaining specialized talent pipelines for high-end instrument development.
Market Restraints
- GPU supply concentration:Taiwan Semiconductor Manufacturing dominates advanced node fabrication for AI acceleration hardware, creating single-source vulnerability for deconvolution rendering pipelines.
- IEC 62304 compliance burden:Lifecycle documentation requirements impose 18-24 month development timelines that exclude smaller software vendors from regulated clinical segments.
- Open-source image analysis libraries:CellProfiler and ImageJ ecosystems are commoditizing basic particle counting and segmentation functions, pressuring standalone package pricing.
Strategic Opportunities
- India's diagnostic laboratory expansion:The country's PLI scheme for medical devices is attracting cloud-based pathology platform deployments to amortize infrastructure across distributed hospital networks.
- Quantum dot labeling convergence:Integration of fluorescent nanoparticle chemistry with spectral unmixing algorithms is opening multiplexed biomarker quantification in immuno-oncology workflows.
- Subscription licensing models:Academic consortia in the Netherlands and Denmark are piloting shared-seat arrangements that lower per-laboratory entry costs for advanced analysis suites.
Industry Challenges
- Computational microscopy skill scarcity:The intersection of optical physics, machine learning engineering, and regulatory documentation expertise remains concentrated among senior developers at established vendors.
- Legacy LIS integration complexity:Hospital information systems built on HL7 v2 protocols require costly middleware development for seamless digital pathology workflow embedding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microscope Software Market |
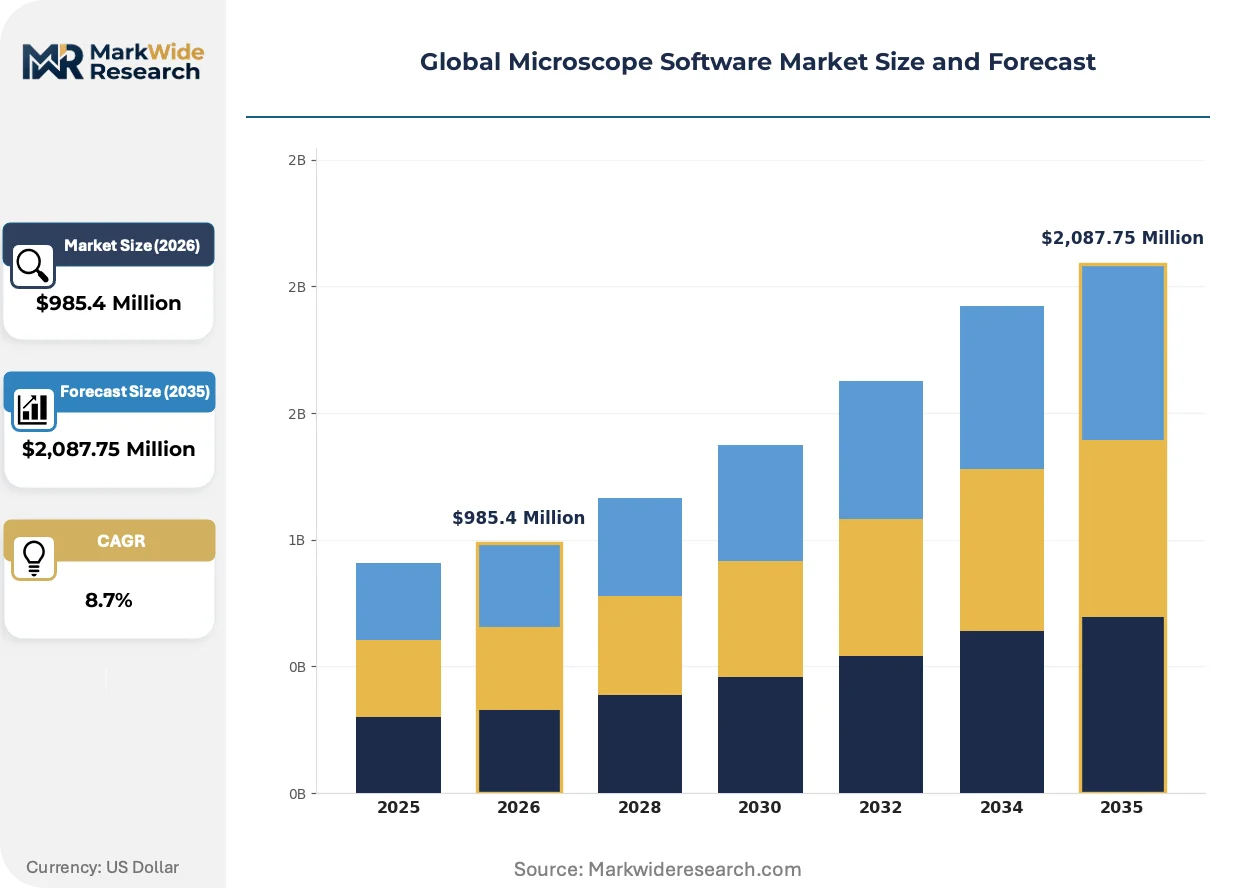
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $2,087.75 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Image Analysis, 3D Reconstruction, Digital Pathology, Data Visualization, Automation Tools Deployment Mode: Cloud-Based, On-Premises, Hybrid, Web-Based Application: Life Sciences, Material Science, Semiconductor Inspection, Forensic Analysis, Educational Research End User Industry: Pharmaceutical Labs, Academic Institutions, Electronics Manufacturers, Research Institutes |
| Companies Covered | Carl Zeiss AG, Leica Microsystems, Nikon Corporation, Thermo Fisher Scientific Inc., Olympus Corporation, Oxford Instruments plc, Basler AG, JEOL Ltd., Gatan, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microscope Software Market Shifts & Advancements
Deep learning architectures are compressing the trade-off between acquisition speed and image fidelity, while regulatory frameworks fragment across jurisdictions and procurement models pivot toward operational expenditure structures.
GPU-accelerated deconvolution is overtaking CPU-bound iterative algorithms as the default reconstruction method for live-cell super-resolution microscopy. Pharmaceutical screening facilities in Massachusetts and California are adopting real-time processing pipelines that eliminate overnight batch reconstruction delays. This hardware shift is compressing time-to-insight metrics from hours to minutes, repositioning instrument purchasing criteria toward NVIDIA CUDA ecosystem compatibility.
EU MDR digital pathology guidance is mandating clinical validation studies that parallel pharmaceutical trial rigor for primary diagnostic use. The regulation requires prospective reader studies with pathologist panels across multiple clinical sites, adding substantial cost and timeline risk to product launches. In-vitro diagnostic software vendors are responding by pre-submission engagement with notified bodies in Germany and the Netherlands to de-risk certification pathways.
Research consortia are consolidating procurement through shared cloud tenancy arrangements that distribute GPU cluster costs across institutional boundaries. The European Molecular Biology Laboratory and affiliated nodes are negotiating enterprise licenses that pool analysis credits across distributed teams, displacing perpetual seat licenses at individual laboratories. This model is most advanced in Nordic countries where national research infrastructure funding enables centralized service contracting.
Global Microscope Software Market Segmentation
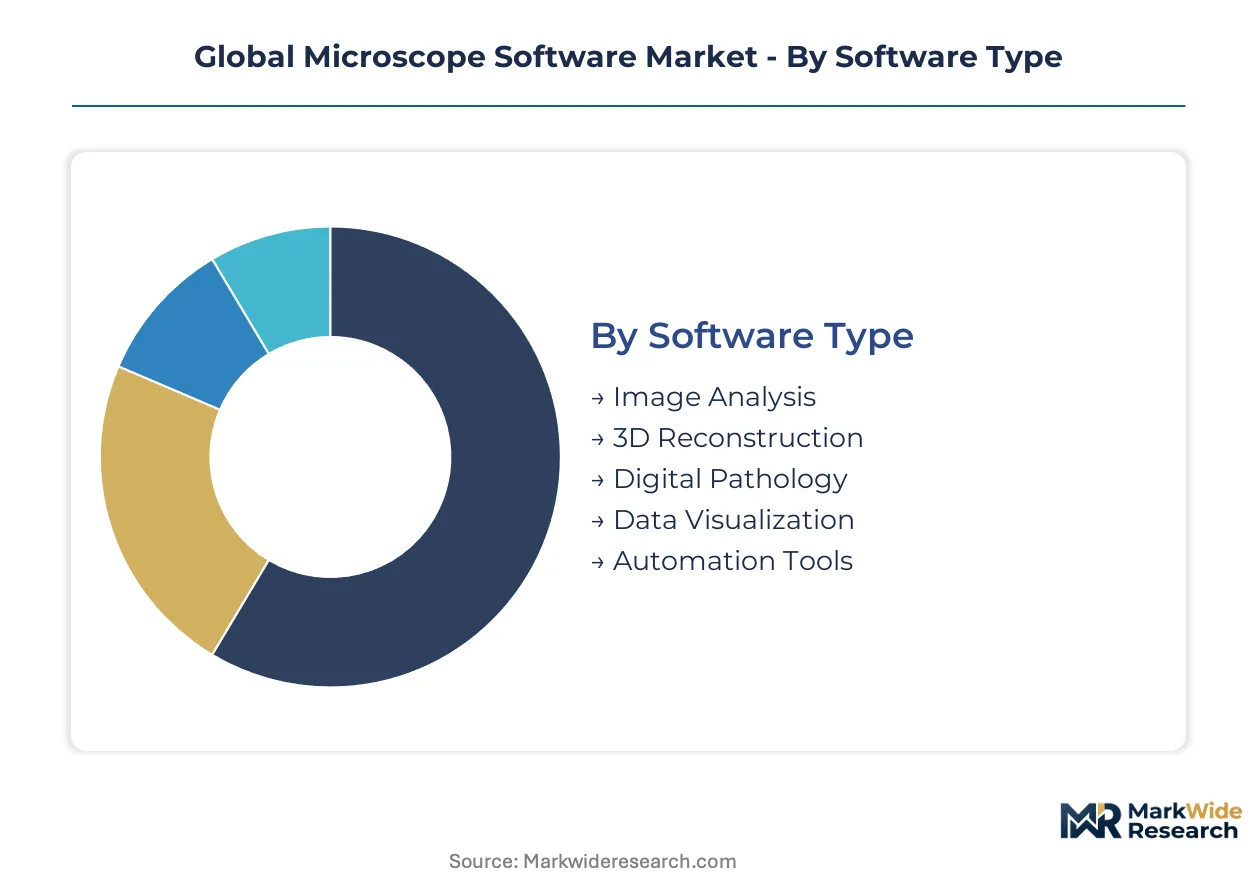
Microscope software segmentation reveals divergent purchasing logics across buyer archetypes. Pharmaceutical procurement teams prioritize regulatory validation and workflow integration, while academic consortia optimize for cost amortization and multi-site accessibility.
Software Type:
Buyers in this category separate by margin sensitivity and regulatory exposure rather than feature breadth alone.
- Image Analysis:Algorithmic platforms execute particle counting, morphometry, and fluorescence quantification through proprietary deconvolution kernels. Demand concentrates in pharmaceutical screening facilities in Massachusetts and Basel, where FDA 21 CFR Part 11 compliance requirements filter vendor selection toward established suites with validated audit trails.
- Digital Pathology:Whole-slide imaging platforms with AI-assisted diagnostic support function as software-as-medical-device under FDA and EU MDR frameworks. German university hospitals in Heidelberg and Berlin anchor deployment volumes, driven by pathology workforce shortages and reimbursement pressure for faster case turnaround.
- 3D Reconstruction:Volumetric rendering engines process electron tomography and light-sheet microscopy datasets through GPU-accelerated pipelines. Materials science departments at ETH Zurich and MIT represent core demand clusters for subsurface defect visualization.
- Data Visualization:Cloud-native dashboards aggregate multi-instrument datasets for distributed research teams. Nordic academic consortia pilot shared-tenant arrangements to distribute infrastructure costs.
- Automation Tools:Closed-loop metrology modules integrate directly with semiconductor fabrication equipment. Taiwan and South Korean fabs drive procurement for neural-network-based defect classification with sub-second cycle times.
Volume sits with Image Analysis; growth tilts toward Digital Pathology.
Deployment Mode:
IT governance maturity and data sovereignty requirements partition buyers across architecture preferences.
- Cloud-Based:Multi-tenant platforms with elastic GPU provisioning enable pay-per-analysis consumption models. India's diagnostic laboratory expansion under the PLI scheme attracts cloud pathology deployments to amortize infrastructure across distributed hospital networks in Mumbai and Bangalore.
- On-Premises:Air-gapped installations with local compute clusters serve semiconductor fabs and defense-adjacent research where export control and intellectual property protection override cost considerations. Samsung and TSMC facilities in Suwon and Hsinchu mandate on-site data retention for process technology security.
- Hybrid:Split architectures process sensitive acquisition data locally while pushing anonymized analytics to cloud inference endpoints. German mid-sized pharmaceutical CROs favor this model to satisfy Bundesdatenschutzgesetz requirements while accessing scalable AI model updates.
- Web-Based:Browser-accessible platforms with minimal local installation reduce IT support burdens for undergraduate teaching laboratories. British and Australian universities deploy these for remote microscopy instruction.
Procurement currently favors On-Premises in regulated segments; Hybrid architectures are gaining share fastest among mid-market life sciences organizations.
Application:
End-use technical requirements create distinct performance thresholds and validation burdens.
- Semiconductor Inspection:Sub-nanometer resolution metrology with closed-loop feedback to fabrication equipment demands real-time processing throughput. Taiwan's foundry ecosystem anchors volume, with South Korean memory manufacturers driving next-generation EUV mask defect detection requirements.
- Life Sciences:Live-cell imaging with phototoxicity minimization and multi-position stage control serves drug discovery workflows. Cambridge and San Francisco biotech clusters concentrate demand for super-resolution compatibility.
- Material Science:Crystallographic analysis and correlative microscopy link structure to mechanical properties. German automotive suppliers and Japanese steelmakers deploy these for failure analysis.
- Forensic Analysis:Ballistics matching and document examination require chain-of-custody documentation and courtroom-admissible image authentication. FBI and state crime laboratories in the United States standardize procurement specifications.
- Educational Research:Cost-optimized packages with simplified acquisition interfaces dominate undergraduate instruction. Indian and Brazilian public university systems represent volume buyers with severe budget constraints.
Revenue concentrates in Semiconductor Inspection; steepest expansion trajectory belongs to Life Sciences as AI-powered phenotypic screening matures.
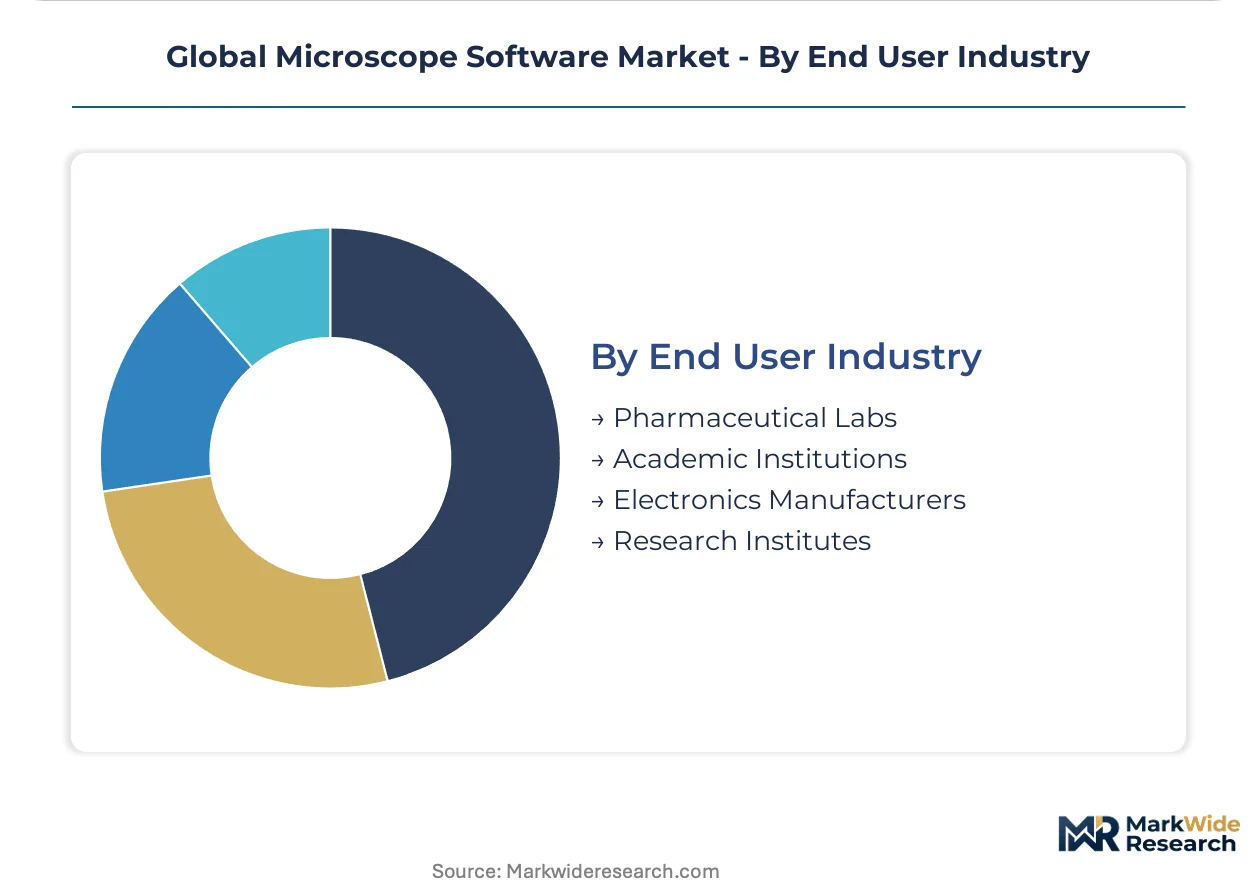
End User Industry:
Buying center composition and procurement cycle length differentiate industry verticals.
- Pharmaceutical Labs:Centralized IT and regulatory affairs functions drive enterprise licensing with mandatory IQ/OQ/PQ validation protocols. Roche and Novartis facilities in Basel standardize on platforms with pre-validated GxP modules.
- Electronics Manufacturers:Equipment engineering teams with fab-level procurement authority prioritize metrology throughput and equipment matching over software margins. Intel and Samsung maintain captive software development for proprietary inspection algorithms.
- Academic Institutions:Distributed principal-investigator purchasing with soft-money funding cycles favors subscription and shared-tenancy models. Max Planck Society and Howard Hughes Medical Institute negotiate enterprise terms across distributed nodes.
- Research Institutes:National laboratory procurement with government funding compliance emphasizes open architecture and data portability. CERN and Brookhaven National Laboratory mandate non-proprietary file formats for long-term data stewardship.
Spending scale sits with Pharmaceutical Labs; subscription conversion is climbing fastest in Academic Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jena and Wetzlar in Germany concentrate precision optics R&D infrastructure that feeds specialized talent pipelines into high-end instrument development. The FDA software-as-medical-device framework in the United States and EU MDR digital pathology guidance create divergent compliance burdens that reshape product roadmaps across jurisdictions.
United States
FDA's software-as-medical-device pathway accelerates digital pathology platform commercialization in diagnostic laboratories. HIPAA data governance requirements reshape cloud deployment architectures and geographic data residency specifications. Massachusetts and California pharmaceutical screening facilities anchor demand for real-time GPU-accelerated processing pipelines.
Germany
EU MDR digital pathology guidance mandates clinical validation studies with prospective reader panels across multiple sites. ISO 13485 quality management standards and IEC 62304 software lifecycle requirements impose development discipline favoring established vendors. Heidelberg and Berlin university hospitals drive whole-slide imaging deployment volumes amid pathology workforce shortages.
China
NMPA software registration pathways govern cloud deployment architectures for diagnostic platforms entering the market. The country's diagnostic laboratory expansion attracts infrastructure investment for distributed hospital networks. Shanghai and Beijing research institutes concentrate demand for multi-dimensional image data capture systems.
India
PLI scheme for medical devices attracts cloud-based pathology platform deployments to amortize infrastructure across hospital networks. CDSCO regulatory frameworks shape validation protocols for software entering clinical use. Mumbai and Bangalore diagnostic laboratory networks represent volume buyers for cost-optimized analysis suites.
South Korea
MFDS medical device regulations establish compliance requirements for AI-assisted diagnostic software commercialization. Samsung semiconductor fabs in Suwon mandate on-premises data retention for process technology security. Memory manufacturers drive next-generation EUV mask defect detection requirements with sub-second cycle time specifications.
Global Microscope Software Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the microscopy software value chain. The market structure tilts toward consolidation at the premium instrument-integrated tier while fragmentation persists in standalone commodity packages. Three archetypes dominate: embedded ecosystem vendors leveraging hardware-software integration, specialized module developers anchoring fab-level procurement decisions, and platform extenders integrating cloud visualization with existing instrumentation. M&A activity concentrates on regulatory capability acquisition, while strategic partnerships target GPU acceleration hardware alignment.
Among German precision optics specialists, Carl Zeiss AG and Leica Microsystems occupy positions within the embedded ecosystem archetype, leveraging captive hardware platforms to sustain pricing power. Nikon Corporation exemplifies the specialized module approach, anchoring semiconductor inspection procurement decisions through dedicated metrology development. Thermo Fisher Scientific Inc. represents the platform extension strategy, integrating cloud-based data visualization with electron microscopy hardware to deepen enterprise relationships.
| Leading Market Players |
|---|
| Carl Zeiss AG |
| Leica Microsystems |
| Nikon Corporation |
| Thermo Fisher Scientific Inc. |
| Olympus Corporation |
| Oxford Instruments plc |
| Basler AG |
| JEOL Ltd. |
| Gatan, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up software specialists have consolidated fragmented image analysis toolchains into unified platforms, tightening pricing discipline while squeezing GPU hardware margins through volume procurement leverage. This ownership pattern concentrates supply negotiation power among three to four platform vendors, enabling subscription pricing escalation in regulated clinical segments while commoditizing standalone analysis modules.
Pricing Analysis
Outcome-based pricing tied to diagnostic throughput anchors premium digital pathology contracts, with FDA-validated suites commanding three to five times standard licensing fees over unvalidated alternatives. Price differentiation hinges on IEC 62304 certification tier and GxP audit trail completeness, with pharmaceutical procurement teams in Basel and Massachusetts showing lowest price sensitivity. Cost compression in academic site licensing intensifies as open-source CellProfiler ecosystems displace entry-level particle counting functions. Subscription conversion rates run highest among Nordic research consortia seeking elastic GPU provisioning without capital commitment.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for medical devices are reshaping sourcing architectures, requiring local data residency infrastructure for cloud pathology platforms entering Mumbai and Bangalore hospital networks. GPU acceleration hardware concentrates in Taiwan and South Korea, with NVIDIA CUDA ecosystem compatibility tethering deconvolution rendering pipelines to TSMC advanced node fabrication. Optical component supply draws from German precision clusters in Jena and Wetzlar, while sensor arrays source from Japanese CMOS foundries. Single-source vulnerability in AI acceleration silicon creates tariff exposure risk as export control regimes tighten. Distribution runs through direct enterprise sales for semiconductor fabs and GPO-negotiated frameworks for hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microscope software market reads as a cost-of-compliance story where IEC 62304 lifecycle documentation requirements impose eighteen-to-twenty-four-month development timelines, erecting barrier-to-entry moats that protect established vendors with dedicated regulatory affairs functions.
For Market Incumbents: Deploy regulatory capability acquisition as the primary consolidation lever, targeting notified-body relationships in Germany and the Netherlands to de-risk EU MDR certification pathways. Vertical integration into GPU-optimized rendering kernels defends margin position against cloud-native challengers. Pre-submission engagement with FDA software-as-medical-device pathways accelerates digital pathology platform launches before mid-market competitors achieve validation readiness.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in whole-slide imaging creates entry space for web-based teaching laboratory platforms with minimal local installation overhead. British and Australian undergraduate microscopy instruction represents the most penetrable segment, with remote-access browser deployment as the go-to-market angle. India's PLI-attracted diagnostic laboratory expansion offers white-space targeting for cost-optimized analysis suites amortized across distributed hospital networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regulatory-capability-light specialists in Nordic academic consortia facing subscription renewal pressure. Long-term viability over the next decade hinges on AI-assisted diagnostic software achieving primary diagnostic reimbursement codes. Watch FDA SaMD clearance velocity as the inflection indicator distinguishing platform consolidation winners from stranded tooling investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Capability Acquisition | Notified-body relationships in Germany compress EU MDR certification timelines for digital pathology platforms. |
| GPU-Optimized Kernel Development | CUDA ecosystem compatibility anchors pharmaceutical screening facility procurement in Massachusetts and California. |
| Cloud-Native Platform Launch | Multi-tenant architectures with elastic provisioning penetrate India's PLI-supported diagnostic laboratory networks. |
| Academic Consortium Licensing | Shared-seat subscription models displace perpetual licenses across Max Planck Society and Howard Hughes Medical Institute nodes. |
| Hybrid Deployment Architecture | Split local-cloud processing satisfies Bundesdatenschutzgesetz requirements while enabling scalable AI model updates for German CROs. |
Research Methodology
Document review covered SEC 10-K filings, FDA 510(k) and De Novo submission databases, EU MDR notified-body guidance documents, and hyperscaler capex disclosures, complemented by interviews with digital pathology platform product managers, semiconductor fab metrology engineers, hospital biomedical informatics officers, and research institute procurement directors. Secondary validation drew from ISO 13485 certification registries, GPO contract databases, and academic consortium licensing agreements. Bottom-up instrument shipment modeling and top-down enterprise software spending analysis provided cross-referencing triangulation.
Historical validation against panel input from regulatory affairs specialists and IT procurement officers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user industry vertical, regulatory compliance tier, and regional adoption pattern. CAGRs were derived from weighted scenario analysis incorporating GPU supply elasticity, pathology workforce shortage severity, and reimbursement code expansion trajectories. Forecast inputs included semiconductor fab capital expenditure cycles and pharmaceutical screening facility automation investment schedules.
Inputs from FDA pre-submission meeting minutes and EU notified-body consultation records were available through the study window; gaps in NMPA software registration pathway transparency introduce uncertainty bands around China market penetration assumptions. Forecasts reflect documented assumptions regarding cloud data sovereignty enforcement and AI diagnostic software reimbursement policy evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Automotive Digital Retailing Software Market
Software & Services
Content Curation Software Market
Software & Services
UK Applicant Tracking System Market
Software & Services
Global Qualitative Data Analysis Software Market
Software & Services
Lead Management Software Market
Software & Services
Customer Advocacy Software Market
Software & Services
Global Local SEO Software Market
Software & Services
Admission Management Software Market
Software & Services
Global Political Campaign Software Market
Software & Services
Specification Management Software Market
Software & Services
Global Managed Application Services Market
Software & Services
Global Continuous Integration Tools Market
Software & Services
Europe Digital Signage Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Agile Application Life-Cycle Management Market
Software & Services
Global Remote Desktop Management Market