
 Quiet Commerce Market | 2026-2036
Quiet Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Quiet Commerce Market Insights
A capital-intensity divergence between cloud infrastructure operators and edge hardware vendors is bifurcating competitive dynamics in quiet commerce. Amazon leverages its serverless architecture to sustain low-latency voice processing at checkout terminals. Alibaba anchors its position through proprietary biometric sensors that integrate with domestic mobile wallet standards. JD.com differentiates by controlling last-mile fulfillment data that feeds predictive inventory algorithms for silent replenishment.
Quiet commerce encompasses frictionless transaction systems that eliminate traditional point-of-sale interaction through NFC field ranges under 4 centimeters, tokenized credential exchange, and ambient authentication protocols. These systems process payments, identity verification, and inventory debits without explicit consumer action, serving retail environments where speed and invisibility enhance throughput. Contactless payments and biometric authentication currently occupy the deepest margin pools due to interchange fee structures and hardware subscription models, while voice commerce registers the fastest expansion as natural language processing latency drops below 300 milliseconds. Edge computing deployments are gaining share in food delivery and transportation booking where cellular dead zones demand localized transaction completion.
EU GDPR and the EU AI Act constrain biometric data retention periods and mandate algorithmic transparency for authentication systems, directly elevating compliance costs for hospitality chains and entertainment services deploying facial recognition. The US FTC and state-level biometric privacy statutes in Illinois and Texas create a fragmented compliance map that disadvantages smaller ecommerce platforms lacking dedicated legal infrastructure. Stakeholders must decide whether to absorb regulatory complexity in-house or cede market access to compliance-native infrastructure providers.
Market Dynamics
Edge computing architectures are redistributing transaction processing from centralized cloud nodes to localized hardware, compressing authentication latency below perceptible thresholds and enabling true ambient commerce without consumer-directed action.
Growth Catalysts
- EU AI Act compliance mandates:Facial recognition deployment in French and German hospitality sectors now requires algorithmic transparency documentation, accelerating demand for privacy-preserving biometric alternatives that process data locally without cloud retention.
- Super-app ecosystem integration:China's urban payment rails now embed voice commerce modules within existing mobile wallet interfaces, eliminating separate app downloads and collapsing consumer onboarding friction to near-zero.
- NFC field range compression:Sub-4-centimeter proximity protocols are eliminating accidental transaction triggers in dense retail environments, expanding merchant willingness to deploy silent checkout across high-throughput grocery and convenience formats.
Market Restraints
- Biometric sensor supply concentration:Proprietary hardware manufacturing clusters in East Asian foundries create single-source vulnerability for European and North American terminal vendors seeking GDPR-compliant facial recognition modules.
- Illinois BIPA and Texas biometric statutes:Fragmented US state-level privacy litigation exposure elevates insurance and legal infrastructure costs for multi-state retailers, compressing margins on authentication-as-a-service offerings.
- Tokenized credential interoperability gaps:Competing standards between domestic mobile wallet protocols prevent seamless cross-border silent transactions, fragmenting addressable market scope for unified platform providers.
Strategic Opportunities
- India's UPI silent payment rails:The National Payments Corporation of India's voice-enabled transaction infrastructure remains underpenetrated in tier-2 and tier-3 urban centers, offering first-mover positioning for localized biometric authentication vendors.
- Transportation and food delivery dead zones:Cellular coverage gaps in underground transit systems and remote logistics corridors create demand for edge-completed transactions that bypass cloud dependency entirely.
- CSRD sustainability disclosure alignment:European merchants can leverage carbon-footprint reduction from eliminated paper receipts and reduced checkout queue energy consumption to meet corporate sustainability reporting requirements.
Industry Challenges
- Edge-to-cloud security architecture integration:Retailers must maintain cryptographic continuity across distributed processing nodes without creating vulnerability seams that breach PCI-DSS tokenization standards.
- Natural language processing latency engineering:Sub-300-millisecond voice response thresholds require specialized acoustic modeling talent scarce outside major technology hubs, constraining vendor scaling velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quiet Commerce Market |
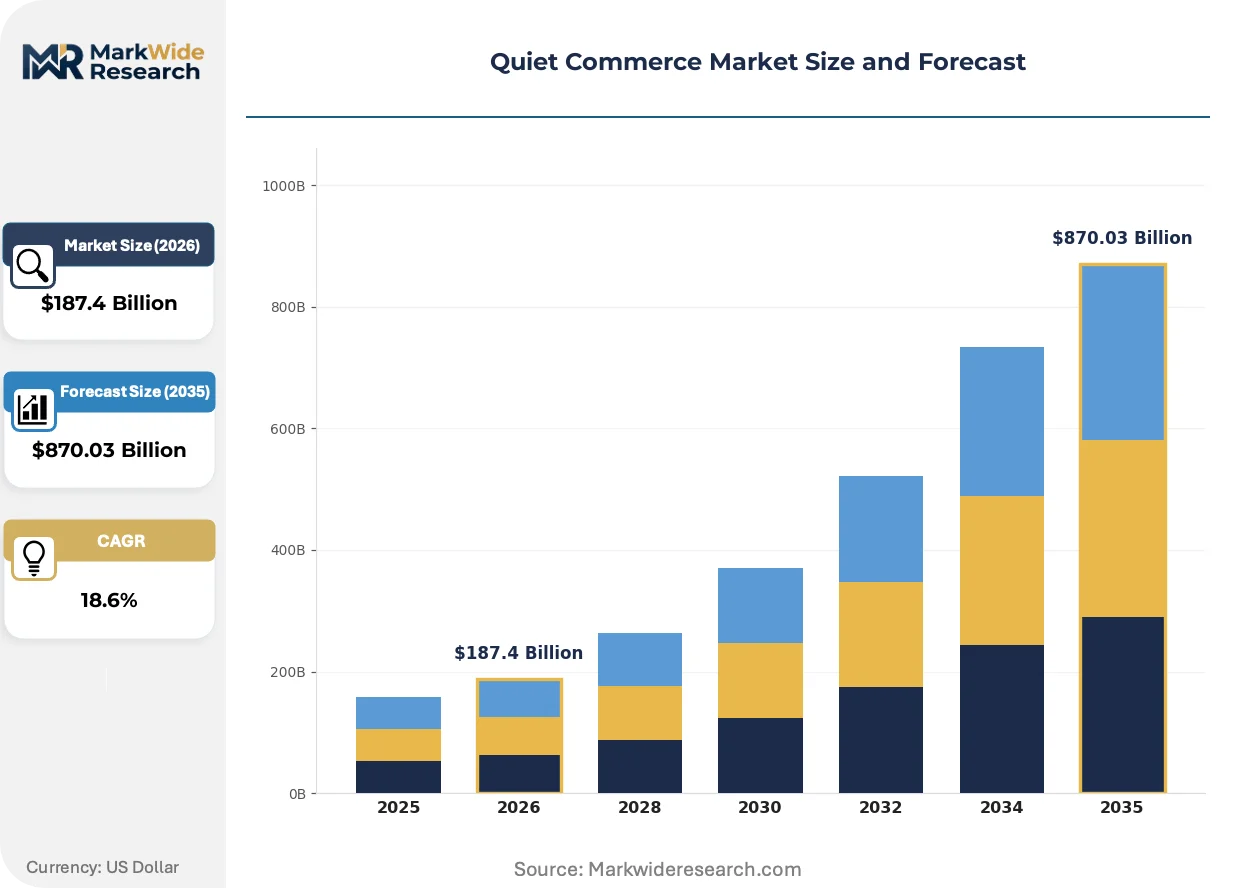
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $870.03 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Contactless Payments, Mobile Wallets, Voice Commerce, Near Field Communication, Biometric Authentication Application: Retail Checkout, E-Grocery, Food Delivery, Transportation Booking, Event Ticketing End User Industry: Ecommerce Platforms, Financial Institutions, Hospitality Chains, Transportation Providers, Entertainment Services Deployment Model: Cloud-Based, On-Premise, Hybrid, Edge Computing |
| Companies Covered | Amazon, Alibaba Group, Shopify, Walmart, eBay, JD.com, Mercado Libre, Rakuten, Sea Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quiet Commerce Market Trends and Innovations
Ambient authentication protocols are dissolving the visible boundary between consumer intention and transaction execution, rendering traditional point-of-sale hardware obsolete in favor of invisible infrastructure embedded within physical environments.
On-device neural processing units are displacing cloud-dependent voice recognition in retail terminals. Grocery chains in Japan and South Korea now deploy localized acoustic models that complete intent parsing without data transmission, eliminating network latency and GDPR retention risks while compressing authentication cycles to under 200 milliseconds. This displacement of centralized AI inference is fragmenting vendor power toward semiconductor designers with edge-optimized architectures.
The EU AI Act's risk-classification framework for biometric systems is compelling algorithmic audit investments from hospitality and entertainment deployers. Facial recognition installations in French stadiums and German hotels now require conformity assessment documentation that adds 12-18 months to procurement cycles, favoring established compliance infrastructure providers over emerging hardware vendors.
Silent replenishment procurement is compressing inventory decision cycles from days to minutes. JD.com's fulfillment data integration enables predictive restocking triggers based on consumption velocity patterns rather than periodic manual review, displacing traditional ERP-driven reorder point systems in China's urban convenience retail. This behavioral shift is most visible in Shanghai and Beijing where super-app wallet penetration exceeds 90 percent.
Quiet Commerce Market Segmentation
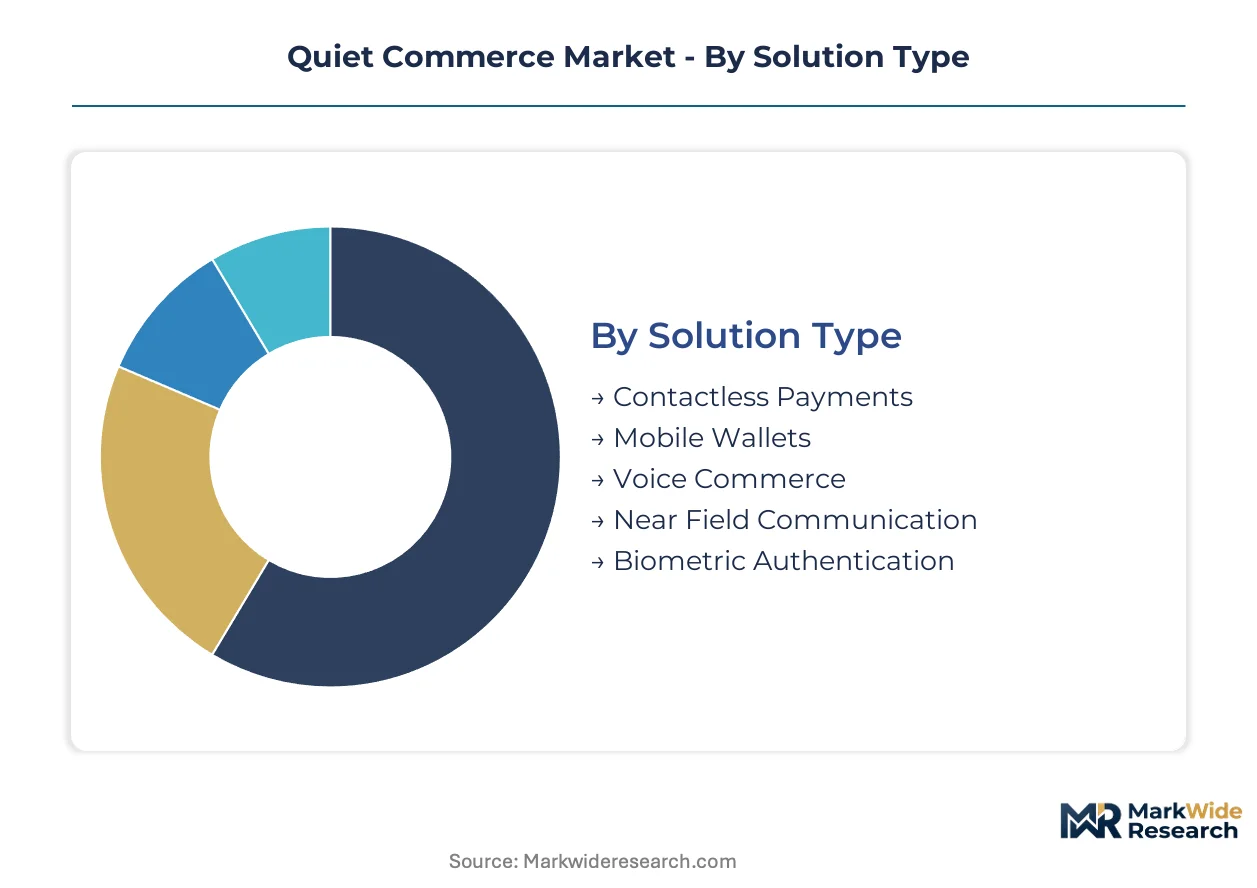
Quiet commerce segmentation reveals how transaction friction elimination varies across technical architectures and use contexts. Solution types determine latency thresholds and biometric exposure. Application contexts dictate whether ambient authentication or directed consumer action proves optimal.
Solution Type:
Contactless payments and mobile wallets face intensifying substitution pressure from voice commerce and ambient biometric protocols that eliminate even tap-based interaction.
- Contactless Payments:NFC field protocols under 4 centimeters process tokenized credentials through proximity detection without app launch. Grocery chains in France and Germany deploy these for high-throughput checkout lanes where queue compression drives merchant preference.
- Mobile Wallets:Super-app embedded payment rails consolidate identity, loyalty, and transaction authorization within single interfaces. China's urban centers concentrate demand where wallet penetration exceeds 90 percent and voice modules collapse onboarding friction.
- Voice Commerce:Natural language processing below 300 milliseconds latency enables hands-free transaction intent parsing. Edge-completed acoustic models in Japan and South Korea eliminate cloud transmission and GDPR retention exposure.
- Near Field Communication:Sub-4-centimeter proximity standards prevent accidental triggers in dense retail environments. Merchant willingness expands in high-frequency convenience formats.
- Biometric Authentication:Facial recognition and fingerprint protocols process identity verification without credential presentation. EU AI Act compliance costs elevate procurement cycles for hospitality deployers.
Contactless payments anchor the volume base while voice commerce gains share at the steepest rate.
Application:
Cost tier differentiation separates premium-positioned event ticketing from commodity-pressured food delivery where margin compression demands infrastructure efficiency.
- Retail Checkout:Silent terminal deployments eliminate visible point-of-sale hardware in favor of embedded environmental sensors. North American grocery operators expand these systems to reduce labor allocation at front-end positions.
- E-Grocery:Predictive replenishment algorithms trigger automatic inventory debits based on consumption velocity patterns. JD.com's fulfillment data integration in Shanghai and Beijing displaces traditional ERP reorder systems.
- Food Delivery:Cellular dead zones in urban canyons and remote logistics corridors demand edge-completed transactions. Localized processing bypasses cloud dependency entirely.
- Transportation Booking:Underground transit systems require sub-200-millisecond authentication without network connectivity. Edge architectures satisfy this constraint.
- Event Ticketing:Facial recognition entry systems in French stadiums and German venues face EU AI Act conformity assessment requirements extending procurement timelines.
Retail checkout commands the installed base while e-grocery climbs fastest as predictive inventory systems mature.
End User Industry:
Customer type fragmentation splits between compliance-heavy regulated entities and agile platform-native deployers with lighter legal infrastructure burdens.
- Ecommerce Platforms:Unified checkout experiences across device types demand tokenized credential interoperability. Competing domestic mobile wallet standards fragment cross-border silent transaction capability.
- Financial Institutions:PCI-DSS tokenization standards require cryptographic continuity across distributed edge nodes. Security architecture integration challenges elevate implementation complexity.
- Hospitality Chains:GDPR-compliant facial recognition modules face supply concentration in East Asian foundries. Single-source vulnerability constrains European terminal vendor procurement flexibility.
- Transportation Providers:Ambient authentication in cellular dead zones prioritizes edge computing deployments over cloud-dependent alternatives.
- Entertainment Services:Algorithmic transparency documentation mandates under EU AI Act extend vendor qualification periods.
Financial institutions anchor procurement volume while hospitality chains expand most quickly as biometric entry systems proliferate.
Deployment Model:
Supply concentration in semiconductor design capabilities favors edge-optimized architectures over centralized cloud infrastructure for latency-sensitive applications.
- Cloud-Based:Serverless architectures sustain low-latency voice processing for checkout terminals with consistent network connectivity. Amazon leverages this approach for North American grocery deployments.
- On-Premise:Dedicated hardware installations satisfy data residency requirements for financial institutions with strict custody protocols.
- Hybrid:Split processing between local inference and cloud analytics balances latency against computational depth for voice commerce applications.
- Edge Computing:On-device neural processing units complete transactions without data transmission. Japanese and South Korean grocery chains deploy localized acoustic models eliminating GDPR retention risks.
Cloud-based systems anchor current deployment share while edge computing expands at the steepest trajectory as on-device AI capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for quiet commerce infrastructure varies sharply by geography: European buyers absorb premium pricing for GDPR-compliant biometric modules while emerging market operators prioritize low-cost NFC deployments over voice-enabled edge systems.
United States
Grocery retailers in Illinois and Texas face divergent biometric privacy litigation exposure under state-specific statutes, elevating insurance costs for multi-state silent checkout rollouts. The FTC's evolving stance on algorithmic transparency creates compliance uncertainty for facial recognition deployers. Amazon's serverless architecture sustains low-latency voice processing at checkout terminals across Seattle and San Francisco Bay Area pilot locations.
China
Super-app wallet penetration exceeding ninety percent in Shanghai and Beijing collapses consumer onboarding friction for voice commerce modules. MIIT standards for mobile payment interoperability constrain tokenized credential exchange across competing domestic protocols. JD.com controls last-mile fulfillment data feeding predictive inventory algorithms in Yangtze River Delta convenience retail clusters.
Germany
French and German hospitality sectors now require algorithmic transparency documentation for facial recognition under EU AI Act risk-classification frameworks. The KBA and federal data protection authorities enforce strict biometric data retention limits extending procurement cycles to 12-18 months. Berlin and Munich hotel operators favor privacy-preserving alternatives processing authentication locally without cloud retention.
Japan
Grocery chains deploy localized acoustic models completing intent parsing without data transmission, eliminating GDPR-equivalent retention risks under Japan's APPI framework. METI subsidies for edge computing infrastructure accelerate on-device neural processing unit adoption. Tokyo and Osaka retail terminals achieve sub-200-millisecond voice response thresholds through domestic semiconductor partnerships.
India
The National Payments Corporation of India's voice-enabled UPI infrastructure remains underpenetrated in tier-2 and tier-3 urban centers, offering first-mover positioning for localized biometric vendors. RBI guidelines on tokenized card transactions create interoperability requirements for silent payment rails. Maharashtra and Karnataka urban corridors concentrate early deployment of NFC field protocols under four centimeters.
Quiet Commerce Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with cloud infrastructure operators sustaining low-latency processing through serverless architectures while edge hardware vendors capture margin pools in proprietary biometric sensor manufacturing. The market structure bifurcates between consolidated platform ecosystems with super-app integration capabilities and fragmented terminal vendors competing on GDPR compliance specialization. Three strategic archetypes dominate: vertically integrated technology conglomerates controlling payment rails and fulfillment data, compliance-native infrastructure providers serving European regulatory complexity, and edge-optimized semiconductor designers displacing cloud-dependent inference. Competitive moves concentrate on strategic partnerships with grocery chains for pilot deployments and geographic expansion through tier-2 urban penetration in underbanked markets.
Within the platform ecosystem tier, Amazon and Alibaba Group exemplify divergent approaches to silent checkout architecture, with the former leveraging serverless cloud infrastructure and the latter anchoring position through proprietary biometric sensors integrated with domestic mobile wallet standards. JD.com occupies a distinct position controlling last-mile fulfillment data that feeds predictive inventory algorithms, representing the vertical integration archetype where transaction processing and logistics optimization converge. Among specialized commerce enablers, Shopify sits within the merchant-facing infrastructure layer, exemplifying the compliance-agnostic platform model that cedes regulatory complexity to regional partners rather than absorbing biometric privacy litigation exposure directly.
| Leading Market Players |
|---|
| Amazon |
| Alibaba Group |
| Shopify |
| Walmart |
| eBay |
| JD.com |
| Mercado Libre |
| Rakuten |
| Sea Limited |
| Others |
Pricing and Supply Chain Analysis
Twelve-to-eighteen-month procurement cycles for GDPR-compliant facial recognition modules compress inventory turns and amplify pricing power for East Asian foundries with certified biometric sensor capacity. Hardware subscription models and interchange fee structures in contactless payments create divergent margin pools that reward cloud infrastructure operators with serverless architectures while squeezing terminal vendors facing single-source component vulnerability.
Pricing Analysis
Hardware-as-a-service recurring revenue streams anchor lifetime value for edge computing terminal deployers, with subscription tiers scaling by authentication throughput volume and API call frequency. Three-tier pricing structure across premium, standard, and economy levels separates PCI-DSS Level 1 certified terminals from basic NFC proximity readers and white-label biometric modules. Cost compression in voice commerce edge devices is intensifying because acoustic modeling talent scarcity constrains vendor scaling velocity. Ecommerce platforms with multi-state US presence exhibit highest price sensitivity due to fragmented BIPA litigation exposure, while European hospitality chains absorb premium pricing for algorithmic audit documentation.
Supply Chain Analysis
Strategic stockpiling of neural processing units dominates inventory strategy as lead-time volatility from Taiwan and South Korean foundries disrupts edge-optimized semiconductor availability. Biometric sensor manufacturing concentrates in East Asian foundries, with specialized acoustic components drawing from Japanese domestic partnerships and German precision optics clusters. Supply chain risk centers on single-source vulnerability for GDPR-compliant facial recognition modules subject to EU AI Act conformity assessment delays. Distribution runs through terminal OEMs serving grocery chains and hospitality deployers, with direct-to-merchant hardware subscriptions gaining share in North American pilot deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of sub-300-millisecond acoustic engineering talent and certified edge-optimized semiconductor design capability concentrates competitive advantage among vertically integrated technology conglomerates. The capability gap between cloud-native serverless architectures and localized neural processing unit deployment creates divergent investment theses across infrastructure layers.
For Market Incumbents: Fortify position through captive supply of biometric sensor manufacturing capacity in Taiwan and South Korea, insulating against EU AI Act procurement cycle extensions. Absorb compliance-native infrastructure providers in Europe to internalize algorithmic transparency documentation costs. Defend against voice commerce latency disruption by acquiring specialized acoustic modeling teams outside major technology hubs. For New Entrants and Emerging Players: Lead with edge-completed transaction architectures targeting India's tier-2 and tier-3 urban centers where NPCI voice-enabled UPI rails remain underpenetrated. White-space concentration in cellular dead zones of underground transit systems and remote logistics corridors offers lowest competitive density. Go-to-market through localized biometric authentication partnerships with domestic mobile wallet standards in underbanked markets. For Investors and Strategic Acquirers: Carve-out targets emerge from technology conglomerates divesting non-core terminal hardware divisions to focus on cloud infrastructure software layers. Long-term viability favors edge-optimized semiconductor designers with neural processing unit architectures displacing cloud-dependent inference. Watch EU AI Act enforcement intensity against French and German hospitality facial recognition deployments as inflection indicator for compliance-native infrastructure provider valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Partnership | Localized transaction completion in cellular dead zones bypasses cloud dependency entirely for transportation and food delivery operators. |
| Biometric Sensor Manufacturing Scale-Up | Captive supply of GDPR-compliant facial recognition modules insulates against East Asian foundry concentration risk. |
| Acoustic Modeling Talent Acquisition | Sub-300-millisecond voice response engineering capability constrains vendor scaling velocity in voice commerce expansion. |
| Compliance-Native Infrastructure Investment | Algorithmic transparency documentation expertise compresses 12-18 month EU AI Act procurement cycles for hospitality deployers. |
| Predictive Inventory System Integration | Last-mile fulfillment data convergence with silent replenishment triggers displaces traditional ERP reorder point systems. |
Research Methodology
Operator-level perspectives from grocery chain CTOs, hospitality procurement directors, biometric sensor manufacturing plant managers, and edge computing infrastructure engineers anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings of platform ecosystem operators, ETSI technical standards documentation, EU AI Act implementation guidance from French CNIL and German KBA, and NPCI UPI transaction volume disclosures. Bottom-up terminal deployment estimates triangulated against top-down payment rail transaction forecasts.
Sensitivity analysis tested authentication latency thresholds, biometric data retention period assumptions, and super-app wallet penetration elasticity across the analysis window. Segmentation modeling incorporated solution type, application context, end user industry, and deployment model dimensions with regional regulatory cluster differentiation. CAGRs derived from fitted growth curves applied to hardware subscription revenue streams and interchange fee pool allocations, with edge computing adoption velocity and voice commerce NLP latency improvement rates as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained sub-4-centimeter NFC protocol standardization and EU AI Act risk-classification stability would require recalibration. Forecasts reflect documented assumptions regarding biometric sensor supply concentration and tokenized credential interoperability progression. Revision becomes warranted when Illinois BIPA litigation exposure or EU algorithmic audit enforcement intensity crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Clothing E-Commerce Platform Market
E-Commerce Solutions
Agricultural E-Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
Hungary E-Commerce Market
E-Commerce Solutions
Bedding E-Commerce Platform Market
E-Commerce Solutions
Asia Pacific B2B E-Commerce Market
E-Commerce Solutions
Iceland E-Commerce Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
UAE Q-Commerce Industry Market
E-Commerce Solutions
China Online Trading Platform Market
E-Commerce Solutions
Pharmaceutical E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
Global Shopping Cart Market
E-Commerce Solutions
Belgium E-Commerce Market
E-Commerce Solutions
LAMEA Dropshipping Market