
 Global Customer Communications Management (CCM) Software Market | 2026-2036
Global Customer Communications Management (CCM) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Customer Communications Management (CCM) Software Market Foresight
Subscription-based managed services is pivoting how CCM vendors monetize customer relationships, shifting perpetual licenses toward recurring revenue models. Quadient leverages its established presence in document composition to sustain enterprise loyalty across European banking clients. Salesforce Service Cloud anchors its competitive stance through deep CRM integration, while Zoho Desk competes aggressively on price for mid-market telecom providers in Asia.
Customer Communications Management (CCM) software orchestrates the creation, delivery, storage, and retrieval of outbound communications across print and digital channels, typically integrating template libraries, business rules engines, and output management systems to ensure regulatory-compliant, personalized correspondence at scale. Cloud-based deployment leads solution type demand as insurers and utilities seek elastic infrastructure for seasonal billing spikes, while multi-channel delivery represents the fastest-growing segment as enterprises unify SMS, email, and portal messaging under single workflow governance. Document composition retains mature, high-margin utility in BFSI institutions where legacy mainframe integrations create switching costs.
The EU AI Act and GDPR impose strict audit trails on automated customer communications, compelling vendors to embed consent logging and explainability features into platform architectures. In the United States, HIPAA and state-level data privacy laws shape healthcare and insurance CCM requirements, while India's Digital Personal Data Protection Act drives localization mandates for cloud-hosted customer notification systems. Stakeholders must evaluate whether their architecture supports real-time compliance adaptation as regulatory fragmentation deepens across jurisdictions.
Market Dynamics
Cloud-native document composition architectures are compressing deployment cycles from months to weeks, forcing incumbent vendors to re-engineer monolithic platforms into API-first microservices or surrender enterprise accounts to agile challengers.
Growth Catalysts
- EU AI Act audit mandates:Financial institutions across Germany and France require embedded consent logging for automated correspondence, expanding platform replacement cycles.
- India's Digital Personal Data Protection Act:Data localization requirements for customer notifications are driving domestic cloud infrastructure investments by insurers and telecom operators.
- Real-time personalization engines:Machine learning-driven content variation is overtaking static template libraries in US healthcare payer communications.
Market Restraints
- Legacy mainframe integration debt:European banks face prohibitive switching costs from decades-old document composition systems with custom COBOL connectors.
- Specialized compliance talent scarcity:GDPR and HIPAA-certified solution architects command premium compensation, inflating implementation timelines.
- Open-source template alternatives:Apache FOP and community-driven composition tools erode pricing power in mid-market segments.
Strategic Opportunities
- Brazilian pension reform digitization:Regulatory mandates for electronic beneficiary communications create first-mover advantages for multi-channel platforms.
- Conversational AI fusion:Integration of large language models with structured document workflows enables dynamic policy explanation generation.
- Embedded finance ecosystems:Banking-as-a-Service providers require white-labeled CCM capabilities for co-branded customer touchpoints.
Industry Challenges
- Cross-channel identity resolution:Unifying customer profiles across disconnected SMS, email, and portal systems demands complex master data management investments.
- Explainability documentation:AI-generated content variations require auditable decision trails that most existing workflow engines cannot natively produce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Customer Communications Management (CCM) Software Market |
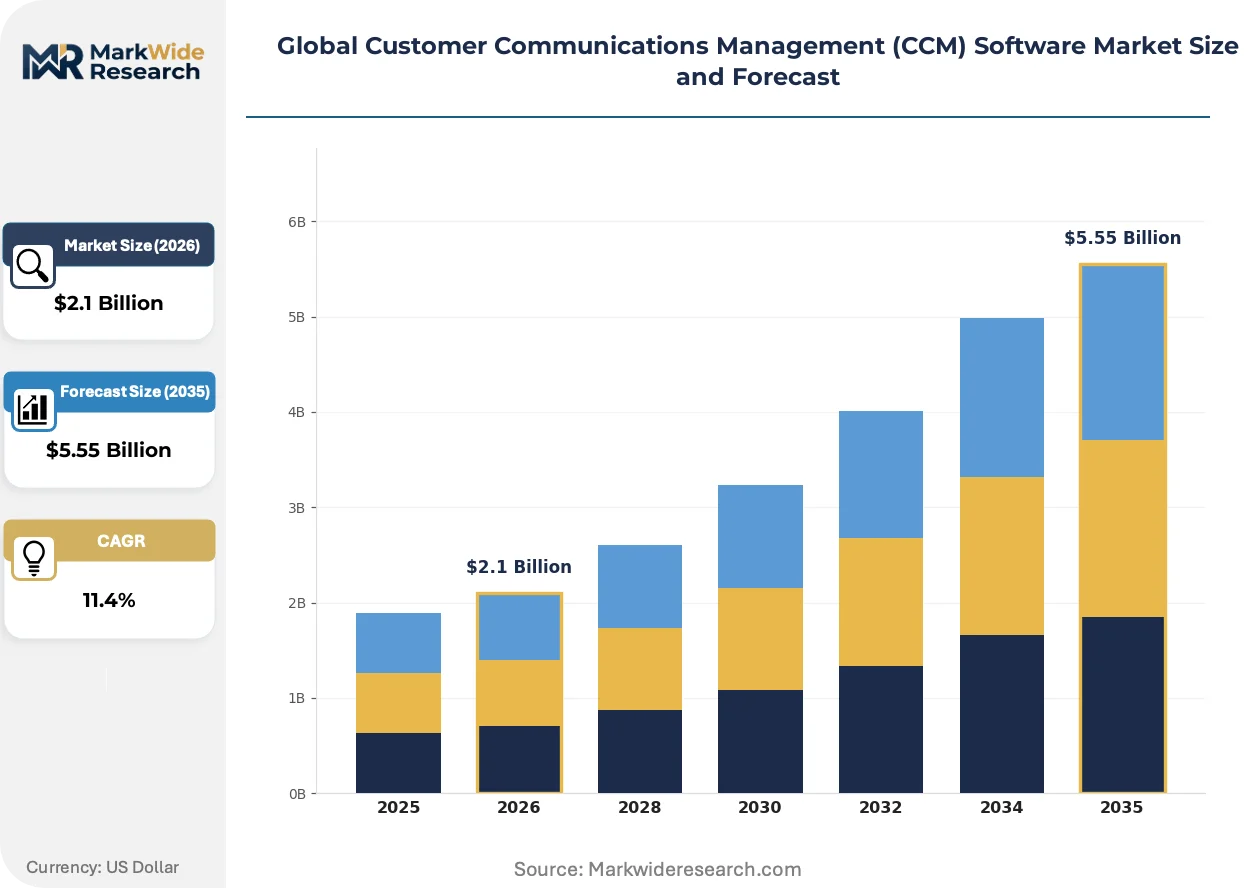
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid Cloud, Software as a Service, Managed Services Solution Type: Document Composition, Customer Interaction Management, Multi-Channel Delivery, Analytics & Reporting, Digital Experience Use Case: Policy Documentation, Billing & Invoicing, Customer Notifications, Marketing Campaigns, Regulatory Communications End User Sector: BFSI Institutions, Telecommunications Providers, Insurance Carriers, Utilities Companies, Government Agencies |
| Companies Covered | Quadient, Clinked, Salesforce Service Cloud, SuiteDash, Odoo, Zoho Desk, Podium, Moxo, Freshdesk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Customer Communications Management (CCM) Software Market Shifts & Advancements
Generative AI is compressing content production timelines while regulatory fragmentation forces architectural investments in jurisdictional flexibility. Vendors must simultaneously accelerate innovation cycles and harden compliance infrastructure.
Headless document composition APIs are overtaking traditional desktop-centric design environments. Insurers in the United States are adopting these interfaces to embed correspondence generation directly into Salesforce Service Cloud and proprietary policy administration systems. This shift collapses the handoff delays between CRM data and physical or digital output, enabling same-day policy endorsement communications.
The EU AI Act's risk classification framework imposes documentation burdens on automated customer communications that fall under "high-risk" AI applications. Financial services firms must maintain technical files demonstrating human oversight of content generation algorithms. German banking regulators are requiring pre-deployment conformity assessments for systems generating credit decision explanations.
Subscription consumption models are displacing perpetual license arrangements across mid-market buyers. Telecom providers in India prefer managed service contracts where vendors assume infrastructure scaling responsibility for seasonal billing spikes. This transfers operational risk to platform providers while locking in predictable recurring revenue streams that fund continuous compliance adaptation.
Global Customer Communications Management (CCM) Software Market Segmentation
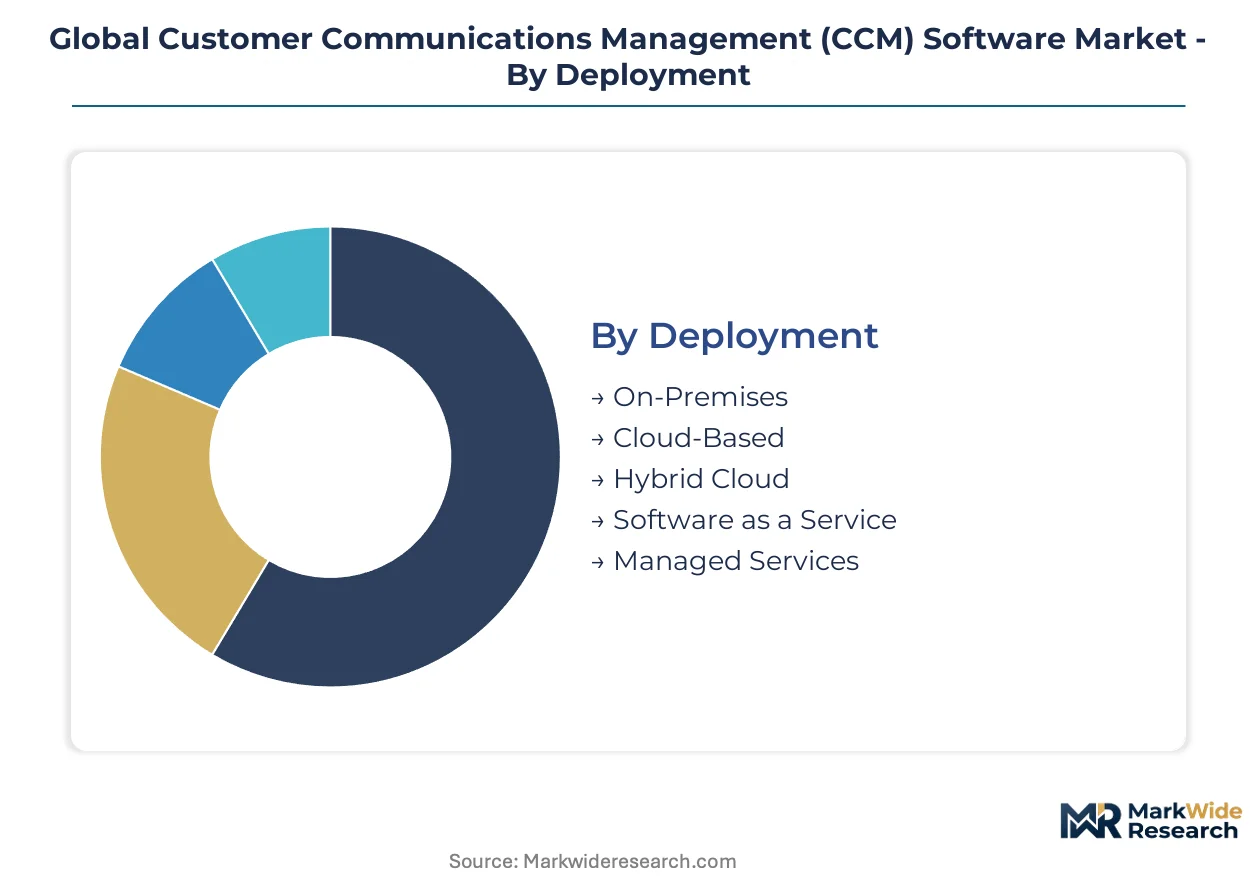
CCM procurement patterns diverge sharply by organizational scale, regulatory exposure, and infrastructure legacy. Buyers select deployment architectures and solution bundles based on seasonal volume volatility, compliance audit frequency, and existing core system dependencies.
Deployment:
Enterprise buyers sort into cost tiers defined by capital availability, internal IT headcount, and risk tolerance for vendor dependency.
- Cloud-Based:Elastic infrastructure provisions compute on demand for insurers processing quarterly billing spikes. German utilities favor this model to avoid data center CapEx while maintaining GDPR-compliant EU data residency through regional cloud zones.
- Managed Services:Vendors assume operational responsibility for infrastructure scaling and patch management. Indian telecom operators prefer consumption-based contracts that transfer seasonal capacity risk to platform providers.
- On-Premises:Legacy installations persist in US healthcare payers bound by HIPAA data sovereignty requirements.
- Hybrid Cloud:Workload splitting between private and public infrastructure accommodates phased cloud migration in European banking.
- Software as a Service:Standardized multi-tenant platforms serve mid-market BFSI institutions with limited customization needs.
Volume sits with On-Premises legacy estates; growth tilts toward Cloud-Based consumption models.
Solution Type:
Functional maturity separates segments: core composition utilities command stable maintenance revenue while experience-layer capabilities capture expansion budgets.
- Multi-Channel Delivery:Unified workflow governance across SMS, email, and portal messaging collapses operational silos. US insurers prioritize this segment to consolidate policy notifications under single audit trails for state regulator examinations.
- Document Composition:Template libraries with embedded business rules engines remain embedded in BFSI core systems. French banks retain these tools for credit decision explanation generation under EU AI Act documentation mandates.
- Customer Interaction Management:Real-time conversation threading supports high-touch service recovery in telecommunications.
- Analytics & Reporting:Communication effectiveness measurement attracts marketing operations investment.
- Digital Experience:Self-service portal integration expands in utilities modernizing customer account management.
Revenue concentrates in Document Composition; expansion spending flows fastest into Multi-Channel Delivery.
Use Case:
Regulatory pressure intensity determines solution complexity and implementation timeline.
- Regulatory Communications:Mandated disclosure delivery requires immutable audit trails and consent logging. German banking supervisors demand pre-deployment conformity assessments for automated correspondence systems.
- Policy Documentation:Contract generation workflows integrate with core administration systems. US property insurers invest here to accelerate endorsement turnaround from weeks to same-day delivery.
- Billing & Invoicing:High-volume transactional output drives infrastructure scale requirements.
- Customer Notifications:Proactive service alerts reduce call center volume in telecommunications.
- Marketing Campaigns:Personalized promotional content generation attracts retail banking investment.
Implementation backlog clusters in Regulatory Communications; automation penetration runs deepest in Policy Documentation.
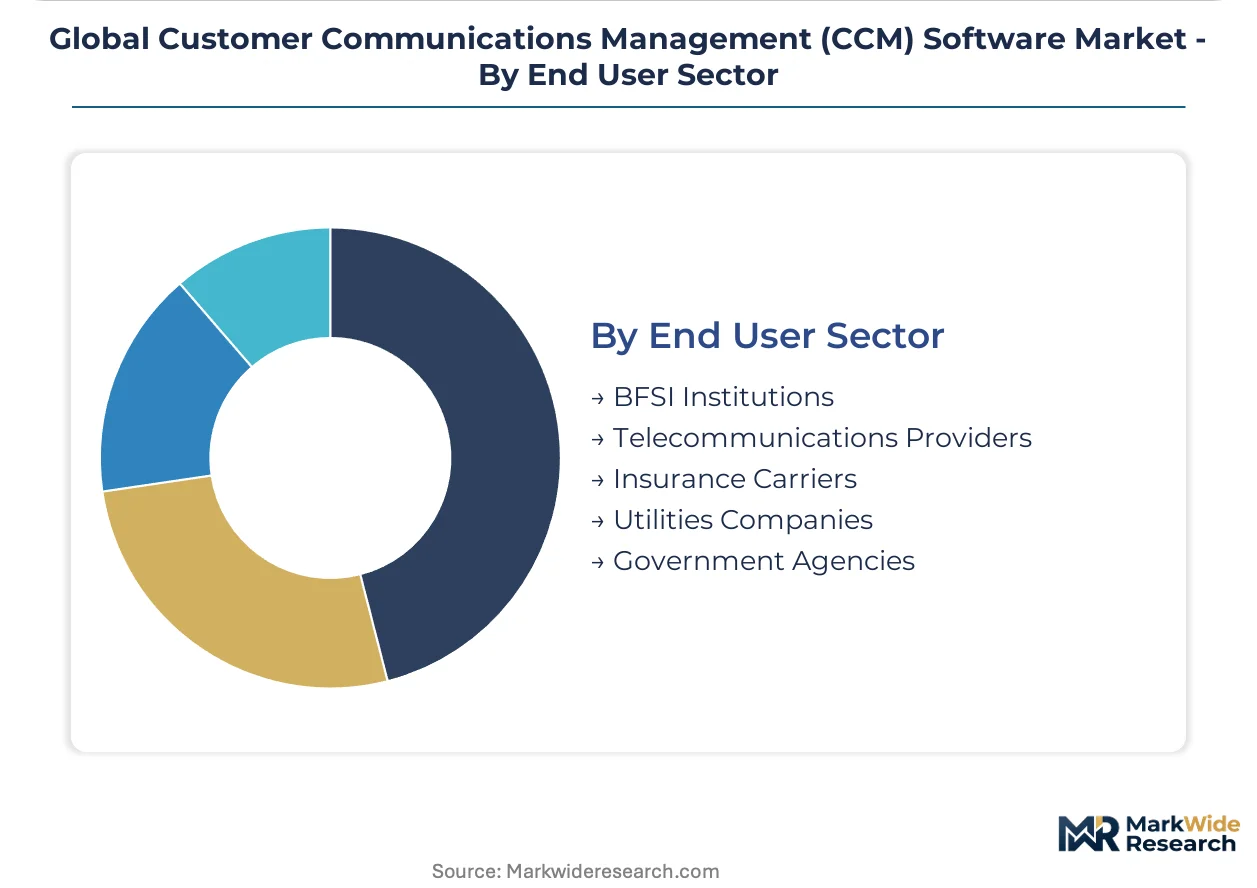
End User Sector:
Industry-specific compliance regimes dictate platform selection criteria and vendor evaluation weightings.
- BFSI Institutions:Multi-jurisdictional operations require platforms adapting to fragmented regulatory frameworks. Indian banks under RBI localization mandates prioritize domestic cloud-hosted deployments.
- Insurance Carriers:Seasonal premium cycles and claims correspondence volume demand elastic infrastructure. US health insurers combine HIPAA compliance with real-time personalization for member engagement.
- Telecommunications Providers:High-frequency billing cycles and churn management drive notification volume.
- Utilities Companies:Rate case documentation and outage communications require regulatory filing integration.
- Government Agencies:Citizen service delivery modernization programs expand digital-first communication investment.
Platform spending dominates in BFSI Institutions; steepest expansion trajectory appears in Insurance Carriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's banking district generates concentrated demand for audit-ready CCM platforms as German financial institutions confront EU AI Act documentation mandates for automated credit communications.
United States
New York-based insurers and Boston-area healthcare payers drive cloud migration for HIPAA-compliant member correspondence. The IRA's digital health provisions accelerate real-time personalization investments. Silicon Valley vendors embed headless APIs into Salesforce Service Cloud deployments, collapsing policy endorsement turnaround to same-day delivery.
Germany
BaFin supervision of automated credit explanations compels Frankfurt banks to replace legacy document composition systems. The EU AI Act's high-risk classification for financial communications mandates pre-deployment conformity assessments. Munich insurers favor managed service contracts that transfer seasonal capacity risk to platform providers.
India
Mumbai's banking sector and Bengaluru's telecom operators confront RBI localization mandates for customer notification systems. The Digital Personal Data Protection Act drives domestic cloud infrastructure investments. Hyderabad insurers prefer consumption-based pricing that accommodates quarterly premium cycle spikes.
United Kingdom
London's BFSI cluster seeks GDPR-compliant multi-channel delivery for post-Brexit regulatory divergence. The FCA's consumer duty rules intensify audit trail requirements for policy documentation. Edinburgh insurers test hybrid cloud architectures to phase out mainframe dependencies.
Brazil
São Paulo pension administrators digitize beneficiary communications under ANS electronic delivery mandates. Regulatory reform creates first-mover advantages for multi-channel platforms. Rio de Janeiro insurers evaluate conversational AI integration for dynamic policy explanation generation.
Global Customer Communications Management (CCM) Software Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the CCM software landscape. The vendor base separates into established document composition incumbents, CRM-anchored platform extenders, and agile SaaS challengers. Three strategic archetypes dominate: legacy modernization specialists, ecosystem-integrated suites, and API-first microservices providers. Consolidation pressure intensifies as cloud-native entrants compress deployment cycles, forcing incumbents toward strategic partnerships or portfolio diversification.
Within the legacy modernization tier, Quadient occupies a position exemplifying European banking loyalty sustained through document composition depth. Salesforce Service Cloud anchors the CRM-integrated archetype, representing ecosystem extension strategies that embed correspondence generation within customer service workflows. Zoho Desk exemplifies price-competitive positioning for mid-market telecom providers across Asian markets, occupying a position within the agile challenger tier that prioritizes rapid deployment over customization depth.
| Leading Market Players |
|---|
| Quadient |
| Clinked |
| Salesforce Service Cloud |
| SuiteDash |
| Odoo |
| Zoho Desk |
| Podium |
| Moxo |
| Freshdesk |
| Others |
Supply & Pricing Matrix
Subscription fatigue among mid-market telecom providers in India and Asia is compressing vendor margins, forcing platform providers to absorb infrastructure scaling costs and restructure delivery models around consumption-based contracts that transfer operational risk downstream.
Pricing Analysis
Margin tightening in the SaaS tier reflects hyperscaler compute cost pass-throughs and open-source template erosion. Three-tier pricing structure across enterprise, mid-market, and entry-level segments dominates, with differentiation anchored in compliance certification depth and API integration complexity. Cost-down pressure on managed service contracts accelerates because Indian telecom operators demand seasonal elasticity without premium pricing. Mid-market buyers exhibit highest price sensitivity; BFSI institutions with legacy switching costs show lowest.
Supply Chain Analysis
Cross-border data residency compliance adds 15-25% freight-equivalent cost premiums to cloud infrastructure delivery between EU zones and Indian domestic facilities. Supply concentrates in the United States, Germany, and India for core platform development, with compute infrastructure drawing from Irish, Singaporean, and Mumbai cloud regions. Dependency on NVIDIA GPU clusters, specialized encryption hardware, and jurisdictional data center certifications creates single-source vulnerability. Distribution runs through direct enterprise sales, hyperscaler marketplaces, and regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race: platform providers are capturing downstream managed service revenue and upstream compliance certification capabilities to lock in recurring revenue streams.
For Market Incumbents: Acquire cloud-native microservices architectures to compress deployment cycles against agile challengers. Consolidate API-first document composition capabilities to defend against headless entrants embedding into Salesforce Service Cloud and Zoho Desk ecosystems. Pursue backward integration into domestic data center infrastructure for Indian and EU localization mandates. For New Entrants and Emerging Players: Begin with Brazilian pension reform digitization and ANS electronic delivery mandates where incumbent presence remains thin. Target mid-market utilities in the United States seeking HIPAA-compliant member correspondence without enterprise pricing. Lead with conversational AI fusion for dynamic policy explanation generation as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Re-rating potential sits with API-first microservices providers given EU AI Act documentation mandates accelerating platform replacement cycles. Long-term viability favors vendors with embedded consent logging and explainability infrastructure. Watch German BaFin pre-deployment conformity assessment timelines as inflection indicator for enterprise replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Compresses deployment cycles from months to weeks for German banking clients. |
| Compliance Certification Investment | Captures EU AI Act and GDPR audit-ready positioning in Frankfurt financial district. |
| Managed Service Contract Expansion | Transfers seasonal capacity risk to providers serving Indian telecom operators. |
| API-First Platform Integration | Embeds correspondence generation directly into Salesforce Service Cloud workflows. |
| Geographic Data Center Localization | Satisfies RBI and Digital Personal Data Protection Act mandates for Mumbai banks. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and EU regulatory compliance databases formed the secondary backbone. Primary interviews with CCM platform CTOs, IT procurement officers at US healthcare payers, integration specialists serving European banking, and regulatory affairs leads at German insurers combined with bottom-up and top-down triangulation. Stakeholder input validated deployment model adoption rates and compliance investment timelines.
Bottom-up modeling aggregated segment-level deployment, solution type, and end-user sector volumes across the analysis window. Top-down cross-checks incorporated regulatory mandate acceleration curves and cloud infrastructure expansion trajectories. CAGRs derived from weighted technology adoption S-curves and compliance-driven replacement cycle compression. Forecast inputs included EU AI Act implementation phasing and India's Digital Personal Data Protection Act localization requirements.
Underlying measurement precision varies by segment; cloud-based and multi-channel delivery carry tighter precision than on-premises legacy estates. Forecasts reflect assumptions around regulatory enforcement intensity and hyperscaler pricing stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Recreation Management Software Market
Software & Services
Live Software Market
Software & Services
Europe Business Software Market
Software & Services
Discount Management Software Market
Software & Services
Acoustic Simulation Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
North America Servicenow Store Apps Market
Software & Services
School Timetable Software Market
Software & Services
Meditation Software Market
Software & Services
Global Gamification Software Market
Software & Services
CGI Software Market
Software & Services
Photobooth Software Market
Software & Services
POS Software Market
Software & Services
Global AR Game Engine Software Market
Software & Services
Global DevOps Software Market
Software & Services
Global Managed File Transfer Software Market