
 Simulation Software Market | 2026-2036
Simulation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Simulation Software Market Analysis
The EU Green Deal is decoupling engineering validation from physical prototyping cycles across European automotive supply chains. Siemens AG leverages its industrial software stack to anchor digital twin deployments in German manufacturing. Dassault Systemes SE differentiates through integrated PLM-simulation workflows that sustain long-term aerospace contracts. Altair Engineering, Inc. competes on solver performance in lightweighting applications for electric vehicle platforms.
Simulation software encompasses computational tools that model physical phenomena through numerical methods, typically executing finite element discretization or Navier-Stokes fluid dynamics on high-performance clusters to predict product behavior before physical build. The primary industrial purpose centers on reducing development cost and failure risk across engineered systems. Finite Element Analysis dominates current license revenue due to its entrenched role in structural safety certification, while Cloud-Based deployment represents the fastest-expanding consumption model as enterprises shift capital expenditure to operational budgets. Academic Institutions constitute a stable, price-sensitive demand pool that trains future commercial users.
The European Union's CSRD and EU AI Act impose algorithmic transparency requirements on simulation-driven autonomous systems, compelling vendors to embed audit trails within solver outputs. The US FAA mandates computational validation for aircraft component certification, creating a regulated demand floor for high-fidelity physics engines. China's MIIT promotes domestic CAE substitution through GB standards alignment, reshaping vendor access patterns. Stakeholders must weigh sovereign data requirements against cloud solver elasticity when architecting multi-regional deployment strategies.
Market Dynamics
Cloud-native solver architectures are compressing procurement cycles as engineering departments shift capital expenditure to operational budgets, while the EU AI Act mandates algorithmic transparency in simulation-driven autonomous systems.
Growth Catalysts
- EU AI Act compliance:Aerospace and automotive manufacturers must embed audit trails within solver outputs for autonomous system certification, expanding license demand for traceable simulation platforms.
- Digital twin adoption:Engine certification workflows at major aerospace manufacturers now require high-fidelity physics engines that mirror physical component behavior.
- Stuttgart-Munich corridor:Germany's automotive engineering concentration drives concentrated procurement of lightweighting simulation tools for electric vehicle platforms.
Market Restraints
- High-performance computing costs:Navier-Stokes fluid dynamics and finite element discretization require specialized GPU clusters, creating sustained operational expenditure pressure.
- License concentration:Structural safety certification workflows depend on entrenched finite element analysis vendors, limiting price competition and solver substitution.
- Domestic CAE substitution:China's MIIT promotes GB standards-aligned domestic software, reshaping vendor access patterns for foreign simulation providers.
Strategic Opportunities
- Academic institution channel:Price-sensitive university demand trains future commercial users, creating captive pipeline development for downstream enterprise licensing.
- EU Green Deal validation:Decoupling engineering validation from physical prototyping cycles opens subscription revenue in European automotive supply chains.
- AI-solver convergence:Machine learning surrogate models integrated with traditional physics engines reduce computational load for iterative design exploration.
Industry Challenges
- Multiphysics integration complexity:Coupling structural, thermal, and fluid solvers requires specialized expertise scarce in mid-tier engineering departments.
- CSRD audit trail implementation:Embedding sustainability reporting data capture within simulation metadata adds development overhead for software vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Simulation Software Market |
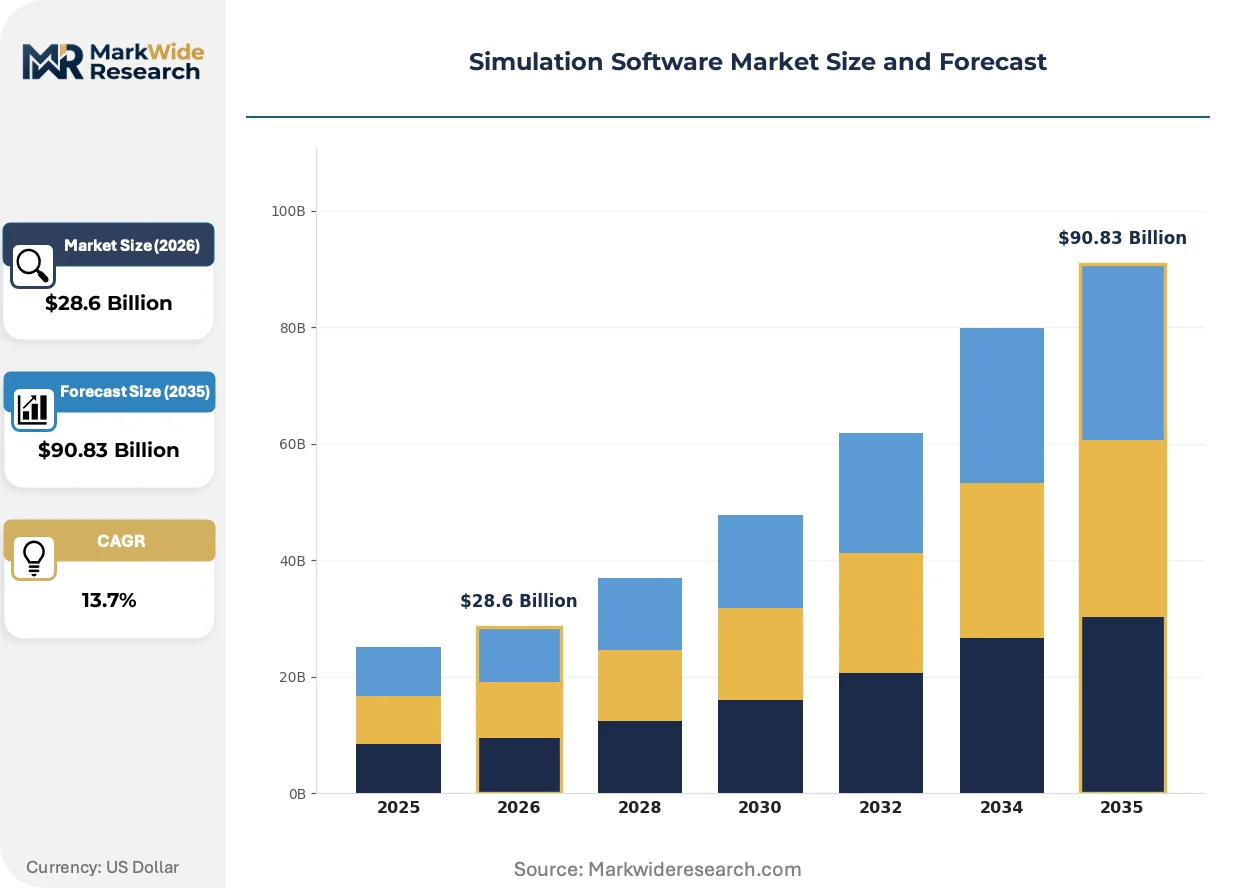
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $90.83 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
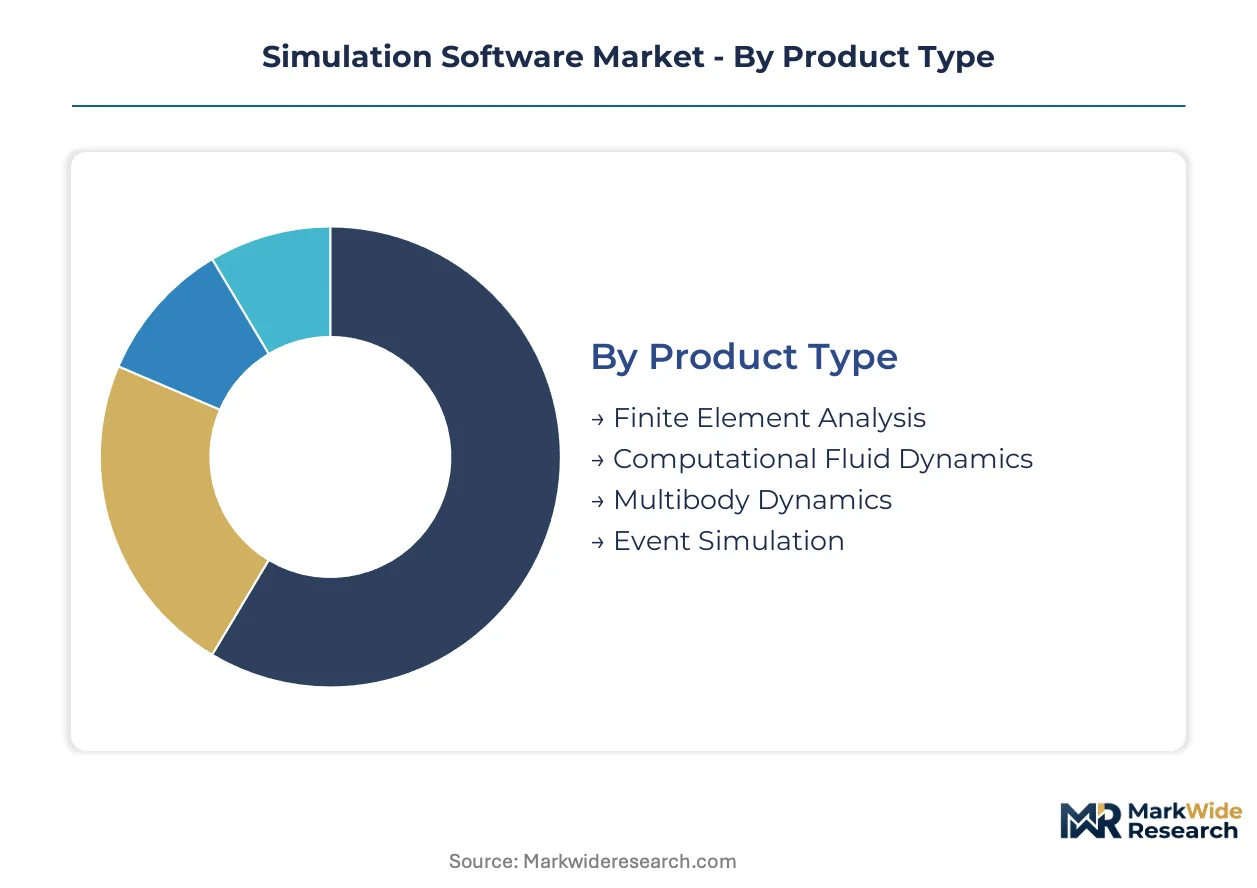
| Segmentation | Product Type: Finite Element Analysis, Computational Fluid Dynamics, Multibody Dynamics, Event Simulation End User: Aerospace, Automotive OEMs, Healthcare Providers, Academic Institutions Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Application: Training Simulations, Process Optimization, Risk Assessment, Product Design |
| Companies Covered | ANSYS, Inc., Dassault Systemes SE, Siemens AG, Altair Engineering, Inc., Autodesk, Inc., The MathWorks, Inc., PTC, Inc., Hexagon AB, Bentley Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Simulation Software Market Emerging Trajectories
Physics-informed machine learning is compressing solver runtimes while regulatory mandates force transparency into previously black-box computational methods.
GPU-accelerated lattice Boltzmann methods are consolidating computational fluid dynamics workflows by replacing traditional finite volume approaches in automotive aerodynamics. Tier-one suppliers now deploy these solvers for overnight design iterations. The technology is consolidating previously separate pre-processing and solving stages into unified cloud-native environments.
The EU AI Act's algorithmic transparency requirements now extend to simulation-driven decision systems in autonomous vehicles. Manufacturers must demonstrate reproducibility in physics-based predictions used for safety certification. German automotive engineering clusters are responding by embedding version-controlled solver configurations directly into PLM audit trails.
Consumption-based licensing is displacing perpetual seat models as enterprise buyers prioritize operational flexibility. Engineering departments at aerospace manufacturers now meter solver hours against project budgets rather than maintaining fixed license pools. This pattern is most visible in US and German defense-adjacent manufacturing where contract volatility demands scalable computational resources.
Simulation Software Market Segmentation
Simulation software procurement patterns diverge sharply across deployment architectures and end-use certification requirements. Aerospace manufacturers demand FAA-validated physics engines, while automotive buyers prioritize EU AI Act-compliant traceability for autonomous systems.
Product Type:
Certification burdens vary dramatically by solver methodology, with structural safety mandates driving divergent approval pathways across engineering disciplines.
- Finite Element Analysis:Structural discretization solvers dominate safety-critical validation workflows. Entrenched FEA vendors anchor procurement in German automotive engineering corridors and US defense-adjacent manufacturing where FAA and EASA certification requirements lock in incumbent platforms.
- Computational Fluid Dynamics:Navier-Stokes and lattice Boltzmann implementations compress overnight design iterations for aerodynamic optimization. GPU-accelerated CFD deployments concentrate in Stuttgart-Munich automotive clusters pursuing electric vehicle lightweighting targets.
- Multibody Dynamics:Kinematic solver suites address vehicle dynamics and robotics motion planning.
- Event Simulation:Discrete-event modeling tools optimize manufacturing line throughput and logistics networks.
Finite Element Analysis sits at the top of the volume ranking, with Computational Fluid Dynamics climbing the fastest.
End User:
Cost tiers separate price-insensitive regulated industries from budget-constrained training environments.
- Aerospace:Airframe and propulsion manufacturers mandate computational validation for FAA/EASA certification. High-fidelity physics engines mirror physical component behavior in digital twin deployments for engine certification workflows.
- Automotive OEMs:Stuttgart and Munich engineering clusters drive concentrated procurement of lightweighting simulation tools. EU AI Act compliance requirements now embed audit trails within solver outputs for autonomous vehicle safety certification.
- Healthcare Providers:Patient-specific surgical planning and medical device validation create regulated demand for biomechanical modeling.
- Academic Institutions:Price-sensitive university demand trains future commercial users across engineering disciplines.
Aerospace commands the premium pricing tier, with Academic Institutions representing the volume base for pipeline development.
Deployment:
Customer type determines infrastructure preference, with capital-constrained buyers accelerating operational expenditure shifts.
- On-Premises:Perpetual license models persist in defense-adjacent manufacturing where sovereign data requirements block cloud migration. US and German aerospace contractors maintain captive GPU clusters for classified solver workloads.
- Cloud-Based:Metered consumption models displace fixed license pools as engineering departments shift capital expenditure to operational budgets. Contract volatility in aerospace supply chains demands scalable computational resources without infrastructure commitment.
- Hybrid:Split architectures balance sensitive preprocessing on-premises with elastic solving in cloud environments.
- SaaS:Browser-delivered simulation platforms lower entry barriers for mid-tier engineering departments lacking specialized IT support.
On-Premises retains the installed base, with Cloud-Based gaining share fastest among new procurement cycles.
Application:
Maturity curves separate established engineering validation from emerging AI-driven use cases.
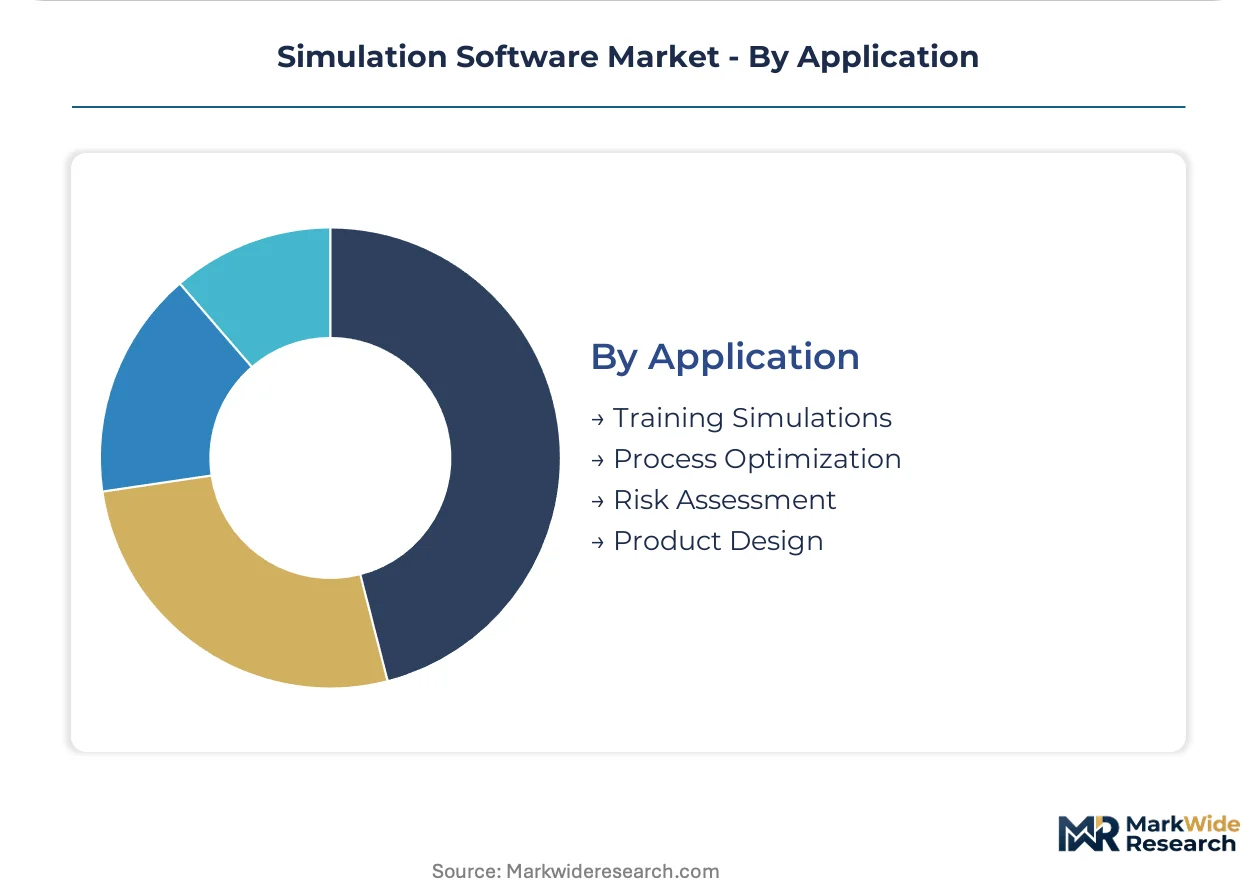
- Training Simulations:Operator and maintenance training systems leverage real-time physics engines for immersive environments.
- Process Optimization:Manufacturing line and supply chain digital twins reduce physical prototyping cycles under EU Green Deal mandates.
- Risk Assessment:Probabilistic simulation models quantify failure modes for insurance and regulatory filing requirements.
- Product Design:Iterative exploration workflows integrate machine learning surrogate models with traditional physics engines to compress design cycles.
Product Design anchors current license revenue, with Risk Assessment expanding most quickly under tightening regulatory disclosure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Simulation software originated in US aerospace laboratories during Cold War defense programs, migrated to German automotive engineering clusters by the 1990s, and now concentrates in cloud-native deployments across three continents. Regulatory divergence shapes procurement patterns as sovereign data requirements clash with elastic computing economics.
United States
FAA mandates computational validation for aircraft component certification, creating regulated demand for high-fidelity physics engines. Defense-adjacent manufacturers maintain captive GPU clusters for classified solver workloads under sovereign data requirements. Greater Boston and Pacific Northwest engineering corridors anchor cloud-native simulation deployments for contract-volatile aerospace supply chains.
Germany
Stuttgart-Munich automotive clusters drive concentrated procurement of lightweighting simulation tools for electric vehicle platforms. EU AI Act compliance requirements embed audit trails within solver outputs for autonomous vehicle safety certification. Baden-Württemberg engineering departments meter solver hours against project budgets rather than maintaining fixed license pools.
China
MIIT promotes domestic CAE substitution through GB standards alignment, reshaping vendor access patterns for foreign simulation providers. Dual carbon goals accelerate digital twin adoption in heavy industrial applications. Yangtze River Delta manufacturing hubs deploy physics-informed machine learning to compress solver runtimes for iterative design exploration.
France
EASA certification requirements lock in incumbent platforms for aerospace structural safety validation. EU Green Deal mandates decouple engineering validation from physical prototyping cycles across automotive supply chains. Île-de-France defense contractors integrate version-controlled solver configurations directly into PLM audit trails for algorithmic transparency.
Japan
METI industrial digitization programs subsidize cloud migration for mid-tier engineering departments lacking specialized IT support. JIS standards alignment creates procurement friction for non-domestic simulation vendors. Kanto manufacturing clusters pursue GPU-accelerated lattice Boltzmann methods for overnight aerodynamic design iterations.
Simulation Software Market Vendor Landscape
Capital-heavy producers compete with asset-light designers as perpetual license vendors face pressure from consumption-based cloud entrants. The vendor base stratifies across three tiers: diversified industrial conglomerates with captive software stacks, pure-play simulation specialists competing on solver performance, and emerging AI-native entrants offering machine learning surrogate models. Consolidation pressures intensify as enterprises demand integrated PLM-simulation workflows rather than point solutions. Dominant competitive moves include strategic partnerships between hardware manufacturers and solver developers, plus geographic expansion through academic institution channel capture.
Within the diversified industrial tier, Siemens AG and Dassault Systemes SE exemplify conglomerate-backed platforms that anchor enterprise deployments through integrated manufacturing software ecosystems. Altair Engineering, Inc. occupies a specialist position competing on solver performance in computationally intensive applications. These three entities represent contrasting archetypes: the captive industrial stack, the PLM-integrated workflow provider, and the performance-optimized independent solver house.
| Leading Market Players |
|---|
| ANSYS, Inc. |
| Dassault Systemes SE |
| Siemens AG |
| Altair Engineering, Inc. |
| Autodesk, Inc. |
| The MathWorks, Inc. |
| PTC, Inc. |
| Hexagon AB |
| Bentley Systems, Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FAA-validated physics engines and academic-tier solvers manifests in both subscription pricing and supply chain sourcing strategies. Premium deployments draw from US and German GPU cluster providers with sovereign data compliance, while price-sensitive buyers source from cloud-native entrants with elastic metered consumption.
Pricing Analysis
Consumption-based licensing with metered solver hours now dominates enterprise procurement, displacing perpetual seat models as aerospace manufacturers shift capital expenditure to operational budgets. Price differentiation hinges on certification grade—FAA/EASA-validated platforms command premium tiers against unvalidated academic licenses—and integration depth with PLM audit trails. Cost compression in mid-tier CFD subscriptions is intensifying because GPU-accelerated lattice Boltzmann methods reduce computational overhead. Academic institutions represent the most price-sensitive segment, while defense-adjacent manufacturers show minimal elasticity due to sovereign data mandates.
Supply Chain Analysis
Single-source vulnerability sits with NVIDIA's dominance in GPU accelerator supply for high-fidelity physics engines, creating concentration risk for solver vendors dependent on HPC infrastructure. Manufacturing concentration spans Taiwan for semiconductor fabrication, the United States for specialized server assembly, and Germany for precision engineering components. Raw material dependencies include advanced node silicon wafers, high-bandwidth memory modules, and liquid cooling systems. Tariff exposure on Chinese-manufactured server components threatens cost structures for cloud-native deployment architectures. Distribution runs through direct enterprise sales with embedded professional services, supplemented by academic channel partnerships for pipeline development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Simulation software offers margin expansion through AI-solver convergence reducing computational infrastructure costs, while EU AI Act compliance creates premium-tier pricing power for traceable audit-trail platforms.
For Market Incumbents: Anchor market position by deepening backward integration into GPU cluster provisioning to capture infrastructure margin and reduce dependency on NVIDIA supply allocation. Invest in EASA certification maintenance for structural safety solvers to defend against emerging physics-informed machine learning substitutes. Prioritize channel control through exclusive academic institution partnerships that lock in future enterprise licensing pipelines. For New Entrants and Emerging Players: Physics-informed machine learning surrogate models offer a technology-first wedge into iterative design exploration workflows where computational load reduction justifies platform switching. White-space targets include mid-tier automotive suppliers in the Stuttgart-Munich corridor lacking specialized multiphysics expertise, and Japanese manufacturing clusters subsidized by METI digitization programs. A SaaS-delivered browser platform with metered consumption lowers entry barriers against entrenched on-premises incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where enterprises demand integrated PLM-simulation workflows rather than point solutions, favoring vendors with captive manufacturing software ecosystems. Long-term viability centers on vendors bridging traditional physics engines with AI-native architectures across the analysis window. Acquisition target archetypes include GPU-accelerated CFD specialists with automotive lightweighting traction and cloud-native solver platforms with consumption-based revenue models. Watch for MIIT domestic CAE substitution policy shifts as inflection indicators for foreign vendor access patterns in China.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | PLM-simulation workflow unification meets EU AI Act audit trail mandates at Dassault and Siemens ecosystems. |
| Strategic Partnership | GPU manufacturer alliances with solver developers secure HPC capacity allocation for cloud-native deployments. |
| Geographic Expansion | Academic institution channel capture in Germany's Baden-Württemberg engineering corridor builds downstream enterprise pipelines. |
| Acquisition of Specialist Firm | Lattice Boltzmann CFD specialists add overnight aerodynamic iteration capability for Stuttgart automotive clusters. |
| Product Launch | Browser-delivered SaaS simulation lowers entry barriers for METI-subsidized Japanese mid-tier manufacturers. |
Methodological Framework
Direct dialogue with CTOs at aerospace manufacturers, IT procurement officers at automotive OEMs, platform engineers at cloud infrastructure providers, and academic licensing coordinators grounded qualitative insights for this analysis. Secondary validation drew from FAA certification filings, EASA safety directives, EU AI Act implementation guidance, MIIT GB standards documentation, and hyperscaler capex disclosures. Bottom-up solver deployment estimates triangulated against top-down software market sizing across the analysis window.
Segment-level projections across deployment architectures, solver methodologies, and end-use certification requirements fed into consolidated market estimates over the projection horizon. The analytical framework modeled consumption shifts from perpetual licenses to metered cloud hours, regulatory compliance cost pass-through, and AI-solver convergence adoption curves. CAGRs derived from elasticity-adjusted demand functions incorporating EU Green Deal validation mandates and domestic CAE substitution policy impacts.
The model holds under stable regulatory enforcement of FAA and EASA certification requirements; deviation in MIIT domestic software promotion intensity or EU AI Act audit trail interpretation would shift vendor access and pricing power distributions. Forecasts reflect documented assumptions about GPU cluster cost trajectories and cloud migration rates in defense-adjacent manufacturing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Design Collaboration Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Trading Software Market
Software & Services
Live Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
Business Productivity Software Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
B2B Gateway Software Market
Software & Services
Sales Training and Onboarding Software Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Interior Design Software Market
Software & Services
Global Remote Desktop Management Market
Software & Services
Global Digital Rights Management Software Market
Software & Services
Global Audit Software Market
Software & Services
Network Documentation Software Market