
 Global Building Information Modeling (BIM) Software Market | 2026-2036
Global Building Information Modeling (BIM) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Building Information Modeling (BIM) Software Market Foresight
Multi-source procurement of BIM platforms is rebalancing toward integrated suites that span design through operations. Autodesk Inc. anchors the design visualization layer with deep interoperability across construction phases. Bentley Systems Inc. specializes in heavy infrastructure workflows, sustaining its position through advanced parametric modeling for transportation and utilities.
Building Information Modeling software constitutes a digital representation technology that integrates 3D geometric data with temporal, cost, and performance attributes across a structure's lifecycle, typically employing Industry Foundation Classes for interoperability between applications. Its primary purpose is to enable clash detection, quantity takeoff, and asset handover from design teams to facility operators. Cloud-based solutions now lead technology adoption as engineering consultants and general contractors demand real-time model synchronization across distributed project sites. Design visualization commands the largest product type share, while facility management applications are expanding fastest as owners seek operational returns on digital twins.
The EU Green Deal and CE marking requirements are pressuring architectural firms to demonstrate embodied carbon calculations within BIM deliverables. The EPA's construction stormwater regulations and Japan's METI building energy standards are similarly embedding digital compliance documentation into tender requirements. Stakeholders must weigh vendor lock-in risks against the interoperability gains of openBIM standards as procurement cycles extend into decade-long enterprise agreements.
Market Dynamics
Cloud-based collaboration platforms are compressing procurement cycles and forcing legacy on-premise vendors to rearchitect delivery models around real-time synchronization across distributed project sites.
Growth Catalysts
- EU Green Deal mandates:Architectural firms across Germany, France, and Italy must now document embodied carbon calculations within BIM deliverables, expanding software functionality requirements.
- Heavy infrastructure digitization:Transportation authorities in Japan and the United States are embedding BIM compliance into tender specifications for bridges, tunnels, and utility networks.
- Digital twin convergence:Facility operators in commercial real estate are demanding operational-phase modules that extend model utility from construction handover through asset lifecycle management.
Market Restraints
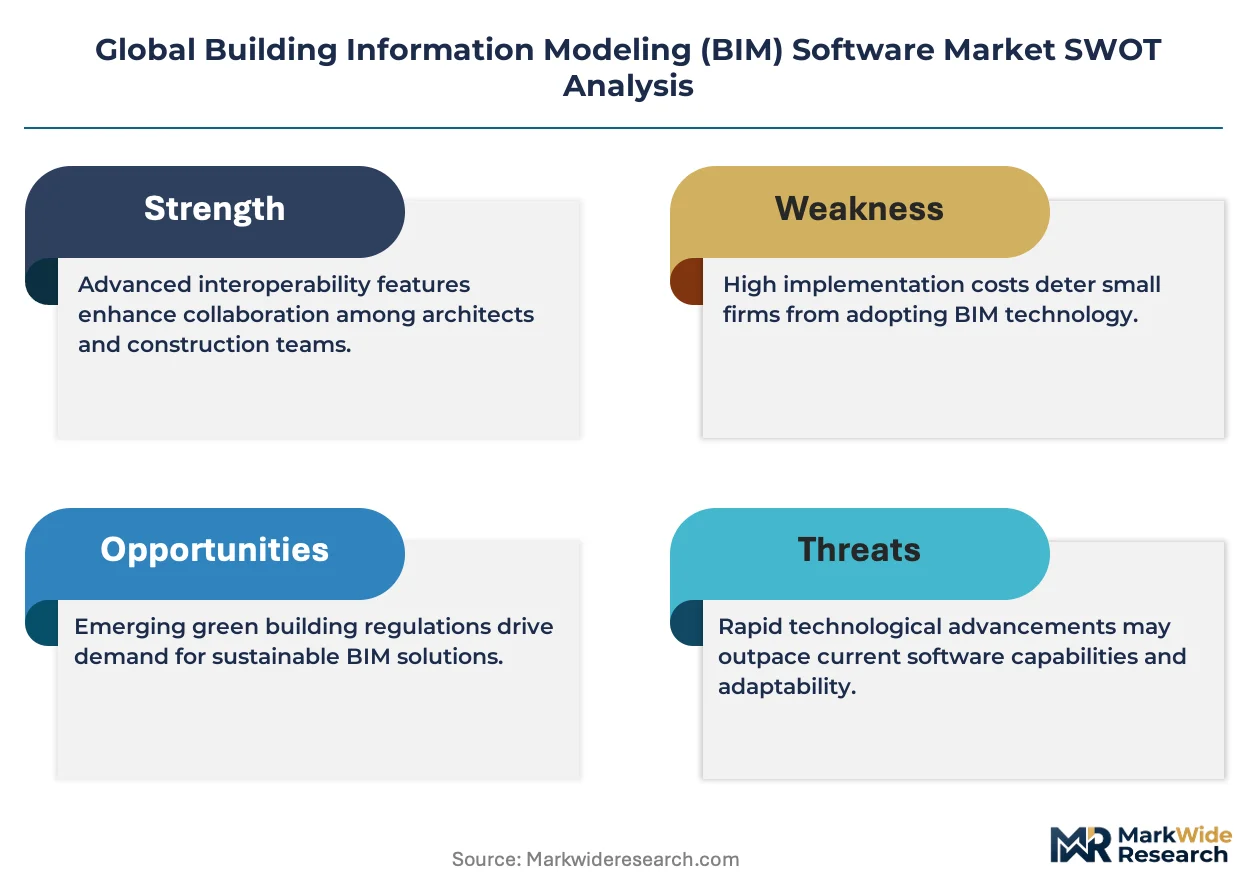
- Interoperability friction:Vendor-specific file formats create lock-in risks that deter multi-platform procurement despite openBIM standardization efforts.
- Skill scarcity:Qualified BIM managers command premium compensation in the United States and United Kingdom, inflating implementation costs for mid-tier engineering consultancies.
- Data sovereignty constraints:Cross-border cloud hosting restrictions in China and Russia fragment platform deployment architectures for multinational contractors.
Strategic Opportunities
- India infrastructure buildout:National highway and smart city programs lack mature BIM penetration, creating first-mover advantages for cloud-native platform providers.
- Operational-phase modules:Asset management integration represents underdeveloped white space as owners seek ROI on construction-phase digital investments.
- AI-assisted clash detection:Machine learning algorithms trained on historical project data are reducing manual model review cycles for structural and MEP coordination.
Industry Challenges
- Legacy system integration:ERP and CMMS connectivity requires custom API development that extends deployment timelines for owner-operators.
- Certification bottlenecks:ISO 19650 compliance auditing creates procurement delays as architectural practices validate internal processes against international standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Building Information Modeling (BIM) Software Market |
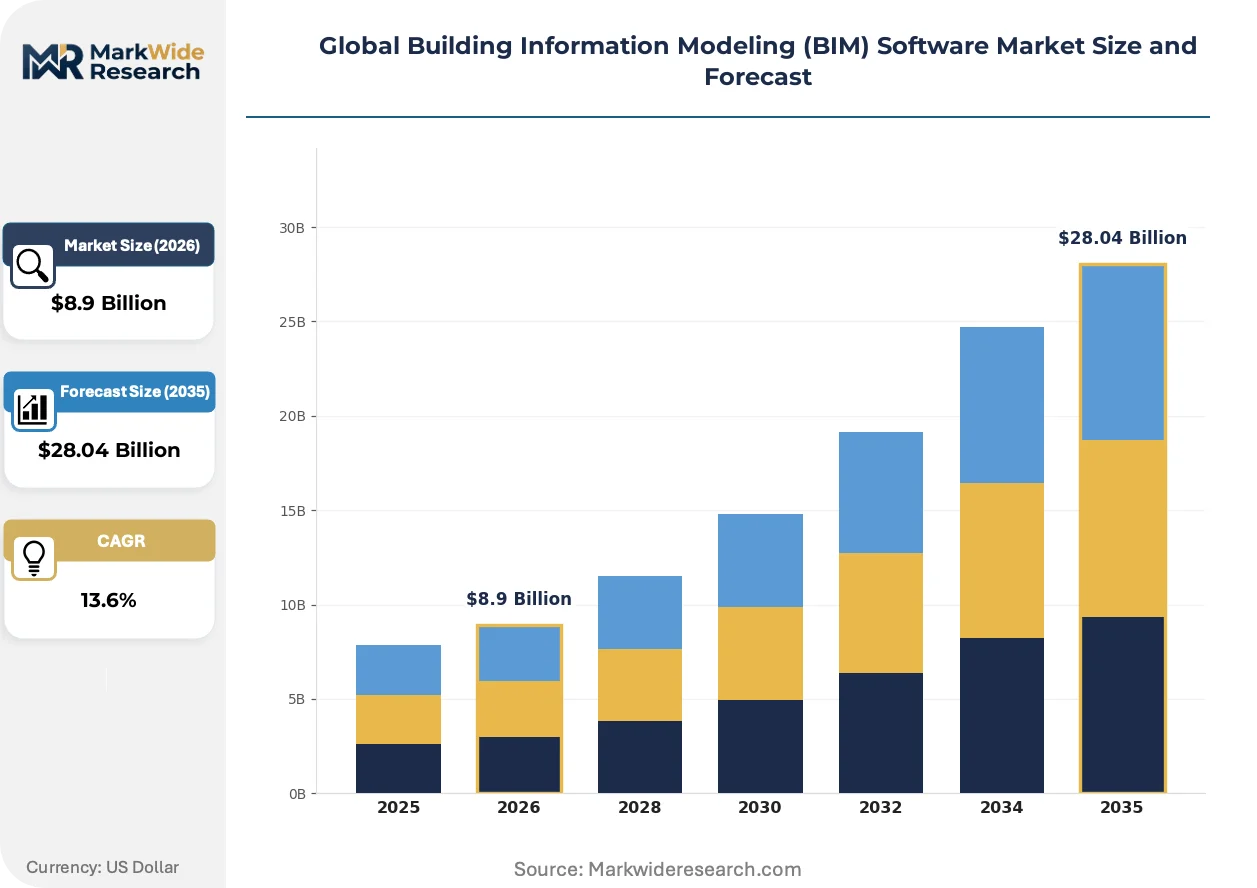
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $28.04 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design Visualization, Construction Scheduling, Facility Management, Cost Estimation, Structural Analysis Technology: Cloud-Based Solutions, Desktop Applications, Mobile Platforms, Collaborative Software, VR Integration Application: Commercial Structures, Institutional Projects, Infrastructure Development, Industrial Complexes, Cultural Sites End User: Architectural Firms, Engineering Consultants, Project Management Offices, General Contractors, Surveying Specialists |
| Companies Covered | Autodesk Inc., Nemetschek Group, Bentley Systems Inc., Trimble Inc., Dassault Systèmes SE, AVEVA Group Plc, Hexagon AB, Asite Solutions Ltd., Procore Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Building Information Modeling (BIM) Software Market Shifts & Advancements
Generative design algorithms and edge-computing deployment are restructuring how engineering teams allocate computational workloads across project phases.
Artificial intelligence is absorbing routine clash detection and quantity takeoff tasks previously executed by junior engineers. General contractors in the United States and Japan are deploying these tools on complex healthcare and airport projects. This capability compression is reallocating technical staff toward higher-value coordination and client-facing activities.
REACH chemical disclosure requirements and the EU AI Act are mandating algorithmic transparency for automated design recommendations used in public infrastructure. Engineering consultancies serving European markets must now document training data provenance and decision audit trails. Heavy civil projects in Germany and the Netherlands face the steepest compliance adjustments.
Subscription pricing for integrated design-to-operations suites is displacing perpetual licenses and modular point-solution procurement. Owner-operators in commercial real estate and healthcare verticals are consolidating vendor relationships under enterprise agreements spanning ten-plus years. This concentration is most pronounced in the United States, where facility management outsourcing firms negotiate portfolio-wide platform access.
Global Building Information Modeling (BIM) Software Market Segmentation
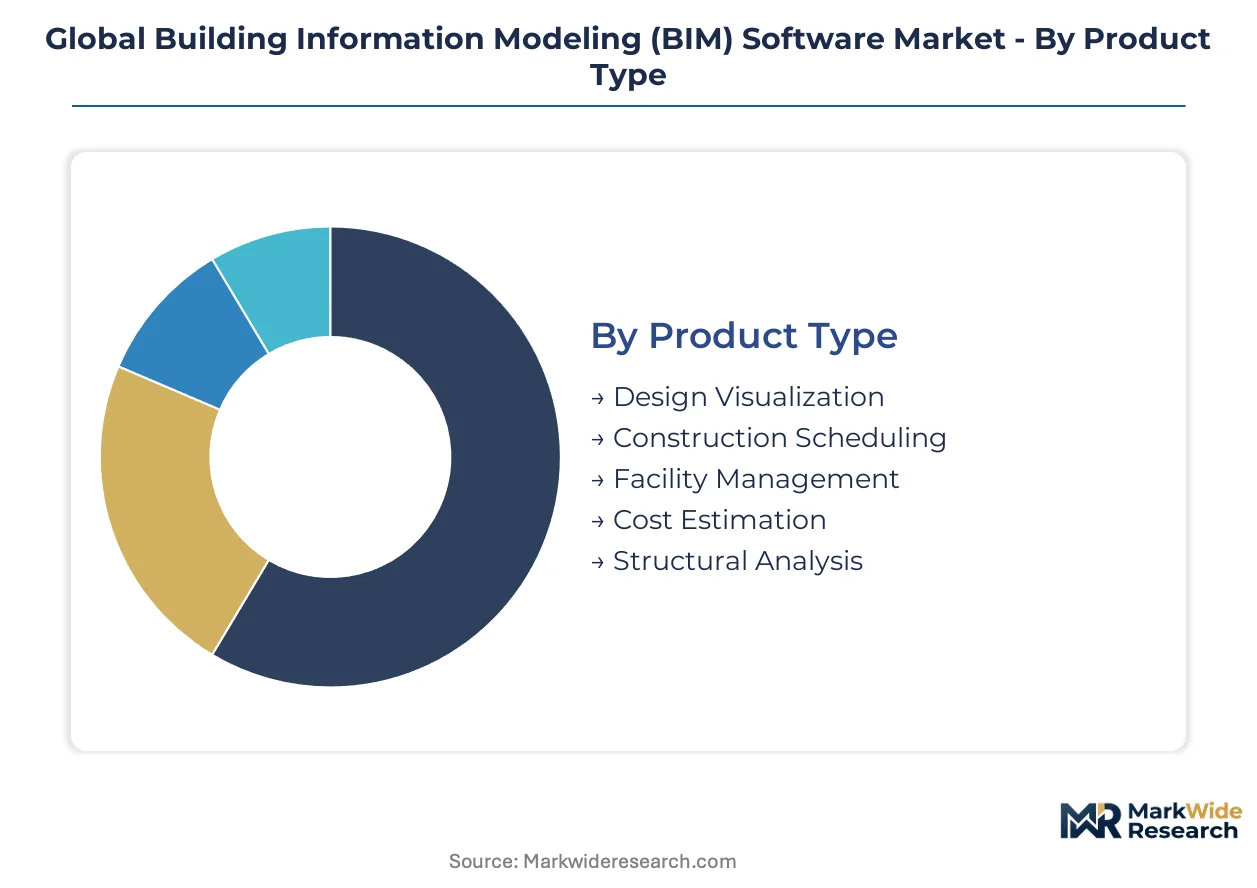
BIM software procurement fragments across technical layers, deployment modes, and professional workflows. Each segmentation axis reveals distinct vendor positioning strategies and buyer decision hierarchies that shape contract structures and platform loyalty.
Product Type:
Customization intensity varies sharply across this category, with visualization tools demanding heavy client-specific configuration while cost modules prioritize standardized calculation engines.
- Design Visualization:Geometric modeling engines integrate 3D parametric objects with rendering pipelines for architectural concept development. Demand concentrates among German and Japanese architectural studios facing EU Green Deal visualization requirements for embodied carbon disclosure.
- Construction Scheduling:4D simulation tools link geometric models to temporal task sequences for critical path optimization. United States general contractors on healthcare and airport projects drive procurement as FAA and OSHA compliance documentation requirements tighten.
- Facility Management:Operational-phase modules extend model utility into asset lifecycle tracking.
- Cost Estimation:Automated quantity takeoff engines reduce manual measurement cycles for quantity surveyors.
- Structural Analysis:Finite element calculation cores verify load-bearing performance against regional building codes.
Most installed capacity flows through Design Visualization. Expansion is steepest in Facility Management.
Technology:
Deployment architecture determines total cost of ownership, with cloud-native platforms commanding premium subscriptions against perpetual-licensed desktop alternatives.
- Cloud-Based Solutions:Real-time model synchronization across distributed project sites eliminates version control conflicts. Engineering consultants in the United States and Japan prioritize these platforms for multi-office coordination on complex infrastructure tenders.
- Desktop Applications:Local processing preserves computational independence for large-model manipulation. German engineering practices retain these for transportation authority projects with stringent data sovereignty requirements.
- Mobile Platforms:Field-accessible model viewers enable on-site clash detection and progress verification.
- Collaborative Software:Multi-stakeholder annotation and approval workflows streamline design review cycles.
- VR Integration:Immersive walkthrough environments support client presentation and constructability review.
Cloud-Based Solutions carry the heaviest transaction volume. Mobile Platforms are climbing the fastest as field deployment accelerates.
Application:
Project scale and regulatory exposure shape module selection, with infrastructure developers demanding specialized compliance documentation against commercial developers prioritizing speed-to-market.
- Commercial Structures:Office, retail, and hospitality projects emphasize leasable area optimization and tenant improvement flexibility. Facility management outsourcing firms in the United States consolidate procurement under decade-long enterprise agreements spanning portfolio-wide platform access.
- Infrastructure Development:Bridges, tunnels, and utility networks require geotechnical integration and environmental impact documentation. Japan's transportation authorities embed BIM compliance into tender specifications, accelerating platform adoption among domestic contractors.
- Institutional Projects:Healthcare and educational facilities demand infection control and occupancy safety modeling.
- Industrial Complexes:Manufacturing and process facilities integrate equipment specification databases with spatial coordination.
- Cultural Sites:Heritage preservation projects require as-built documentation and reversible intervention planning.
Commercial Structures dominate current deployment. Infrastructure Development shows the steepest expansion trajectory as government mandates proliferate.
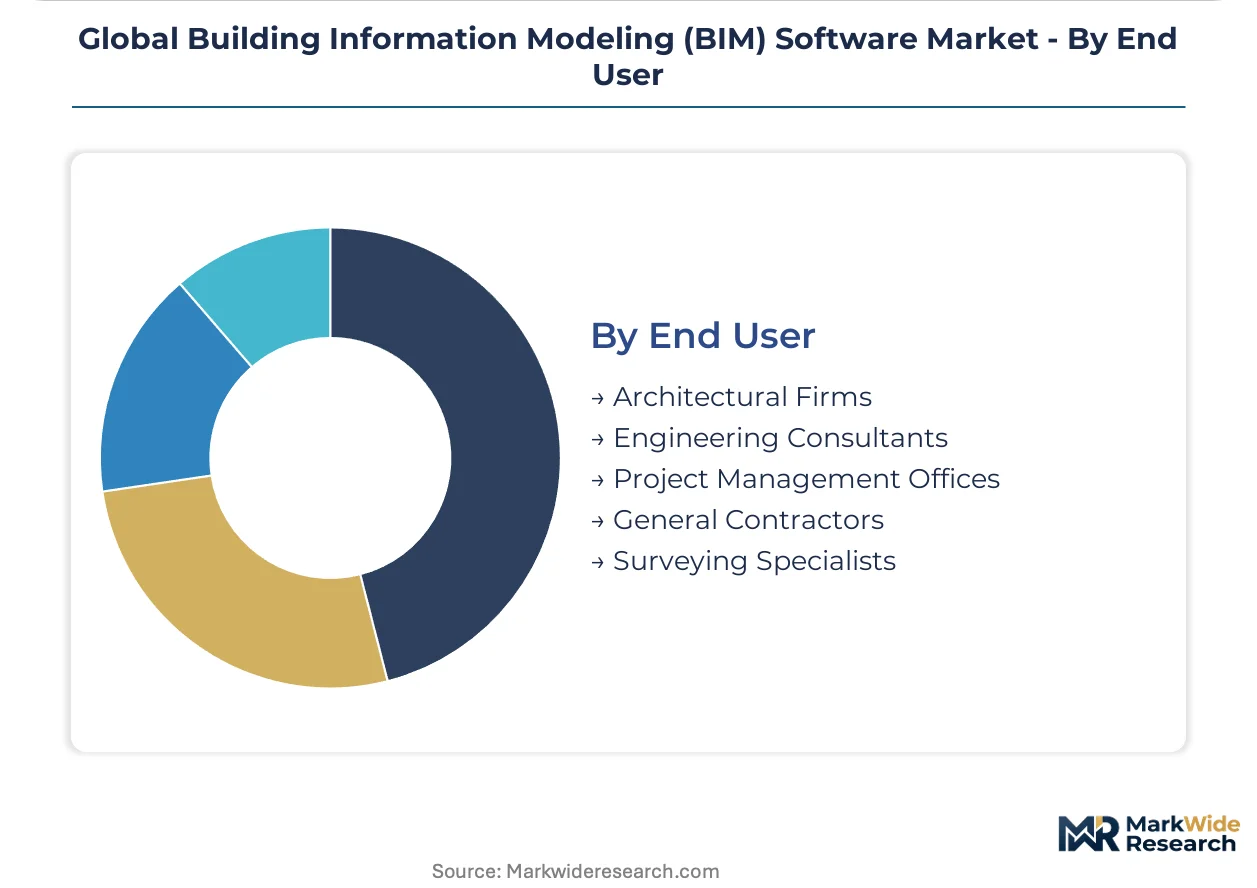
End User:
Professional liability profiles and fee structures determine software investment thresholds, with architects prioritizing visualization quality against contractors emphasizing clash detection throughput.
- Architectural Firms:Design authoring and presentation tools constitute core practice infrastructure. Practices across Germany, France, and Italy must now document embodied carbon calculations within BIM deliverables under EU Green Deal enforcement.
- General Contractors:Coordination and quantity takeoff modules drive field productivity and claim prevention. United States contractors deploy AI-assisted clash detection on complex healthcare projects to compress manual review cycles.
- Engineering Consultants:Structural, MEP, and civil analysis tools support technical submittal preparation.
- Project Management Offices:Schedule and cost integration platforms enable owner oversight of design and construction phases.
- Surveying Specialists:Point cloud processing and as-built verification tools support reality capture workflows.
Architectural Firms maintain the deepest installed base. General Contractors are gaining share fastest as construction-phase platform penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley technology corridors anchor North American BIM innovation pipelines, while German industrial clusters drive European standardization. Government procurement mandates in Japan and infrastructure buildouts in India reshape regional deployment trajectories across the forecast window.
United States
Healthcare and airport construction drives platform adoption among general contractors seeking FAA and OSHA compliance documentation. The EPA's construction stormwater regulations embed digital deliverables into federal infrastructure tenders. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate contractor procurement of cloud-based coordination platforms.
Germany
Transportation authorities mandate parametric modeling for bridge and tunnel projects, sustaining Bentley Systems' infrastructure specialization. EU Green Deal enforcement requires embodied carbon calculations within BIM deliverables from architectural practices. Munich and Stuttgart engineering clusters lead compliance integration for heavy civil workflows.
Japan
METI building energy standards accelerate operational-phase module adoption among facility operators seeking lifecycle returns. Transportation authorities embed BIM compliance into tender specifications for domestic contractors. Tokyo and Osaka metropolitan construction markets dominate cloud-based collaboration procurement decisions.
India
National highway and smart city programs create first-mover opportunities for cloud-native platform providers in underpenetrated markets. The central government's infrastructure push lacks mature BIM penetration across state-level procurement. Mumbai and Delhi-NCR construction corridors concentrate early pilot deployments among engineering consultancies.
United Kingdom
ISO 19650 compliance auditing creates procurement delays as architectural practices validate internal processes against international standards. Qualified BIM managers command premium compensation, inflating implementation costs for mid-tier engineering consultancies. London and Manchester design clusters concentrate certification-driven platform investments.
Global Building Information Modeling (BIM) Software Market Competitive Landscape
Global majors compete with regional champions across design-to-operations integration depth, with specialized infrastructure vendors defending niches against suite consolidation. The vendor base stratifies into three tiers: integrated platform providers spanning visualization through asset management, vertical specialists in heavy civil or industrial workflows, and point-solution vendors defending modular positions. Dominant competitive moves include decade-long enterprise agreement negotiations with facility management outsourcing firms and rearchitecting delivery models around real-time cloud synchronization.
Among integrated platform providers, Autodesk Inc. and Bentley Systems Inc. exemplify contrasting strategic archetypes. Autodesk anchors design visualization layers with deep interoperability across construction phases, while Bentley Systems occupies a specialized position in heavy infrastructure workflows through advanced parametric modeling capabilities. Nemetschek Group represents the European-centered alternative, sitting within a portfolio-based structure that addresses fragmented national procurement preferences across German-speaking markets.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Nemetschek Group |
| Bentley Systems Inc. |
| Trimble Inc. |
| Dassault Systèmes SE |
| AVEVA Group Plc |
| Hexagon AB |
| Asite Solutions Ltd. |
| Procore Technologies Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up facility management outsourcing firms in the United States have consolidated vendor relationships under decade-long enterprise agreements, compressing pricing flexibility for mid-tier engineering consultancies while concentrating procurement leverage among portfolio-scale buyers. This ownership pattern reinforces subscription-based pricing discipline across cloud-native platform providers and fragments negotiating power among standalone architectural practices.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and AI compute resources is intensifying margin pressure on SaaS-tiered subscription models across the BIM software stack. Three-tier pricing structure across premium, standard, and economy levels separates enterprise facility management outsourcing firms with portfolio-wide access from mid-tier engineering consultancies facing skill-scarcity-inflated implementation costs. Price differentiation hinges on ISO 19650 certification tier and customization depth for heavy infrastructure workflows. Cost compression in the standard tier runs through intensifying competition from cloud-native entrants, while architectural firms in Germany and France demonstrate highest price sensitivity due to EU Green Deal compliance cost absorption.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States healthcare and airport construction consortia, while value-added resellers serve fragmented mid-tier engineering consultancies across Germany and Japan. Development and delivery gravity centers on the United States, Germany, and Japan, with India emerging as a cloud-native deployment hub for underpenetrated infrastructure markets. Software supply draws from hyperscale cloud infrastructure providers, specialized geospatial data vendors, and finite-element calculation engine licensors. Single-source vulnerability in AI training data provenance creates exposure as the EU AI Act mandates algorithmic transparency for automated design recommendations. Distribution runs through vendor-direct enterprise agreements for owner-operators and channel partner networks for regional engineering practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BIM software market represents a late-cycle quality story as facility operators in commercial real estate and healthcare verticals shift procurement toward operational-phase modules with decade-long utility horizons. This demand migration favors vendors with integrated design-to-operations suites over point-solution specialists.
For Market Incumbents: Extend platform interoperability investments to defend against cloud-native entrants exploiting API-first architectures. Lock in facility management outsourcing firms through embedded AI-assisted clash detection modules that increase switching costs. Prioritize ISO 19650 certification tooling to accelerate architectural practice compliance auditing and compress competitor sales cycles. Vertical integration into geospatial data services reinforces positioning for heavy infrastructure tenders in Japan and Germany. For New Entrants and Emerging Players: Regional system integrators in India offer the most penetrable channel pathway for cloud-native platforms targeting national highway and smart city programs lacking mature BIM penetration. White space concentrates in operational-phase asset management modules for owner-operators seeking construction-phase digital investment returns. AI-assisted quantity takeoff tools for mid-tier United States general contractors provide a defensible beachhead against entrenched visualization incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among vertical specialists in heavy civil workflows with proprietary parametric modeling IP but limited cross-vertical expansion. Long-term viability across the analysis window depends on convergence toward integrated suites spanning design through operations. Acquisition targets should demonstrate ISO 19650 compliance tooling and existing channel relationships with transportation authorities. Watch facility management outsourcing firm RFP timing as the primary inflection signal for enterprise agreement renewal velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates design visualization through asset management under unified data architecture for facility operators. |
| AI Module Development | Absorbs routine clash detection tasks and reallocates engineering staff toward client-facing coordination activities. |
| ISO 19650 Certification Tooling | Accelerates architectural practice compliance auditing and compresses procurement delays in United Kingdom markets. |
| Geographic Expansion | Captures first-mover positioning in India's underpenetrated national highway and smart city procurement pipelines. |
| Strategic Partnership | Links cloud-native providers with regional system integrators for transportation authority tender compliance in Japan. |
Research Methodology
Multiple input streams — primary interviews with CTOs, IT procurement officers, and platform engineers; secondary validation against SEC filings, hyperscaler capex disclosures, and government tender databases; and trade data from customs records — were reconciled through bottom-up and top-down triangulation. Conversations with facility management outsourcing firms, engineering consultancy principals, and transportation authority procurement officers informed deployment architecture and compliance requirement assessments. Secondary sources included ISO 19650 certification body records, EU Green Deal implementation guidance, and METI building energy standard documentation.
Data-stream reconciliation across deployment model, organization size, vertical specialization, and regional adoption pattern dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic infrastructure investment trajectories. Forecast inputs incorporated cloud infrastructure cost curves, AI compute availability trends, and government mandate implementation timelines across Germany, Japan, and the United States.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cross-border data sovereignty enforcement in China and Russia, EU AI Act algorithmic transparency implementation stringency, and infrastructure budget volatility in India. Forecasts reflect assumptions around subscription pricing durability and interoperability standard adoption velocity. Periodic stress-testing of base assumptions is recommended against regulatory enforcement delays and cloud vendor consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Gamification Software Market
Software & Services
Global Auction Software Market
Software & Services
Global Intelligent Apps Market
Software & Services
Global Backup Restore Software Market
Software & Services
Global Integration Software Market
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Global Affiliate Software Market
Software & Services
Global Address Verification Software Market
Software & Services
Expense Management Software Market
Software & Services
Europe Human Resource (HR) Technology Market
Software & Services
Observability Platform Market
Software & Services
Time and Attendance Software Market
Software & Services
Email Optimization Software Market
Software & Services
Global MSP Software Market
Software & Services
Vehicle Embedded Software Market
Software & Services
Middle East and Africa Workforce Management Software Market