
 General Ledger Accounting Software Market | 2026-2036
General Ledger Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
General Ledger Accounting Software Market Analysis
Mid-market enterprises is unwinding the dominance of large-corporate procurement in general ledger software selection, as finance teams at smaller firms now demand enterprise-grade automation without IT overhead. Oracle NetSuite leverages its unified ERP-to-ledger architecture to capture this migration wave. Sage Intacct anchors its position through deep multi-entity consolidation capabilities that appeal to growing franchise and distributed-business models. SAP S/4HANA competes by extending in-memory ledger processing to real-time close scenarios for complex multinational structures.
General ledger accounting software comprises the core financial record-keeping module within enterprise accounting systems, enforcing double-entry bookkeeping protocols, supporting multi-currency transaction normalization, and maintaining immutable audit trails through automated journal entry workflows and period-end reconciliation engines. Its primary commercial purpose is to deliver accurate, real-time financial position data to stakeholders while ensuring compliance with statutory reporting and tax obligations. Cloud-based deployments now lead new installations among small businesses and enterprises alike, while SaaS delivery captures the fastest expansion as vendors shift from perpetual licenses to recurring revenue models. On-premise installations retain margin concentration in highly regulated sectors where data sovereignty requirements override cost considerations.
The EU AI Act and GDPR impose algorithmic transparency and data localization obligations on cloud-hosted ledger platforms processing European financial data, compelling vendors to architect region-specific instance isolation. In the United States, SEC disclosure rules and IRS electronic filing mandates drive demand for audit-ready general ledger outputs with embedded supporting documentation. Stakeholders must monitor how divergent cross-border compliance frameworks reshape vendor roadmaps and customer switching costs across jurisdictions.
Market Dynamics
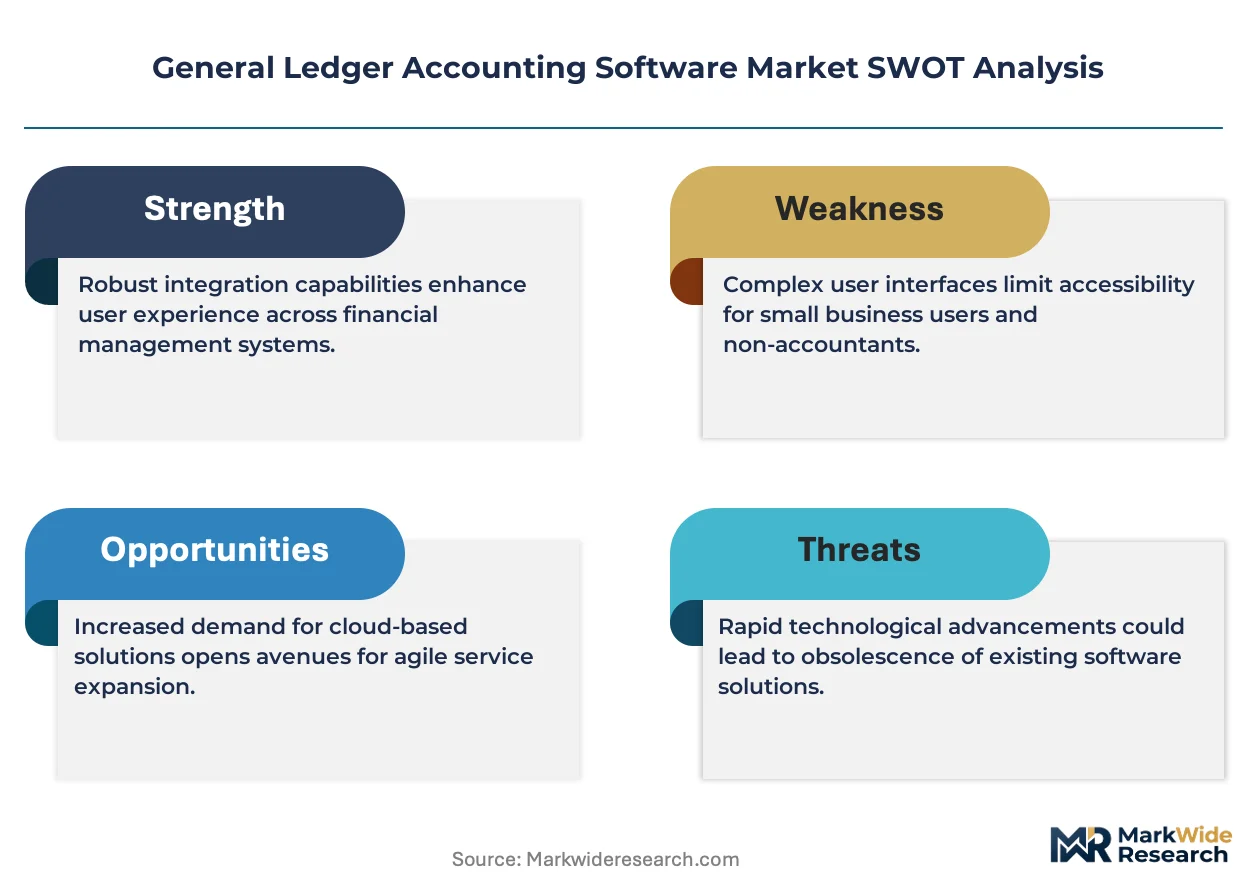
Mid-market finance teams are accelerating migration from spreadsheets to automated ledger systems as cloud delivery models collapse the cost barrier to enterprise-grade functionality. This structural shift is compressing vendor sales cycles and expanding addressable market boundaries.
Growth Catalysts
- IRS electronic filing mandates:US tax infrastructure modernization forces audit-ready digital trails, driving replacement demand for legacy on-premise systems.
- Multi-entity consolidation automation:Franchise and distributed business models require real-time consolidation across jurisdictions without IT overhead.
- India's digital audit trail mandates:The country's tax reporting infrastructure overhaul compels mid-market enterprises to abandon manual bookkeeping.
Market Restraints
- GDPR data localization costs:EU financial data residency rules force vendors to maintain region-specific cloud instances, inflating operational overhead.
- Legacy system integration friction:Technical debt in established ERP environments creates switching costs that delay SaaS migration timelines.
- Cyber insurance premium escalation:Cloud-hosted ledger platforms face rising input costs as underwriters tighten coverage terms for financial data breaches.
Strategic Opportunities
- Germany's CSRD reporting requirements:Sustainability disclosure mandates create white space for ledger platforms with embedded ESG data capture.
- Embedded AI reconciliation engines:Machine learning convergence with automated journal workflows promises to compress month-end close cycles.
- Partner channel expansion:Accounting firm networks emerge as preferred distribution path for mid-market customer acquisition.
Industry Challenges
- Certified public accountant talent scarcity:Vendors struggle to hire sufficient accounting domain experts for product development and customer success functions.
- API standardization delays:Fragmented bank connectivity protocols force costly bespoke integrations for multi-currency transaction normalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | General Ledger Accounting Software Market |
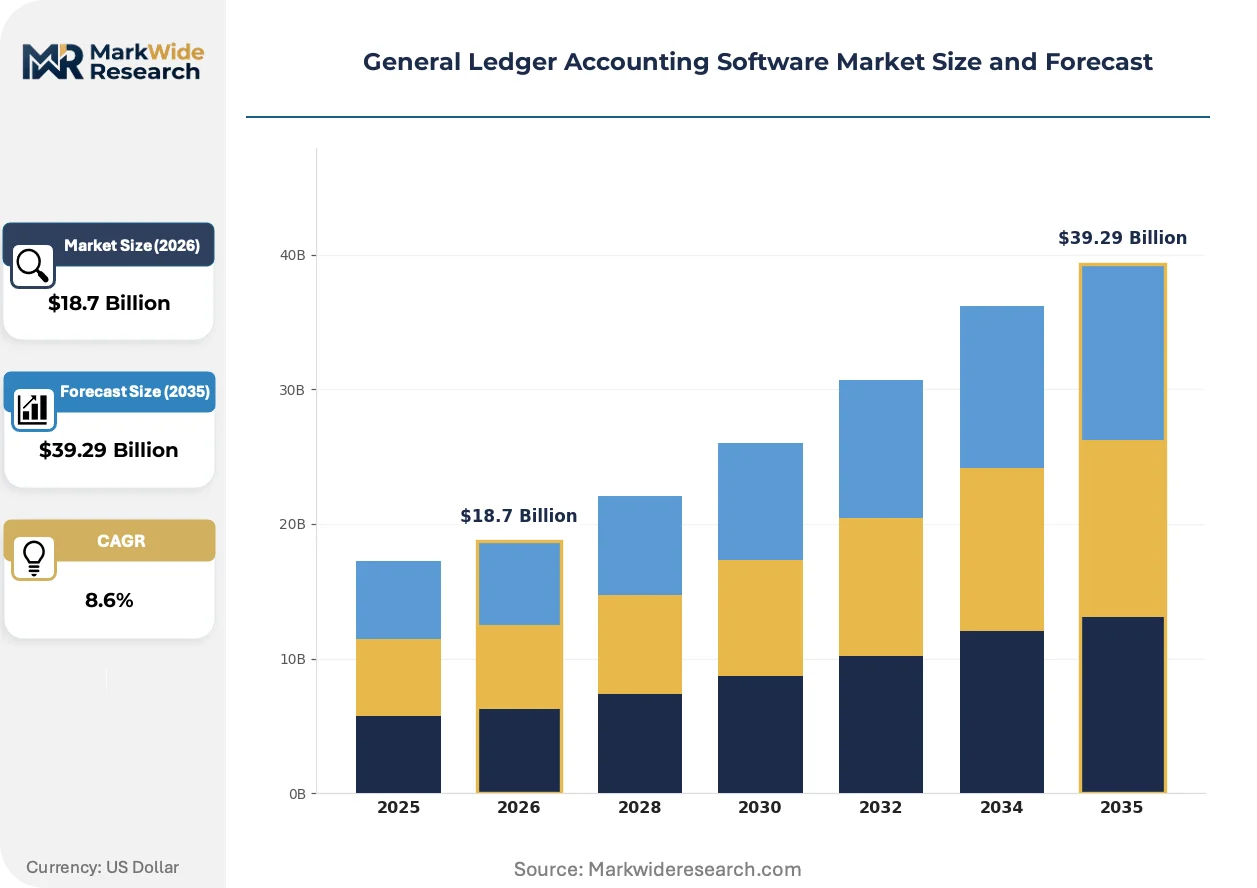
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, SaaS End User: Small Businesses, Enterprises, Startups, Non-Profits Deployment: Single-Tenant, Multi-Tenant, Private Cloud, Public Cloud Integration Level: API, Middleware, Direct Integration, Manual |
| Companies Covered | Xero, Workday Financial Management, Oracle NetSuite, QuickBooks Online, FundCount, Sage Intacct, SAP S/4HANA, Osfin, Microsoft Dynamics 365 Finance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
General Ledger Accounting Software Market Emerging Trajectories
Real-time financial close capabilities and embedded compliance automation are redefining competitive differentiation in ledger software. Vendors race to compress reconciliation cycles while embedding jurisdiction-specific regulatory logic.
Continuous close technology is bifurcating the market between batch-processed legacy architectures and event-driven ledger systems. Mid-market enterprises adopt in-memory processing to eliminate period-end bottlenecks. This capability compression is forcing incumbents to rebuild core engines or cede premium positioning.
The EU AI Act imposes algorithmic transparency obligations on automated reconciliation and anomaly detection features. Vendors must document decision pathways for AI-generated journal entries. European financial services firms now prioritize vendors with explainable AI architectures over black-box alternatives.
Subscription pricing models displace perpetual licenses across all buyer segments. Finance leaders prefer operational expenditure treatment and bundled upgrade paths. This preference shift is most visible in US mid-market procurement, where three-year SaaS commitments now dominate RFP evaluation criteria.
General Ledger Accounting Software Market Segmentation
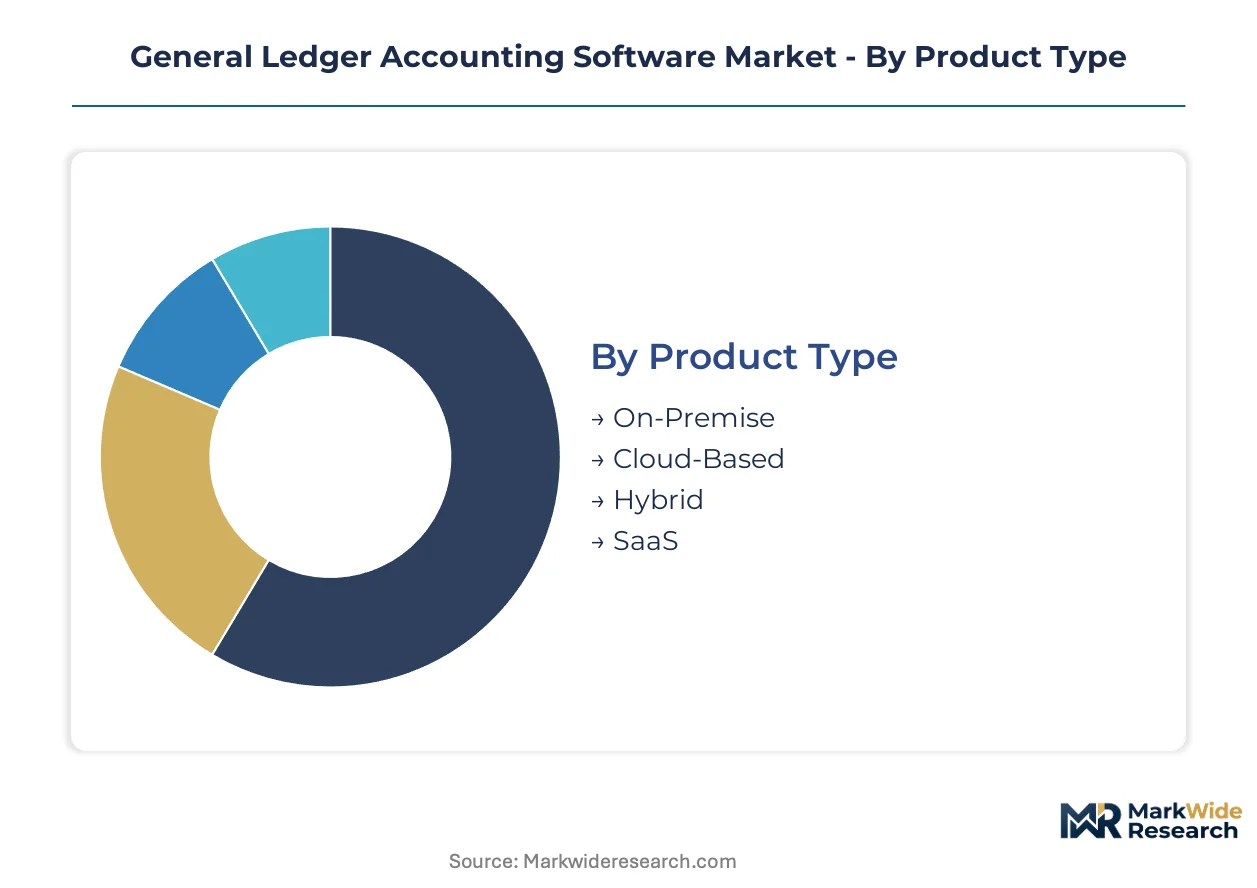
General ledger software purchasing splits sharply across technical architecture and organizational scale, with deployment choices now carrying compliance consequences under divergent national data regimes. Vendors must architect segment-specific roadmaps that reconcile functional requirements against jurisdictional constraints.
Product Type:
GDPR and the EU AI Act impose divergent certification burdens on each technical architecture, reshaping vendor investment priorities and customer eligibility across European markets.
- On-Premise:Licensed software installed within customer-controlled data centers maintains immutable audit trails through localized hardware governance. German financial services firms and Indian public sector entities favor this architecture to satisfy RBI data localization directives and BIS cybersecurity standards without third-party cloud dependency.
- Cloud-Based:Fully managed infrastructure delivered via browser access collapses IT overhead for mid-market finance teams while embedding automatic compliance updates. United States healthcare providers select this model to streamline HIPAA technical safeguard implementation through vendor-assumed security responsibilities.
- Hybrid:Split architectures segregate sensitive transaction data on-premise while routing non-critical workflows to cloud instances. French manufacturing conglomerates deploy hybrid configurations to satisfy CNIL data residency requirements for payroll records without sacrificing operational agility.
- SaaS:Subscription-delivered functionality with continuous feature deployment eliminates version fragmentation and accelerates regulatory adaptation. Indian startups and United States mid-market enterprises gravitate toward SaaS pricing to preserve capital for core business investment.
Established volume favors On-Premise; emerging adoption favors SaaS.
End User:
Organizational scale determines feature complexity thresholds, with procurement authority increasingly decentralizing below enterprise tier.
- Small Businesses:Owner-operated finance functions demand pre-configured chart-of-accounts templates and automated bank reconciliation without implementation consulting. India's GST-registered micro-enterprises drive replacement of Tally-ledger hybrids with cloud-native alternatives.
- Enterprises:Multi-entity consolidation, intercompany elimination, and currency translation engines support complex organizational structures. German automotive suppliers and United States pharmaceutical distributors require these capabilities to manage hundreds of legal entities under CSRD and SEC disclosure mandates.
- Startups:Venture-backed companies prioritize scalable seat pricing and rapid internationalization support over deep functionality. Y Combinator portfolio companies in the United States and Bengaluru technology clusters represent concentrated demand for startup-optimized ledger configurations.
- Non-Profits:Fund accounting, grant compliance tracking, and donor restriction management differentiate requirements from commercial counterparts. United States 501(c)(3) organizations and German gemeinnützige entities constitute stable demand for purpose-built nonprofit modules.
Revenue concentration sits with Enterprises; steepest expansion trajectory belongs to Small Businesses.
Deployment:
Isolation architecture directly determines data sovereignty compliance scope and operational cost structure.
- Single-Tenant:Dedicated infrastructure instances prevent data commingling across customers, satisfying stringent regulatory audit requirements. United States defense contractors and German critical infrastructure operators mandate single-tenant deployments to meet contractual security classification obligations.
- Multi-Tenant:Shared resource pools maximize vendor economies of scale and minimize customer subscription pricing. Indian mid-market enterprises and United States professional services firms accept multi-tenant architectures where data residency rules permit.
- Private Cloud:Customer-exclusive cloud infrastructure operated by vendor or third party splits operational burden with controlled environment isolation. French banking subsidiaries and United States hospital systems deploy private cloud to reconcile HIPAA and GDPR concurrent obligations.
- Public Cloud:Hyperscaler-hosted instances deliver elastic capacity and geographic redundancy without infrastructure ownership. German software scale-ups and Indian e-commerce platforms leverage public cloud for rapid market entry with minimal capital deployment.
Margin optimization favors Multi-Tenant; compliance-sensitive procurement favors Single-Tenant.
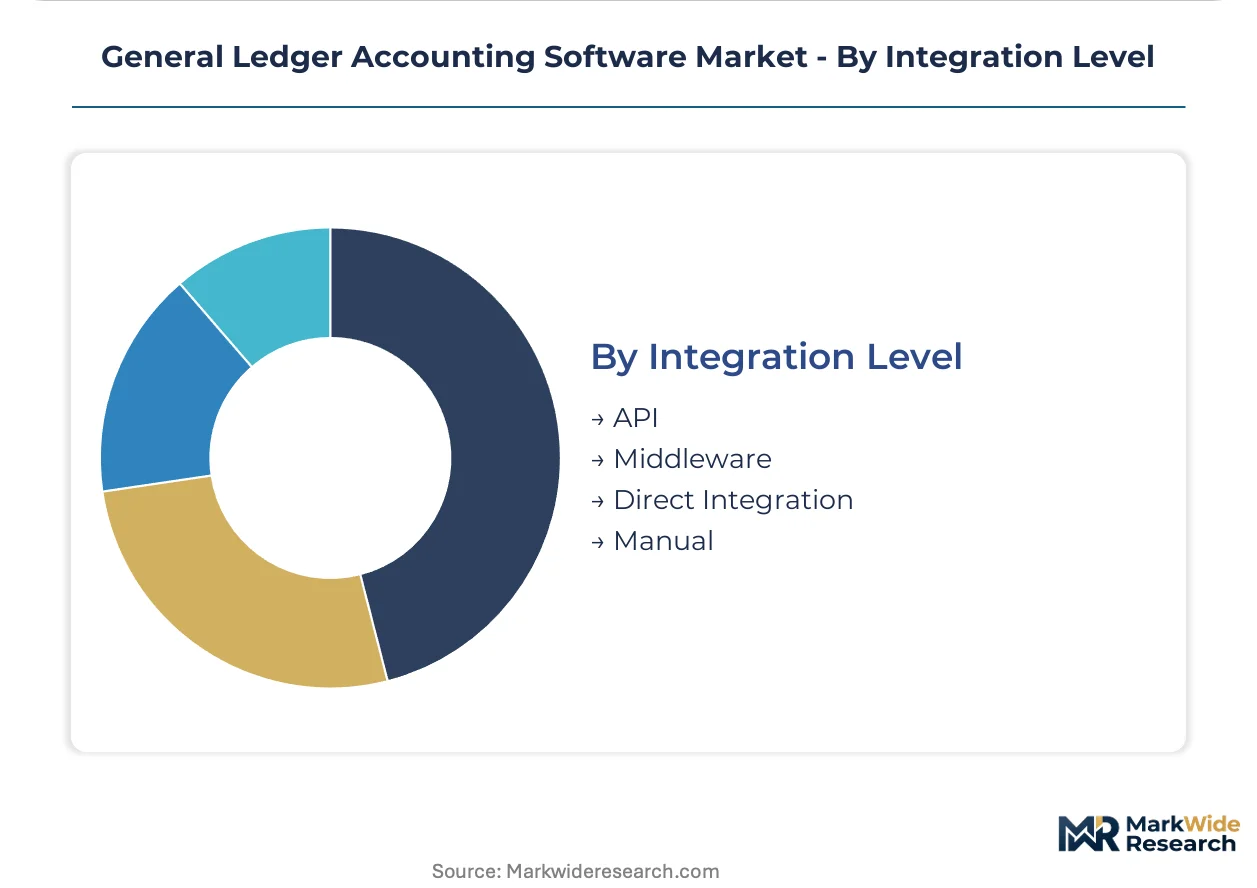
Integration Level:
Connectivity architecture determines implementation timeline and ongoing maintenance burden across heterogeneous system landscapes.
- API:REST and GraphQL interfaces enable real-time data exchange with banking, payroll, and CRM systems without middleware dependency. United States fintech-enabled enterprises and German Industry 4.0 manufacturers prioritize native API connectivity for event-driven financial workflows.
- Middleware:Integration platform layers translate between legacy protocol formats and modern ledger requirements. Indian conglomerates with decades of ERP accumulation deploy middleware to preserve existing SAP and Oracle investments during cloud migration.
- Direct Integration:Pre-built connectors to specific vendor ecosystems eliminate custom development for standardized technology stacks. United States NetSuite and Sage Intacct customer bases leverage direct integration for rapid subsidiary onboarding.
- Manual:File-based import and spreadsheet upload persist in transitional environments and severely resource-constrained settings. Indian micro-enterprises below GST registration thresholds and United States early-stage nonprofits occasionally accept manual workflows pending automation investment.
Implementation velocity favors API; legacy system preservation favors Middleware.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' IRS electronic filing infrastructure anchors transatlantic ledger modernization, while India's digital audit trail mandates and Germany's CSRD disclosure rules create parallel upgrade cycles across three distinct regulatory time zones.
United States
Healthcare providers and defense contractors drive single-tenant procurement to satisfy HIPAA technical safeguards and contractual security classifications. SEC disclosure rules and IRS electronic filing mandates compel audit-ready digital trails with embedded supporting documentation. Silicon Valley fintech clusters and Boston healthcare corridors concentrate SaaS migration demand among mid-market enterprises.
Germany
Automotive suppliers and critical infrastructure operators favor on-premise architectures to satisfy BIS cybersecurity standards without third-party cloud dependency. CSRD sustainability disclosure mandates create white space for ledger platforms with embedded ESG data capture. Bavarian manufacturing conglomerates and Frankfurt financial services hubs deploy hybrid configurations to reconcile CNIL-aligned data residency with operational agility.
India
GST-registered micro-enterprises and mid-market enterprises abandon Tally-ledger hybrids for cloud-native alternatives under digital audit trail mandates. RBI data localization directives and SEBI compliance requirements shape vendor certification priorities. Bengaluru technology clusters and Mumbai financial districts anchor startup-optimized ledger configurations for venture-backed companies.
United Kingdom
Professional services firms and fintech-enabled enterprises prioritize API connectivity for event-driven financial workflows. GDPR algorithmic transparency obligations influence vendor selection for automated reconciliation features. London financial services corridors and Manchester industrial clusters represent concentrated demand for multi-entity consolidation capabilities.
France
Banking subsidiaries and manufacturing conglomerates deploy private cloud to reconcile HIPAA-concurrent obligations with CNIL data residency requirements. EU AI Act documentation mandates for AI-generated journal entries reshape procurement evaluation criteria. Paris financial districts and Lyon industrial basins anchor hybrid architecture adoption for payroll record isolation.
General Ledger Accounting Software Market Vendor Landscape
Concentration sits with cloud-native specialists and legacy ERP incumbents competing for mid-market migration waves. The vendor base splits between unified ERP-to-ledger architectures and standalone financial automation platforms. Three archetypes dominate: unified suite providers, best-of-breed cloud specialists, and legacy on-premise incumbents. M&A activity and partner channel expansion constitute the dominant competitive moves as vendors race to capture accounting firm distribution networks.
Among unified suite providers, Oracle NetSuite and SAP S/4HANA exemplify contrasting approaches to real-time close capabilities and multi-entity consolidation. Sage Intacct occupies a position within the best-of-breed tier, anchoring specialist positioning through deep franchise and distributed-business functionality. These three represent divergent strategic bets on whether mid-market procurement favors integrated suites or specialized financial automation.
| Leading Market Players |
|---|
| Xero |
| Workday Financial Management |
| Oracle NetSuite |
| QuickBooks Online |
| FundCount |
| Sage Intacct |
| SAP S/4HANA |
| Osfin |
| Microsoft Dynamics 365 Finance |
| Others |
Supply Flow & Price Mechanics
Three-year SaaS commitments with bundled upgrade paths lock in both supply access and price visibility for mid-market finance teams migrating from perpetual licenses. This contract structure collapses vendor sales cycles while embedding automatic compliance updates that protect against regulatory-driven cost surprises.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise, mid-market, and small-business seat thresholds. Pricing pressure stems from cyber insurance premium escalation as underwriters tighten coverage terms for cloud-hosted financial data breaches. Small businesses exhibit highest price sensitivity due to capital constraints, while defense contractors and German critical infrastructure operators accept premium single-tenant pricing to satisfy contractual security classifications. Certification grade differentiation separates SOC 2 Type II vendors from standard-tier alternatives.
Supply Chain Analysis
Implementation lead times stretch from six weeks for API-native configurations to eighteen months for complex middleware deployments preserving legacy ERP investments. Engineering talent concentrates in the United States, Germany, and India where Bengaluru technology clusters and Silicon Valley fintech hubs anchor development capacity. Cloud infrastructure draws from hyperscaler networks in the United States and European Union, with data residency requirements forcing region-specific instance provisioning. Single-source vulnerability sits with certified public accountant talent scarcity constraining vendor product development velocity. Distribution runs through accounting firm partner channels emerging as preferred mid-market acquisition paths.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vendors face substitution pressure from embedded finance platforms and vertical SaaS providers integrating ledger functionality as a loss-leader feature, requiring active defense of core financial automation positioning.
For Market Incumbents: Consolidate partner channel control by exclusive accounting firm distribution agreements that lock out emerging competitors. Deepen API standardization investments to reduce bespoke integration costs that delay customer switching. Vertical integration into embedded AI reconciliation engines addresses talent scarcity while compressing month-end close cycles that drive renewal decisions.
For New Entrants and Emerging Players: Lead with India GST-registered micro-enterprises as the most penetrable segment where Tally-ledger hybrid abandonment creates immediate replacement demand. Target German CSRD sustainability disclosure mandates as regulatory white space where ESG data capture functionality remains underserved. Go-to-market through regional system integrators accelerates credibility establishment without direct incumbent confrontation.
For Investors and Strategic Acquirers: Cloud-native specialists with multi-entity consolidation depth represent the priority acquisition archetype as franchise and distributed-business models expand. Long-term viability hinges on continuous close technology differentiation displacing batch-processed legacy architectures. Watch for API standardization breakthroughs at major banking consortia as inflection signals reducing integration friction and accelerating SaaS migration timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded AI Reconciliation Engine Development | Machine learning convergence with journal workflows compresses month-end close cycles for competitive differentiation. |
| Partner Channel Expansion | Accounting firm networks emerge as preferred distribution path capturing mid-market customer acquisition efficiency. |
| Regional Cloud Instance Provisioning | GDPR and RBI data localization directives force infrastructure investment satisfying jurisdictional compliance obligations. |
| API Standardization Investment | REST and GraphQL native connectivity reduces implementation timelines against fragmented bank protocol environments. |
| ESG Data Capture Module Launch | CSRD sustainability disclosure mandates create white space for ledger platforms embedding environmental reporting functionality. |
Methodological Framework
A standing panel of CFOs, IT procurement officers, accounting firm partners, and cloud platform engineers provided ongoing calibration combining primary interviews with secondary validation. SEC filings, IRS electronic filing mandate documentation, EU AI Act regulatory texts, and vendor SaaS pricing disclosures anchored bottom-up triangulation against top-down market sizing.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures and accounting software vendor revenue segmentations across the analysis window. Segmentation dimensions modeled deployment architecture, organization scale, integration complexity, and regional adoption pattern. CAGRs derived from trend extrapolation of IRS mandate compliance deadlines and India's digital audit trail enforcement timelines.
Forecasts assume regulatory continuity in SEC disclosure rules, GDPR data residency requirements, and RBI localization directives; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Home Design Software Market
Software & Services
Cloud-Based Dental Practice Management Software Market
Software & Services
Business Rules Management System Market
Software & Services
Global UIUX Software Market
Software & Services
Germany HR Payroll Software Market
Software & Services
Radio Propagation Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Automotive Dealer Management Systems (DMS) Market
Software & Services
Movie Editing Software Market
Software & Services
Global Handyman Software Market
Software & Services
ELD Compliance Software Market
Software & Services
Workshop Management Software Market
Software & Services
Generative Design Software Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Data Compression Software Market
Software & Services
Global Rapid Application Development Market