
 Global User Interface Service Market | 2026-2036
Global User Interface Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global User Interface Service Market Foresight
Multi-sourced UI design partnerships is expanding as enterprises abandon captive in-house studios for specialized external vendors. Adobe Inc. leverages its Creative Cloud ecosystem to anchor enterprise creative workflows. Accenture competes through its embedded systems integration practice across telecommunications clients. Figma differentiates via real-time collaborative prototyping that displaces legacy desktop tools.
User interface services encompass the design, engineering, and optimization of human-machine interaction layers across digital touchpoints, spanning wireframing, visual design systems, interaction mapping, and accessibility compliance to WCAG 2.1 AA thresholds. These services reduce cognitive load, accelerate task completion, and standardize brand consistency across software environments. Consulting services command premium pricing due to strategic advisory bundling, while cloud-based deployment captures the fastest expansion as organizations retire on-premise design infrastructure. Embedded systems application lags in maturity but offers concentrated margin pools in automotive and industrial IoT verticals where safety-critical HMI standards apply.
The EU AI Act and GDPR impose algorithmic transparency and consent-layer design mandates that elevate compliance-oriented UI service contracts. The U.S. FCC accessibility guidelines and Section 508 standards expand federal procurement requirements for inclusive design verification. Japan's METI pushes human-centric interface guidelines through JIS standards that shape export-bound product specifications. Stakeholders must monitor regulatory divergence between privacy-first European frameworks and U.S. sector-specific mandates when structuring cross-border service delivery models.
Market Dynamics
Enterprise abandonment of captive design studios in favor of specialized external vendors is restructuring competitive positioning across the user interface service landscape. Financial services firms are accelerating this shift as regulatory complexity demands specialized compliance expertise that in-house teams cannot sustain.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency and consent-layer design requirements are elevating contract values for compliance-oriented UI services across European enterprise procurement.
- Automotive HMI safety standards:Safety-critical interface specifications in embedded systems are creating concentrated margin pools as tier-1 suppliers outsource verification-heavy design work.
- Cloud-based design infrastructure retirement:Organizations are eliminating on-premise creative servers, accelerating subscription-based service adoption and recurring revenue models for vendors.
Market Restraints
- Specialized talent scarcity:WCAG 2.1 AA accessibility certification requirements are narrowing the qualified labor pool, inflating wage costs for certified interaction designers.
- Cross-border regulatory friction:Divergence between GDPR consent-layer specifications and U.S. sector-specific accessibility guidelines is fragmenting service delivery architectures.
- Legacy tool lock-in:Desktop-based prototyping software with deep workflow integration creates switching costs that delay cloud-native platform migration.
Strategic Opportunities
- India's enterprise software expansion:Domestic IT services giants are building captive UI centers to serve export markets, creating partnership openings for specialized design consultancies.
- Industrial IoT interface convergence:Machine-control visualization and predictive maintenance dashboards are merging, requiring hybrid skill sets that incumbent automation vendors lack.
- Japan's METI human-centric guidelines:JIS standards for elderly-accessible interfaces are shaping export-bound product specifications, mandating design verification services for market entry.
Industry Challenges
- Accessibility certification bottlenecks:Third-party WCAG 2.1 AA verification timelines are extending delivery schedules, compressing project margins on fixed-price contracts.
- Multi-stakeholder alignment complexity:Design system governance across distributed product teams requires organizational change management capabilities that pure-play studios rarely possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global User Interface Service Market |
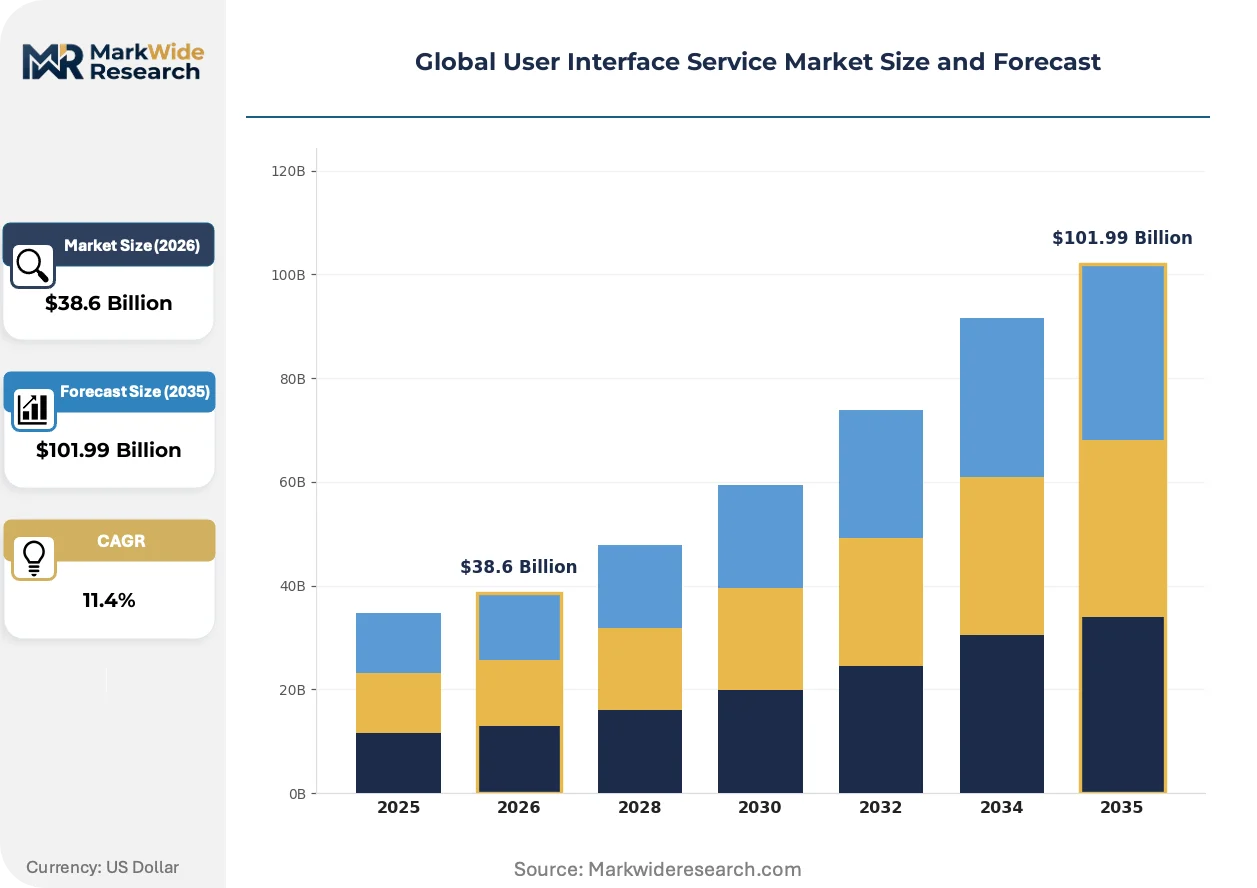
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Integration, Customization, Maintenance Application: Enterprise Software, Mobile Devices, Web Portals, Embedded Systems End User: Financial Firms, Telecommunications Providers, Government Agencies, Educational Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Adobe Inc., Figma, Accenture, Microsoft Corporation, Google LLC, InVision, Sketch, PwC, IDEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global User Interface Service Market Shifts & Advancements
Real-time collaborative environments are absorbing functionality from legacy desktop tools, compressing the vendor landscape around platform-centric ecosystems. This technological pivot is reshaping how design assets are created, versioned, and deployed across enterprise workflows.
Generative design algorithms are absorbing repetitive layout and component-generation tasks previously executed by junior interface designers. Mid-market SaaS vendors are adopting these tools fastest, reducing headcount ratios on standard dashboard projects. The structural consequence is margin compression for body-shop staffing models while premium advisory services retain pricing power.
The EU AI Act's algorithmic transparency mandates are forcing explanatory interface layers into previously opaque recommendation systems. Industrial consequence includes mandatory human-in-the-loop checkpoints and audit-trail visualization requirements. Financial services applications in Germany face the steepest compliance burden, driving demand for specialized legal-design hybrid consultancies.
Enterprise buying committees are consolidating vendor relationships around integrated design-to-development platforms, displacing point-solution procurement. Systems integrators and creative agencies are responding through capability acquisitions and partnership restructuring. This pattern is most visible in U.S. telecommunications and healthcare IT verticals where procurement centralization has advanced furthest.
Global User Interface Service Market Segmentation
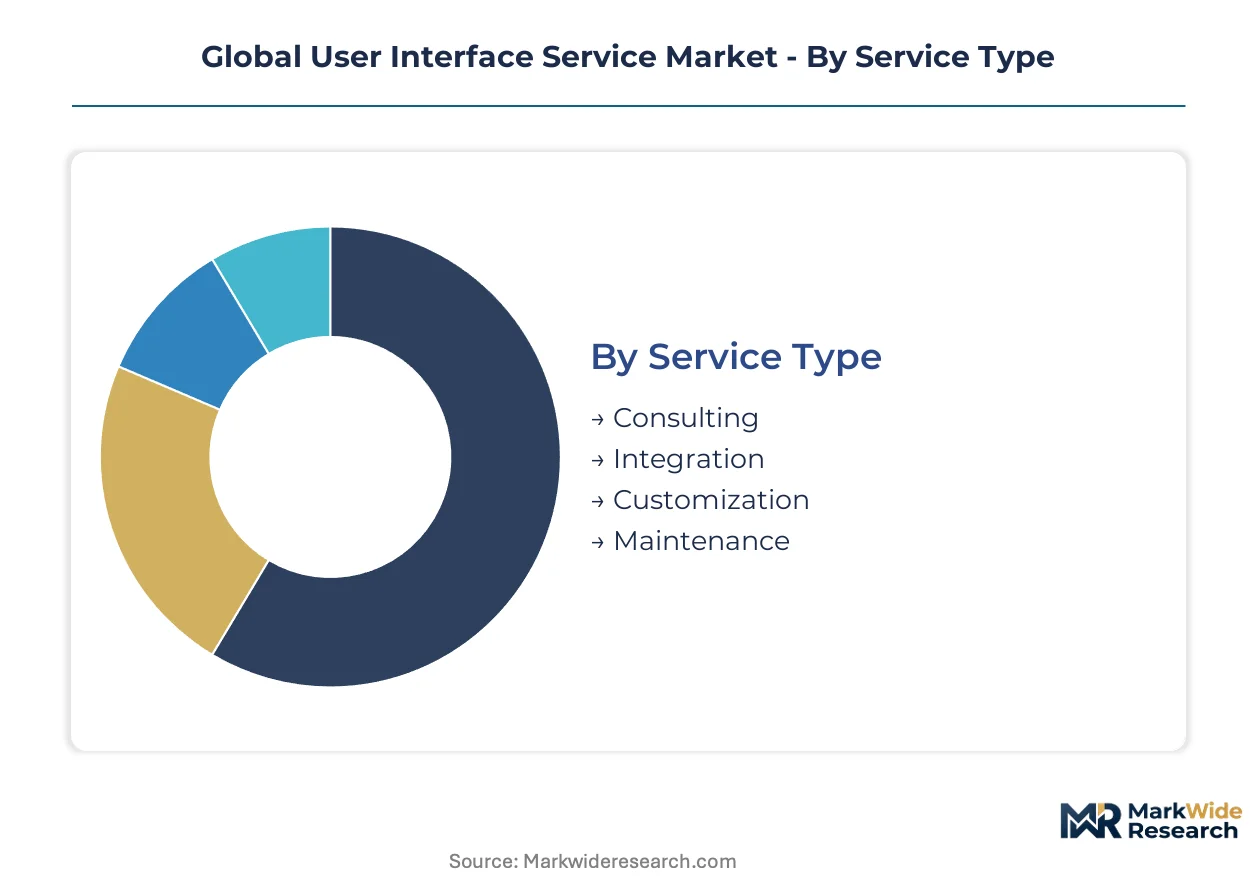
User interface service procurement splits across four critical dimensions that determine vendor selection criteria and contract structures. Each segmentation axis reveals distinct pricing models, technical requirements, and compliance burdens that reshape competitive positioning across the value chain.
Service Type:
Upgrade cycles for legacy design infrastructure are accelerating replacement demand across all service tiers as enterprises retire captive studios.
- Consulting:Strategic advisory engagements bundle design system architecture with organizational change management. Financial firms in Germany concentrate procurement here as EU AI Act compliance mandates elevate contract values for algorithmic transparency advisory.
- Integration:Systems-level service connecting design assets to development pipelines and enterprise software ecosystems. Telecommunications providers in the United States drive volume through procurement centralization around integrated design-to-development platforms.
- Customization:Tailored interface adaptations for proprietary workflows and brand-specific design systems. Demand concentrates among mid-market SaaS vendors seeking differentiation.
- Maintenance:Ongoing design system governance, accessibility auditing, and WCAG 2.1 AA compliance verification. Government agencies require this for Section 508 federal procurement adherence.
Volume placements concentrate in Integration; the faster expansion belongs to Consulting.
Application:
Cost tier differentiation separates safety-critical specifications from standard commercial deployments.
- Enterprise Software:Complex multi-module interface ecosystems requiring design system standardization across distributed product teams. Financial firms generate concentrated demand as regulatory complexity outpaces in-house capability.
- Mobile Devices:Touch-optimized interaction patterns with platform-specific human interface guidelines from Apple and Google. Consumer-facing deployments dominate this tier.
- Web Portals:Cross-browser responsive design with accessibility compliance and performance optimization. Educational institutions procure here for public-facing service delivery.
- Embedded Systems:Safety-critical HMI specifications for automotive and industrial IoT with ISO 26262 and IEC 61508 verification requirements. Tier-1 automotive suppliers in Germany outsource verification-heavy design work, creating concentrated margin pools.
Enterprise Software captures the largest contract values; Embedded Systems climbs the fastest as automotive HMI standards tighten.
End User:
Customer type determines procurement sophistication and compliance burden intensity.
- Financial Firms:Algorithmic transparency mandates and consent-layer design requirements under EU AI Act and GDPR. German banking applications face steepest compliance burden, driving specialized legal-design hybrid consultancy demand.
- Telecommunications Providers:Procurement centralization around integrated platforms with embedded systems integration requirements. U.S. carriers lead vendor consolidation trends.
- Government Agencies:Section 508 accessibility guidelines and federal procurement mandates for inclusive design verification. U.S. FCC guidelines shape specifications.
- Educational Institutions:Budget-constrained deployments with WCAG 2.1 AA compliance for public accessibility. State university systems in India expand procurement.
Financial Firms command premium pricing; Government Agencies provide steadiest recurring revenue.
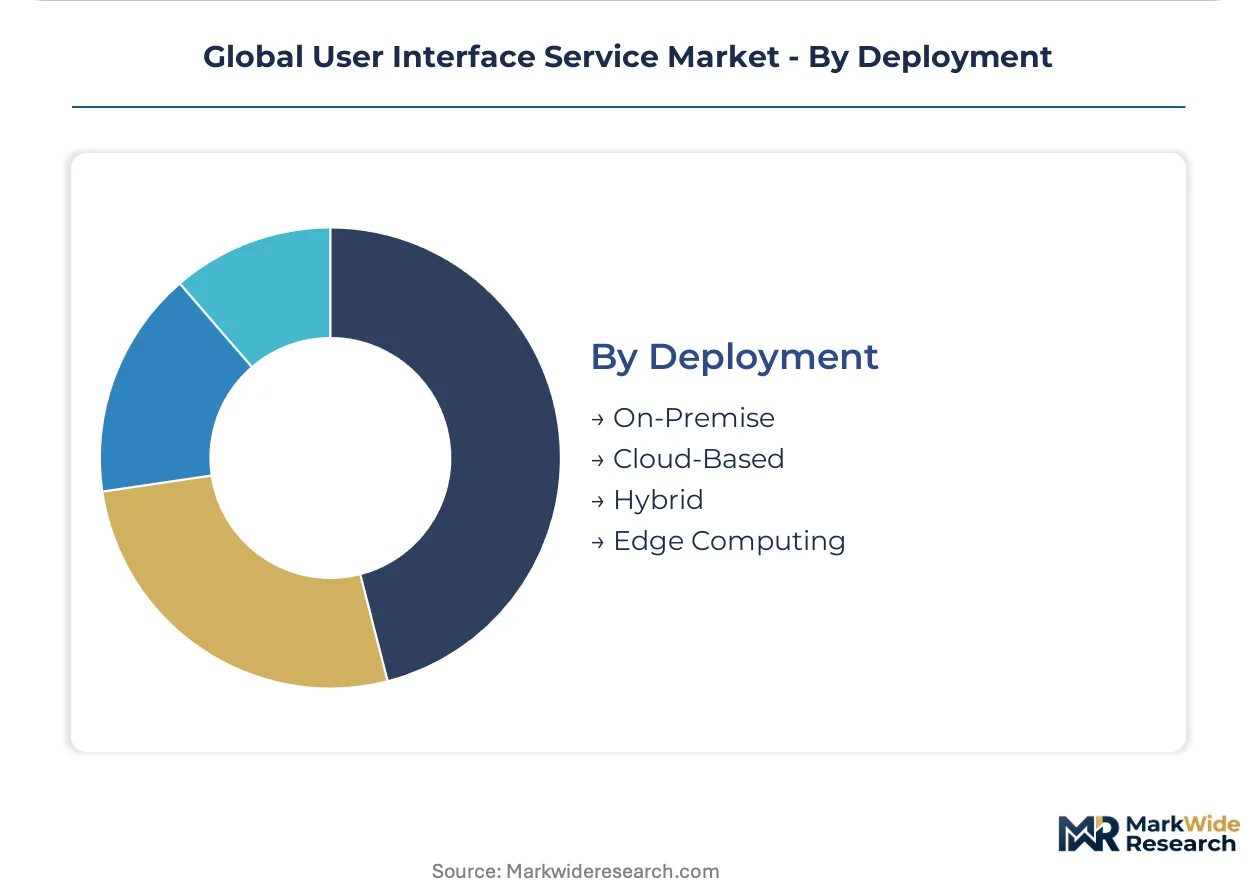
Deployment:
Maturity gradients separate legacy infrastructure from cloud-native architectures.
- On-Premise:Creative servers and design infrastructure maintained within organizational data centers. Retiring fastest as organizations eliminate capital-intensive hardware refresh cycles.
- Cloud-Based:Subscription-accessed design platforms with real-time collaboration and version control. Mid-market SaaS vendors adopt these tools fastest, reducing headcount ratios on standard projects.
- Hybrid:Mixed architecture preserving sensitive assets on-premise while leveraging cloud collaboration for distributed teams. Financial firms prefer this for data sovereignty requirements.
- Edge Computing:Low-latency interface rendering for industrial IoT and autonomous systems with localized processing. Automotive and robotics applications in Japan follow METI human-centric guidelines.
On-Premise retains residual volume in regulated sectors; Cloud-Based gains share fastest as infrastructure retirement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's design talent density anchors the United States' position in interface services, while Germany's automotive engineering heritage and India's software export infrastructure shape complementary demand centers across three continents.
United States
Telecommunications procurement centralization and healthcare IT vendor consolidation drive contract volume. FCC accessibility guidelines and Section 508 standards mandate inclusive design verification for federal agencies. Seattle and Austin clusters concentrate cloud-native platform development as enterprises retire on-premise creative infrastructure.
Germany
EU AI Act algorithmic transparency mandates and automotive HMI safety specifications elevate compliance-oriented contract values. BSI and KBA regulatory frameworks impose verification-heavy design standards on tier-1 suppliers. Stuttgart and Munich engineering corridors outsource safety-critical interface work, creating concentrated margin pools in embedded systems.
India
Domestic IT services giants build captive UI centers to serve export markets, expanding specialized consultancy demand. RBI and SEBI data governance requirements shape financial services interface specifications. Bangalore and Hyderabad technology corridors attract partnership investments from global design consultancies seeking delivery scale.
Japan
METI human-centric interface guidelines through JIS standards reshape export-bound product specifications. PMDA medical device usability requirements elevate design verification service demand for healthcare applications. Nagoya automotive clusters and Tokyo software districts integrate elderly-accessible interaction patterns into industrial control systems.
United Kingdom
Financial services regulatory complexity and fintech startup density accelerate specialized external vendor adoption. FCA conduct rules and GDPR consent-layer requirements elevate legal-design hybrid consultancy demand. London's creative agency ecosystem consolidates around integrated design-to-development platforms serving telecommunications clients.
Global User Interface Service Market Competitive Landscape
Strategic partnership restructuring dominates the current landscape as systems integrators and creative agencies acquire specialized capabilities to serve consolidated procurement committees. The vendor base separates into three tiers: platform-centric ecosystems anchoring enterprise workflows, embedded systems specialists commanding safety-critical premiums, and compliance-oriented consultancies bundling legal advisory with design execution. Competitive positioning hinges on M&A activity targeting workflow integration assets and geographic expansion into India's export-oriented delivery centers.
Within the platform-centric tier, Adobe Inc. and Figma occupy positions anchored by real-time collaborative environments that displace legacy desktop tools. Accenture exemplifies the systems integration archetype, embedding design services within telecommunications and financial services transformation programs. These three entities represent distinct strategic vectors: creative cloud ecosystem dominance, browser-native collaboration disruption, and consultative workflow integration at enterprise scale.
| Leading Market Players |
|---|
| Adobe Inc. |
| Figma |
| Accenture |
| Microsoft Corporation |
| Google LLC |
| InVision |
| Sketch |
| PwC |
| IDEO |
| Others |
Supply & Pricing Matrix
WCAG 2.1 AA certified interaction designers concentrated in Germany and the United States command wage premiums that compress margins on fixed-price contracts while widening spreads between compliance-grade and commodity UI service tiers.
Pricing Analysis
Post-delivery accessibility auditing and WCAG 2.1 AA certification verification are increasingly unbundled from base design fees, shifting risk to buyers. Pricing stratifies across premium advisory bundles, standard project-based engagements, and economy staffing augmentation. Cost compression in economy tiers intensifies as generative design tools reduce headcount ratios on standard dashboard projects. Mid-market SaaS vendors exhibit highest price sensitivity; financial firms under EU AI Act mandates show lowest.
Supply Chain Analysis
Frontend engineering talent availability in Bangalore, Hyderabad, and Berlin shapes delivery capacity for time-zone-aligned client service. The supply chain draws from specialized design consultancies, cloud-native platform providers, and embedded systems verification labs. Single-source vulnerability concentrates in WCAG 2.1 AA certification bodies where third-party verification timelines extend delivery schedules. Distribution runs through direct enterprise sales, systems integrator partnerships, and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
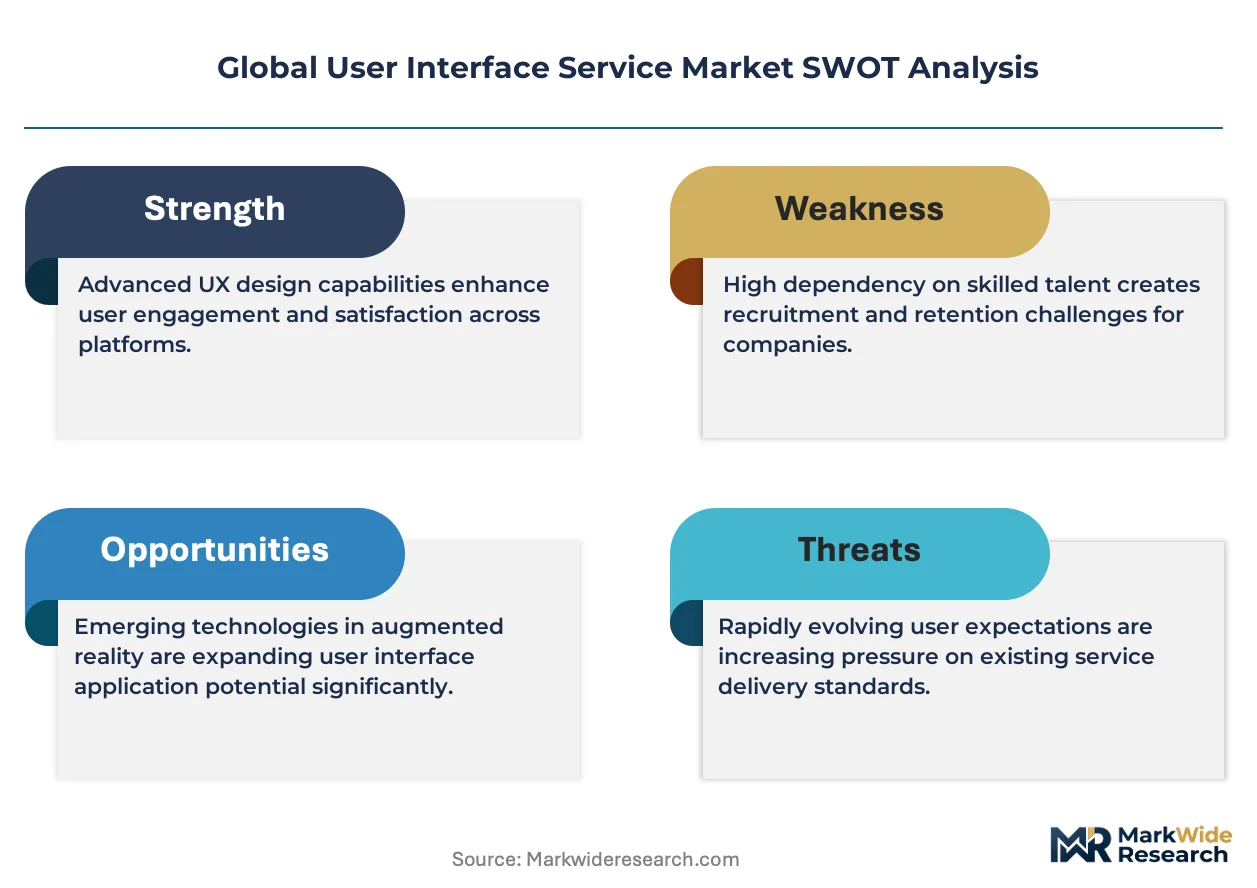
The Global User Interface Service Market functions as a cost-of-compliance arena where EU AI Act algorithmic transparency mandates erect barrier-to-entry moats favoring legal-design hybrid consultancies over pure-play studios.
For Market Incumbents: Hedge against margin erosion in commodity design tiers by acquiring specialized accessibility verification capabilities and embedding services within telecommunications transformation programs. Cloud-native platform substitution threatens legacy desktop tool franchises; vertical integration into real-time collaborative environments preserves workflow anchoring.
For New Entrants and Emerging Players: Generative design algorithms positioned for mid-market SaaS dashboard automation offer the most penetrable wedge. Target India's captive UI center buildouts through partnership structures with domestic IT services giants. Lead with outcome-based pricing tied to task-completion velocity rather than headcount ratios.
For Investors and Strategic Acquirers: The window for entry favors compliance-oriented consultancies bundling GDPR consent-layer expertise with design execution. Long-term viability rests on regulatory divergence persistence between European privacy-first frameworks and U.S. sector-specific mandates. Monitor EU AI Act enforcement intensity in German banking applications as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Systems integrators absorb WCAG 2.1 AA verification capabilities to serve financial services procurement committees. |
| Platform Integration | Real-time collaborative environments displace legacy desktop tools through embedded version control and asset pipelines. |
| Geographic Expansion | Global design consultancies establish delivery presence in Bangalore and Hyderabad to capture India's export-oriented software growth. |
| Strategic Partnership | Tier-1 automotive suppliers outsource ISO 26262 verification-heavy HMI design to specialized embedded systems studios. |
| Product Launch | Legal-design hybrid services address EU AI Act algorithmic transparency mandates in German banking applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with design system architects, regulatory affairs leads at financial institutions, accessibility compliance officers, and procurement directors at telecommunications providers. Bottom-up modeling of project pipelines and top-down validation against cloud platform subscription disclosures ensured cross-method triangulation. EMA guidance documents, FCC accessibility rulemakings, and METI JIS standard publications provided regulatory boundary conditions.
Data-stream reconciliation across deployment mode, service type tier, application complexity, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth trajectory modeling calibrated to enterprise software adoption patterns and infrastructure retirement timelines. Forecast inputs incorporated EU AI Act implementation phase transitions and automotive HMI safety standard evolution.
Several conditions sit outside the modeled scope, including hypothetical regulatory harmonization between GDPR and U.S. sector-specific guidelines, and catastrophic disruption to WCAG 2.1 AA certification body capacity. Forecasts reflect assumptions about sustained regulatory divergence and cloud-native platform substitution velocity. Material deviation in EU AI Act enforcement intensity or generative design capability maturation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Construction Project Management Software Market
Software & Services
Africa HR Payroll Software Market
Software & Services
Business Activity Monitoring Software (BAM) Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
Business Email Market
Software & Services
Computer Assisted Coding Software Market
Software & Services
Global Chromatography Software Market
Software & Services
File Sharing Software Market
Software & Services
Poland IT Software and Service Market
Software & Services
Global Legal Case Management Software Market
Software & Services
Enterprise-Grade Saas Market
Software & Services
Global Recreation Management Software Market
Software & Services
Special Effects (SFX) Software Market
Software & Services
Library Management Software Market
Software & Services
Sales Training Software Market
Software & Services
Chemical Manufacturing Software Market