
 Lighting Control Software Market | 2026-2036
Lighting Control Software Market Size, Share, and Industry Trends Forecast 2026-2036
Lighting Control Software Market Foresight
Modular bundling of lighting control software with sensor hardware and energy analytics dashboards is expanding buyer choice across project scales. Signify Holding leverages its Interact platform ecosystem to anchor large commercial and municipal deployments. Acuity Brands Lighting, Inc. sustains R&D intensity in tunable-white and circadian lighting algorithms. Schneider Electric dominates building-management integration, competing on BACnet and Modbus protocol compatibility.
Lighting control software comprises programmable platforms that manage luminaire output, scheduling, occupancy response, and energy metering through DALI, Zigbee, or IP-based protocols. These systems execute dimming curves, daylight harvesting algorithms, and demand-response protocols to reduce commercial building energy consumption. Cloud-based solutions capture expanding margin pools as recurring SaaS revenue displaces perpetual licenses. Integrated systems lead project value, though standalone software retains traction in retrofit scenarios where legacy hardware persists. Smart Cities as an end-user segment is growing fastest, driven by streetlight central-management mandates and pole-mounted IoT densification.
EPA Energy Star certification and ASHRAE Standard 90.1 shape product efficiency benchmarks and procurement eligibility across US federal and commercial buildings. FCC Part 15 governs radio-frequency emissions from wireless control modules, while NIST cybersecurity frameworks increasingly influence vendor architecture decisions. Stakeholders must monitor evolving interoperability standards between proprietary ecosystems and open-protocol deployments, as buyer preference tilts toward vendor-agnostic system integration without full infrastructure replacement.
Market Dynamics
Networked lighting management platforms are compressing hardware margins while elevating software and analytics to the primary value capture layer, forcing incumbent luminaire manufacturers to restructure revenue models around recurring service streams.
Growth Catalysts
- EU Green Deal building mandates:Retrofit requirements across member states are triggering wholesale control system replacements in commercial portfolios, with Germany's municipal programs serving as the deployment template.
- DALI-2 protocol standardization:Interoperability certification is eliminating proprietary lock-in, enabling multi-vendor system architectures that reduce buyer switching costs and expand addressable retrofit volumes.
- Industrial facility automation:Manufacturing plants are integrating lighting controls with building management systems to synchronize energy loads with production schedules, driving platform deployment in Germany and the Netherlands.
Market Restraints
- Semiconductor supply concentration:Wireless control module production depends on concentrated Asian foundry capacity, creating lead time volatility for Zigbee and Bluetooth mesh chipsets.
- Technical debt in legacy DALI installations:First-generation DALI ballasts lack addressable dimming curves, forcing complete luminaire replacement rather than control overlay in pre-2010 commercial buildings.
- FCC Part 15 certification friction:Radio-frequency emissions testing for wireless control modules adds 4-6 months to product launch timelines, compressing competitive response windows.
Strategic Opportunities
- Pole-mounted IoT densification:Streetlight central-management systems are expanding into environmental sensing and traffic monitoring, creating multi-revenue municipal contracts in German cities.
- Circadian lighting algorithms:Healthcare and education facilities are specifying tunable-white systems aligned with human centric lighting research, opening premium specification channels.
- SaaS revenue migration:Cloud-based energy analytics dashboards are displacing perpetual licenses, enabling vendors to capture lifetime value through subscription retention rather than upfront hardware margins.
Industry Challenges
- Integration complexity with BACnet legacy:Building automation technicians face protocol translation failures when merging IP-based lighting controls with 1990s-era HVAC management systems, extending commissioning timelines.
- Cybersecurity skill scarcity:NIST framework compliance for networked lighting systems requires embedded security architecture expertise that electrical contractors rarely possess, forcing vendor professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lighting Control Software Market |
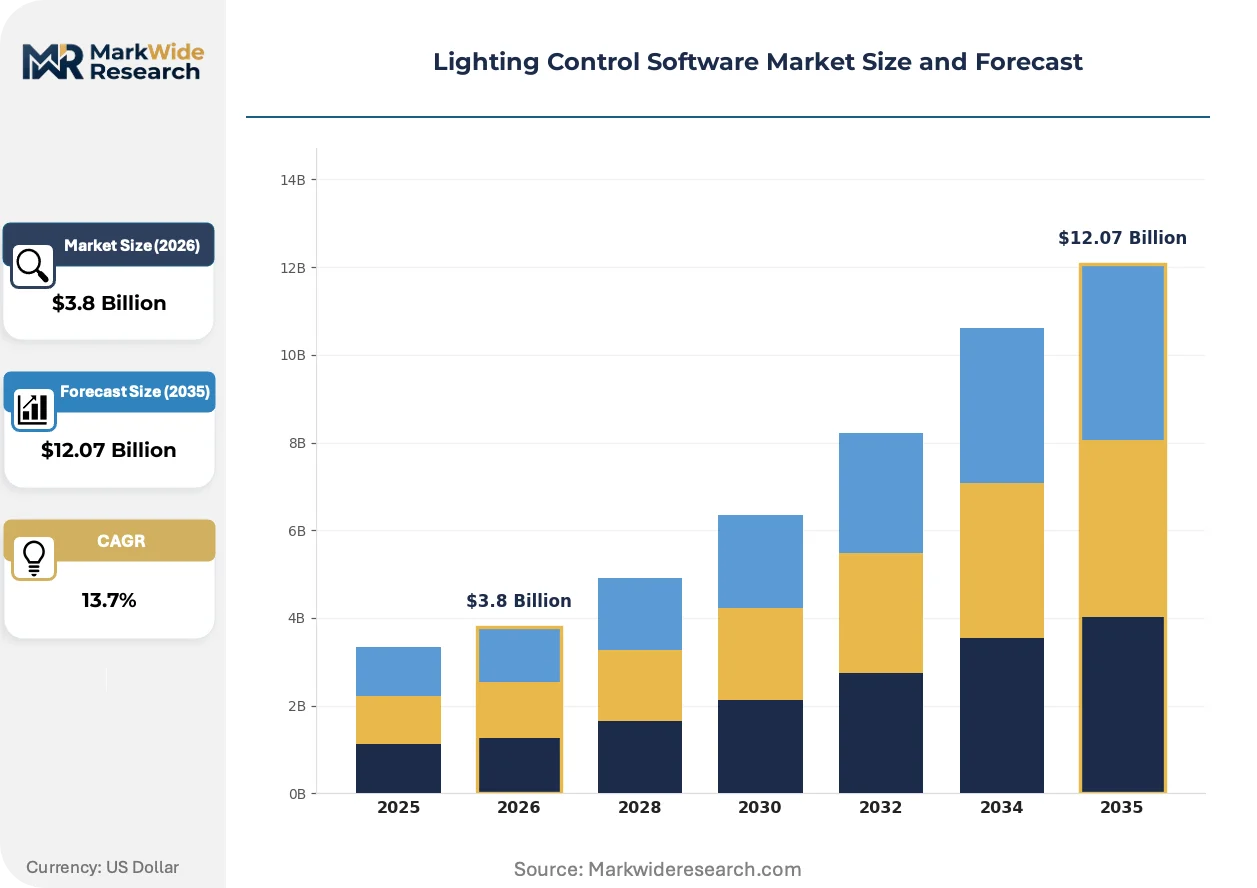
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Cloud-Based Solutions, Mobile Applications, Integrated Systems Deployment: On-Premises, Cloud Hosting, Hybrid Solutions, Edge Computing End User: Commercial Spaces, Residential Users, Industrial Facilities, Smart Cities Technology: Zigbee, Bluetooth, Wi-Fi, DALI |
| Companies Covered | Signify Holding, Acuity Brands Lighting, Inc., Lutron Electronics Co., Inc., Schneider Electric, Eaton Corporation, Honeywell International Inc., Legrand Group, General Electric Company, Crestron Electronics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lighting Control Software Market Shifts & Advancements
Edge computing architectures are redistributing processing load from cloud servers to luminaire-mounted controllers, enabling sub-second occupancy response while reducing bandwidth costs and latency vulnerability.
Software-defined lighting control is unifying previously separate dimming, color tuning, and sensor fusion functions within single firmware platforms. Large commercial landlords in Germany are specifying these unified systems for new construction, collapsing the procurement categories that historically separated hardware from software vendors.
ASHRAE Standard 90.1 updates are mandating automatic daylight harvesting in commercial buildings over 5,000 square feet. The regulation is forcing control system upgrades in US federal and state facilities, with procurement officers prioritizing DALI-2 certified products to satisfy interoperability audit requirements.
Building operators are unbundling energy analytics from hardware procurement, subscribing to third-party SaaS platforms that aggregate data across multi-vendor installations. This pattern is most visible in German municipal streetlight programs, where central management software is increasingly procured separately from LED retrofit hardware.
Lighting Control Software Market Segmentation
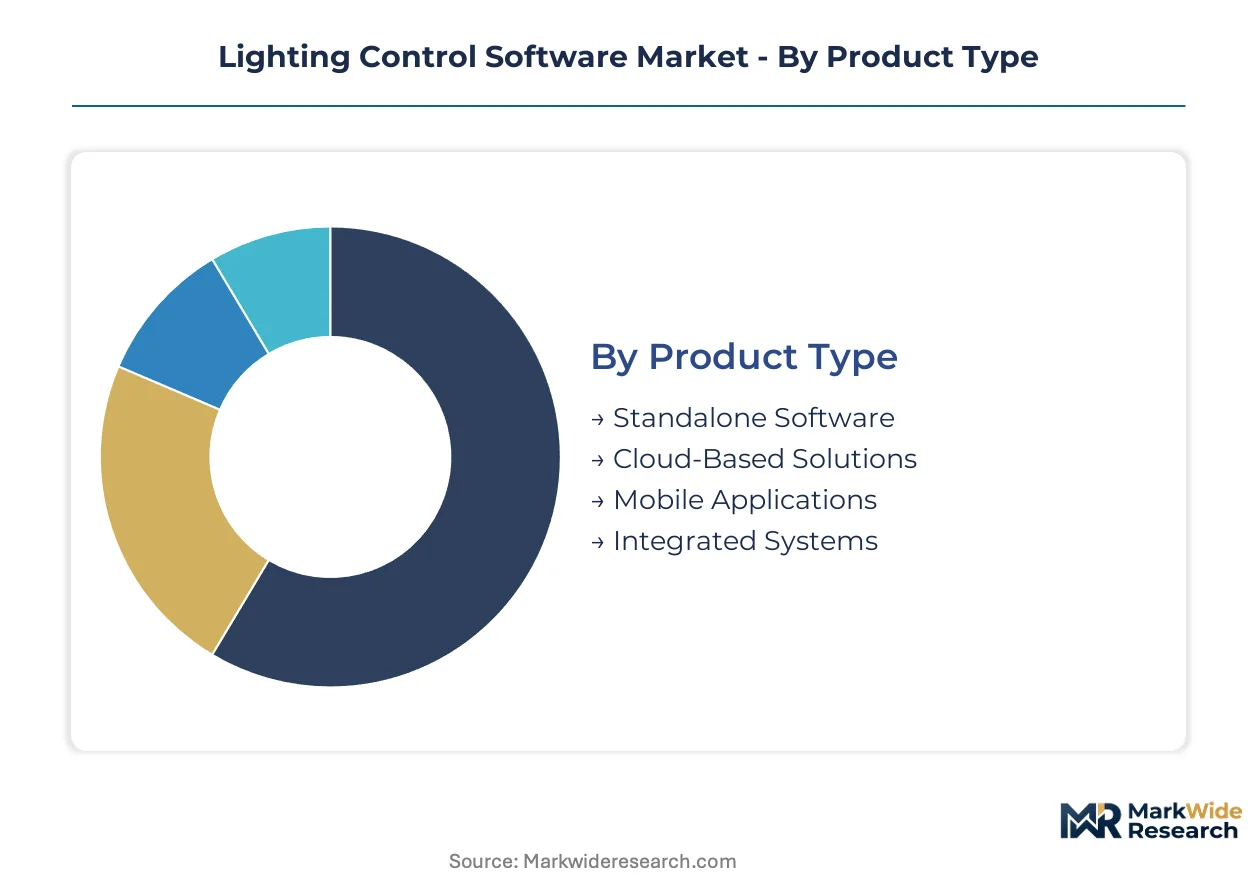
Lighting control software procurement varies sharply by infrastructure maturity and compliance burden. Buyers in regulated commercial environments prioritize certified interoperability, while municipal deployments favor scalable architectures that accommodate future sensor densification without hardware replacement.
Product Type:
FCC Part 15 certification applies to wireless-enabled software bundles, while standalone platforms face lighter electromagnetic compliance burdens. Cloud-based solutions must satisfy NIST cybersecurity frameworks for federal building eligibility.
- Standalone Software:Perpetual-license platforms controlling legacy DALI and 0-10V hardware through local servers. Demand concentrates in US federal facilities where air-gapped networks satisfy security mandates, though retrofit volumes are compressing as SaaS alternatives mature.
- Cloud-Based Solutions:Browser-accessible platforms executing remote commissioning, energy analytics, and predictive maintenance algorithms. German municipal streetlight programs are specifying these systems to centralize multi-city operations, with subscription revenue displacing upfront licensing in commercial portfolios.
- Mobile Applications:Smartphone-based commissioning and override interfaces for facility managers.
- Integrated Systems:Unified firmware controlling luminaires, sensors, and HVAC through single management layers.
Leading the category by volume: Integrated Systems. Growing fastest: Cloud-Based Solutions.
Deployment:
Cost tiers separate enterprise-grade redundancy from mid-market simplicity, with hybrid architectures commanding premium positioning for their operational flexibility.
- On-Premises:Local server installations with dedicated network segmentation for cybersecurity-sensitive environments. Healthcare facilities in Germany specify these deployments to satisfy GDPR data residency requirements, though higher capital expenditure limits adoption in smaller commercial portfolios.
- Cloud Hosting:Fully managed SaaS infrastructure with automatic firmware updates and elastic compute scaling. US state government facilities are migrating to these platforms to satisfy ASHRAE Standard 90.1 audit automation requirements without maintaining internal IT staffing.
- Hybrid Solutions:Split architectures processing sensitive occupancy data locally while aggregating analytics in cloud environments.
- Edge Computing:Luminaire-mounted controllers executing sub-second response algorithms with minimal bandwidth dependency.
Dominating procurement value: Hybrid Solutions. Expanding most quickly: Edge Computing.
End User:
Application context dictates specification complexity, with industrial automation demanding tight building management integration and residential favoring smartphone simplicity.
- Commercial Spaces:Office towers, retail chains, and hospitality venues requiring daylight harvesting, demand response, and space utilization analytics. Germany's commercial building operators are retrofitting these systems to satisfy EU Green Deal efficiency mandates, with DALI-2 certification now standard in new construction specifications.
- Smart Cities:Municipal streetlight networks expanding into environmental sensing, traffic monitoring, and public safety applications. German cities including Hamburg and Munich are deploying central management platforms that aggregate pole-mounted IoT data, creating multi-revenue service contracts beyond illumination.
- Residential Users:Single-family and multi-tenant installations prioritizing voice assistant integration and circadian scheduling.
- Industrial Facilities:Manufacturing plants synchronizing lighting energy loads with production schedules and safety systems.
Generating highest project values: Commercial Spaces. Climbing the fastest: Smart Cities.
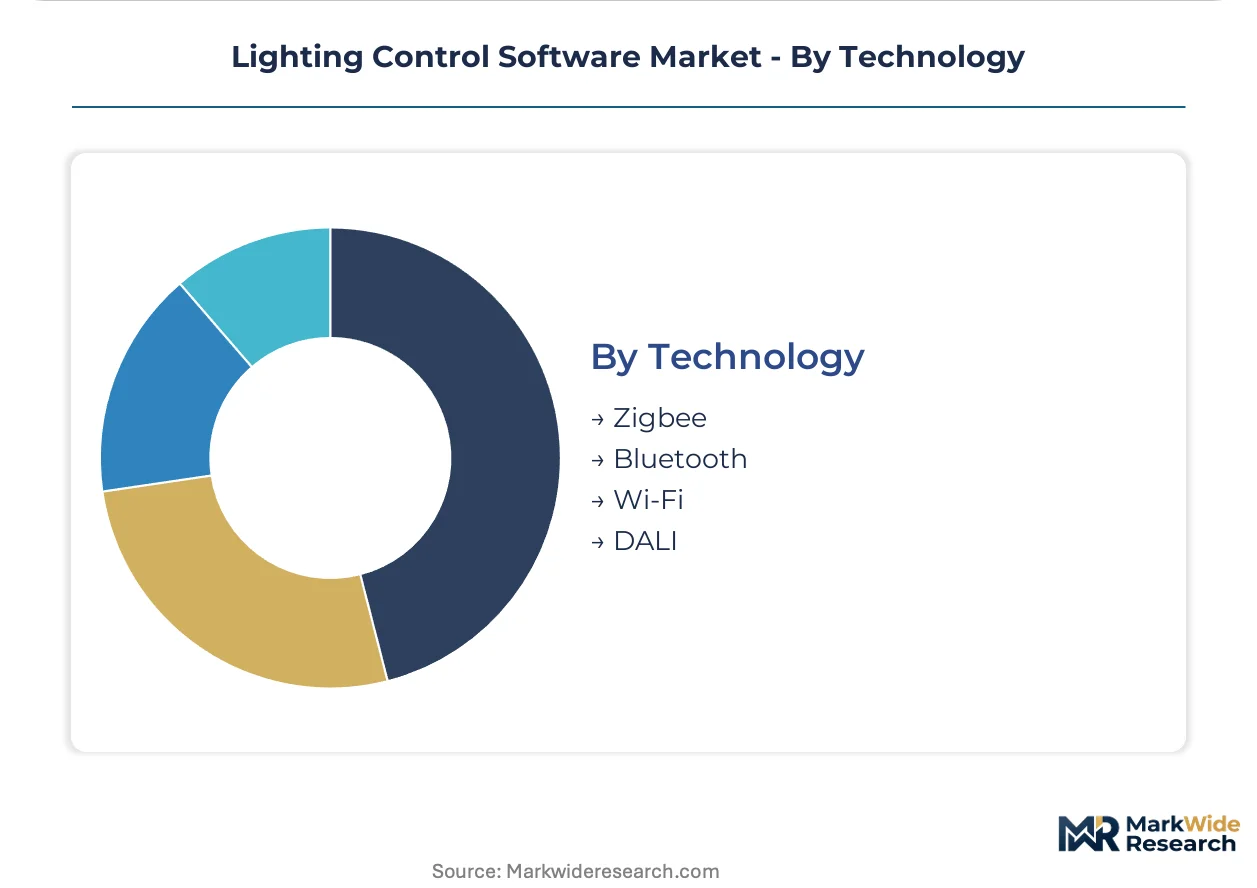
Technology:
Protocol maturity determines interoperability range, with open standards expanding vendor choice while proprietary ecosystems lock in recurring service revenue.
- DALI:Digital Addressable Lighting Interface protocol enabling individual luminaire control, status monitoring, and energy metering through two-wire bus architecture. ASHRAE Standard 90.1 compliance in US commercial buildings over 5,000 square feet is mandating DALI-2 certified installations, with procurement officers prioritizing interoperability audit documentation.
- Zigbee:Mesh networking standard for wireless sensor and control module communication at sub-gigahertz frequencies. FCC Part 15 certification requirements for radio-frequency emissions are extending product launch timelines, compressing competitive response windows for chipset vendors dependent on concentrated Asian foundry capacity.
- Bluetooth:Low-energy mesh protocols leveraging smartphone ubiquity for commissioning and user control.
- Wi-Fi:IP-based control leveraging existing infrastructure for high-bandwidth sensor fusion and video analytics.
Commanding specification share: DALI. Gaining adoption fastest: Bluetooth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Industrie 4.0 tax incentive zones are concentrating smart building technology procurement, drawing control software vendors into municipal and industrial clusters across the country.
Germany
Municipal smart streetlight programs in Hamburg and Munich are deploying central management platforms for pole-mounted IoT densification. EU Green Deal building efficiency mandates are accelerating retrofit requirements across commercial portfolios. Bavaria's industrial automation corridor is integrating lighting controls with building management systems to synchronize energy loads with production schedules.
United States
Federal facilities are upgrading control systems to satisfy ASHRAE Standard 90.1 daylight harvesting mandates for buildings exceeding 5,000 square feet. EPA Energy Star certification shapes procurement eligibility across government and commercial portfolios. The Pacific Northwest corridor is specifying DALI-2 certified products for interoperability audit compliance in new construction.
Netherlands
Industrial facility automation is driving platform deployment to coordinate lighting energy with manufacturing operations. REACH regulations influence material composition in wireless control module manufacturing. The Eindhoven high-tech cluster is piloting edge computing architectures for sub-second occupancy response in commercial buildings.
United Kingdom
Commercial building operators are retrofitting networked lighting management to meet tightening building efficiency standards. The country's national building regulator is enforcing cybersecurity frameworks for networked infrastructure. London's financial district is specifying cloud-based energy analytics dashboards for multi-tenant portfolio management.
France
Healthcare and education facilities are specifying tunable-white systems aligned with circadian lighting research. CE marking requirements govern radio-frequency emissions from wireless control modules. The Île-de-France region is consolidating municipal streetlight procurement under central management software contracts.
Lighting Control Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the lighting control software market. Tier-one electrical equipment manufacturers leverage building management integration capabilities to anchor enterprise contracts. Mid-scale lighting specialists compete on DALI-2 certification depth and circadian algorithm development. The dominant competitive moves are strategic partnerships with sensor hardware vendors and portfolio diversification into energy analytics subscriptions.
Among diversified electrical equipment conglomerates, Schneider Electric and Eaton Corporation exemplify the building-management integration archetype, competing on protocol compatibility breadth. Signify Holding occupies a position within the lighting-native platform tier, leveraging luminaire manufacturing scale to anchor SaaS revenue migration. These three represent distinct strategic postures: protocol-centric systems integration, hardware-anchored software monetization, and cloud-native energy analytics specialization.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands Lighting, Inc. |
| Lutron Electronics Co., Inc. |
| Schneider Electric |
| Eaton Corporation |
| Honeywell International Inc. |
| Legrand Group |
| General Electric Company |
| Crestron Electronics, Inc. |
| Others |
Supply & Pricing Matrix
Captive integration of wireless chipset sourcing into luminaire manufacturing anchors supply resilience and pricing power for vendors serving German municipal smart streetlight programs. This vertical control over Zigbee and Bluetooth mesh module procurement insulates platform providers from Asian foundry lead-time volatility while enabling premium positioning for DALI-2 certified integrated systems.
Pricing Analysis
Premium pricing for sub-12-week lead-time delivery of wireless control modules commands 15-25% markups over spot inventory in German industrial automation corridors. Three-tier pricing structure across premium certified, standard interoperable, and economy retrofit levels stratifies buyer segments, with ASHRAE 90.1 compliance tiering separating federal facility procurement from commercial retrofit demand. Cost compression in economy retrofit tiers is intensifying because legacy DALI ballast replacement cycles compress project margins. Municipal buyers in Hamburg and Munich exhibit lowest price sensitivity due to multi-revenue IoT service contract structures, while mid-market commercial landlords in US federal facilities demonstrate highest sensitivity to perpetual-license versus SaaS migration costs.
Supply Chain Analysis
Workforce availability constraints in Taiwanese semiconductor foundries and Malaysian electronics assembly plants are extending chipset procurement cycles for wireless control module vendors. Supply concentration in China, South Korea, and Taiwan for Zigbee SoCs, Bluetooth mesh chipsets, and DALI-2 protocol controllers creates single-source vulnerability when geopolitical trade restrictions disrupt logistics corridors. Raw material dependencies span gallium nitride substrates, rare earth magnets for sensor actuation, and copper busbar for luminaire power distribution. Distribution runs through electrical contractor channels in Germany, specification engineer networks in US commercial construction, and direct municipal procurement offices for smart city deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lighting control software market sits in a protocol-transition phase, with DALI-2 and IP-based architectures displacing first-generation DALI and proprietary 0-10V systems across commercial retrofit portfolios.
For Market Incumbents: Deepen backward integration into wireless chipset supply through captive foundry partnerships or long-term offtake agreements with Taiwanese semiconductor vendors, insulating against lead-time volatility that threatens project delivery commitments in German municipal programs. Reinforce DALI-2 certification depth as a defensive moat against emerging cloud-native entrants targeting mid-market commercial portfolios with subscription-only energy analytics platforms. For New Entrants and Emerging Players: Begin with circadian lighting algorithm specialization for healthcare and education facilities in France and the Netherlands, where tunable-white specification channels remain underpenetrated by integrated building management vendors. White-space concentration in SaaS-only energy analytics for multi-vendor retrofit portfolios offers lowest competitive density, with procurement unbundling trends in German municipal streetlight programs validating separate software-from-hardware contracting models. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by electrical equipment conglomerates seeking building management integration capabilities, with Schneider Electric and Eaton Corporation archetypes representing logical acquirers of DALI-2 certified platform specialists. Long-term viability favors vendors with recurring SaaS revenue exceeding 40% of total mix and NIST cybersecurity framework compliance for federal building eligibility. The signal to watch is EU Green Deal enforcement acceleration triggering wholesale control system replacement mandates across member state commercial portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| DALI-2 Certification Investment | ASHRAE 90.1 compliance unlocks US federal and state facility procurement eligibility. |
| Wireless Chipset Supply Agreement | Taiwanese foundry partnerships insulate against lead-time volatility in Zigbee module production. |
| Circadian Algorithm Development | Tunable-white specification channels in French healthcare facilities command premium positioning. |
| SaaS Revenue Migration | Subscription retention models displace perpetual licenses in German municipal streetlight programs. |
| Edge Computing Architecture Deployment | Luminaire-mounted controllers enable sub-second occupancy response with minimal bandwidth dependency. |
Research Methodology
Document review covered SEC filings from Signify Holding and Acuity Brands, EU Green Deal regulatory impact assessments, and ASHRAE Standard 90.1 compliance documentation, complemented by interviews with building automation system integrators, municipal procurement officers in Hamburg and Munich, electrical contractor technical directors, and facility management software vendors. Secondary validation drew from FCC Part 15 certification databases, NIST cybersecurity framework implementation guides, and DALI-2 interoperability audit records. Bottom-up project pipeline analysis across German commercial retrofit portfolios triangulated with top-down market sizing from luminaire shipment data and control software licensing disclosures.
Cross-referencing historical retrofit cycle patterns against expert panel input on EU mandate enforcement timelines anchored the projection framework. Segmentation dimensions modeled span deployment architecture, protocol technology, end-use application, and regional regulatory cluster. CAGRs derived from weighted average of technology diffusion curves and policy implementation schedules. Industry-specific forecast inputs included DALI-2 certification adoption velocity and municipal IoT densification contract structures.
Semiconductor supply disruption, EU Green Deal enforcement variance, and NIST cybersecurity framework revision are the dominant revision risks that could compress or extend addressable retrofit volumes across the analysis window. Forecasts reflect assumptions on protocol standardization momentum and interoperability audit stringency. Material deviation in named triggers warrants pause and re-evaluation of segment-specific growth trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Enterprise Data Observability Software Market
Software & Services
Global Reporting Software Market
Software & Services
Time and Attendance Software Market
Software & Services
Neurodiverse Workforce Productivity Tools Market
Software & Services
Urban Planning Software and Services Market
Software & Services
Global App Builder Software Market
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
Global Application Release Automation Market
Software & Services
Global Digital Adoption Platform Software Market
Software & Services
DevOps Market
Software & Services
Runtime Software Market
Software & Services
Library Management Software Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Email Optimization Software Market
Software & Services
Global UIUX Software Market
Software & Services
Salesforce Services Market