
 Online Powersports Market | 2026-2036
Online Powersports Market Size, Share, and Industry Trends Forecast 2026-2036
Online Powersports Market Analysis
The capital-intensity divergence between mass-market assemblers and premium engineering houses is rotating competitive investment toward proprietary powertrain development and captive digital retail infrastructure. Polaris leverages its vertically integrated manufacturing campus in Minnesota to control snowmobile and side-by-side supply chains from foundry to doorstep delivery. BRP sustains aggressive R&D allocation across its Rotax engine portfolio and Sea-Doo watercraft lines, anchoring its position in high-margin personal watercraft segments. Yamaha Motor competes through dual-channel strength, combining dealer network density with direct-to-consumer configurators that bypass traditional showroom economics.
Online powersports encompasses gasoline and electric recreational vehicles, parts, and riding gear transacted through digital platforms, with engine displacement typically ranging from 50cc entry motorcycles to 1000cc utility ATVs and turbocharged side-by-sides exceeding 150 horsepower. The category serves weekend enthusiasts, commercial fleet operators, and guided tour companies seeking terrain traversal, payload capacity, or water-based recreation. Motorcycles and ATVs dominate transaction volume through established dealer portals and manufacturer-direct websites, while personal watercraft generates disproportionate margin contribution due to seasonal scarcity and coastal demographic concentration. E-commerce and online marketplaces represent the fastest-expanding sales channel as younger buyers prioritize mobile configurators, subscription financing, and home delivery over traditional showroom negotiations.
The EPA enforces Tier 3 emissions standards for off-highway motorcycles and ATVs, while NHTSA governs on-road lighting and braking requirements for dual-sport machines that bridge trail and street legality. State-level regulators like California Air Resources Board impose additional evaporative emissions controls that effectively gate market access for non-compliant engines. The EU F-Gas Regulation and impending Euro 5 extensions for leisure craft are pressuring manufacturers to accelerate electric propulsion roadmaps and certify battery thermal management systems for extreme-temperature operation. Stakeholders must monitor how carbon-border adjustment mechanisms and battery mineral sourcing rules reshape landed costs for imported electric powertrains against domestically assembled combustion alternatives.
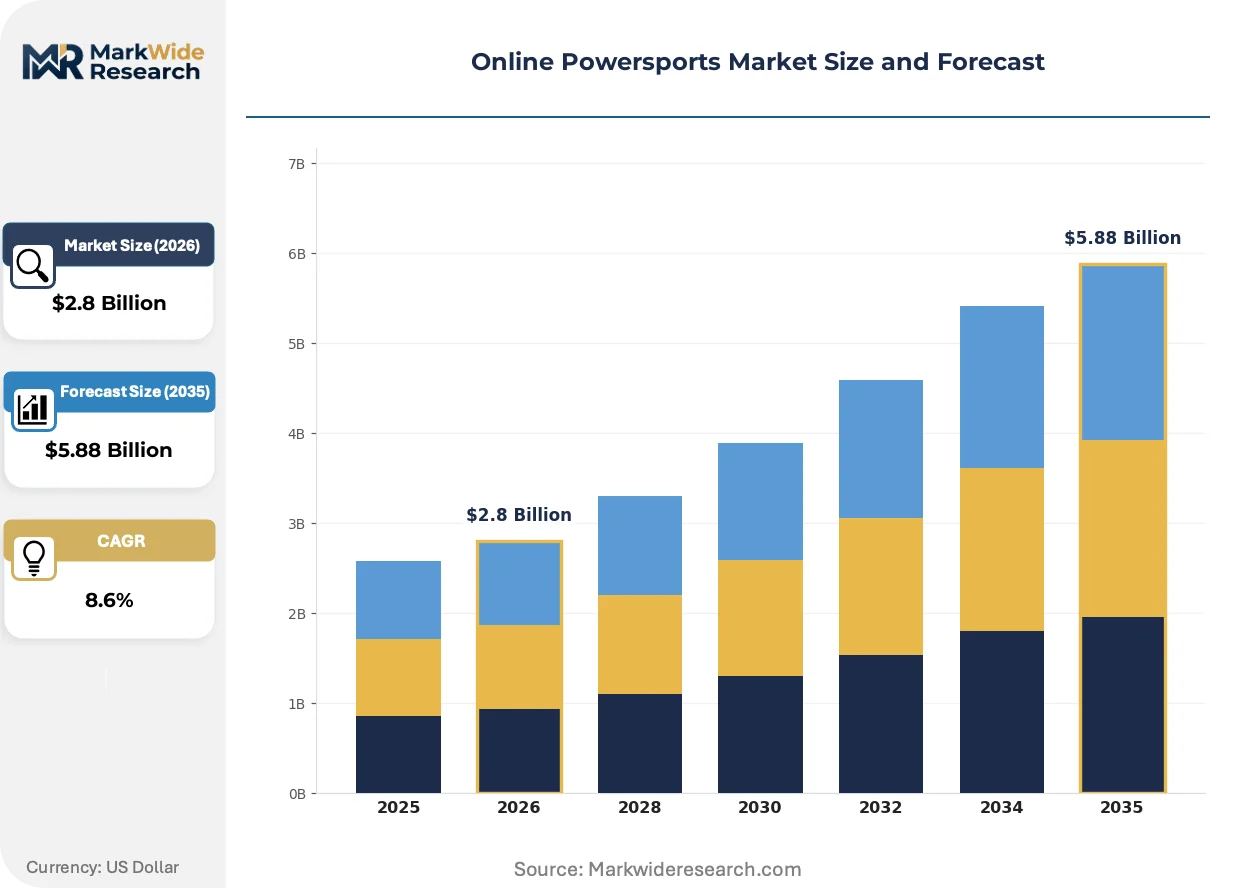
Market Dynamics
Digital retail infrastructure is compressing traditional dealer margins while EPA Tier 3 and CARB evaporative emissions standards force powertrain redesign cycles that favor capital-rich manufacturers with captive certification laboratories.
Growth Catalysts
- CARB Certification Acceleration:California's evaporative emissions controls are filtering non-compliant small-engine manufacturers from the digital channel, concentrating transaction volume among certified assemblers with laboratory infrastructure.
- Subscription Financing Platforms:Fintech-enabled lease-to-own instruments are lowering entry barriers for younger buyers seeking side-by-side utility vehicles without traditional credit underwriting delays.
- Rocky Mountain Trail Access Expansion:Utah and Colorado land management agencies are issuing new off-highway vehicle permits on Bureau of Land Management territory, stimulating replacement demand through expanded legal riding areas.
Market Restraints
- Lithium-Ion Cell Supply Concentration:Battery pack assembly for electric ATVs depends on cathode precursor refining concentrated in Chinese industrial zones, exposing landed cost volatility to mineral export licensing shifts.
- Steel and Aluminum Input Volatility:Chassis fabrication and suspension component sourcing face commodity price swings that compress assembler margins on fixed-price digital pre-orders.
- Gasoline Engine Substitution Pressure:Electric powertrains with instant torque delivery are eroding performance differentiation historically claimed by 1000cc utility ATV platforms in recreational segments.
Strategic Opportunities
- IRA Clean Vehicle Tax Credits:The Inflation Reduction Act's commercial EV incentives extend to electric utility vehicles assembled in North American facilities, creating margin expansion for qualifying electric side-by-side configurations.
- Guided Tour Fleet Electrification:Moab and Sedona adventure operators are piloting silent-running electric UTVs to access noise-restricted canyon corridors previously closed to combustion engines.
- Telematics-Enabled Usage Insurance:Connected vehicle data streams are enabling pay-per-mile coverage products that reduce total cost of ownership for occasional-use recreational buyers.
Industry Challenges
- Battery Thermal Management Certification:Validating lithium pack performance across desert heat and mountain freeze cycles requires extended test protocols that delay model-year launches.
- Dealer Network Digital Integration:Legacy franchise agreements obstruct manufacturer-direct configurators from accessing service infrastructure for warranty fulfillment and collision repair.
- Power Electronics Talent Scarcity:Electric drivetrain development competes with automotive and aerospace sectors for motor control firmware engineers and battery management system architects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Powersports Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorcycles, ATVs, Snowmobiles, Personal Watercraft Sales Channel: Direct Sales, E-commerce, Dealerships, Online Marketplaces Customer Type: Enthusiasts, Casual Riders, Fleet Operators, Rentals Accessory Type: Helmets, Protective Gear, Apparel, Maintenance Tools |
| Companies Covered | Polaris, BRP, Yamaha Motor, Honda Motor, Harley-Davidson, Kawasaki Heavy Industries, KTM, Arctic Cat, RevZilla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Powersports Market Emerging Trajectories
Powertrain electrification and connected vehicle architectures are restructuring competitive investment priorities away from displacement-based segmentation toward software-defined performance tuning and over-the-air feature activation.
Silicon carbide MOSFETs in 800-volt architectures are displacing traditional IGBT inverter designs in premium electric side-by-side development programs. BRP and Polaris engineering teams have adopted these wide-bandgap semiconductors for their thermal efficiency gains in sustained hill-climb duty cycles. The technology is displacing 15-year incumbent power electronics suppliers who lack automotive-scale SiC sourcing relationships.
The EU F-Gas Regulation and its impending extension to leisure craft propulsion systems are mandating refrigerant transitions in cabin climate systems and battery thermal loops. Manufacturers must certify alternative cooling chemistries that maintain performance across Mediterranean summer and Nordic winter operation envelopes. Personal watercraft and enclosed-cab UTV segments face the steepest compliance cost escalation due to sealed-system engineering requirements.
Mobile-first configurators with augmented reality visualization are capturing transaction flow from traditional showroom negotiations. Younger buyers in Texas and Arizona markets complete purchase journeys entirely through manufacturer apps, selecting accessories and financing before physical vehicle inspection. This channel compression is most visible in entry-level motorcycle and youth ATV categories where specification standardization reduces tactile evaluation requirements.
Online Powersports Market Segmentation
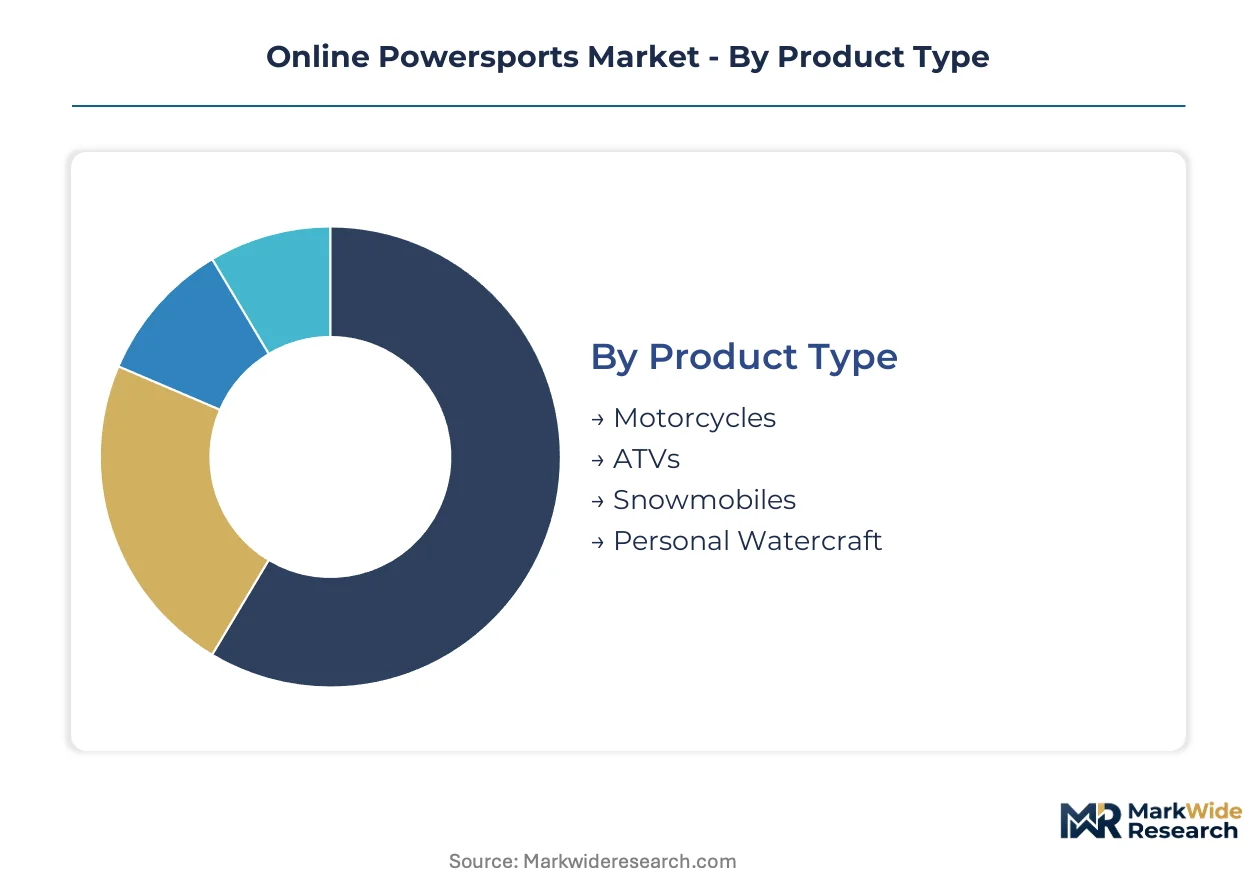
Online powersports segmentation reveals divergent channel economics and customer lifetime value profiles. Product type determines fulfillment complexity, while sales channel selection shapes margin capture and warranty liability structures.
Product Type:
Domestic assembly concentrates in Minnesota and Quebec for snowmobiles and side-by-sides, while personal watercraft production clusters in Florida coastal zones for export to Mediterranean and Gulf markets.
- Motorcycles:Engine displacement spans 50cc urban commuters to 1800cc touring platforms with integrated navigation and heated grips. Demand concentrates in Texas and Arizona where lane-splitting permissibility and year-round riding seasons sustain replacement cycles. EPA Tier 3 certification costs favor established assemblers with captive testing laboratories.
- ATVs:Utility configurations with 1000cc displacement and 1500-pound payload ratings dominate commercial fleet procurement in Utah and Colorado ranching operations. Rocky Mountain trail access expansion is accelerating side-by-side substitution in recreational segments.
- Snowmobiles:Seasonal production cycles in Roseau, Minnesota and Valcourt, Quebec supply northern tier states and Canadian provinces. Pre-order windows compress digital transaction timelines to July-September fulfillment slots.
- Personal Watercraft:Turbocharged 300-horsepower platforms command premium pricing in Florida and California coastal markets. CARB evaporative emissions certification gates California market access for imported two-stroke alternatives.
Motorcycles hold the largest share; momentum sits with ATVs as Rocky Mountain trail permits expand.
Sales Channel:
Channel selection determines warranty fulfillment pathways and service revenue retention, with direct-to-consumer models capturing financing margin but ceding collision repair volume.
- Direct Sales:Manufacturer-operated configurators in Texas and Arizona markets enable complete purchase journeys through mobile apps. Younger buyers prioritize subscription financing and home delivery over showroom negotiation.
- E-commerce:Proprietary brand websites with augmented reality visualization are displacing third-party platform dependency. Integrated logistics networks support doorstep delivery of crated vehicles requiring minimal dealer preparation.
- Dealerships:Legacy franchise agreements retain service infrastructure for warranty fulfillment and collision repair. Digital integration remains incomplete as legacy dealer management systems obstruct real-time inventory visibility.
- Online Marketplaces:Third-party platforms aggregate used inventory and aftermarket parts with variable certification standards. Transaction volume concentrates in entry-level youth ATV categories where specification standardization reduces inspection requirements.
Dealerships retain the largest share; direct sales channels are expanding most quickly as mobile-first configurators capture younger demographics.
Customer Type:
Customer classification determines financing instrument design and telematics integration depth, with fleet operators driving connected vehicle adoption for usage-based insurance products.
- Enthusiasts:Technical buyers prioritize powertrain specifications and suspension travel metrics over price positioning. Digital communities on manufacturer forums influence configuration decisions before platform engagement.
- Casual Riders:Weekend users in suburban Texas and Arizona markets seek entry-level displacement with automatic transmission simplicity. Subscription financing platforms reduce credit underwriting friction for this price-sensitive segment.
- Fleet Operators:Guided tour companies in Moab and Sedona pilot electric UTV fleets for noise-restricted canyon access. Telematics-enabled usage insurance reduces total cost of ownership through pay-per-mile coverage.
- Rentals:Seasonal operators in Florida and Lake Tahoe markets prioritize durability specifications and rapid turnaround maintenance protocols. Procurement concentrates in utility ATV configurations with standardized parts availability.
Enthusiasts command the highest per-unit margin; fleet operators are gaining share fastest as commercial electrification incentives reshape procurement criteria.
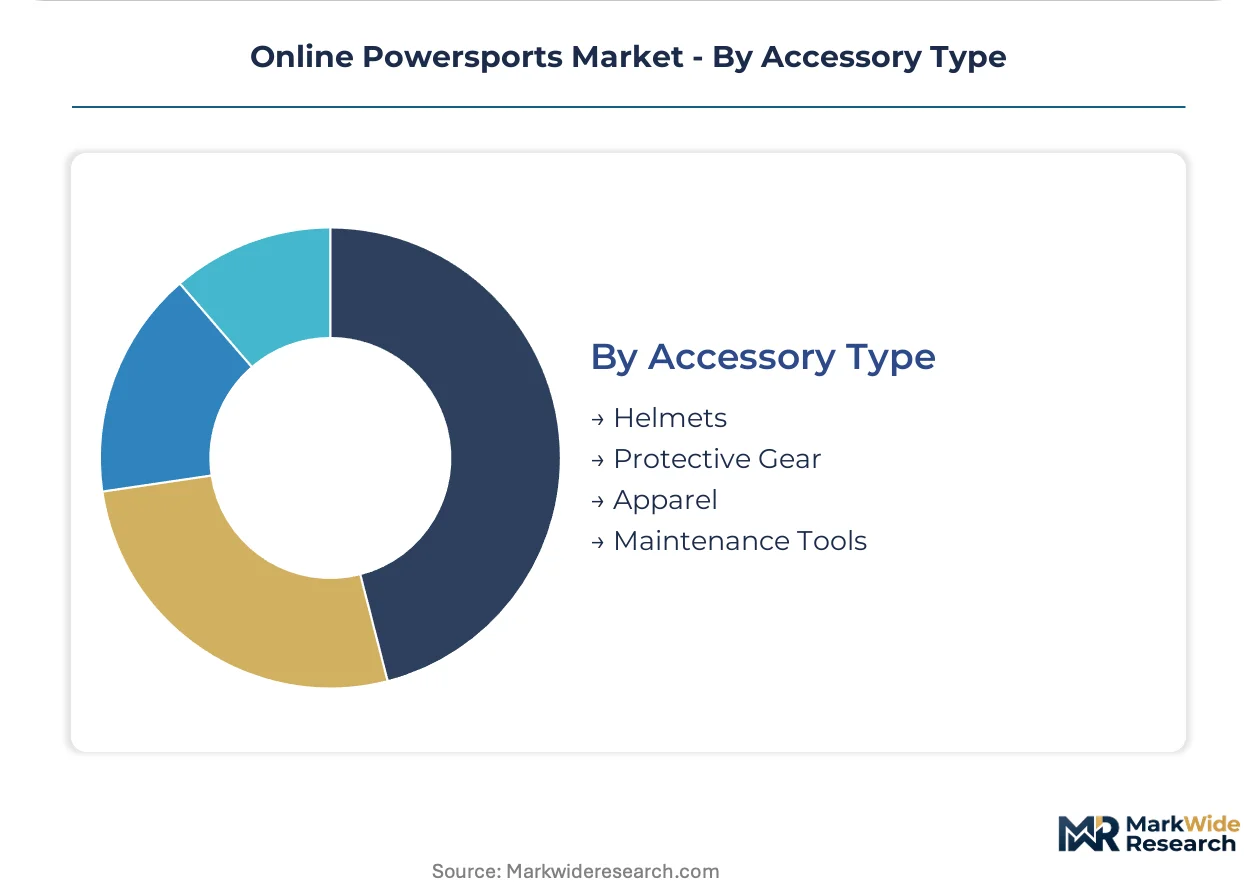
Accessory Type:
Accessory economics favor recurring revenue models with lower fulfillment complexity than vehicle transactions, though sizing variability drives return rates in digital channels.
- Helmets:DOT and ECE certification requirements segment pricing across polycarbonate entry and carbon fiber premium tiers. AR-enabled sizing tools on manufacturer apps reduce fit-related returns in direct channels.
- Protective Gear:Armor-integrated jackets and knee guards target high-speed ATV and motorcycle segments with CE Level 2 impact ratings. Rocky Mountain riding seasons sustain replacement demand for weathered equipment.
- Apparel:Branded merchandise with moisture-wicking textiles generates repeat purchase frequency absent in vehicle transactions. Seasonal colorway releases mirror automotive industry pattern cycles.
- Maintenance Tools:Specialized diagnostic equipment and suspension service kits concentrate in enthusiast segments with technical self-service capability. Digital tutorials on manufacturer platforms reduce dealer service dependency.
Helmets hold the largest share; protective gear is climbing the fastest as safety regulation awareness spreads through rider education programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rocky Mountain states consume powersports equipment for trail recreation, while coastal markets prioritize personal watercraft and desert Southwest regions favor side-by-side utility configurations for land management work.
United States
Utah and Colorado land management agencies issue new off-highway vehicle permits on Bureau of Land Management territory, stimulating replacement demand through expanded legal riding areas. EPA Tier 3 emissions standards and CARB evaporative controls in California filter non-compliant small-engine manufacturers from digital channels. Domestic assembly concentrates in Minnesota and Quebec for snowmobiles and side-by-sides, with vertically integrated manufacturing campuses controlling supply chains from foundry to doorstep delivery.
Canada
Quebec's Valcourt region anchors snowmobile production for northern tier provinces and export markets, with seasonal pre-order windows compressing digital transaction timelines to July-September fulfillment slots. Health Canada and Transport Canada coordinate vehicle safety certification with EPA-aligned emissions standards for cross-border product compatibility. Ontario's manufacturing corridor supplies chassis components and suspension systems to Minnesota-based assemblers through integrated North American supply networks.
Germany
KBA vehicle type approval requirements and impending Euro 5 extensions for leisure craft pressure manufacturers to accelerate electric propulsion roadmaps and certify battery thermal management systems. Bavaria's automotive supplier ecosystem feeds power electronics and motor control firmware expertise into electric ATV development programs. Stuttgart engineering consultancies validate alternative cooling chemistries for Mediterranean summer and Nordic winter operation envelopes.
Japan
METI industrial policy supports domestic motorcycle manufacturers maintaining dual-channel strength through dealer network density combined with direct-to-consumer configurators. JIS standards govern component interoperability for aftermarket parts traded through digital platforms. Tokyo-based fintech platforms enable subscription financing instruments that reduce credit underwriting friction for younger buyers seeking entry-level displacement machines.
Australia
TGA-equivalent vehicle safety frameworks and state-level off-road vehicle registration requirements create fragmented compliance landscapes for imported powersports equipment. Queensland and Western Australia ranching operations drive commercial fleet procurement of utility ATVs with 1500-pound payload ratings. Sydney and Melbourne digital retailers aggregate used inventory through third-party platforms with variable certification standards for entry-level youth categories.
Online Powersports Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-rich manufacturers controlling captive certification laboratories while mid-scale assemblers rely on outsourced testing partnerships. The structure rewards backward integration into powertrain development and captive digital retail infrastructure over pure distribution plays. Three archetypes dominate: vertically integrated engineering houses with foundry-to-doorstep control, dual-channel operators balancing dealer density with manufacturer-direct configurators, and platform aggregators capturing transaction flow through mobile-first interfaces. Competitive moves concentrate on proprietary powertrain development and strategic partnerships for battery mineral sourcing.
Among North American integrated manufacturers, Polaris and BRP exemplify the vertically integrated archetype through Minnesota and Quebec-based production campuses. Yamaha Motor occupies a position bridging engineering-house capabilities with dual-channel retail sophistication. These three anchors represent distinct strategic vectors: captive supply chain control, Rotax engine portfolio specialization, and dealer-digital hybrid distribution respectively.
| Leading Market Players |
|---|
| Polaris |
| BRP |
| Yamaha Motor |
| Honda Motor |
| Harley-Davidson |
| Kawasaki Heavy Industries |
| KTM |
| Arctic Cat |
| RevZilla |
| Others |
Supply Flow & Price Mechanics
Silicon carbide MOSFET substitution for traditional IGBT inverters is redrawing procurement geography toward automotive-scale semiconductor suppliers while compressing power electronics margins for incumbent powersports vendors lacking 800-volt sourcing relationships. This input transition simultaneously elevates landed costs for premium electric side-by-side development and concentrates supplier bargaining power among wide-bandgap semiconductor foundries.
Pricing Analysis
Long-term offtake contracts dominate battery pack procurement for electric ATV programs, insulating assemblers from spot lithium carbonate volatility while locking in cathode precursor pricing. Price differentiation hinges on EPA Tier 3 certification tier and regional delivery logistics to Rocky Mountain markets. Cost compression in entry-level youth ATV segments is intensifying due to fixed-price digital pre-orders compressing assembler margins. Casual riders in Texas and Arizona markets exhibit highest price sensitivity, while guided tour fleet operators prioritize total cost of ownership over upfront unit pricing.
Supply Chain Analysis
Strategic stockpiling of steel and aluminum inputs prevails among Minnesota-based snowmobile assemblers to buffer commodity price swings through seasonal production cycles. Chassis fabrication draws from Ontario manufacturing corridors and Quebec foundry networks, while lithium-ion cell assembly rests on Chinese cathode precursor refining. Single-source vulnerability in battery mineral supply exposes landed cost volatility to export licensing shifts. Distribution runs through vertically integrated manufacturing campuses controlling fulfillment from foundry to doorstep delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where CARB certification entrenchment and captive laboratory infrastructure create switching costs that filter non-compliant entrants from digital channels.
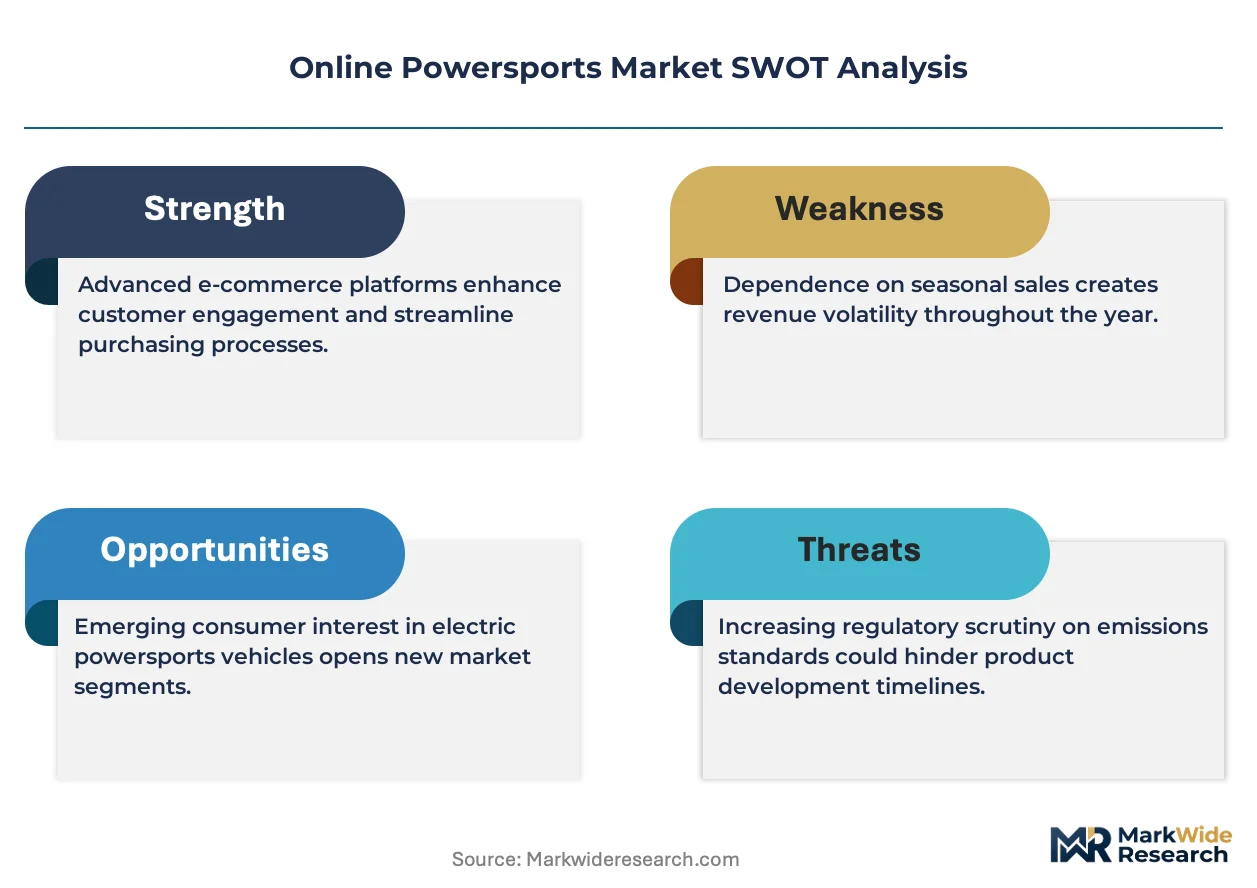
For Market Incumbents: Secure backward integration into battery thermal management testing protocols to accelerate model-year launch timelines against electric powertrain substitution pressure. Fortify captive digital retail infrastructure to capture financing margin from subscription-enabled lease-to-own instruments, countering fintech-enabled new entrants. For New Entrants and Emerging Players: Aftermarket telematics integration represents a service-layer gap where incumbents under-serve occasional-use recreational buyers seeking usage-based insurance products. Target fleet operator segments in Moab and Sedona with silent-running electric UTV configurations for noise-restricted canyon access, leveraging IRA commercial EV incentives as go-to-market leverage. For Investors and Strategic Acquirers: The market sits at a powertrain-transition phase that favors vertically integrated engineering houses with captive certification laboratories and foundry-to-doorstep supply chain control. Long-term viability centers on proprietary powertrain development capabilities and strategic battery mineral sourcing partnerships. Watch EPA Tier 4 pre-rulemaking signals as inflection indicator for accelerated gasoline engine substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Powertrain Electrification Roadmap | Accelerates Rotax and Polaris engineering programs toward 800-volt SiC architectures for hill-climb duty cycles. |
| CARB Certification Laboratory Investment | Creates evaporative emissions testing capacity that gates California digital market access for competing assemblers. |
| Mobile-First Configurator Deployment | Captures younger Texas and Arizona buyers completing purchase journeys without showroom negotiation. |
| Battery Mineral Supply Agreement | Reduces cathode precursor exposure to Chinese export licensing volatility for electric side-by-side programs. |
| Telematics Platform Integration | Enables pay-per-mile usage insurance products reducing total cost of ownership for occasional-use recreational segments. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with powersports OEM platform engineers, dealer operations directors, and fleet procurement managers at guided tour operators; and secondary validation through EPA certification filings, NHTSA safety databases, and Bureau of Land Management permit issuance records. Bottom-up transaction volume estimates from manufacturer-direct configurators and e-commerce platforms were triangulated against top-down macroeconomic indicators and regional demographic data.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, sales channel architecture, customer classification, and accessory category. CAGRs were derived from trend extrapolation of digital channel penetration rates, regulatory compliance cost trajectories, and electric powertrain substitution patterns. Industry-specific forecast inputs included Rocky Mountain trail permit expansion timelines and IRA commercial EV incentive qualification criteria.
Underlying assumptions cover stable lithium-ion cell supply chain conditions and continued CARB regulatory stringency, with deviation risk concentrated in battery mineral export licensing shifts and EPA emissions standard acceleration. Revision becomes warranted when electric powertrain performance parity crosses psychological thresholds for recreational displacement segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
North America Motorhome Market
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
US Electric UTV and ATV Powertrain Market
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
Snowmobile Trailer Axle Market
Recreational Vehicles
Global Segway Consumption Market
Recreational Vehicles
Caravanning Market
Recreational Vehicles
Electric Golf Cart Market