
 Ring Pull Caps Market | 2026-2036
Ring Pull Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Ring Pull Caps Market Analytics
The EU Green Deal is consolidating the cost-of-entry calculus for ring pull cap suppliers targeting European beverage accounts. Silgan Closures GmbH leverages its integrated aluminum supply chain to sustain margin stability under tightening carbon-border adjustments. Crown Holdings, Inc. anchors its position through high-volume production platforms across multiple continents. BERICAP GmbH & Co. KG differentiates via specialized coating technologies that reduce material thickness without sacrificing seal integrity.
Ring pull caps are single-use closures featuring an integrated lever mechanism that fractures a scored panel upon lifting, typically manufactured from 3104-H19 aluminum alloy or tinplate steel with internal plastisol liners to ensure hermetic sealing of carbonated and non-carbonated contents. Their primary purpose is to provide tamper-evident, tool-free access to beverage cans, food tins, and aerosol containers while maintaining internal pressure resistance up to 90 psi. Aluminum ring pull caps currently lead volume due to their recyclability alignment with circular economy mandates, while composite variants represent the fastest-expanding margin pool as brands seek hybrid solutions that blend metal rigidity with polymer weight reduction. The canned drinks application dominates unit demand, though nutritional supplements are emerging as a high-value niche where premium closure finishes command pricing premiums.
The EPA regulates volatile organic compound emissions from coating operations at US can closure plants, while REACH restricts certain chromium-based surface treatments across European supply chains. China's SAMR enforces GB standards for food-contact metal packaging that directly affect export-qualified cap specifications. Stakeholders must monitor how diverging national recycling targets reshape material specifications and certification requirements across their supplier networks.
Market Dynamics
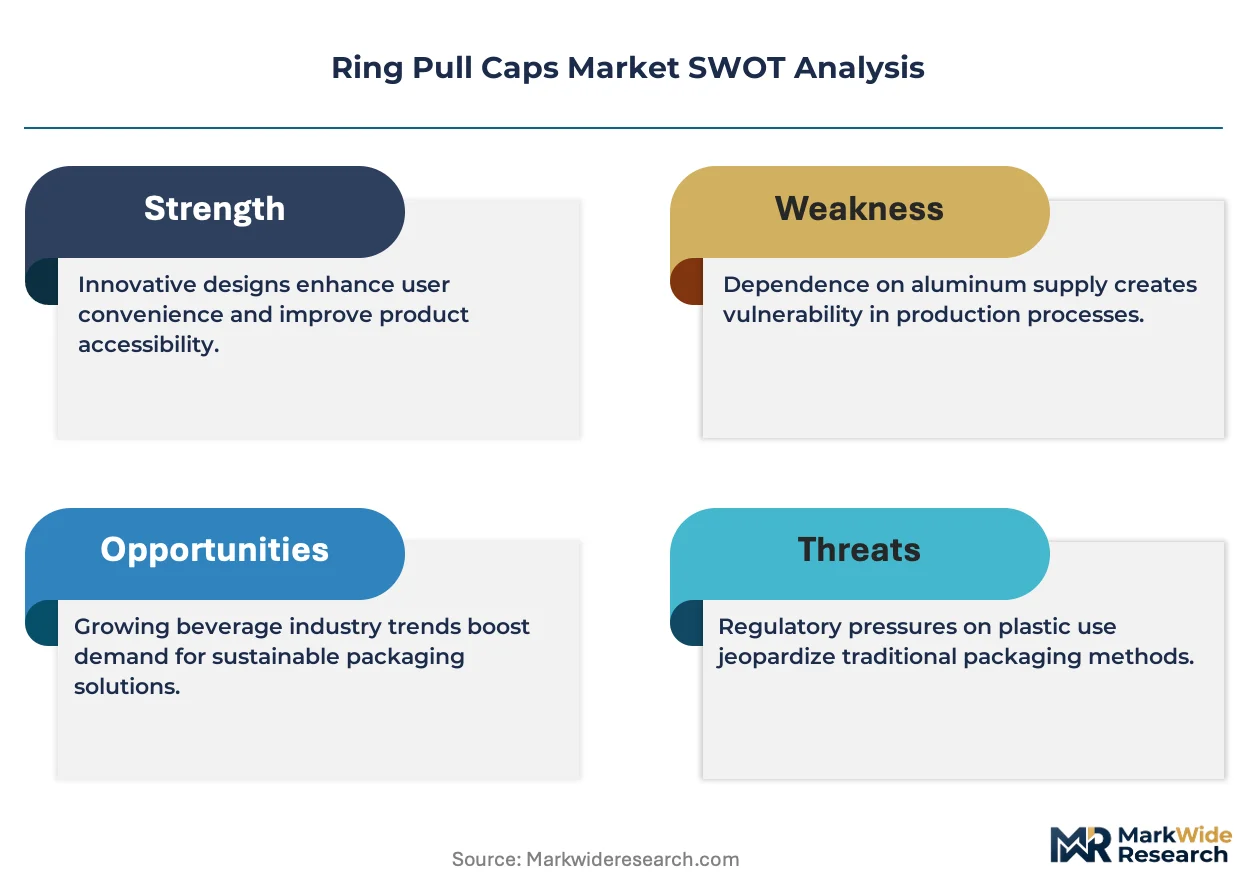
Aluminum alloy specification tightening under the EU Green Deal and F-Gas Regulation is forcing European closure suppliers to requalify their entire coating chemistry stack, while Southeast Asian canning capacity expansion pulls global production capacity toward Vietnam and Thailand.
Growth Catalysts
- EU F-Gas Regulation compliance:Beverage producers across Germany, France, and Italy are accelerating aluminum ring pull cap adoption to meet fluorinated gas phase-down mandates in cold-chain packaging.
- Southeast Asian canning hubs:Vietnam and Thailand beverage bottling capacity expansion is concentrating regional demand for 3104-H19 alloy closures with hermetic seal specifications.
- Recyclability alignment:Circular economy mandates in the EU and China's dual carbon goals are elevating aluminum closure preference over composite alternatives in carbonated drink applications.
Market Restraints
- Aluminum ingot price volatility:LME aluminum price swings directly compress margin stability for closure manufacturers locked into annual beverage supply contracts.
- Coating chemistry concentration:Chromium-based surface treatment restrictions under REACH have eliminated qualified European suppliers, creating single-source dependency for compliant plastisol liner formulations.
- Steel substitution threat:Tinplate ring pull caps retain cost advantage in non-carbonated food tins where pressure resistance requirements fall below 60 psi.
Strategic Opportunities
- Nutritional supplements niche:Premium closure finishes with embossed branding and matte coatings command pricing premiums in protein powder and vitamin aerosol segments.
- Hybrid composite development:Convergence of metal rigidity with polymer weight reduction is opening margin pools in ready-to-drink coffee cans where shelf differentiation drives purchase decisions.
- India beverage expansion:FSSAI food-contact compliance pathways and PLI scheme incentives for packaging localization are drawing capacity investment toward Mumbai and Delhi NCR bottling corridors.
Industry Challenges
- Coating technician scarcity:Volatile organic compound emission control expertise under EPA guidelines is concentrated among aging workforces at US Gulf Coast can closure plants.
- GB standard certification timelines:China's SAMR export qualification protocols for food-contact metal packaging extend validation cycles by 8-14 months for new alloy specifications.
- Legacy press retrofit requirements:Scored panel precision tooling for sub-0.25mm aluminum gauges demands capital replacement of mechanical stamping lines at European production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ring Pull Caps Market |
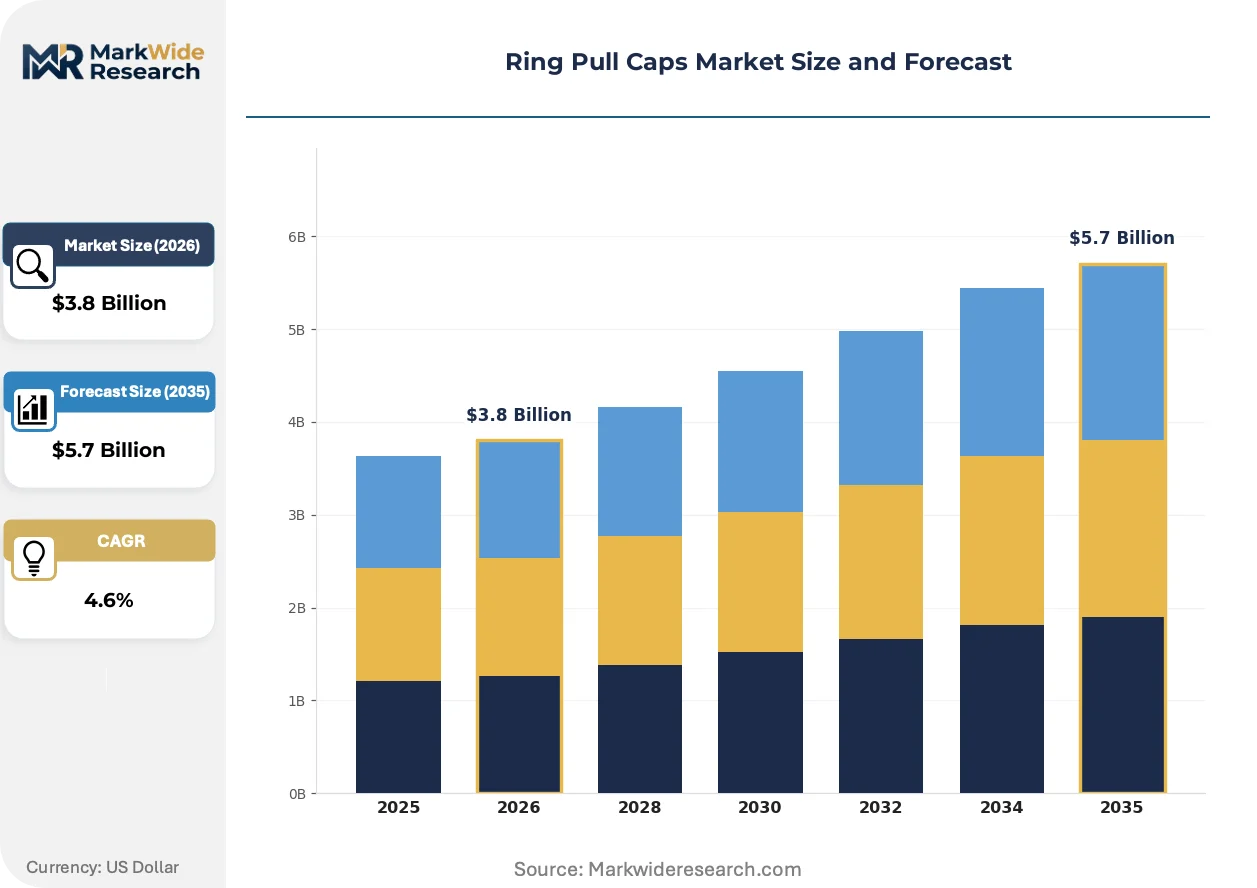
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Steel, Plastic, Composite End User: Beverage Industry, Food Packaging, Household Applications, Pharmaceutical Products Application: Canned Drinks, Ready-to-Eat Meals, Snacks, Nutritional Supplements Size: Standard, Mini, Large, Custom |
| Companies Covered | Silgan Closures GmbH, Berry Global Ltd., Finn-Korkki, Taiwan Hon Chuan Group, BERICAP GmbH & Co. KG, Pelliconi Ltd., Closure Systems International Inc., SACMI, Crown Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ring Pull Caps Market Evolving Landscape
Digital printing integration and alloy thinning technologies are compressing production economics while regulatory chemistry shifts and procurement model evolution reshape competitive positioning across beverage packaging supply chains.
Laser-etched QR codes and variable-data printing on ring pull cap surfaces are overtaking static embossed branding as beverage marketers pursue direct-to-consumer engagement through packaging. Energy drink and craft beer producers in the US and Germany are adopting this capability at pilot scale. The technology is overtaking traditional decoration methods by collapsing minimum order quantities from millions to tens of thousands while enabling regional campaign customization.
REACH restrictions on hexavalent chromium surface treatments are forcing European suppliers to migrate toward trivalent chrome and chrome-free passivation chemistries. This transition has eliminated three qualified coating houses in Eastern Europe since 2023. Aerosol and food tin segments with extended shelf-life requirements are absorbing the steepest compliance costs as they revalidate seal integrity under accelerated aging protocols.
Beverage brand procurement departments are consolidating closure supply agreements from multi-source spot purchasing to single-source partnership models with volume commitment clauses. This restructuring concentrates negotiation leverage with Silgan and Crown-scale suppliers while squeezing mid-tier European specialists. The shift is most visible in German and Dutch brewing conglomerates where technical service integration and joint R&D roadmaps now accompany multi-year contracts.
Ring Pull Caps Market Segmentation
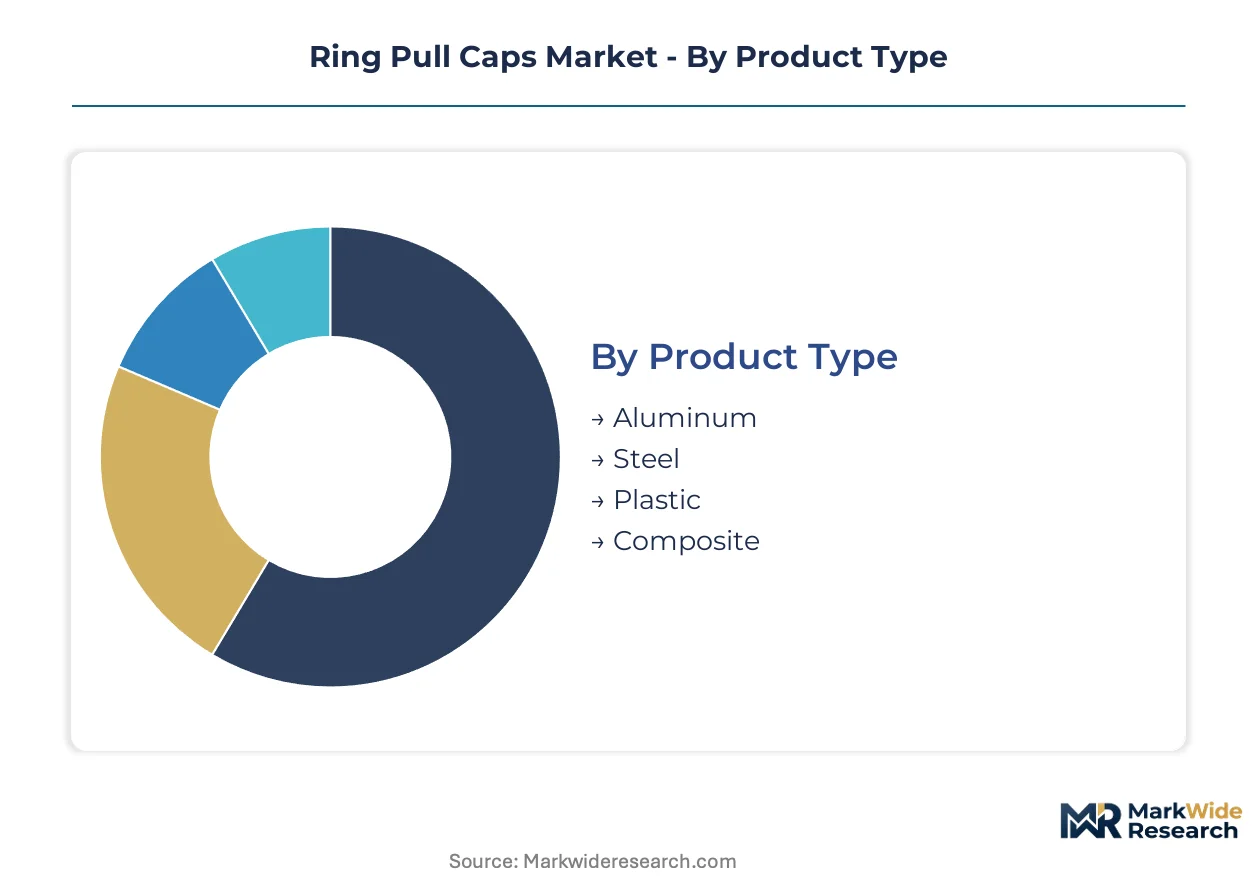
Ring pull cap specifications diverge sharply across beverage carbonation pressures, food sterilization requirements, and pharmaceutical barrier demands. Material selection and dimensional precision determine seal integrity performance, recyclability compliance, and line-speed compatibility at canning facilities.
Product Type:
Aluminum alloy grades and coating chemistries define pressure resistance thresholds and circular economy qualification pathways.
- Aluminum:3104-H19 alloy delivers 90 psi pressure resistance with hermetic plastisol liners, dominating carbonated beverage applications across Vietnam and Thailand canning hubs where recyclability mandates concentrate procurement decisions.
- Steel:Tinplate construction retains cost advantage below 60 psi pressure thresholds, serving non-carbonated food tins where EU F-Gas Regulation compliance costs do not apply.
- Plastic:Polymer formulations target lightweighting specifications in aerosol segments.
- Composite:Hybrid metal-polymer structures blend rigidity with weight reduction for ready-to-drink coffee differentiation.
Aluminum leads on scale; composite structures lead on momentum.
End User:
Customer procurement models range from high-volume annual contracts to specialized validation protocols for barrier-critical applications.
- Beverage Industry:German and Dutch brewing conglomerates consolidate supply agreements into single-source partnerships with volume commitment clauses and joint R&D roadmaps.
- Food Packaging:Extended shelf-life requirements drive chrome-free passivation chemistry adoption under REACH restrictions.
- Household Applications:Aerosol segments absorb steepest coating revalidation costs for seal integrity protocols.
- Pharmaceutical Products:Barrier specifications demand specialized liner formulations with accelerated aging validation cycles.
Beverage industry leads on scale; pharmaceutical products lead on margin capture.
Application:
Pressure differential and shelf-life duration dictate material thickness, liner chemistry, and scored panel precision requirements.
- Canned Drinks:Carbonation pressures up to 90 psi specify 3104-H19 aluminum with hermetic plastisol seals, absorbing the majority of Southeast Asian capacity expansion.
- Ready-to-Eat Meals:Retort sterilization compatibility requires modified coating stacks for thermal cycling resistance.
- Snacks:Lower pressure thresholds permit tinplate substitution where cost minimization dominates procurement.
- Nutritional Supplements:Premium embossed branding and matte coatings command pricing premiums in protein powder and vitamin aerosol niches.
Canned drinks lead on scale; nutritional supplements lead on pricing power.
Size:
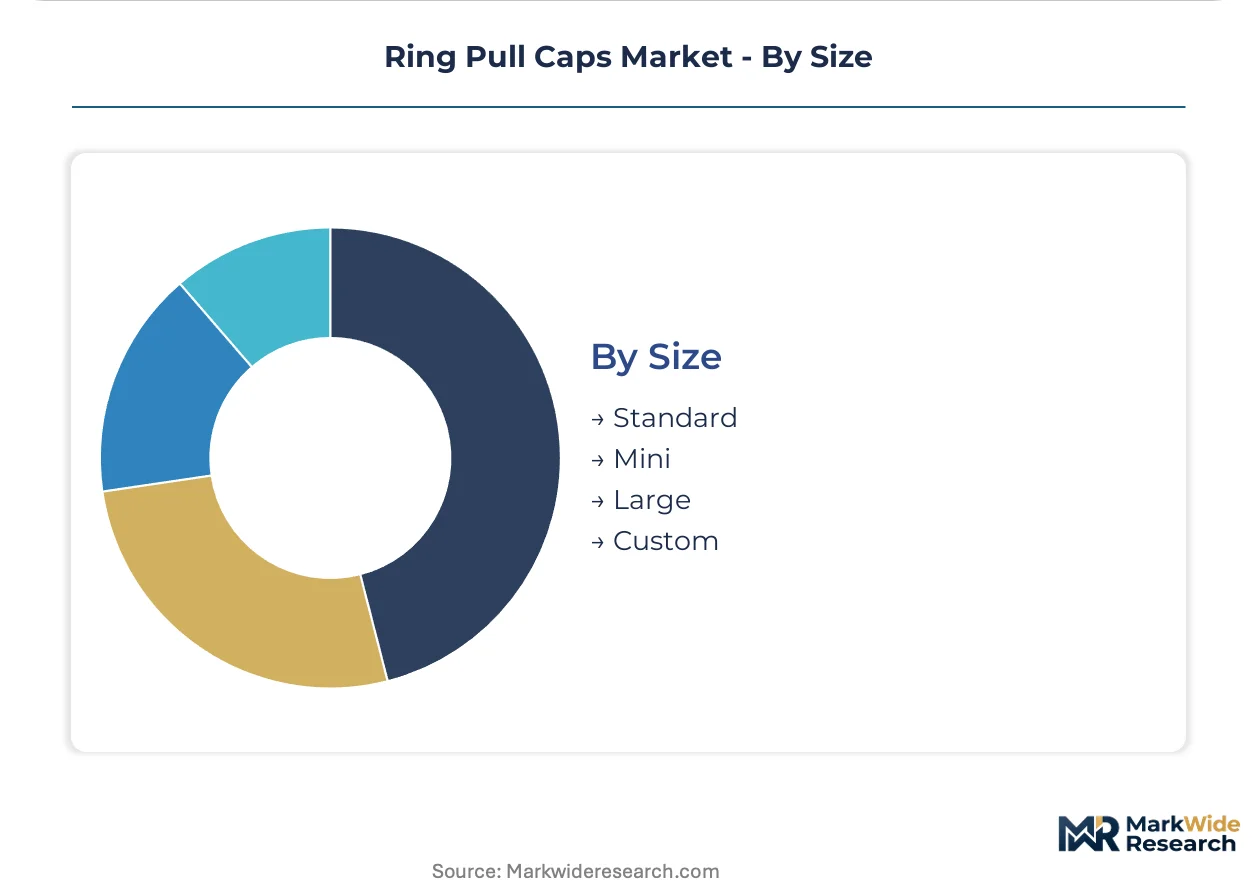
Dimensional standardization versus customization determines tooling capital requirements and minimum order quantity flexibility.
- Standard:202 and 206 diameter specifications dominate high-volume beverage canning lines across mass-market production platforms.
- Mini:Single-serve formats align with portion-control trends in nutritional supplement positioning.
- Large:Family-size containers require reinforced scored panel geometry for reliable lever actuation.
- Custom:Digital printing integration enables regional campaign customization with collapsed minimum order quantities.
Standard leads on scale; custom leads on marketing agility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized coating technicians and aluminum metallurgists concentrate in Germany's Ruhr Valley and China's Yangtze Delta, anchoring the technical workforce that enables precision closure manufacturing across three continents.
Germany
German beverage conglomerates in Bavaria and North Rhine-Westphalia are consolidating procurement into single-source partnerships with volume commitments. The EU F-Gas Regulation and EU Green Deal mandate fluorinated gas phase-downs, forcing coating chemistry requalification. Closure fabrication clusters around Siegen and Solingen absorb compliance costs through integrated aluminum supply chains.
United States
Energy drink and craft beer producers in Texas and Colorado are piloting laser-etched QR codes for direct-to-consumer engagement. EPA volatile organic compound emission controls govern coating operations at Gulf Coast can closure plants. Technical service expertise concentrates in aging workforces across Ohio and Pennsylvania stamping facilities.
China
Export-qualified cap manufacturers in Guangdong and Zhejiang provinces face extended SAMR validation cycles for GB standard food-contact compliance. The country's dual carbon goals elevate aluminum closure preference over composites in carbonated applications. Yangtze River Delta canning hubs near Shanghai and Ningbo scale 3104-H19 alloy production for Southeast Asian export.
Vietnam
Beverage bottling capacity expansion in Ho Chi Minh City and Binh Duong province concentrates regional demand for hermetic seal specifications. The country's packaging localization incentives draw equipment investment from multinational closure suppliers. Canning corridors along the Mekong Delta absorb the majority of Southeast Asian aluminum ring pull cap volume growth.
India
FSSAI food-contact compliance pathways and PLI scheme incentives are drawing capacity investment toward Mumbai and Delhi NCR bottling corridors. Nutritional supplement brands in Maharashtra command premium pricing for embossed branding and matte coating finishes. Gujarat-based aluminum processors supply substrate to closure fabricators serving domestic ready-to-drink coffee expansion.
Ring Pull Caps Market Competitive Landscape
The competitive structure tilts toward integrated aluminum specialists with captive metallurgy capabilities. Tier-one suppliers anchor multi-continent production platforms while mid-tier European coating houses face elimination under REACH chemistry restrictions. Three archetypes dominate: integrated aluminum-metallurgy players, precision-coating specialists, and high-volume stamping operators. Consolidation through single-source procurement partnerships and backward integration into aluminum substrate supply represent the dominant competitive moves reshaping supplier relationships.
Among Germany-based integrated specialists, Silgan Closures GmbH and BERICAP GmbH & Co. KG exemplify the metallurgy-coating convergence archetype, occupying positions where aluminum supply chain control meets specialized liner formulation expertise. Crown Holdings, Inc. represents the scale-driven multinational tier with production footprint across multiple continents. Taiwan Hon Chuan Group anchors the Asia-Pacific fabrication vector, sitting within the export-qualified supplier tier serving SAMR-regulated markets.
| Leading Market Players |
|---|
| Silgan Closures GmbH |
| Berry Global Ltd. |
| Finn-Korkki |
| Taiwan Hon Chuan Group |
| BERICAP GmbH & Co. KG |
| Pelliconi Ltd. |
| Closure Systems International Inc. |
| SACMI |
| Crown Holdings, Inc. |
| Others |
Value Network & Pricing Analysis
Captive aluminum supply chains anchor both cost position and pricing power for integrated closure manufacturers serving European beverage accounts under EU Green Deal compliance mandates. German and Dutch brewing conglomerates leverage single-source partnership structures to compress procurement leverage while locking in volume commitments that stabilize input cost pass-through.
Pricing Analysis
Bundled technical service and joint R&D roadmaps separate premium-tier suppliers from unbundled spot-market competitors in German and Dutch procurement consolidation. Price differentiation rests on REACH-compliant coating chemistry certification and hermetic seal performance under accelerated aging protocols. Cost compression in standard-grade aluminum closures is intensifying because LME aluminum price volatility erodes margin stability for annual contract manufacturers. Beverage conglomerates exhibit lowest price sensitivity due to regulatory compliance requirements, while regional Southeast Asian bottlers absorb highest price elasticity.
Supply Chain Analysis
Regional distribution centers in Germany's Ruhr Valley and China's Yangtze Delta feed hub-and-spoke patterns into Vietnam and Thailand canning corridors. Supply concentration centers on Germany, China, and Vietnam for 3104-H19 alloy substrate, plastisol liner formulations, and precision stamping equipment. Raw material dependencies draw from LME-traded aluminum ingot, chromium-free passivation chemicals, and specialized coating resins. Single-source vulnerability for REACH-compliant coating houses in Eastern Europe creates supply chain risk. Distribution runs through integrated aluminum-metallurgy players with captive substrate production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ring pull caps market reads as a late-cycle quality story justified by nutritional supplement brands commanding pricing premiums for embossed branding and matte coating finishes. Specification tightening under EU F-Gas Regulation and REACH chemistry restrictions elevates premium-tier supplier preference.
For Market Incumbents: To counter REACH-driven coating house elimination in Eastern Europe, backward integration into aluminum substrate supply secures margin stability under carbon-border adjustments. Joint R&D roadmaps with German beverage conglomerates lock in multi-year volume commitments that resist spot-market price erosion. For New Entrants and Emerging Players: Laser-etched QR code integration capability opens white-space targeting of US energy drink and craft beer pilot programs. Nutritional supplement aerosol segments in Maharashtra present the most penetrable geography for premium closure finishes. Go-to-market positioning through FSSAI compliance pathways in Mumbai bottling corridors bypasses established European supply relationships. For Investors and Strategic Acquirers: Roll-up economics work for precision-coating specialists because REACH restrictions have eliminated three qualified European suppliers since 2023. Five-to-ten year viability favors acquisition targets with trivalent chrome or chrome-free passivation chemistry validation. The signal to watch is SAMR GB standard certification timeline compression for export-qualified Chinese manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Substrate | Crown Holdings and Silgan leverage captive metallurgy to sustain margins under EU carbon-border adjustments. |
| REACH-Compliant Coating Chemistry Migration | Trivalent chrome adoption eliminates Eastern European competitors and consolidates supply among qualified houses. |
| Digital Printing Capability Investment | Laser-etched QR codes collapse minimum order quantities for US craft beer regional campaign customization. |
| Southeast Asian Capacity Expansion | Vietnam and Thailand bottling corridors absorb equipment investment from multinational closure suppliers. |
| Single-Source Partnership Consolidation | German brewing conglomerates concentrate leverage with Silgan-scale suppliers through volume commitment clauses. |
Research Methodology
Multiple input streams — primary interviews with coating technicians, procurement managers at German beverage conglomerates, and aluminum metallurgists in the Yangtze Delta — were reconciled against secondary validation from SAMR GB standard filings, REACH restriction notices, and SEC disclosures by integrated packaging suppliers. Bottom-up demand modeling across canned drinks, nutritional supplements, and aerosol applications triangulated with top-down aluminum closure consumption estimates derived from beverage canning capacity databases.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmentation by material type, end-use industry, and application pressure requirements. CAGRs were derived from installed canning capacity expansion trajectories in Vietnam and Thailand, alloy specification adoption curves under EU regulatory mandates, and pricing elasticity estimates for premium versus standard-grade closures. Industry-specific forecast inputs included F-Gas Regulation phase-down schedules and SAMR export qualification protocol timelines.
The model holds under sustained regulatory enforcement of REACH and EU Green Deal mandates; deviation in aluminum LME price volatility or coating chemistry innovation breakthroughs would shift competitive positioning. Forecasts reflect documented assumptions about Southeast Asian bottling capacity expansion and European compliance cost pass-through. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Side Pour Caps Market
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
Plastic Sifter Caps Market
Caps and Closures
Brush Caps Market
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
Global Aluminum Caps and Closures Market
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Latin America Metal Caps and Closures Market
Caps and Closures
Spout Closures Market
Caps and Closures
Cap Liner Market