
 Dispensing Caps Market | 2026-2036
Dispensing Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Dispensing Caps Market Outlook
ISO 8317 child-resistant packaging certification is rotating supplier eligibility across North America and Europe, disqualifying molders without validated testing protocols. AptarGroup Inc. leverages precision dosing technology to dominate pharmaceutical closure contracts. Silgan Holdings Inc. sustains massive throughput across food and beverage dispensing platforms through backward integration into resin compounding. Berry Global Inc. competes on sustainability credentials with post-consumer recycled content pipelines.
Dispensing caps are engineered closures incorporating orifices, valves, or pumps that meter controlled product release from rigid or flexible containers, typically manufactured through injection molding or compression molding with tolerances below 0.1 mm for seal surfaces. Their primary purpose is to preserve shelf stability while enabling precise consumer-directed flow of liquids, creams, powders, or aerosols. Plastic screw-on closures anchor the highest volume tier across beverage and household applications where cost thresholds dominate procurement. Push-button mechanisms represent the fastest-growing closure type in cosmetics and pharmaceuticals where single-hand operation commands premium positioning. Flip-top formats occupy mature growth trajectories in personal care, with margin pools concentrating in custom color-matched and embossed variants.
FDA 21 CFR regulations govern pharmaceutical dispensing cap performance in the United States, while EMA guidelines and REACH compliance shape European material approvals and migration limits. India's BIS certification and PLI scheme for packaging materials are redirecting domestic capacity toward export-grade pharmaceutical closures. Stakeholders must monitor evolving extended producer responsibility frameworks in the EU and state-level recycled content mandates in California and New York to anticipate resin specification shifts.
Market Dynamics
Pharmaceutical closure certification is concentrating supplier eligibility around ISO 8317-validated molders, while resin lightweighting and child-resistant mechanism patents are compressing margins for undifferentiated commodity producers.
Growth Catalysts
- FDA 21 CFR pharmaceutical compliance:Child-resistant and tamper-evident mandates in the United States are disqualifying uncertified molders and redirecting procurement toward validated suppliers.
- Polypropylene material innovation:Unit weight reductions of 15-20% are preserving seal integrity while cutting resin costs for beverage and household brands.
- Germany contract manufacturing clusters:Precision dosing technology hubs around Stuttgart and Munich are capturing regional pharmaceutical brand owner contracts.
Market Restraints
- Propylene feedstock volatility:Crude oil and naphtha price swings are compressing margin predictability for injection molders dependent on virgin resin contracts.
- REACH migration limit compliance:ECHA substance restrictions on additives and colorants are extending material qualification timelines for European pharmaceutical closures.
- Biodegradable polymer substitution:Paperboard pumps and fiber-based dispensing systems are displacing conventional plastic caps in premium cosmetics segments.
Strategic Opportunities
- India PLI scheme for packaging:Production-linked incentives are redirecting domestic capacity toward export-grade pharmaceutical closures for regulated markets.
- Connected dispensing integration:NFC-enabled caps with dose-tracking are converging with mobile health platforms in chronic disease management applications.
- Direct-to-consumer pharmacy channels:E-commerce fulfillment is demanding single-unit protective packaging with enhanced child-resistance for home delivery.
Industry Challenges
- ISO 8317 certification timeline:Six-to-twelve month validation protocols are delaying new supplier entry and freezing contract rotations.
- Multi-cavity mold capex intensity:High-speed compression molding lines require capital deployment that mid-tier molders cannot access.
- Legacy ERP integration:Track-and-trace serialization mandates are forcing incompatible MES upgrades across aging production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispensing Caps Market |
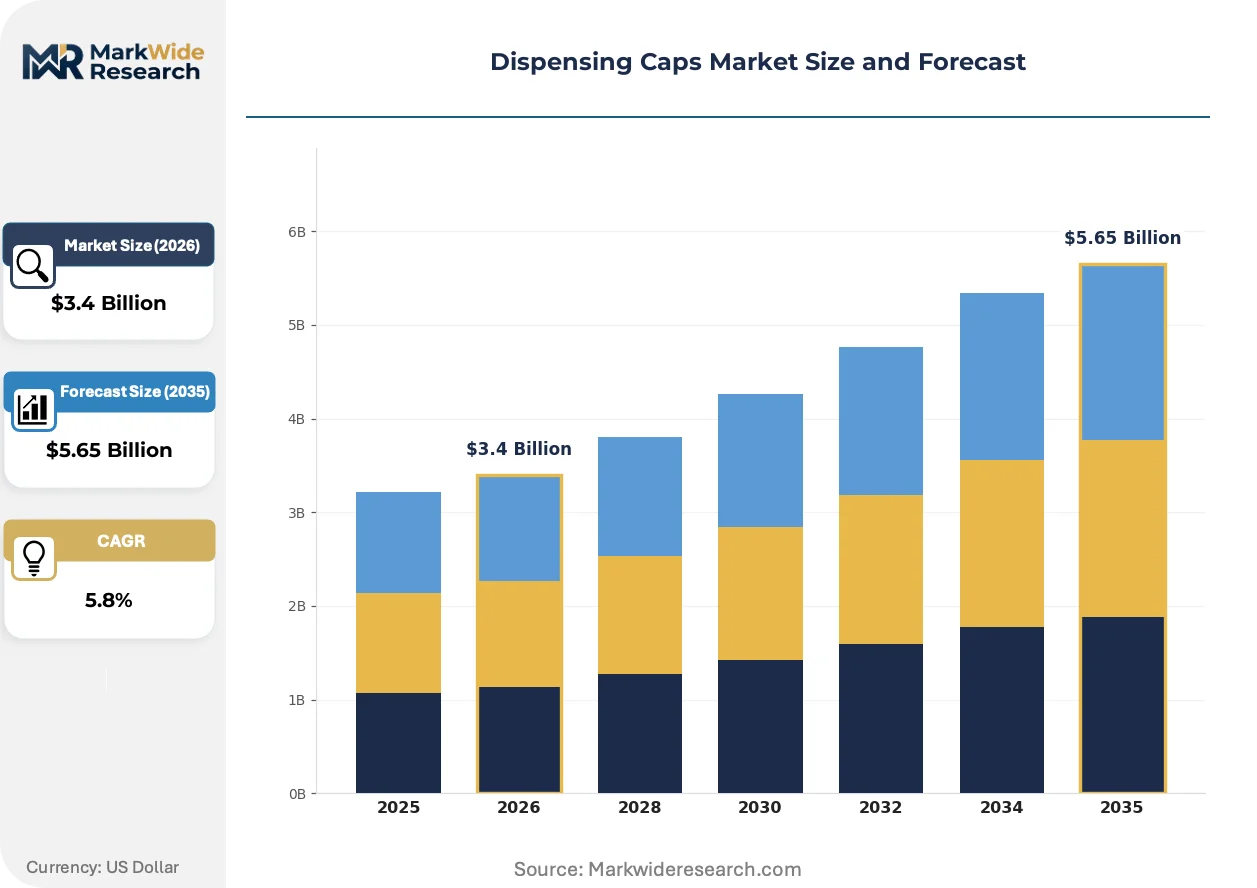
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Metal, Rubber, Glass Closure Mechanism: Screw-On, Snap-On, Flip-Top, Push-Button End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Application: Liquid Dispensing, Powder Dispensing, Cream Dispensing, Aerosol Dispensing |
| Companies Covered | Silgan Holdings Inc., AptarGroup Inc., Amcor plc, United Caps, Guala Closures Group, Closure Systems International, BERICAP, Berry Global Inc., Phoenix Closures Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispensing Caps Market Strategic Shifts
Precision dosing mechanisms and connected closure technologies are fragmenting the traditional screw-cap commodity tier, while regulatory serialization and sustainability mandates are rewriting material specifications and supplier qualification protocols.
Mono-material polypropylene dispensing architectures are fragmenting multi-component closure designs across pharmaceutical and personal care segments. Brand owners in Germany and Switzerland are specifying all-PP pumps and caps to meet EFSA recycling stream requirements. This convergence is compressing demand for spring-loaded metal valves and silicone gaskets previously standard in premium positioning.
EMA serialization and anti-tampering directives are mandating unique identifier integration at the closure level for prescription pharmaceuticals. Molders serving European markets are retrofitting production lines with vision systems and laser marking stations. The cost burden falls heaviest on mid-volume generic drug suppliers without captive packaging operations.
Subscription pharmacy fulfillment is compressing traditional wholesale channel dominance for dispensing closures. CVS and Walgreens central fill operations are specifying child-resistant compliance at unit-dose rather than case-level, forcing redesign of secondary packaging assumptions. This behavioral pivot is most visible in United States diabetes and respiratory therapeutic categories where home delivery penetration exceeds 40%.
Dispensing Caps Market Segmentation
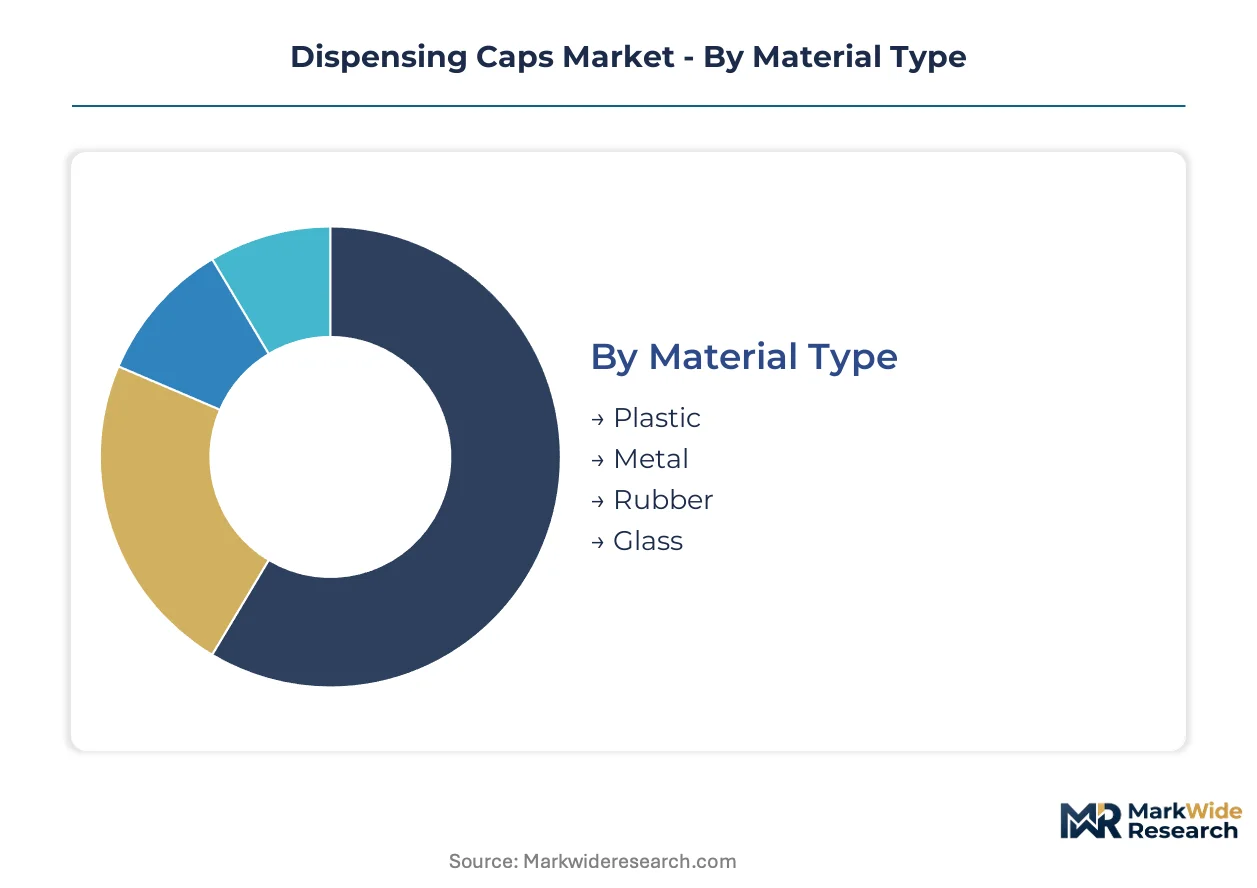
Dispensing caps fragment across material chemistry, closure mechanics, and end-use performance requirements. Each segment carries distinct certification burdens and channel concentration patterns that reshape supplier economics.
Material Type:
Channel distribution varies sharply by resin specification and recyclability credentials.
- Plastic:Polypropylene and HDPE formulations dominate beverage and household procurement through injection molding platforms. FDA 21 CFR compliance and EFSA recycling stream requirements are compressing multi-resin designs toward mono-material architectures in Germany and Switzerland.
- Metal:Aluminum and steel closures serve premium spirits and pharmaceutical aerosol segments where oxygen barrier performance commands unit price premiums. REACH migration limit compliance extends material qualification timelines for European pharmaceutical applications.
- Rubber:Silicone and EPDM gaskets seal pump mechanisms in cosmetics and topical pharmaceuticals.
- Glass:Borosilicate and soda-lime dispensing closures serve laboratory reagent and high-purity pharmaceutical segments.
By volume, plastic leads. By sustainability-driven specification shifts, metal is gaining share fastest.
Closure Mechanism:
Cost tier stratification separates commodity screw caps from precision-engineered alternatives.
- Screw-On:Threaded plastic closures anchor the highest volume tier across beverage and bulk household chemical channels. Unit weight reductions of 15-20% through polypropylene innovation are preserving seal integrity while cutting resin input costs for cost-sensitive brand owners.
- Push-Button:Single-hand actuation mechanisms command premium positioning in cosmetics and over-the-counter pharmaceuticals. CVS and Walgreens central fill operations are specifying child-resistant push-button compliance at unit-dose level for diabetes and respiratory therapeutic home delivery.
- Snap-On:Friction-fit closures serve single-use food service and institutional cleaning product segments.
- Flip-Top:Hinged dispensing formats occupy mature trajectories in personal care where custom color-matching and embossing concentrate margin pools.
By installed base, screw-on dominates. By growth trajectory, push-button mechanisms are expanding most quickly.
End User:
Customer type dictates regulatory burden intensity and contract duration.
- Pharmaceuticals:ISO 8317 child-resistant certification and EMA anti-tampering mandates concentrate procurement around validated molders with six-to-twelve month qualification protocols. India's PLI scheme is redirecting domestic capacity toward export-grade pharmaceutical closures for regulated markets.
- Food & Beverage:High-throughput beverage bottlers prioritize resin lightweighting and compression molding speed over mechanism complexity. Backward integration into resin compounding sustains margin capture for volume leaders.
- Cosmetics:Premium positioning demands mono-material pump architectures and connected closure integration with mobile health platforms.
- Household Products:Bleach, detergent, and surface cleaner brands trade seal reliability against cost thresholds in private-label procurement.
By contract value, pharmaceuticals lead. By volume throughput, food and beverage is ahead.
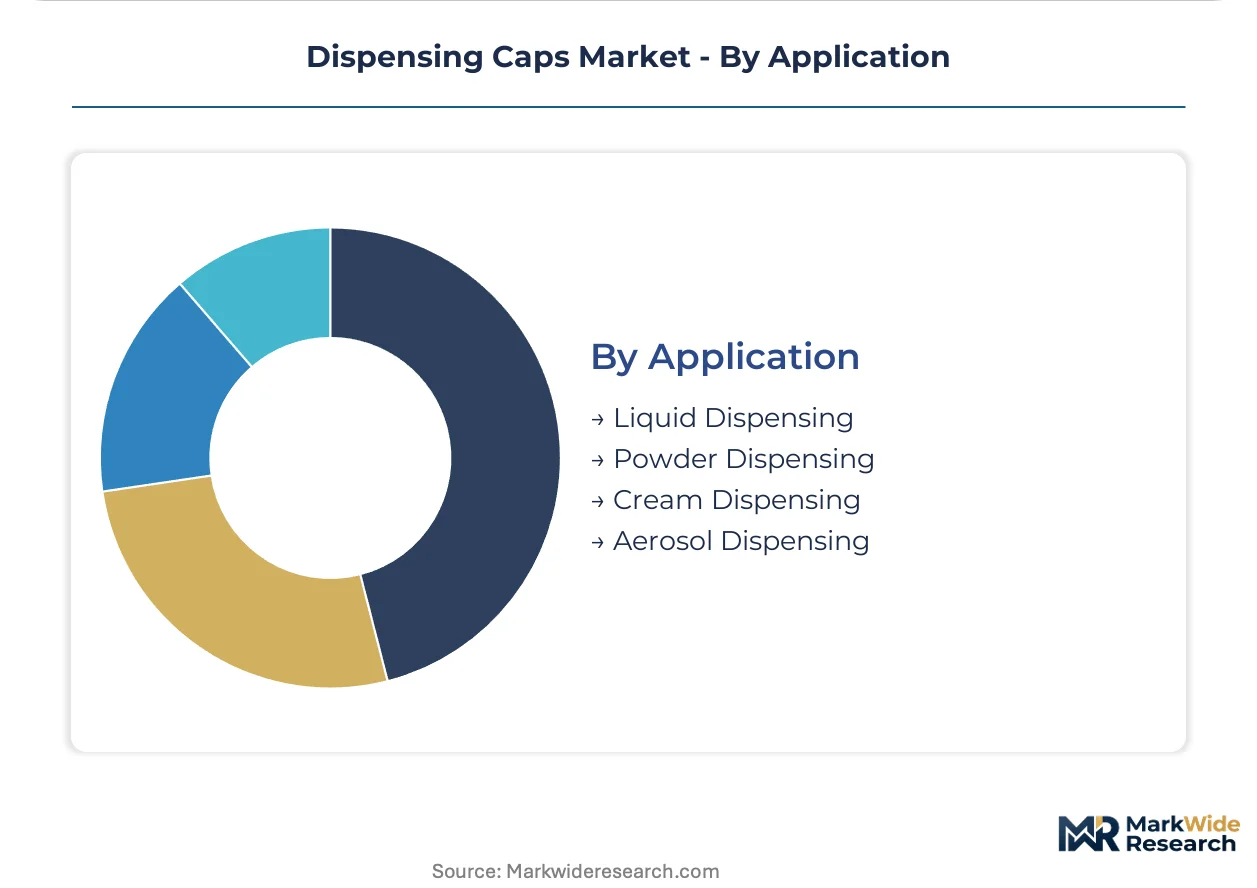
Application:
Supply concentration clusters around precision dosing requirements versus commodity flow control.
- Liquid Dispensing:Orifice and valve designs meter controlled release across beverage, pharmaceutical, and personal care segments. Precision dosing technology hubs around Stuttgart and Munich are capturing regional pharmaceutical brand owner contracts.
- Cream Dispensing:Viscous product pumps with silicone gaskets serve topical pharmaceutical and skincare segments. Mono-material polypropylene architectures are displacing spring-loaded metal valves previously standard in premium positioning.
- Powder Dispensing:Shaker orifices and sift-fitments package spices, infant formula, and dry pharmaceuticals.
- Aerosol Dispensing:Crimped valve assemblies for pressurized products face propellant regulation shifts.
By unit volume, liquid dispensing leads. By technology premiumization, cream dispensing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for packaging materials is redirecting domestic capacity toward export-grade pharmaceutical closures. Germany's precision dosing technology clusters capture regional brand owner contracts. United States FDA 21 CFR compliance mandates disqualify uncertified molders.
United States
CVS and Walgreens central fill operations specify child-resistant compliance at unit-dose level for diabetes and respiratory therapeutic home delivery. FDA 21 CFR pharmaceutical regulations govern closure performance standards. New Jersey and Pennsylvania house contract manufacturing clusters serving generic drug suppliers.
Germany
Stuttgart and Munich precision dosing technology hubs capture regional pharmaceutical brand owner contracts. EMA serialization and anti-tampering directives mandate unique identifier integration at closure level. Baden-Württemberg molders retrofit production lines with vision systems and laser marking stations.
India
BIS certification and PLI scheme for packaging materials redirect domestic capacity toward export-grade pharmaceutical closures for regulated markets. CDSCO pharmaceutical regulations align with FDA and EMA standards. Maharashtra and Gujarat contract manufacturing clusters serve regional and export brand owners.
Switzerland
Brand owners specify all-PP pumps and caps to meet EFSA recycling stream requirements. Swissmedic pharmaceutical regulations enforce stringent quality standards. Basel-Zurich corridor precision molders develop mono-material polypropylene dispensing architectures.
China
NMPA pharmaceutical regulations drive adoption of child-resistant and tamper-evident closure designs. Yangtze River Delta injection molding clusters supply domestic and export beverage markets. Shanghai and Jiangsu province manufacturers invest in high-speed compression molding lines.
Dispensing Caps Market Competitive Environment
Player mix skews toward diversified packaging conglomerates with captive resin operations and precision dosing specialists holding pharmaceutical certification. Structure concentrates around ISO 8317-validated molders with six-to-twelve month qualification protocols freezing contract rotations. Two strategic archetypes dominate: backward-integrated volume leaders capturing food and beverage throughput, and certification-heavy specialists commanding pharmaceutical premium tiers. Competitive moves center on portfolio diversification into connected closure technologies and geographic expansion through India PLI scheme participation.
Within the diversified packaging conglomerate tier, Silgan Holdings Inc. and Berry Global Inc. represent backward-integrated volume leaders with captive resin compounding operations. AptarGroup Inc. occupies the precision dosing specialist position, exemplifying certification-heavy pharmaceutical focus. These three companies anchor the competitive structure across beverage, pharmaceutical, and personal care closure segments.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| AptarGroup Inc. |
| Amcor plc |
| United Caps |
| Guala Closures Group |
| Closure Systems International |
| BERICAP |
| Berry Global Inc. |
| Phoenix Closures Inc. |
| Others |
Value Chain & Pricing Dynamics
Mono-material polypropylene substitution for multi-component closure designs simultaneously shifts procurement geography toward Germany and Switzerland while compressing pricing premiums previously commanded by metal valve assemblies. This material pivot redraws supplier economics as EFSA recycling stream requirements harden.
Pricing Analysis
Cost-plus contracts indexed to propylene feedstock benchmarks dominate procurement between resin-integrated molders and beverage brand owners. Price differentiation separates ISO 8317-certified pharmaceutical specialists from commodity screw-cap producers, with certification tier and volume scale as primary levers. Pricing pressure stems from REACH migration limit compliance extending European material qualification timelines. Generic drug suppliers exhibit highest price sensitivity due to thin margin structures, while precision dosing specialists serving diabetes and respiratory therapeutic categories maintain lowest sensitivity.
Supply Chain Analysis
Germany and India anchor pharmaceutical-grade dispensing cap production, while China and the United States supply high-volume beverage and household applications. Propylene monomer, colorant additives, and multi-cavity mold tooling constitute critical input dependencies. Single-source vulnerability concentrates around ISO 8317-validated testing protocols that freeze supplier rotations for six-to-twelve month qualification windows. Distribution runs through contract manufacturing clusters serving regional brand owners, with central fill pharmacy operations bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dispensing caps market sits in a cyclical recovery phase driven by pharmaceutical serialization mandates forcing closure-level technology refreshes across European and North American supply bases.
For Market Incumbents: Fortify ISO 8317 certification portfolios against emerging biodegradable polymer substitutes in premium cosmetics segments. Deepen backward integration into resin compounding to offset propylene feedstock volatility compressing margin predictability. Prioritize captive production of mono-material polypropylene architectures to defend positioning as EFSA recycling requirements harden. For New Entrants and Emerging Players: Anchor in India's PLI scheme for packaging materials to capture export-grade pharmaceutical closure demand redirecting from established European molders. Target Maharashtra and Gujarat contract manufacturing clusters where BIS certification alignment with FDA and EMA standards lowers regulatory entry barriers. Pursue connected dispensing integration partnerships with mobile health platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors certification-heavy specialists over undifferentiated commodity producers. Long-term viability hinges on five-to-ten year pharmaceutical compliance moats around child-resistant mechanism patents and precision dosing technology. Acquisition targets should display validated ISO 8317 protocols with installed vision systems and laser marking stations. Watch EMA serialization directive enforcement intensity as the inflection signal for contract manufacturing cluster valuations.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 8317 Certification Investment | Six-to-twelve month validation protocols freeze competitor entry and secure pharmaceutical contract rotations. |
| Mono-Material PP Architecture Development | All-polypropylene pump designs meet EFSA recycling requirements specified by German and Swiss brand owners. |
| Connected Dispensing Integration | NFC-enabled dose-tracking caps converge with CVS and Walgreens central fill operations for diabetes therapeutic delivery. |
| India PLI Scheme Participation | Production-linked incentives redirect domestic capacity toward export-grade pharmaceutical closures for regulated markets. |
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates margin predictability against crude oil and naphtha price swings. |
Study Parameters
Cross-validation between primary interviews with molders, pharmaceutical packaging procurement managers, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA 21 CFR filings, EMA serialization directives, and BIS certification records. Plant managers at injection molding facilities, brand owner packaging engineers, and contract manufacturing cluster operators provided operational perspective. Customs data tracking propylene derivative trade flows, SEC 10-K disclosures from packaging conglomerates, and CDSCO pharmaceutical packaging guidelines supplied quantitative grounding. Bottom-up capacity assessments triangulate against top-down demand modeling across end-use segments.
Sensitivity analysis frames volume and value outputs across material type, closure mechanism, and end-use performance requirements, with pharmaceutical certification tier and regional regulatory cluster as additional segmentation dimensions. CAGRs derive from regression-based trend extrapolation calibrated to disclosed capacity additions and contract award patterns. Propylene feedstock price assumptions and ISO 8317 certification timeline distributions constitute key forecast inputs throughout the projection horizon.
Decision-makers should treat outputs as directional under sustained pharmaceutical compliance tightening and resin lightweighting adoption curves; material deviation in biodegradable polymer substitution rates or REACH enforcement intensity would warrant model refresh. Recalibration cycles align with material shifts in EMA serialization directive implementation and India PLI scheme capacity commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Screw Caps and Closure Market
Caps and Closures
Metal Closures Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Fez Caps Market
Caps and Closures
South Africa Plastic Caps and Closures Market
Caps and Closures
PCR Closures Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
India Plastic Caps and Closures Market
Caps and Closures
Polypropylene Screw Caps Market
Caps and Closures
Dauber Caps Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Latin America Plastic Caps and Closure Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Peelable Lid Stock Market