
 Screw Caps and Closure Market | 2026-2036
Screw Caps and Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Screw Caps and Closure Market Analytics
A capital-intensity divergence between high-volume injection molders and precision metal-forming specialists is rotating competitive advantage toward integrated resin-to-cap producers. Berry Global Inc. leverages captive polymer compounding across North American plants to compress cycle times. Silgan Holdings Inc. anchors its position through deep relationships with metal beverage can customers requiring matched closure supply. Amcor Plc competes via global footprint scale, positioning thermoformed and injection-molded closures adjacent to its flexible packaging operations.
Screw caps and closures are threaded sealing devices manufactured from thermoplastic resins, aluminum, or steel, typically featuring internal lugs or continuous helical threads that mate with container neck finishes to form repeatable hermetic seals. Injection molding of polypropylene and high-density polyethylene dominates plastic closure production, with compression molding gaining share for lightweight carbonated beverage caps requiring precise thread tolerance. Plastic closures command volume leadership across beverage and food applications, while metal screw caps retain structural importance in wine and spirits where oxygen transmission rates below 0.1 cc per day preserve product integrity. Tamper-evident bands and child-resistant mechanisms represent the fastest-growing functional segments, driven by pharmaceutical oral-dose packaging mandates and over-the-counter safety regulations.
FDA food-contact notification requirements and EU REACH Annex XVII restrictions on phthalate plasticizers shape material selection and migration testing protocols for closure suppliers accessing North American and European markets. BIS certification under India's Compulsory Registration Scheme blocks uncertified polypropylene and polyethylene imports, forcing localization of resin qualification and mold validation programs. Stakeholders must monitor evolving extended producer responsibility frameworks in Germany's KBA-influenced packaging circularity rules and California's SB 54 implementation, which will restructure recycled content minimums and redesign obligations for single-use beverage closures.
Market Dynamics
Capital-intensity divergence between high-volume injection molders and precision metal-forming specialists is rotating competitive advantage toward integrated resin-to-cap producers with captive polymer compounding capabilities.
Growth Catalysts
- Beverage bottler expansion:Emerging economy bottlers are expanding tamper-evident and child-resistant closure procurement for carbonated and still drinks.
- EU REACH compliance:Tightening plastic resin migration limits under Annex XVII restrictions is forcing specification upgrades across food-contact closures.
- India BIS certification:Compulsory Registration Scheme requirements are accelerating domestic screw cap manufacturing localization.
Market Restraints
- Polypropylene price volatility:Crude-linked resin cost swings compress margin predictability for non-integrated molders lacking captive compounding.
- Aluminum supply concentration:Metal closure producers face input risk from concentrated primary aluminum smelting in specific geographies.
- Oxygen transmission floor:Plastic closures cannot achieve sub-0.1 cc/day rates required for premium wine aging, ceding share to metal.
Strategic Opportunities
- Pharmaceutical oral-dose packaging:Child-resistant mechanism mandates for over-the-counter medications open specialized closure demand.
- Extended producer responsibility frameworks:Germany's KBA-influenced circularity rules and California's SB 54 create redesign service revenue streams.
- Lightweight compression molding:Carbonated beverage caps requiring precise thread tolerance favor technology migration from injection processes.
Industry Challenges
- Mold validation timelines:BIS certification blocks uncertified imports, forcing extended resin qualification and tool validation programs.
- Recycled content integration:Post-consumer resin incorporation requires re-engineering of thread tolerance and seal integrity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screw Caps and Closure Market |
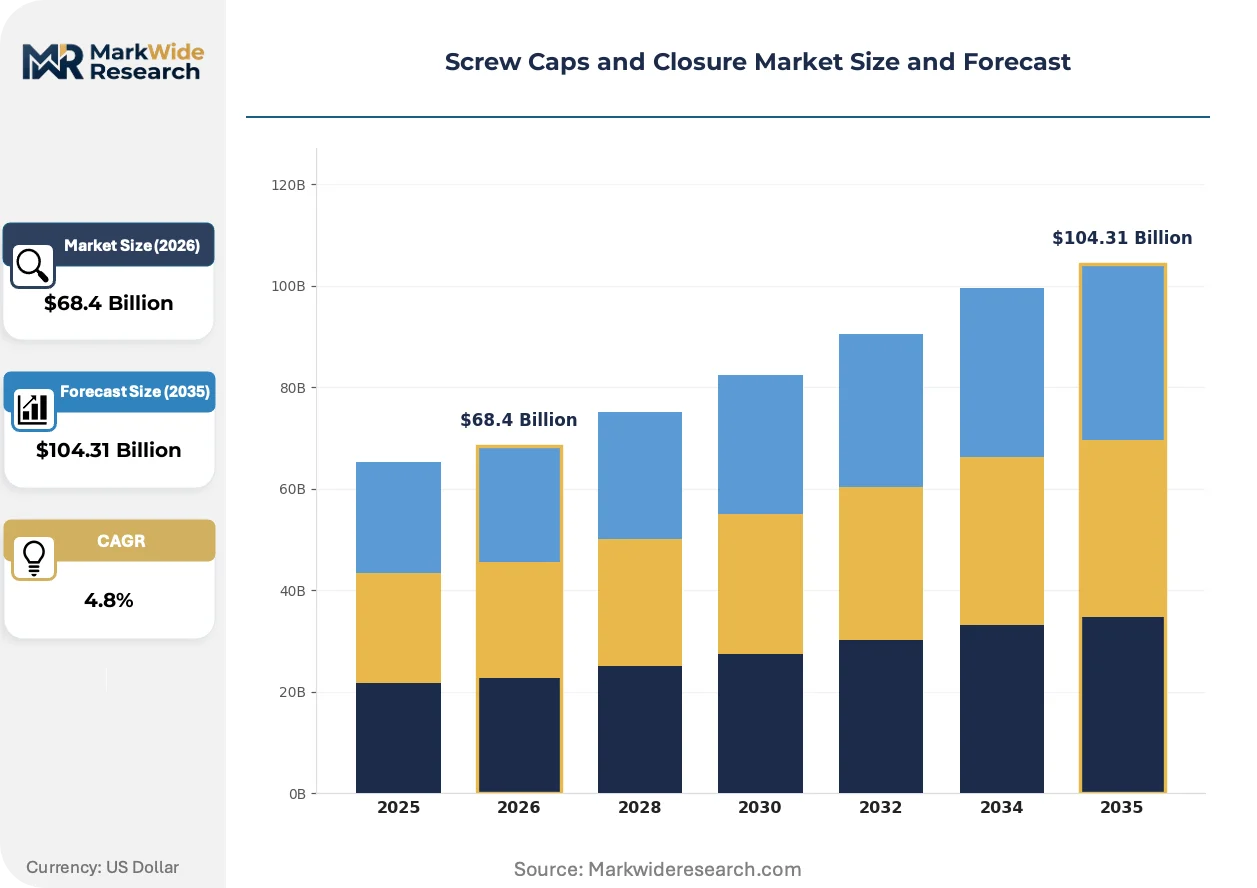
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $104.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Closure Type: Screw Cap, Tamper-Evident Cap, Child-Resistant Cap, Sports Cap Material: Plastic, Metal, Glass, Composite Application: Beverages, Pharmaceuticals, Cosmetics, Food End User: Manufacturers, Retailers, Distributors, Consumers |
| Companies Covered | Berry Global Inc., Silgan Holdings Inc., Amcor Plc, AptarGroup Inc., Crown Holdings, BERICAP, Guala Closures S.p.A, Closure Systems International, Ball Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screw Caps and Closure Market Evolving Landscape
Active reshaping of this market centers on material substitution pressures, regulatory migration testing intensification, and buyer consolidation demanding integrated supply security.
Compression molding for lightweight carbonated beverage caps is displacing conventional injection processes in high-volume bottling operations. Major beverage bottlers in North America and Western Europe are adopting these precision-thread designs for weight reduction targets. The shift is displacing older injection-molded stock from supplier portfolios and compressing equipment amortization cycles.
EU REACH Annex XVII restrictions on phthalate plasticizers are tightening material selection protocols for closure suppliers accessing European markets. Industrial consequence includes expanded migration testing budgets and reformulation of legacy resin compounds. Pharmaceutical and infant nutrition segments are most affected, with suppliers accelerating bio-based plasticizer qualification programs.
Buyer consolidation among multinational beverage conglomerates is compressing supplier qualification timelines and demanding single-source accountability for resin-to-cap quality. Direct procurement relationships are replacing distributor-mediated supply in India and Southeast Asia. This pattern is most visible in carbonated soft drink and bottled water verticals where volume concentration rewards integrated producers.
Screw Caps and Closure Market Segmentation
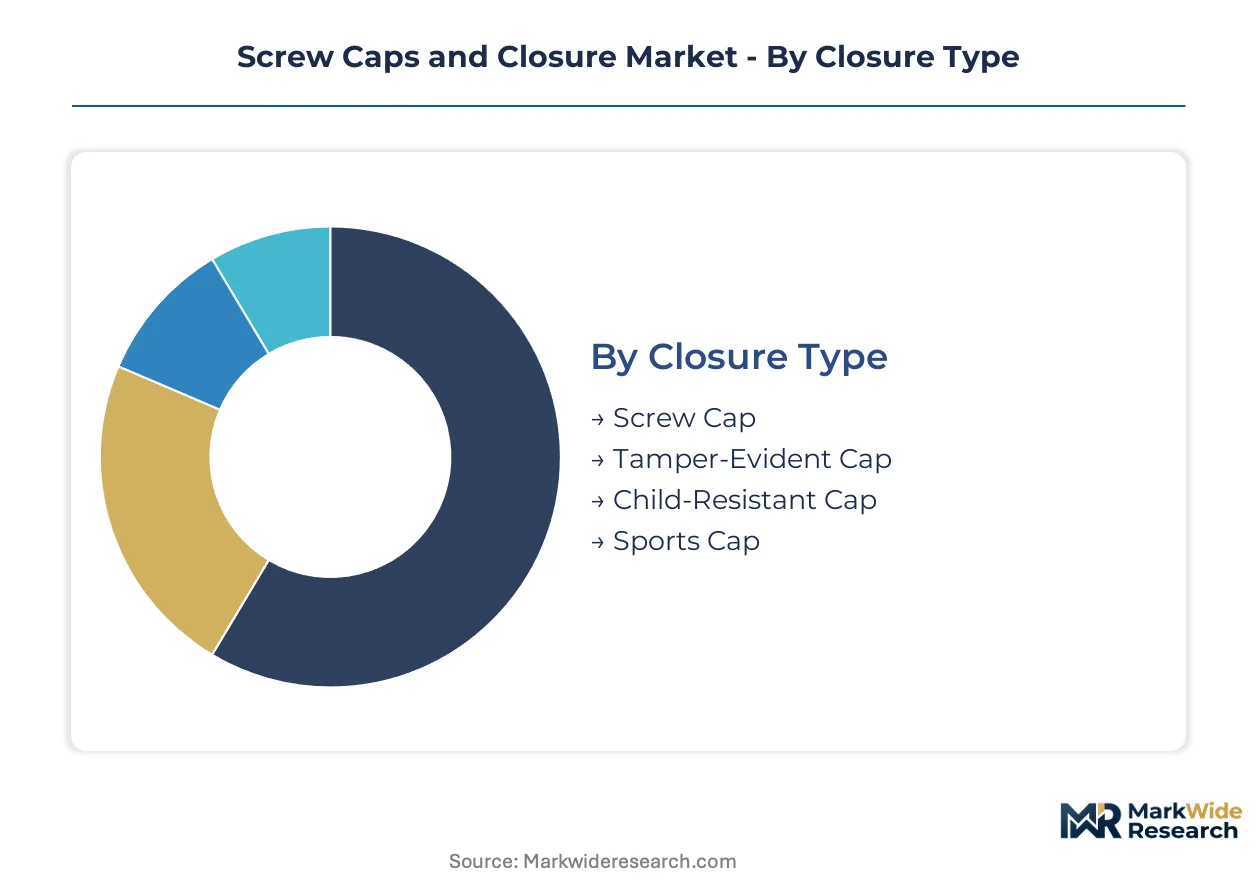
Screw caps and closures serve distinct functional requirements across beverage carbonation retention, pharmaceutical safety compliance, and cosmetic shelf-life extension. Channel differentiation between direct bottler procurement and distributor-mediated supply shapes which segments capture volume concentration versus margin expansion.
Closure Type:
Direct bottler relationships favor high-volume screw and sports cap categories, while pharmaceutical and specialty chemical channels concentrate procurement of tamper-evident and child-resistant mechanisms through qualified vendor lists.
- Screw Cap:Continuous helical thread designs manufactured through injection or compression molding of polypropylene and high-density polyethylene dominate beverage bottling operations. Demand concentrates in India and Southeast Asia where domestic production expansion under BIS certification requirements is accelerating local manufacturing investment.
- Tamper-Evident Cap:Breakaway band mechanisms integrated during molding provide visible post-opening indication for over-the-counter pharmaceuticals and bottled water. Expansion is climbing the fastest in emerging economy beverage markets where counterfeiting concerns are tightening procurement specifications.
- Child-Resistant Cap:Push-and-turn or squeeze-and-turn mechanisms meeting FDA poison prevention packaging standards serve oral-dose pharmaceuticals and household chemicals.
- Sports Cap:Flip-top or pull-spout designs with flow control features target active hydration and on-the-go consumption formats.
Screw caps dominate installed base across carbonated and still beverage production. Child-resistant mechanisms are where expansion concentrates as regulatory mandates extend across additional pharmaceutical categories.
Material:
Cost tier stratification separates commodity resin compounds from precision metal-forming and specialized composite laminates, with recycled content integration requirements reshaping mid-tier positioning.
- Plastic:Polypropylene and high-density polyethylene injection molding commands beverage and food volume leadership, with compression molding gaining share for lightweight carbonated drink applications. EU REACH Annex XVII phthalate restrictions are forcing reformulation of legacy compounds for pharmaceutical and infant nutrition segments.
- Metal:Aluminum and steel screw caps retain structural importance in wine and spirits where oxygen transmission rates below 0.1 cc per day preserve product integrity during aging. Supply concentrates in regions with integrated primary aluminum smelting and rolling capacity.
- Glass:Precision-molded threaded closures for premium cosmetic and pharmaceutical applications requiring inert contact surfaces.
- Composite:Multi-layer structures combining barrier films with structural substrates for extended shelf-life food and sensitive pharmaceutical formulations.
Plastic commands volume leadership across mass-market applications. Composites are gaining share fastest in barrier-sensitive pharmaceutical and food preservation segments.
Application:
End-use maturity curves diverge sharply, with beverages representing scale-driven procurement and pharmaceuticals requiring specialized validation timelines that extend supplier qualification cycles.
- Beverages:Carbonated soft drinks, bottled water, and ready-to-drink formats drive high-volume screw cap demand with weight reduction targets favoring compression-molded precision threads. Procurement is shifting toward direct manufacturer relationships in India and Southeast Asia as bottler consolidation accelerates.
- Pharmaceuticals:Oral-dose packaging mandates for child-resistant and tamper-evident mechanisms create specialized demand with stringent FDA and EMA migration testing requirements. CDSCO and other national regulators are extending comparable standards across domestic markets.
- Cosmetics:Premium positioning through metal and glass closure materials supports brand differentiation in skincare and fragrance segments.
- Food:Condiments, sauces, and preserves require oxygen and moisture barrier performance with extended producer responsibility frameworks influencing recycled content specifications.
Beverages anchor global volume demand. Pharmaceuticals represent the steepest expansion trajectory as safety regulations tighten across over-the-counter and prescription categories.
End User:
Customer type determines contract structure complexity, with manufacturers demanding integrated resin-to-cap accountability while retailers and distributors mediate fragmented regional supply.
- Manufacturers:Beverage bottlers and pharmaceutical packagers procure direct through qualified supplier programs with captive compounding capabilities compressing cycle times and quality variance.
- Retailers:Private label and store-brand packaging specifications are consolidating procurement toward integrated producers with multi-format molding flexibility.
- Distributors:Regional stock-and-serve operations serve mid-tier beverage and food producers lacking direct supplier qualification resources.
- Consumers:Replacement cap and specialty closure demand through retail channels represents marginal volume with premium pricing for functional or aesthetic differentiation.
Manufacturers dominate direct procurement value. Retailers are where channel consolidation is concentrating fastest as private label programs expand specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: emerging markets prioritize tamper-evident beverage closures, while developed regions emphasize pharmaceutical safety compliance and extended producer responsibility mandates. This mix differential shapes where investment concentrates and which regulatory frameworks dominate supplier strategy.
United States
Beverage bottlers in the Southeast and Southwest are expanding compression-molded lightweight cap procurement for carbonated drinks. FDA food-contact notification requirements and California's SB 54 implementation are tightening recycled content specifications and redesign obligations for single-use closures. Manufacturing investment clusters around Atlanta and Dallas-Fort Worth as integrated producers establish captive compounding operations to serve Coca-Cola and PepsiCo bottling networks.
Germany
Premium wine and spirits producers maintain structural demand for aluminum screw caps with sub-0.1 cc/day oxygen transmission rates. KBA-influenced extended producer responsibility frameworks and EU REACH Annex XVII phthalate restrictions are reshaping material selection protocols and migration testing budgets. The Rhine-Main industrial corridor hosts specialized metal-forming operations serving Riesling and sparkling wine exporters.
India
Domestic beverage production growth is accelerating local sourcing of screw cap manufacturing under BIS certification requirements. The Compulsory Registration Scheme blocks uncertified polypropylene and polyethylene imports, forcing localization of resin qualification programs. Maharashtra and Gujarat industrial zones are attracting mold validation investments from global suppliers seeking to bypass import barriers and serve Coca-Cola India's expanding bottling footprint.
China
Carbonated soft drink and bottled water volume leadership supports high-volume injection molding operations serving state-owned and multinational bottlers. NMPA alignment with FDA-style pharmaceutical packaging standards is extending child-resistant closure mandates across domestic oral-dose markets. The Yangtze River Delta manufacturing belt concentrates precision molding capacity for export-oriented pharmaceutical and cosmetic closure production.
Brazil
Still beverage and condiment packaging demand drives polypropylene closure consumption in Latin America's largest consumer market. ANVISA pharmaceutical packaging regulations are tightening tamper-evident and child-resistant specifications for over-the-counter medications. São Paulo state's industrial corridor anchors South American manufacturing for multinational closure suppliers serving Ambev and private-label retail programs.
Screw Caps and Closure Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with competitive advantage rotating toward captive polymer compounding and direct bottler relationships. Three archetypes define positioning: resin-to-cap integrated producers compressing cycle times, precision metal-forming specialists serving wine and spirits, and pharmaceutical-focused mechanism designers. Dominant competitive moves include backward integration into resin compounding and geographic expansion through qualified supplier program wins in India and Southeast Asia.
Within the integrated producer tier, Berry Global Inc. and Amcor Plc exemplify scale-driven positioning through North American and global manufacturing footprints. Silgan Holdings Inc. occupies a distinct anchor position through deep relationships with metal beverage can customers requiring matched closure supply. These three companies represent the structural concentration at the top of the market, while specialists like AptarGroup Inc. and Guala Closures S.p.A. sit within narrower pharmaceutical and premium beverage segments where mechanism design and oxygen barrier performance command premium positioning.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Silgan Holdings Inc. |
| Amcor Plc |
| AptarGroup Inc. |
| Crown Holdings |
| BERICAP |
| Guala Closures S.p.A |
| Closure Systems International |
| Ball Corporation |
| Others |
Value Network & Pricing Analysis
Sixty-day mold validation timelines for BIS certification in India concentrate pricing power with integrated resin-to-cap producers possessing captive compounding capabilities, while spot resin purchasers absorb margin volatility from crude-linked polypropylene swings. This lead-time compression rewards backward integration and punishes non-integrated molders competing on price alone.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational beverage bottlers and integrated closure suppliers, compressing spot market participation to fragmented regional distributors serving mid-tier food producers. Price differentiation hinges on certification tier — FDA food-contact notification versus EU REACH Annex XVII compliance — and volume scale, with tier-one bottlers extracting double-digit discounts against list pricing. Cost compression in standard-grade polypropylene closures is intensifying because lightweight compression-molded designs displace legacy injection-molded stock. Private-label retailers exhibit highest price sensitivity, while premium wine and spirits producers prioritize oxygen transmission performance over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for resin imports into India and Southeast Asia, forcing localization investments. Raw material supply concentrates in Saudi Arabia and South Korea for virgin polypropylene, China for aluminum coil, and Germany for specialty metal-forming equipment. The chain draws from concentrated primary aluminum smelting in specific geographies, creating single-source vulnerability for metal closure producers. Distribution runs through direct manufacturer relationships with bottler consolidation displacing distributor-mediated supply in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The screw caps and closure market is recovering from a cyclical trough driven by post-pandemic beverage bottler restocking and pharmaceutical packaging mandate expansion. Normalized resin costs and reopened mold validation programs are restoring supplier profitability trajectories.
For Market Incumbents: Shield margin position by accelerating captive polymer compounding investments in Maharashtra and Gujarat industrial zones ahead of further BIS certification tightening. Prioritize child-resistant mechanism R&D to capture pharmaceutical oral-dose packaging mandates as FDA and EMA standards extend into emerging markets. Consolidate distributor relationships into direct qualified supplier programs before emerging economy bottler procurement centralizes.
For New Entrants and Emerging Players: Anchor in India's domestic beverage production expansion by establishing localized mold validation capabilities that bypass Compulsory Registration Scheme import barriers. Target white-space in lightweight compression-molded carbonated beverage caps where precision thread tolerance requirements favor technology specialists over legacy injection molders. Pursue go-to-market partnerships with state-level industrial development authorities for subsidized facility access.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core closure operations amid portfolio simplification pressures. Long-term viability centers on integrated resin-to-cap producers with demonstrated regulatory navigation across FDA, EMA, and BIS frameworks. Monitor NMPA alignment with FDA-style pharmaceutical packaging standards in China as the signal for accelerated child-resistant closure mandate expansion across Asian markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply compresses cycle times for Berry Global and Silgan Holdings serving Coca-Cola networks. |
| Lightweight Compression Molding Technology Migration | Precision thread tolerance capabilities displace legacy injection-molded stock in carbonated beverage applications. |
| BIS Certification Localization Investment | Maharashtra and Gujarat facilities bypass India's Compulsory Registration Scheme import barriers for uncertified resins. |
| Child-Resistant Mechanism R&D Expansion | FDA poison prevention packaging standards extend into over-the-counter pharmaceutical categories driving specialized demand. |
| Extended Producer Responsibility Service Development | Germany's KBA-influenced circularity rules and California SB 54 create redesign revenue streams for integrated producers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with beverage bottler procurement directors, pharmaceutical packaging engineers, resin compounding plant managers, and regulatory affairs specialists at closure manufacturers. Secondary validation drew from FDA food-contact notification databases, EU REACH Annex XVII substance restriction updates, BIS Compulsory Registration Scheme technical guidelines, and customs trade data for polypropylene and aluminum coil movements. Bottom-up volume triangulation across injection and compression molding capacity installations was cross-checked against top-down expenditure analysis at major beverage and pharmaceutical packagers.
Across the analysis window, the forecasting framework modeled demand trajectories by closure type, material grade tier, end-use application, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections incorporating beverage bottler expansion rates, pharmaceutical packaging mandate implementation timelines, and recycled content specification phase-ins. Industry-specific inputs included oxygen transmission rate requirements for wine aging applications, child-resistant mechanism qualification timelines, and lightweight compression molding adoption curves.
Material uncertainties — abrupt polypropylene price spikes, BIS certification timeline extensions, or aluminum supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory implementation pacing and resin cost normalization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Canada Plastic Caps and Closures Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Box Latch Market
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market
Caps and Closures
Plastic Sifter Caps Market
Caps and Closures
Cork Stoppers Market
Caps and Closures
Smooth Hinge Caps and Closure Market
Caps and Closures
Gamma Seal Lids Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Flapper Caps Market
Caps and Closures
Screw Closure Market