
 Metal Closures Market | 2026-2036
Metal Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Closures Market Foresight
Beverage bottler procurement channels is reconfiguring as multinational drink brands consolidate supplier rosters across aluminum cap programs. Crown Holdings Inc. leverages vertical integration from coil to finished closure to capture margin pool compression. Silgan Holdings Inc. anchors North American food can lid supply through dense plant networks. Guala Closures Group specializes in premium wine and spirits closures where tamper-evident technology commands pricing power.
Metal closures are mechanically formed sealing devices manufactured from aluminum, steel, tinplate, or composite substrates, typically featuring rolled or threaded profiles that interface with container finishes to preserve contents, prevent contamination, and enable resealability. Aluminum caps dominate beverage end use due to lightweighting and infinite recyclability, while steel lids retain structural primacy in retort food applications where vacuum integrity withstands thermal processing. Pharmaceutical closures represent the fastest-growing end-use segment as serialization mandates and child-resistant mechanisms drive specification upgrades. Composite materials gain share where barrier performance must reconcile with magnetic detection requirements in automated filling lines.
FDA enforces container closure system integrity standards for pharmaceutical applications, while EPA oversees volatile organic compound emissions from metal forming coatings. EU REACH restricts certain chrome-based passivation chemistries in tinplate production, redirecting investment toward trivalent chromium and silicate alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks in the EU and state-level deposit legislation in the US as these mechanisms increasingly determine material selection and design-for-recycling specifications.
Market Dynamics
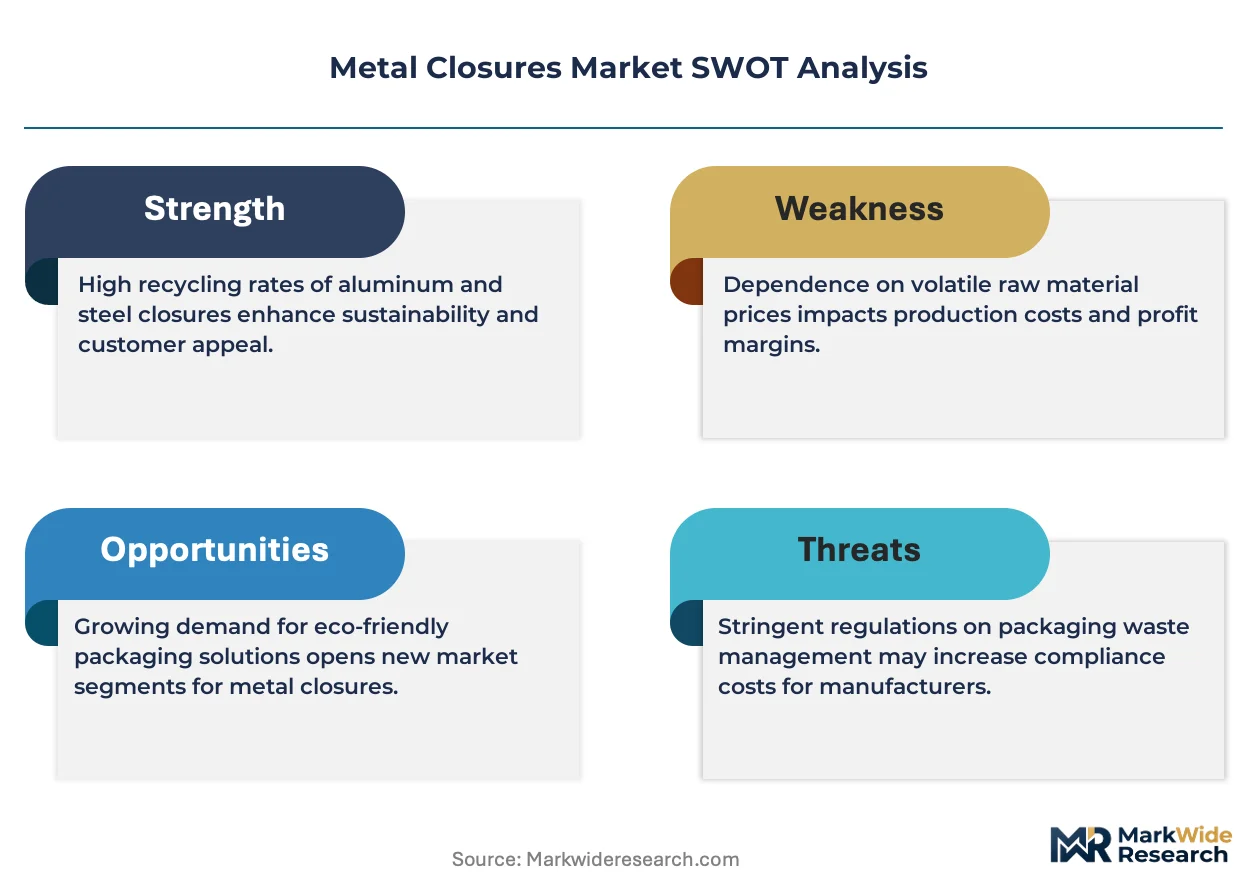
Beverage brand sustainability mandates are forcing aluminum cap conversion at scale, while EU F-Gas Regulation and REACH compliance redirect tinplate investment toward chrome-free passivation chemistries. Coil supply concentration and energy-intensive forming processes amplify margin pressure across converter tiers.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in plastic foam liners accelerate metal closure adoption for carbonated beverage sealing.
- Pharmaceutical serialization mandates:Track-and-trace requirements in the US and EU drive specification upgrades for tamper-evident aluminum closures with embedded RFID.
- Deposit-return schemes:Germany's DRS expansion and pending state-level legislation in the US create material pull for infinitely recyclable aluminum caps.
Market Restraints
- Aluminum coil supply concentration:Five primary smelters control 60% of beverage-grade coil, exposing converters to price volatility and allocation risk.
- REACH chrome restrictions:Trivalent chromium and silicate passivation alternatives for tinplate raise unit coating costs while extending qualification timelines.
- Flexible pouch substitution:Retortable stand-up pouches with spouted fitments capture shelf-stable food volume formerly held by steel can lids.
Strategic Opportunities
- India beverage bottling expansion:Carbonated soft drink and bottled water capacity buildout in Maharashtra and Gujarat creates greenfield aluminum cap demand.
- Child-resistant pharmaceutical mechanisms:Push-and-turn aluminum designs with integrated desiccant chambers address aging demographics and compliance gaps.
- Digital printing convergence:Direct-to-metal inkjet decoration enables lot-level customization for craft spirits and limited-edition beverage releases.
Industry Challenges
- Tooling capex intensity:High-speed rotary forming presses for 26mm crown caps require seven-figure capital deployment with 8-year depreciation cycles.
- Multi-jurisdiction compliance synchronization:Simultaneous FDA container closure integrity, EU MDR, and state-level deposit legislation create certification bottlenecks.
- Legacy press retrofit complexity:Integrating vision inspection and laser coding into 1990s-vintage forming lines demands custom mechanical engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Closures Market |
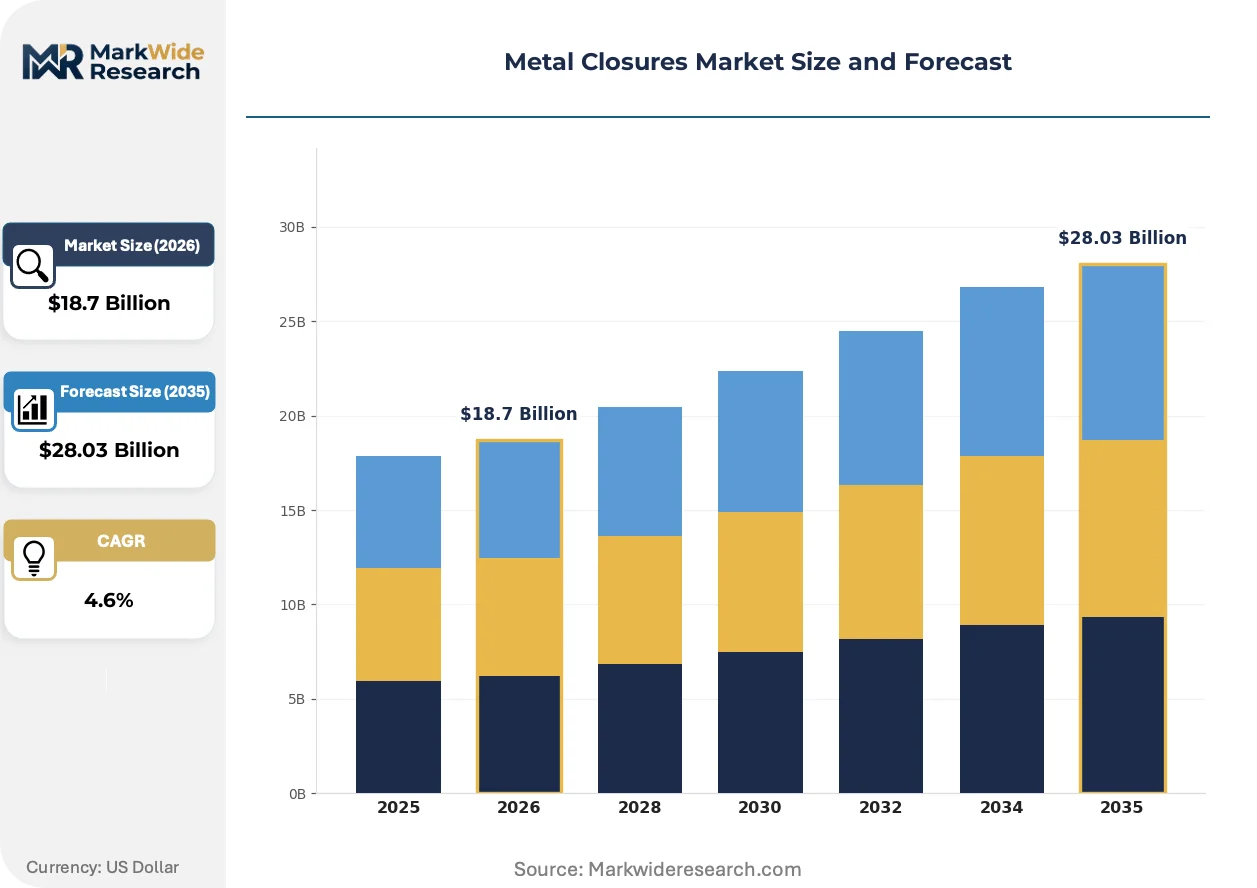
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
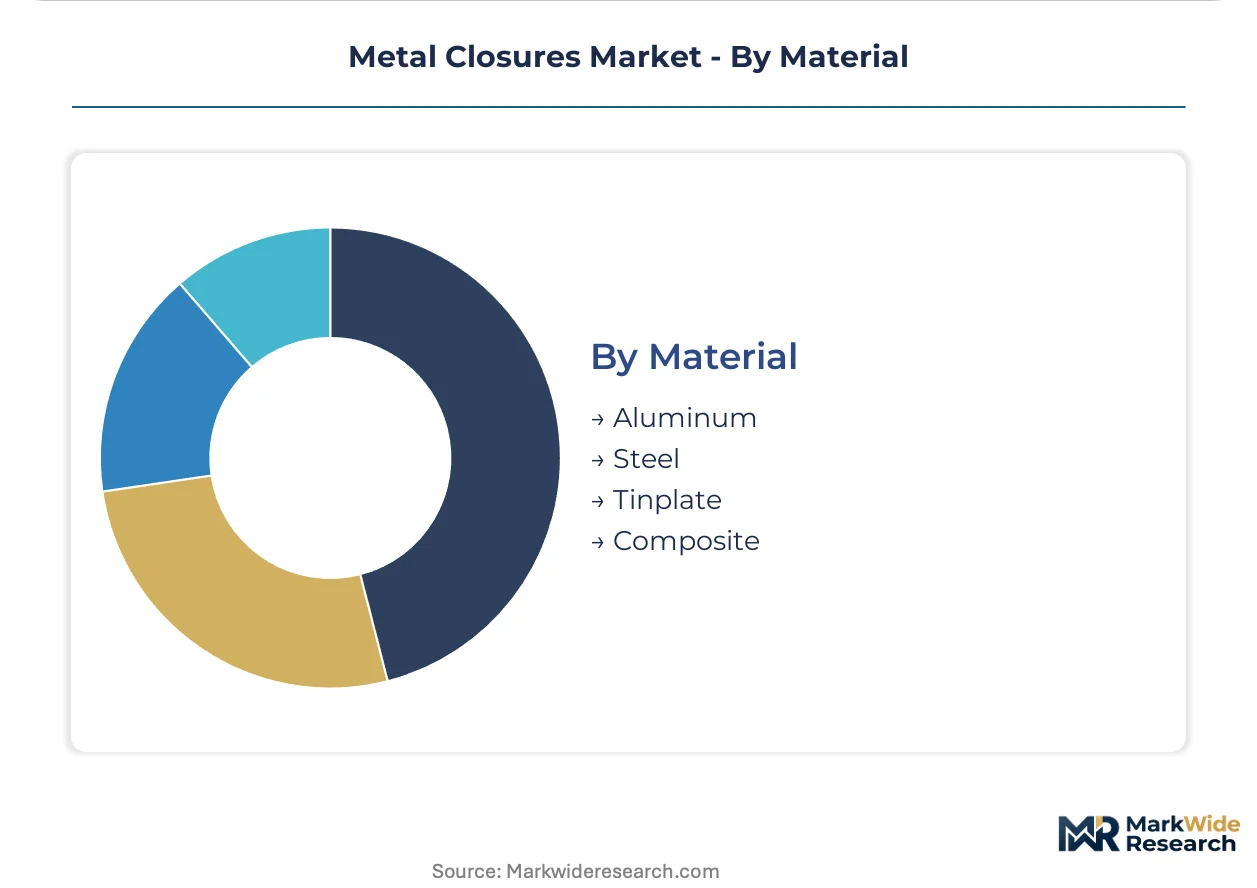
| Segmentation | Closure Type: Caps, Lids, Cans, Closures End Use: Beverages, Food, Pharmaceuticals, Personal Care Technology: Capping, Sealing, Pressure Sensitive, Injection Molding Material: Aluminum, Steel, Tinplate, Composite |
| Companies Covered | Crown Holdings Inc., Silgan Holdings Inc., Guala Closures Group, Tecnocap Group, Pelliconi & C. SpA, Nippon Closures Co. Ltd, O.Berk Company, CL Smith Company, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Closures Market Shifts & Advancements
Digital thread technologies are collapsing the design-to-production cycle for closure geometries, while regulatory chemistry bans and brand circularity commitments reshape material qualification pathways. These forces converge on lighter, smarter, more traceable sealing systems.
Smart closure sensor integration is virtualizing quality assurance in pharmaceutical and high-value beverage applications. Micro-electromechanical pressure and temperature sensors embedded in aluminum caps transmit fill integrity data across Bluetooth Low Energy protocols. Biologic drug manufacturers in Switzerland and Germany are piloting these devices for cold-chain verification, compressing the need for secondary packaging indicators and enabling real-time spoilage alerts.
EU REACH Annex XVII restrictions on hexavalent chromium in tinplate passivation entered full enforcement in 2024, redirecting converter R&D toward trivalent chrome and hybrid silicate systems. The regulation forces reformulation of electrolytic tinning line chemistry across Spanish and Italian steel service centers. Food can lid producers face extended qualification timelines with brand owners, delaying volume shifts from plastic alternatives.
Direct-store-delivery consolidation among beverage bottlers is compressing supplier rosters and extending contract durations. Coca-Cola Europacific Partners and similar operators now specify five-year aluminum cap agreements with volume guarantees and indexed raw material pass-throughs. This concentration is most visible in Brazil's southeastern bottling cluster, where three distributors control 80% of crown cap procurement.
Metal Closures Market Segmentation
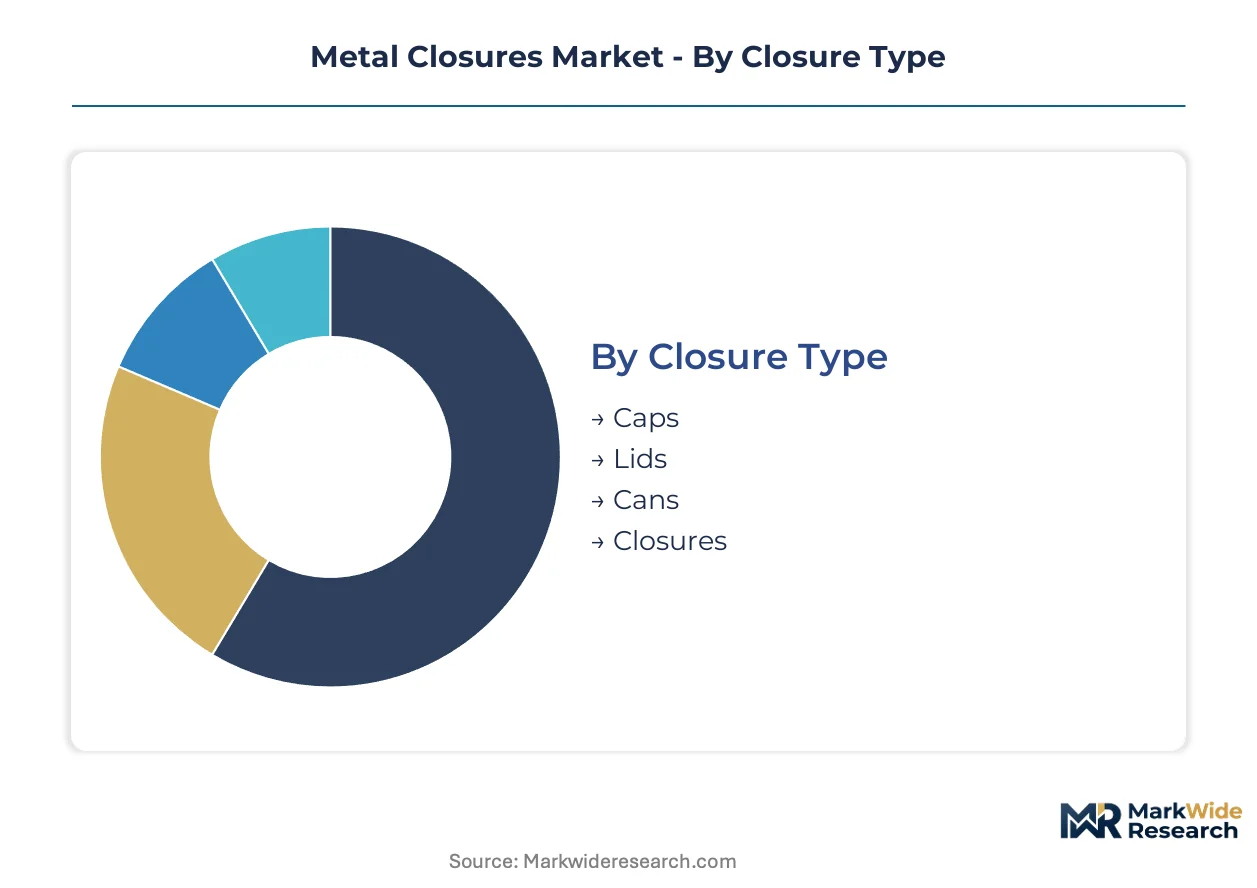
Metal closure segmentation reveals divergent margin structures across material chemistry and forming technology. Specification requirements in pharmaceutical serialization and beverage lightweighting create asymmetric growth vectors that reshape converter investment priorities.
Closure Type:
The use-case spectrum spans single-serve convenience to industrial bulk containment, with thread profiles and sealing mechanics calibrated to content pressure and reseal frequency.
- Caps:Rolled aluminum crown caps with plastisol liners dominate carbonated beverage sealing under internal pressure loads. Crown Holdings captures volume in Brazil's southeastern bottling cluster where three distributors consolidate procurement.
- Lids:Steel easy-open ends with score residual and aluminum peelable foils serve retort food and dairy applications. Silgan Holdings anchors North American supply through dense plant networks proximal to cannery operations.
- Cans:Two-piece drawn aluminum beverage cans and three-piece welded food cans incorporate integral closures via necked-in ends and double-seamed lids.
- Closures:Threaded aluminum ROPP (roll-on pilfer-proof) and plastic-lined metal shells address wine, spirits, and pharmaceutical vial sealing with tamper-evident functionality.
Established volume favors Lids; emerging adoption favors Caps.
End Use:
Customer specification intensity varies by content value and regulatory exposure, with pharmaceutical and beverage commanding premium qualification protocols.
- Beverages:Aluminum crown caps and ROPP closures for carbonated soft drinks, beer, bottled water, and wine face sustainability-driven conversion from plastic alternatives. EU F-Gas Regulation accelerates metal substitution for foam-lined plastic seals.
- Food:Steel easy-open ends for retort vegetables, fish, and ready meals withstand thermal processing cycles. Flexible pouch substitution with spouted fitments erodes volume in shelf-stable segments.
- Pharmaceuticals:Child-resistant aluminum closures with push-and-turn mechanisms and integrated desiccant chambers address aging demographics and FDA container closure integrity mandates. This segment climbs the fastest on serialization requirements.
- Personal Care:Aluminum screw caps and dispensing closures for cosmetics and fragrances prioritize aesthetic finishing and magnetic detection compatibility in automated filling lines.
Pharmaceuticals commands specification premiums; Beverages drives unit scale.
Technology:
Forming method selection trades capital intensity against throughput and geometric complexity, with rotary mechanical forming dominant at beverage scale.
- Capping:High-speed rotary presses apply crown caps and ROPP closures at bottling line speeds exceeding 100,000 units hourly. Seven-figure tooling capex with eight-year depreciation cycles create barrier to entry.
- Sealing:Double-seaming and roll-forming operations join can ends to bodies, with vacuum integrity critical for retort food applications.
- Pressure Sensitive:Adhesive-backed aluminum foils and membranes enable resealable lidding for dairy and ready-to-drink formats.
- Injection Molding:Limited metal closure relevance; primarily serves composite substrate formation where polymer cores require metal overmolding for barrier performance.
Capping anchors beverage throughput; Pressure Sensitive gains in convenience formats.
Material:
Substrate selection balances lightweighting imperatives against barrier requirements and magnetic detection needs in automated handling systems.
- Aluminum:Infinite recyclability and one-third the density of steel drive beverage cap dominance. Five primary smelters control coil supply concentration, exposing converters to allocation risk.
- Steel:Structural rigidity and vacuum retention sustain retort food lid primacy despite weight penalty. Tinplate variants face REACH chrome restriction compliance costs.
- Tinplate:Electrolytic tin coating on steel substrate enables food contact compliance with reduced metallic flavor transfer. Trivalent chromium and silicate passivation alternatives extend qualification timelines with brand owners.
- Composite:Polymer-core metal-skin laminates reconcile barrier performance with magnetic detection in pharmaceutical and personal care automated lines.
Aluminum captures sustainability premiums; Tinplate navigates regulatory transition costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation and REACH compliance anchor European metal closure demand, while beverage bottling clusters in Germany, China, and Brazil concentrate procurement volume. Deposit-return schemes and sustainability mandates reshape material selection across converter networks.
Germany
Beverage bottler consolidation and DRS expansion drive aluminum cap procurement at scale. The EU F-Gas Regulation accelerates metal substitution for foam-lined plastic seals in carbonated beverage applications. Bavaria's bottling corridor anchors converter supply agreements with five-year volume guarantees.
China
Carbonated soft drink and bottled water capacity buildout in Yangtze River Delta provinces generates greenfield aluminum cap demand. SAMR oversight of food contact materials shapes tinplate qualification protocols for export-oriented canneries. Pearl River Delta forming clusters absorb seven-figure press deployments from multinational equipment vendors.
Brazil
Direct-store-delivery consolidation among beverage distributors concentrates crown cap procurement across southeastern bottling networks. ANVISA pharmaceutical serialization mandates push specification upgrades for tamper-evident aluminum closures. São Paulo's three-distributor cluster controls four-fifths of regional aluminum cap volume.
United States
Pending state-level deposit legislation creates material pull for infinitely recyclable aluminum caps across bottling operations. FDA container closure integrity standards govern pharmaceutical specification upgrades with embedded RFID functionality. Pacific Northwest beverage clusters pilot smart closure sensor integration for cold-chain verification.
India
Maharashtra and Gujarat carbonated beverage capacity expansion generates demand for high-speed rotary forming press output. FSSAI food contact compliance requirements redirect tinplate investment toward chrome-free passivation alternatives. Western India bottling corridors attract converter greenfield investments with indexed raw material pass-through structures.
Metal Closures Market Competitive Landscape
Vertically integrated multinationals and specialized regional fabricators split the market across beverage, food, and pharmaceutical end uses. Tier-one converters leverage captive coil supply and dense plant networks to defend margin pools against raw material volatility. Mid-tier specialists occupy premium wine, spirits, and pharmaceutical niches where tamper-evident technology commands specification premiums. Dominant competitive moves include backward integration into aluminum coil processing and strategic capacity placement proximal to bottling clusters.
Among North American-based converters, Crown Holdings Inc. and Silgan Holdings Inc. exemplify the vertically integrated archetype through in-house production of formed closures at beverage scale. Guala Closures Group occupies a position within the premium-tier specialist segment, representing European expertise in wine and spirits closure engineering where regulatory serialization and aesthetic finishing converge. These three anchors illustrate the structural bifurcation between scale-driven beverage supply and specification-intensive pharmaceutical and luxury applications.
| Leading Market Players |
|---|
| Crown Holdings Inc. |
| Silgan Holdings Inc. |
| Guala Closures Group |
| Tecnocap Group |
| Pelliconi & C. SpA |
| Nippon Closures Co. Ltd |
| O.Berk Company |
| CL Smith Company |
| Sonoco Products Company |
| Others |
Supply & Pricing Matrix
Underutilized forming capacity in China's Yangtze River Delta provinces is compressing aluminum cap pricing while amplifying supplier willingness to absorb coil volatility through indexed pass-through contracts. This utilization dynamic concentrates bargaining power with beverage bottlers consolidating procurement across five-year agreements.
Pricing Analysis
Geographic price spreads between European and Asian aluminum cap supply have widened as REACH compliance costs embed in tinplate alternatives. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical serialization-grade closures from beverage commodity caps. Cost compression in standard-tier beverage supply is intensifying because coil allocation risk concentrates with five primary smelters. Brand owners exhibit lowest price sensitivity in pharmaceutical applications where FDA container closure integrity mandates override procurement cost targets.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard as beverage bottlers leverage procurement consolidation to extract supply-chain finance concessions. Raw material flows draw from aluminum coil processing in China, Germany, and Brazil, with steel tinplate supply anchored in Spanish and Italian service centers. Single-source vulnerability concentrates in beverage-grade aluminum coil where five smelters control majority share. Distribution runs through dense converter plant networks proximal to bottling clusters rather than centralized warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal closure markets are shifting toward service-attach revenue as digital printing and smart sensor integration expand faster than base hardware sales. Recurring decoration customization and cold-chain verification subscriptions now represent the fastest-expanding margin pools.
For Market Incumbents: Harden coil supply security through captive tolling arrangements or equity stakes in primary smelters to defend against allocation risk from beverage bottler consolidation. Accelerate chrome-free passivation qualification timelines to preempt EU REACH enforcement gaps that threaten tinplate volume. Vertical integration into aluminum coil slitting and coating preserves margin compression from raw material volatility.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat bottling corridors represent the most penetrable entry point given greenfield capacity buildout and absence of entrenched converter relationships. Pharmaceutical child-resistant mechanisms with integrated desiccant functionality offer specification-intensive niches where incumbent tooling amortization creates incumbent rigidity. Direct digital printing partnerships with craft spirits brands provide a beachhead for lot-level customization capabilities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical closure segments as serialization mandates and smart sensor integration elevate tooling and qualification burdens. Mid-tier specialists with established FDA and EU MDR certification pathways present the most viable acquisition profile for platform consolidation. The signal to watch is beverage bottler contract duration extension beyond five years, which indicates supplier roster stabilization and reduced entry opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Coil Processing | Crown Holdings and Silgan Holdings mitigate coil allocation risk through captive supply from five primary smelters. |
| Chrome-Free Passivation Qualification | Spanish and Italian steel service centers redirect R&D toward trivalent chromium alternatives under EU REACH Annex XVII. |
| Smart Sensor Integration Partnerships | Swiss and German biologic manufacturers pilot Bluetooth-enabled aluminum caps for cold-chain verification. |
| Digital Printing Capability Deployment | Direct-to-metal inkjet decoration enables lot-level customization for craft spirits limited releases. |
| Pharmaceutical Serialization Certification | FDA container closure integrity and EU MDR compliance create barrier to entry for tamper-evident RFID closures. |
Research Methodology
Desk research of trade association filings, customs records, and regulatory databases preceded structured interviews with converter plant managers, beverage procurement directors, pharmaceutical packaging engineers, and steel service center technical leads. Primary fieldwork with Crown Holdings, Silgan Holdings, and Guala Closures Group executives cross-validated capacity utilization and contract structuring patterns. Secondary sources included EU REACH enforcement notices, FDA container closure guidance documents, and beverage bottler sustainability reports. Bottom-up volume builds from forming press deployments and coil consumption patterns were triangulated against top-down end-use demand estimates.
Assumptions held fixed across the projection horizon include current EU F-Gas Regulation enforcement intensity, existing deposit-return scheme coverage, and prevailing aluminum coil supply concentration. Segmentation dimensions modeled encompass closure type, end-use application, forming technology, and substrate material chemistry. CAGRs were derived from slope-intercept analysis of historical volume trajectories adjusted for regulatory inflection points. Forecast inputs incorporated pharmaceutical serialization mandate timelines and beverage brand sustainability commitment acceleration curves.
Stress conditions across aluminum price volatility, REACH enforcement stringency, and flexible pouch substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding coil supply stability and regulatory continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Europe Plastic Caps and Closures Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Gamma Seal Lids Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Buttress Closures Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Bag Closures Market
Caps and Closures
Heat Shrink Bands Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
Foamed End Caps Market
Caps and Closures
Plastic Sifter Caps Market
Caps and Closures
Metal Caps and Closures Market