
 Spigot End Cap Market | 2026-2036
Spigot End Cap Market Size, Share, and Industry Trends Forecast 2026-2036
Spigot End Cap Market Analytics
Turkey is narrowing the cost-competitive manufacturing gap for spigot end caps through expanded extrusion capacity near Istanbul. Kuzeyboru Plastik leverages vertical integration from raw resin to finished fitting, sustaining price advantages across Middle Eastern export markets. Fusion Group anchors its position through proprietary electrofusion technology leadership, while NORMA Group SE competes via clamp and fastening system bundling with end cap offerings.
A spigot end cap is a pipe fitting closure designed with a socket-type female end that receives the spigot (male) end of a pipe, typically manufactured from high-density polyethylene, PVC, or ductile iron with pressure ratings from PN6 to PN16 bar depending on application requirements. Its primary function is to terminate pipeline runs temporarily or permanently while maintaining system pressure integrity and preventing contamination ingress. Plastic spigot end caps dominate volume due to corrosion resistance and fusion welding compatibility, while metal variants command premium positioning in high-temperature heating system applications. Snap-on installation types are gaining traction among retail and contractor channels for repair scenarios, though welded configurations sustain stronger margins in municipal water supply contracts where leak-free permanence is specified.
FDA regulations govern potable water contact materials for spigot end caps deployed in U.S. drinking water infrastructure, while EPA lead-free mandates under the Safe Drinking Water Act directly shape alloy composition requirements for brass or bronze-containing metal variants. REACH compliance in Europe restricts certain phthalate plasticizers in PVC formulations, forcing reformulation investments among suppliers serving EEA markets. Stakeholders must monitor evolving PFAS restrictions across multiple jurisdictions and assess whether current polymer supply chains require substitution strategies before compliance deadlines tighten.
Market Dynamics
Fusion welding compatibility standards from ASTM International are restructuring procurement specifications across municipal water infrastructure, forcing manufacturers to recalibrate material formulations and certification investments to maintain contract eligibility.
Growth Catalysts
- HDPE Material Innovation:High-density polyethylene formulations with enhanced stress-crack resistance are extending service life expectations in buried pipeline applications, driving replacement cycles for aging ductile iron infrastructure.
- EPA Lead-Free Mandates:Safe Drinking Water Act enforcement is eliminating brass and bronze alloy variants from potable water specifications, redirecting demand toward polymer-based spigot end caps.
- German Manufacturing Concentration:Established extrusion clusters serving Central European utility contractors are capturing cross-border procurement from Poland and Czech Republic infrastructure programs.
Market Restraints
- Resin Price Volatility:Ethylene feedstock fluctuations tied to naphtha cracking economics compress margin predictability for HDPE spigot end cap producers.
- REACH Compliance Burden:ECHA restrictions on phthalate plasticizers in PVC formulations force reformulation investments without immediate pricing recovery mechanisms.
- Mechanical Coupling Substitution:Restrained joint systems with integrated end closures are displacing discrete spigot end caps in certain pressure-rated water main applications.
Strategic Opportunities
- Turkish Export Manufacturing:Expanded extrusion capacity near Istanbul positions suppliers to serve Middle Eastern water infrastructure programs at cost-advantaged freight economics.
- PFAS Regulatory Tailwind:Anticipated restrictions on per- and polyfluoroalkyl substances in polymer supply chains create first-mover advantages for fluorine-free formulation pioneers.
- Electrofusion Convergence:Integration of spigot end caps with electrofusion coupling systems enables bundled system sales to contractors seeking simplified installation protocols.
Industry Challenges
- Fusion Technician Certification Scarcity:Qualified butt-fusion and electrofusion operators remain concentrated in established utility workforces, limiting contractor expansion in emerging markets.
- Legacy Pipeline Compatibility:Dimensional standard mismatches between older cast iron outside diameters and modern HDPE spigot specifications complicate repair scenario product selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spigot End Cap Market |
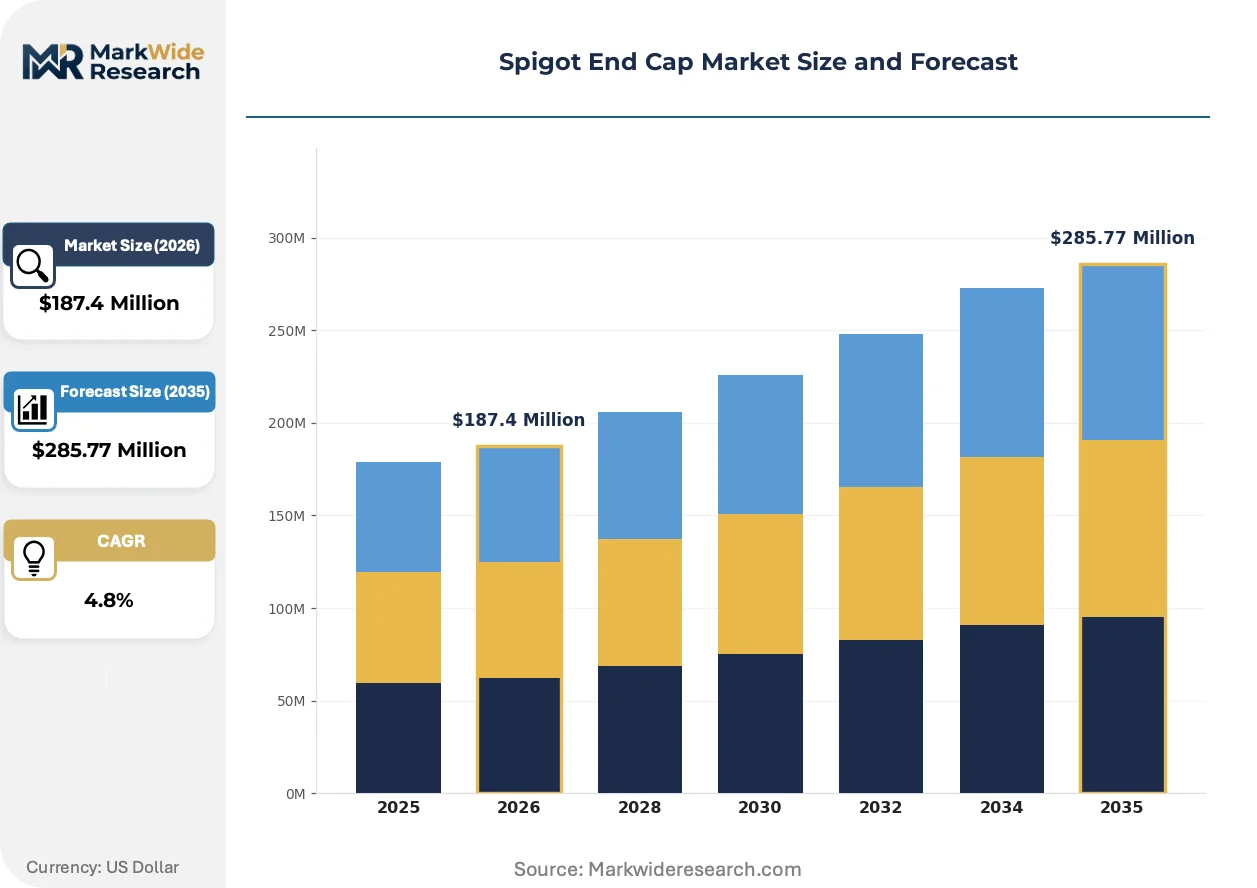
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Composite, Rubber Installation Type: Screwed, Welded, Flanged, Snap-on End User: Manufacturers, Contractors, Retailers, Distributors Application: Water Supply, Irrigation, Drainage, Heating Systems |
| Companies Covered | Plastitalia S.p.A., Fusion Group, NORMA Group SE, Kuzeyboru Plastik, Adroit Piping Systems, Macplast Industries, Drainfast Ltd, T-mex Industrial, Wavin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spigot End Cap Market Evolving Landscape
Active standardization efforts across material specifications and joining technologies are compressing product lifecycle differentiation, while regulatory chemistry restrictions and procurement centralization reshape competitive positioning.
Butt-fusion compatible spigot end caps with integrated heating element pockets are collapsing installation time requirements for municipal contractors. Water utilities in the US Sun Belt region are specifying these configurations for emergency repair scenarios where excavation exposure time drives cost structures. The technology is collapsing the traditional advantage of mechanical joint alternatives in temporary pipeline termination applications.
REACH Annex XVII expansions restricting short-chain chlorinated paraffins in polymer processing aids are forcing compound reformulations among European suppliers. Industrial consequence includes accelerated migration toward calcium-zinc stabilizer systems in PVC spigot end cap production. German and French municipal procurement frameworks are most affected, with contractors now requiring extended material safety data documentation for infrastructure tenders.
Consolidated procurement through regional water authority cooperative purchasing agreements is concentrating vendor qualification requirements. Independent distributors serving smaller municipal systems are losing specification influence to centralized framework agreements. This pattern is most visible across US state-level rural water associations and England's regulated water company supply chains.
Spigot End Cap Market Segmentation
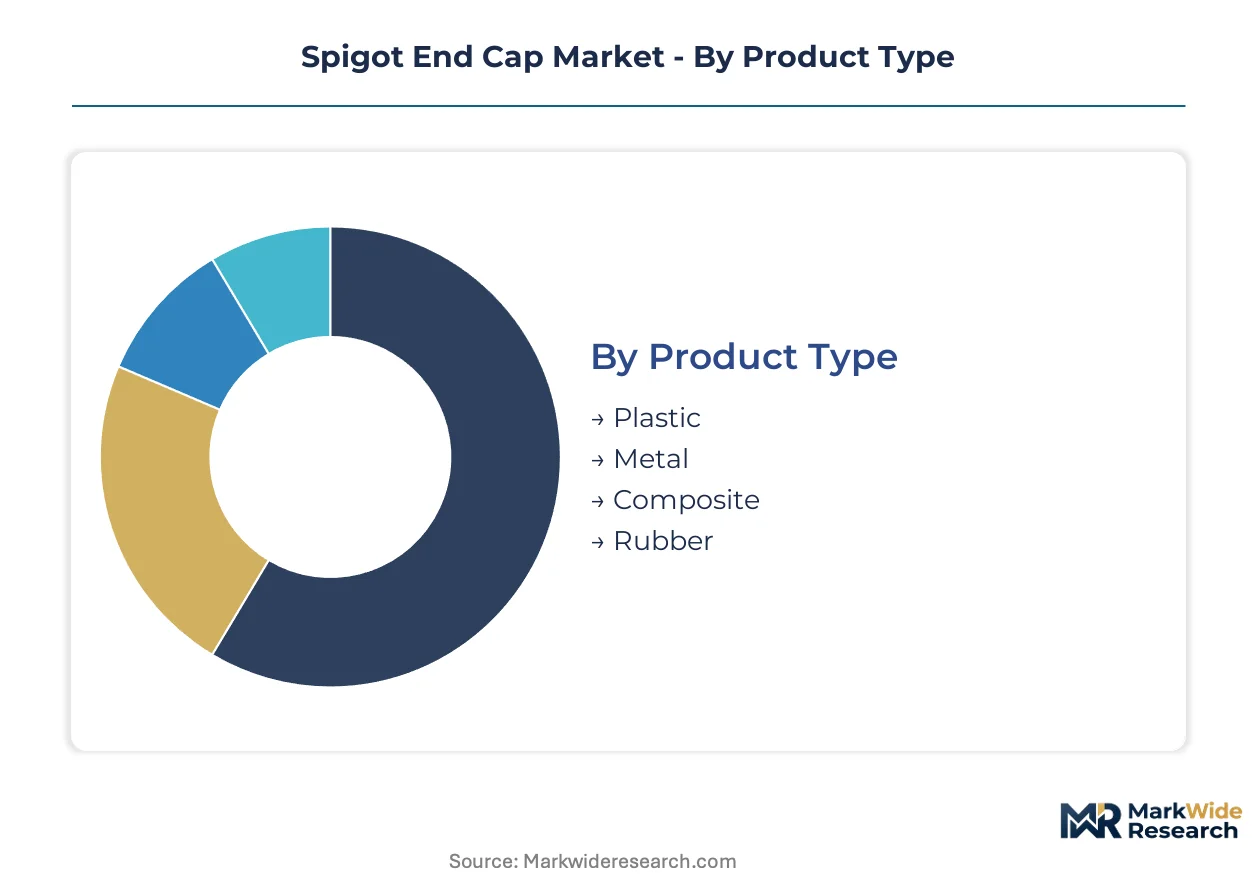
Spigot end cap procurement varies sharply across material specifications, joining methods, and end-use environments. Each segmentation dimension carries distinct margin profiles and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Material selection spans corrosion-resistant polymers, temperature-tolerant metals, and hybrid formulations serving distinct pressure and chemical exposure requirements.
- Plastic:HDPE and PVC formulations dominate municipal water infrastructure through fusion welding compatibility and EPA lead-free compliance. German utility contractors specify these for buried pipeline networks across Central Europe.
- Metal:Ductile iron and stainless steel variants command premium positioning in high-temperature heating systems and industrial process lines. Demand concentrates in legacy infrastructure retrofit scenarios where mechanical joint integrity overrides polymer economics.
- Composite:Fiber-reinforced polymer constructions bridge weight and corrosion resistance for specialized marine and chemical processing applications.
- Rubber:EPDM and NBR formulations serve temporary pressure-testing and maintenance isolation roles with rapid deployment characteristics.
Established volume favors Plastic; emerging adoption favors Composite.
Installation Type:
Joining methodology determines labor skill requirements, equipment capital intensity, and permanence specifications across contractor segments.
- Welded:Butt-fusion and electrofusion configurations deliver leak-free permanence specified in municipal water supply contracts. ASTM International certification requirements concentrate demand among qualified utility workforces in the United States.
- Screwed:Threaded metal-to-metal joints persist in industrial heating systems and repair scenarios requiring future disassembly access.
- Flanged:Bolted connections accommodate high-pressure ratings and pipeline section isolation in treatment plant infrastructure.
- Snap-on:Push-fit designs accelerate retail and emergency repair channels where excavation exposure time drives cost structures.
Contractor preference runs toward Welded for permanence; retail channels favor Snap-on velocity.
End User:
Customer type dictates volume scale, specification authority, and pricing negotiation leverage across the value chain.
- Contractors:Municipal and commercial installation firms drive bulk procurement through framework agreements. Centralized purchasing through US state-level rural water associations and England's regulated water companies concentrates vendor qualification requirements.
- Manufacturers:OEM pipeline system producers bundle end caps with integrated fitting assemblies for vertical product portfolios.
- Distributors:Independent stocking intermediaries serve fragmented smaller municipal systems losing specification influence to cooperative purchasing agreements.
- Retailers:Hardware and plumbing supply channels capture repair-driven demand with lower technical support requirements.
Procurement authority is consolidating toward Contractors; Retailers retain transactional volume.
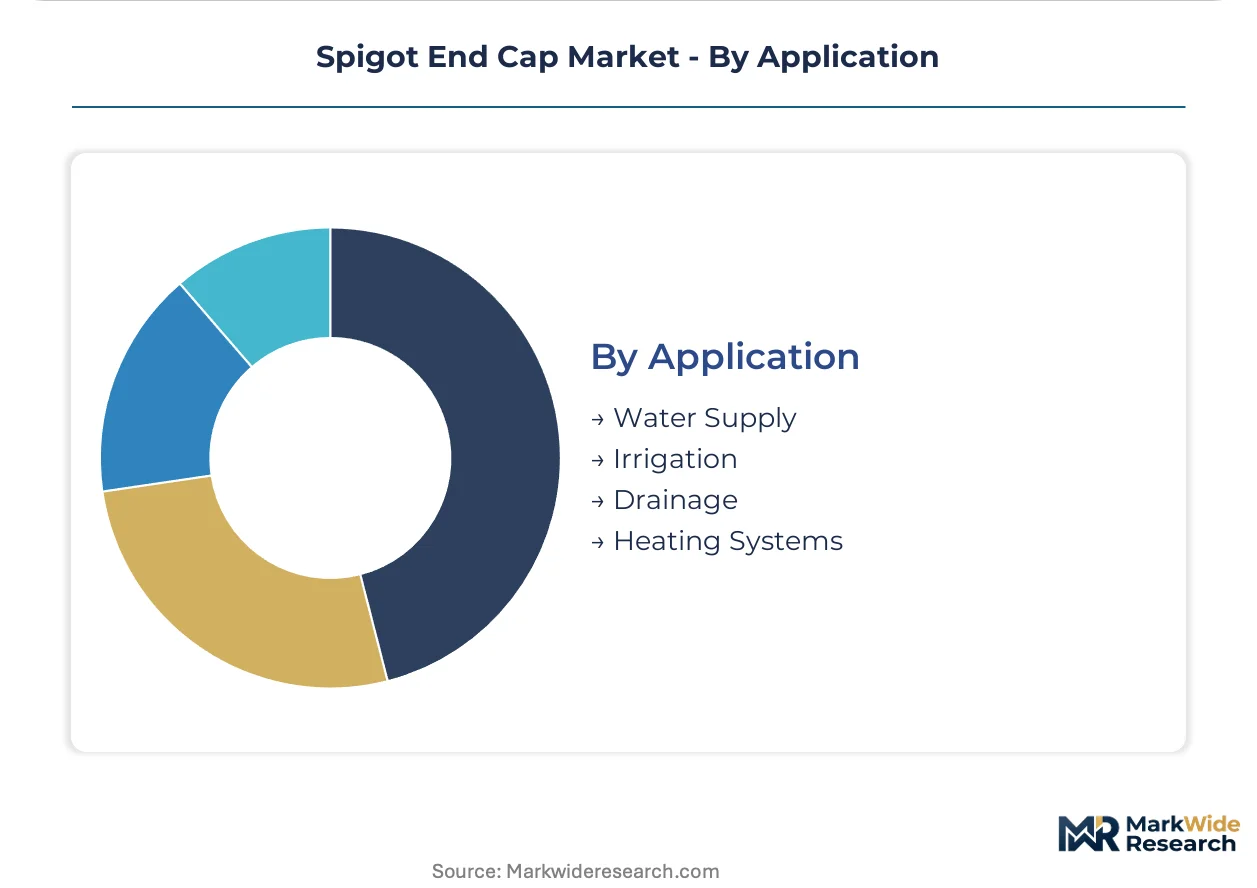
Application:
Use-case environments impose distinct pressure ratings, temperature ranges, and regulatory compliance frameworks.
- Water Supply:Potable distribution networks demand FDA material contact approvals and EPA Safe Drinking Water Act compliance. US municipal infrastructure replacement cycles anchor volume concentration.
- Heating Systems:High-temperature hydronic and steam applications sustain metal variant demand despite polymer cost advantages.
- Irrigation:Agricultural and landscape water management prioritizes UV resistance and seasonal installation flexibility over pressure permanence.
- Drainage:Stormwater and wastewater conveyance tolerates lower pressure ratings with emphasis on chemical resistance and debris passage geometry.
Regulatory stringency peaks in Water Supply; cost sensitivity dominates Drainage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Anatolian Natural Gas Pipeline anchors Turkey's emerging role as a manufacturing-export hub for spigot end caps, while Germany's Rhine-Ruhr industrial corridor sustains established precision extrusion capacity serving Central European utilities.
United States
Municipal water infrastructure replacement cycles in the Sun Belt and Rust Belt drive procurement volume for fusion-welded spigot end caps. EPA Safe Drinking Water Act enforcement eliminates brass alloy variants from potable specifications, redirecting demand toward HDPE formulations. Houston-based distributors serve Permian Basin oilfield water transfer networks with pressure-rated polymer fittings.
Germany
Central European utility contractors specify butt-fusion compatible spigot end caps for buried pipeline networks spanning the Rhine-Ruhr metropolitan region. REACH Annex XVII restrictions on phthalate plasticizers force PVC compound reformulations among suppliers serving EEA markets. Wavin maintains extrusion facilities in North Rhine-Westphalia capturing cross-border procurement from Polish infrastructure programs.
Turkey
Expanded HDPE extrusion capacity near Istanbul positions suppliers to serve Middle Eastern water infrastructure programs at cost-advantaged freight economics. The country's national standardization body aligns polymer specifications with ASTM International fusion welding protocols. Kuzeyboru Plastik leverages captive resin supply from petrochemical complexes along the Marmara Sea coast.
China
Municipal water diversion projects under the South-North Water Transfer Program sustain demand for high-volume spigot end cap production. GB standards for polyethylene piping systems govern pressure rating classifications in domestic procurement. Yangtze River Delta fabricators export containerized fittings to Southeast Asian irrigation contractors.
India
Jawaharlal Nehru National Urban Renewal Mission funding accelerates underground utility modernization in metropolitan regions. BIS certification requirements for potable water contact materials reshape supplier qualification protocols. Gujarat-based extrusion clusters serve Rajasthan agricultural pipeline schemes with UV-stabilized HDPE formulations.
Spigot End Cap Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream serving specification-driven municipal contracts and price-sensitive agricultural channels. The vendor base stratifies across three tiers: multinational pipeline system suppliers with electrofusion bundling capabilities, regional extrusion specialists with backward resin integration, and distributed fabricators serving repair-driven retail channels. Two dominant competitive moves are reshaping positioning: geographic expansion through Turkish and Chinese manufacturing bases to capture Middle Eastern and Southeast Asian infrastructure cycles, and portfolio diversification into electrofusion coupling integration to collapse contractor installation protocols.
Among European-based system suppliers, Fusion Group and NORMA Group SE occupy positions exemplifying divergent strategic archetypes—electrofusion technology leadership versus clamp and fastening system bundling. Plastitalia S.p.A. represents Mediterranean-focused precision extrusion specialization serving Southern European utility frameworks. These three anchors illustrate how competitive positioning fragments across technology integration depth, geographic service radius, and procurement channel concentration.
| Leading Market Players |
|---|
| Plastitalia S.p.A. |
| Fusion Group |
| NORMA Group SE |
| Kuzeyboru Plastik |
| Adroit Piping Systems |
| Macplast Industries |
| Drainfast Ltd |
| T-mex Industrial |
| Wavin |
| Others |
Value Network & Pricing Analysis
Marmara Sea freight corridors connecting Istanbul to Middle Eastern port networks compress landed costs for Turkish extrusion suppliers, concentrating supply-side pricing power among resin-integrated manufacturers while forcing German and Chinese competitors into certification-grade differentiation to defend margin structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by ASTM fusion certification grade and volume commitment scale. Premium tiers command positioning through electrofusion compatibility and third-party pressure testing documentation, while economy tiers serve agricultural irrigation channels where UV stabilization substitutes for weld integrity. Cost compression in standard-grade HDPE formulations is intensifying because of ethylene feedstock volatility tied to naphtha cracking spreads. Municipal contractors exhibit lowest price sensitivity due to total-cost-of-ownership procurement frameworks; retail hardware channels face acute sensitivity to per-unit differentials.
Supply Chain Analysis
Extended payment terms from Turkish petrochemical complexes to extrusion operators anchor working capital structures across the supply base. Manufacturing concentrates in Germany, Turkey, and China, with each hub serving distinct regional procurement frameworks. Raw material dependencies rest on high-density polyethylene resin, calcium-zinc stabilizer systems, and electrofusion heating element components. Single-source vulnerability runs through specialized electrofusion coupling suppliers concentrated in Central European industrial corridors. Distribution runs through regional water authority cooperative purchasing agreements in the United States and England, bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spigot end cap market is positioned for cyclical recovery as municipal water infrastructure replacement cycles accelerate across Sun Belt and Rust Belt regions in the United States. Federal funding allocations through state revolving loan funds are amplifying procurement velocity for fusion-welded pipeline components.
For Market Incumbents: Harden specification control by embedding spigot end caps within proprietary electrofusion system architectures that lock contractor workforces into certified training ecosystems. Deepen backward integration into HDPE resin compounding to buffer margin exposure from ethylene feedstock volatility. Fusion Group and Wavin face emerging pressure from Turkish suppliers with captive petrochemical supply; defensive certification investments in ASTM F1055 compliance documentation sustain contract eligibility against lower-cost entrants. For New Entrants and Emerging Players: Mid-scale agricultural irrigation contractors in India's Gujarat and Rajasthan corridors represent the most penetrable entry point, as BIS certification requirements remain less stringent than FDA/EPA frameworks governing potable water specifications. Turkish export manufacturing bases already demonstrate viable cost positioning for Middle Eastern infrastructure programs; new entrants should replicate this model through Marmara Sea logistics access. A go-to-market angle bundling snap-fit repair configurations with seasonal installation support captures replacement cycle demand outside municipal procurement frameworks. For Investors and Strategic Acquirers: Regional extrusion specialists with backward resin integration and established utility contractor relationships present the most attractive acquisition archetype for portfolio exposure to infrastructure replacement cycles. Long-term viability hinges on positioning ahead of PFAS regulatory restrictions across European and North American jurisdictions. The signal to monitor is ECHA expansion of Annex XVII restrictions to fluorinated polymer processing aids, which would force accelerated reformulation investments and consolidate advantage among first-mover fluorine-free compound developers.| Strategic Initiative | Industry Significance |
|---|---|
| Electrofusion System Integration | Bundled spigot end caps with heating-element couplings collapse contractor installation protocols and lock in specification control. |
| Backward Resin Integration | Captive HDPE compounding from petrochemical feedstock buffers margin compression from ethylene price volatility. |
| PFAS-Free Formulation Development | First-mover fluorine-free polymer compounds capture regulatory tailwinds from anticipated ECHA and EPA restrictions. |
| Turkish Manufacturing Expansion | Marmara Sea logistics access positions cost-advantaged supply to Middle Eastern and North African infrastructure programs. |
| ASTM Certification Investment | Third-party pressure testing documentation sustains contract eligibility in US municipal water authority procurement frameworks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal utility procurement managers, electrofusion equipment distributors, HDPE resin procurement leads at extrusion facilities, and contractor field supervisors across US Sun Belt and Central European infrastructure programs. Secondary validation drew from EPA Safe Drinking Water Act enforcement records, ASTM International standards documentation, ECHA REACH Annex XVII restriction updates, and customs trade data for polyethylene pipe fitting classifications. Bottom-up volume estimates from regional water authority purchasing agreements were triangulated against top-down petrochemical consumption models for HDPE injection molding grades.
Calibration against historical replacement cycle patterns and regulatory enforcement timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material specification tiers, installation methodology categories, end-user procurement authority structures, and application-specific pressure rating requirements. CAGRs were derived from elasticity-adjusted demand curves incorporating infrastructure funding disbursement schedules and resin price forecasting models. Industry-specific inputs encompassed fusion technician certification scarcity indices and municipal procurement centralization trends.
Practitioners should monitor ECHA PFAS restriction proposals, EPA lead-free mandate enforcement intensity, and ethylene-naphtha spread volatility for early signals of forecast deviation. The analysis reflects assumptions regarding continued municipal infrastructure funding availability and ASTM fusion welding protocol adoption rates. Macroeconomic contraction, accelerated regulatory chemistry restrictions, or breakthrough mechanical coupling technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Sterile Lids Market
Caps and Closures
Cap Seals Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Crown Caps Market
Caps and Closures
Cover Caps Market
Caps and Closures
Canada Plastic Caps and Closures Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Screw Closure Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
Lug Caps Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
Disc Top Caps Market
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Sport Caps and Closures Market