
 Low Profile Compact System Closures Market | 2026-2036
Low Profile Compact System Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Low Profile Compact System Closures Market Outlook
Asset-light leasing models for injection molding equipment are rewriting competitive entry barriers in closure manufacturing. Berry Global leverages captive resin compounding to sustain margin control across multi-material product lines. Crown Holdings anchors its position through deep metal-forming expertise that competes with plastic alternatives in premium beverage segments. Silgan Holdings specializes in high-volume screw-on closure production that dominates North American food packaging channels.
Low profile compact system closures are precision-engineered sealing devices, typically measuring under 25 millimeters in installed height, manufactured through injection molding or metal stamping to provide tamper-evident and hermetic sealing for containers. These closures serve primary industrial purposes in pharmaceutical vials, carbonated beverage bottles, and cosmetic dispensers where space constraints and child safety requirements converge. Snap-on and child-resistant closure categories are capturing disproportionate investment as regulatory safety mandates tighten across end-use sectors. Plastic material formulations, particularly polypropylene and polyethylene blends, lead unit volume while composite substrates represent the fastest-growing margin pool due to barrier performance advantages.
FDA child-resistant packaging standards and EMA pharmaceutical serialization directives shape product design requirements and testing protocols for closure manufacturers seeking market access. REACH chemical compliance and EU MDR medical device regulations further constrain material selection and supplier qualification processes in European markets. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in closed-loop recycling-compatible closure designs before compliance deadlines harden.
Market Dynamics
Asset-light equipment leasing is restructuring capital deployment across closure manufacturing, allowing regional molders to compete without owning full injection press fleets. This financing innovation is compressing traditional scale advantages held by integrated resin-to-closure producers.
Growth Catalysts
- FDA Child-Resistant Mandates:Pharmaceutical packaging lines must certify vial closures under 16 CFR 1700 protocols, forcing reformulation of snap-fit mechanisms and driving replacement cycles across generic drug portfolios.
- Polypropylene Barrier Blends:Advanced nucleated PP copolymers with ethylene vinyl alcohol interlayers are displacing metal closures in carbonated beverage segments, cutting unit weight while maintaining CO2 retention.
- Stuttgart Precision Cluster:German tooling houses around Baden-Württemberg supply multi-cavity hot-runner molds to global pharma brands, concentrating technical know-how for 24-cavity high-speed production.
Market Restraints
- Resin Price Volatility:Polypropylene homopolymer feedstock tied to naphtha cracking economics exposes margin structures to petrochemical cycle swings without long-term offtake hedging.
- REACH Compliance Friction:ECHA substance restrictions on phthalate plasticizers and bisphenol derivatives force reformulation of legacy seal compounds, extending qualification timelines for European market access.
- Metal Substitution Persistence:Crown Holdings and Ball Corporation maintain aluminum roll-on closures in premium spirits and wine segments where oxygen scavenging and tactile heft resist full plastic conversion.
Strategic Opportunities
- Closed-Loop Recycling Design:Mono-material PP closures with detachable liners align with EU Packaging and Packaging Waste Regulation targets, positioning early adopters for extended producer responsibility compliance.
- Biologic Drug Delivery:Prefilled syringe and auto-injector formats require ultra-low profile luer-lock closures with elastomeric needle shields, opening specialty margins beyond commodity vial seals.
- Direct Equipment Leasing:Engel and KraussMaffei now offer mold-trial-to-production subscription models, letting contract manufacturers scale capacity without 18-month capital approval cycles.
Industry Challenges
- Hot-Runner Technician Scarcity:Multi-zone temperature control systems for 32-cavity pharmaceutical molds require specialized maintenance skills concentrated among aging European tooling specialists.
- Serialization Integration:EU MDR and FDA DSCSA mandates demand laser-etched closure surfaces compatible with track-and-trace databases, complicating mold cavity design and validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Profile Compact System Closures Market |
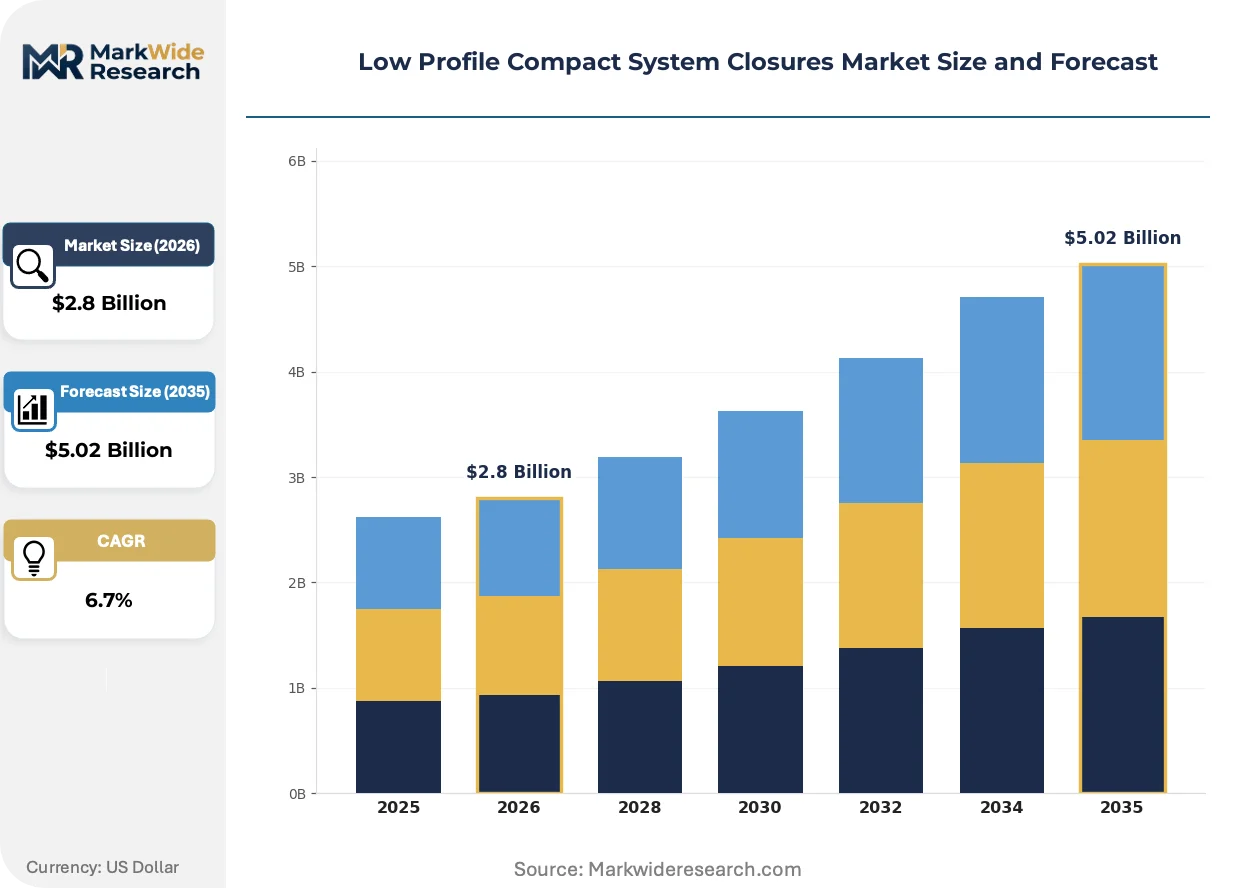
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snap-On Closures, Screw-On Closures, Push-Pull Closures, Child-Resistant Closures Material: Plastic, Metal, Composite, Glass End User: Pharmaceuticals, Food & Beverage, Cosmetics, Household Care Application: Packaging, Dispensing, Sealing, Protection |
| Companies Covered | Berry Global, Crown Holdings, Silgan Holdings, Closure Systems International, AptarGroup, OBerk Company, Vetroplas Packaging, PolyChem Alloy, Guala Closures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Profile Compact System Closures Market Strategic Shifts
Digital mold simulation and in-mold sensor networks are compressing development cycles for complex child-resistant mechanisms. These capabilities are redistributing competitive advantage toward data-integrated manufacturers.
Digital twin platforms for injection molding are collapsing prototype-to-production timelines from 14 weeks to under 6 weeks for multi-component closures. Medical device contract manufacturers in Minnesota and Massachusetts are adopting these simulations to accelerate FDA submission packages. The technology is collapsing traditional barriers between tooling houses and brand-owner engineering teams.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of fluoropolymer barrier coatings used in pharmaceutical closures. European compounders are pivoting to ceramic-filled polyethylene blends that maintain moisture vapor transmission rates without PFAS chemistry. The German generics sector is absorbing the steepest qualification costs as existing drug master files require resubmission.
Buyers in North American food packaging are consolidating supplier bases from 12-15 vendors to 3-4 strategic partners with captive resin compounding and regional distribution. This concentration is displacing spot-market procurement for standard screw closures. The shift is most visible in private-label condiment and sauce segments where retailers now mandate single-source accountability for recall liability.
Low Profile Compact System Closures Market Segmentation
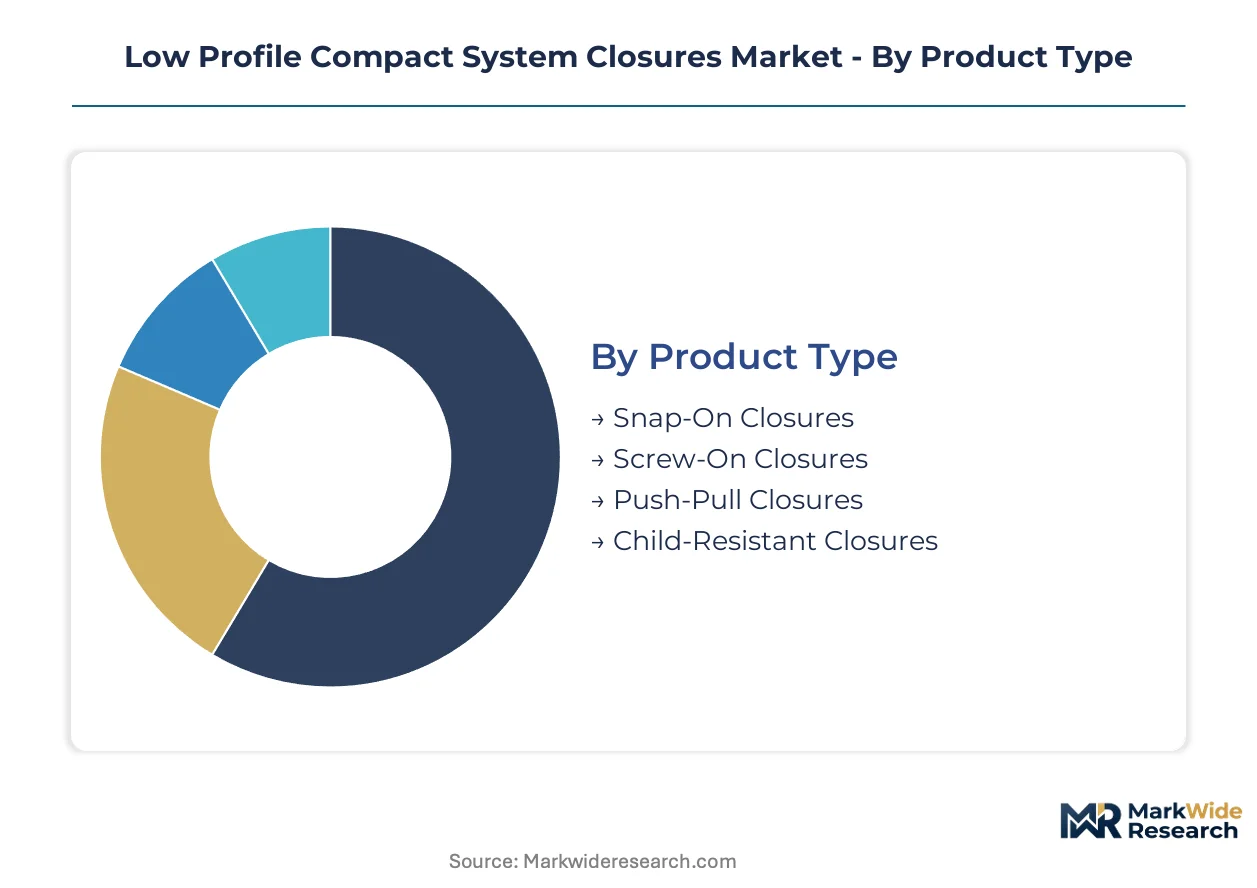
Segmentation in low profile compact system closures reveals distinct procurement rhythms and margin structures across product architectures, material formulations, and end-use verticals. Pharmaceutical and beverage buyers operate on fundamentally different replacement cycles, forcing manufacturers to balance inventory turns against qualification rigor.
Product Type:
Screw-on closures turn inventory fastest through standardized beverage contracts, while child-resistant mechanisms face 18-month FDA validation cycles that freeze design specifications.
- Screw-On Closures:Continuous thread designs with standardized GPI/SPI neck finishes dominate high-volume carbonated beverage lines. German molders around Stuttgart supply 24-cavity hot-runner systems to Coca-Cola and Pepsi bottlers under 6-week replenishment schedules.
- Child-Resistant Closures:Push-and-turn mechanisms with torque-resistant liners require multi-component assembly and 16 CFR 1700 protocol certification. Generic drug manufacturers in India and the United States absorb extended lead times to secure FDA-compliant vial seals for chronic medication portfolios.
- Snap-On Closures:Peripheral bead retention systems serve cosmetic dispensers and single-serve condiment packs with tool-free opening.
- Push-Pull Closures:Integrated spout-and-valve designs target sports nutrition and isotonic beverage segments requiring one-handed dispensing.
Screw-on formats anchor the volume base while child-resistant closures gain share at the steepest rate.
Material:
Cost tiers separate commodity resin compounds from engineered barrier substrates, with qualification expense creating divergent customer switching economics.
- Plastic:Polypropylene homopolymer and nucleated copolymer formulations deliver sub-gram unit weights for beverage applications. REACH Annex XVII restrictions on phthalate plasticizers force European compounders toward bio-based alternatives with equivalent Shore D hardness.
- Composite:Ceramic-filled polyethylene and ethylene vinyl alcohol interlayer structures displace metal in oxygen-sensitive pharmaceutical applications. Japanese drug delivery device manufacturers specify these substrates for prefilled syringe luer-lock seals.
- Metal:Aluminum roll-on and ROPP closures retain premium spirits and wine segments where oxygen scavenging and tactile heft command price premiums.
- Glass:Ground glass stoppers with PTFE-faced seals serve laboratory reagent and high-purity chemical containment in limited specialty volumes.
Plastic formulations dominate unit economics while composite substrates expand most quickly in value terms.
End User:
Application maturity varies sharply, with pharmaceutical and food packaging operating under binding regulatory mandates while cosmetics and household care follow discretionary design trends.
- Pharmaceuticals:Prefilled syringes, auto-injectors, and oral solid dose bottles require ISO 15378 compliant closure systems with extractables testing. FDA DSCSA serialization mandates laser-etched closure surfaces compatible with track-and-trace infrastructure.
- Food & Beverage:Carbonated soft drink and condiment categories drive the highest absolute volume, with private-label retailers consolidating supplier bases to 3-4 strategic partners for recall liability containment.
- Cosmetics:Airless pump and dropper closures follow seasonal color cosmetic launches with compressed 8-week development windows.
- Household Care:Trigger sprayers and dosing caps for cleaning concentrates face less stringent migration testing than food-contact applications.
Food and beverage categories provide the volume foundation while pharmaceutical applications deliver the steepest margin expansion.
Application:
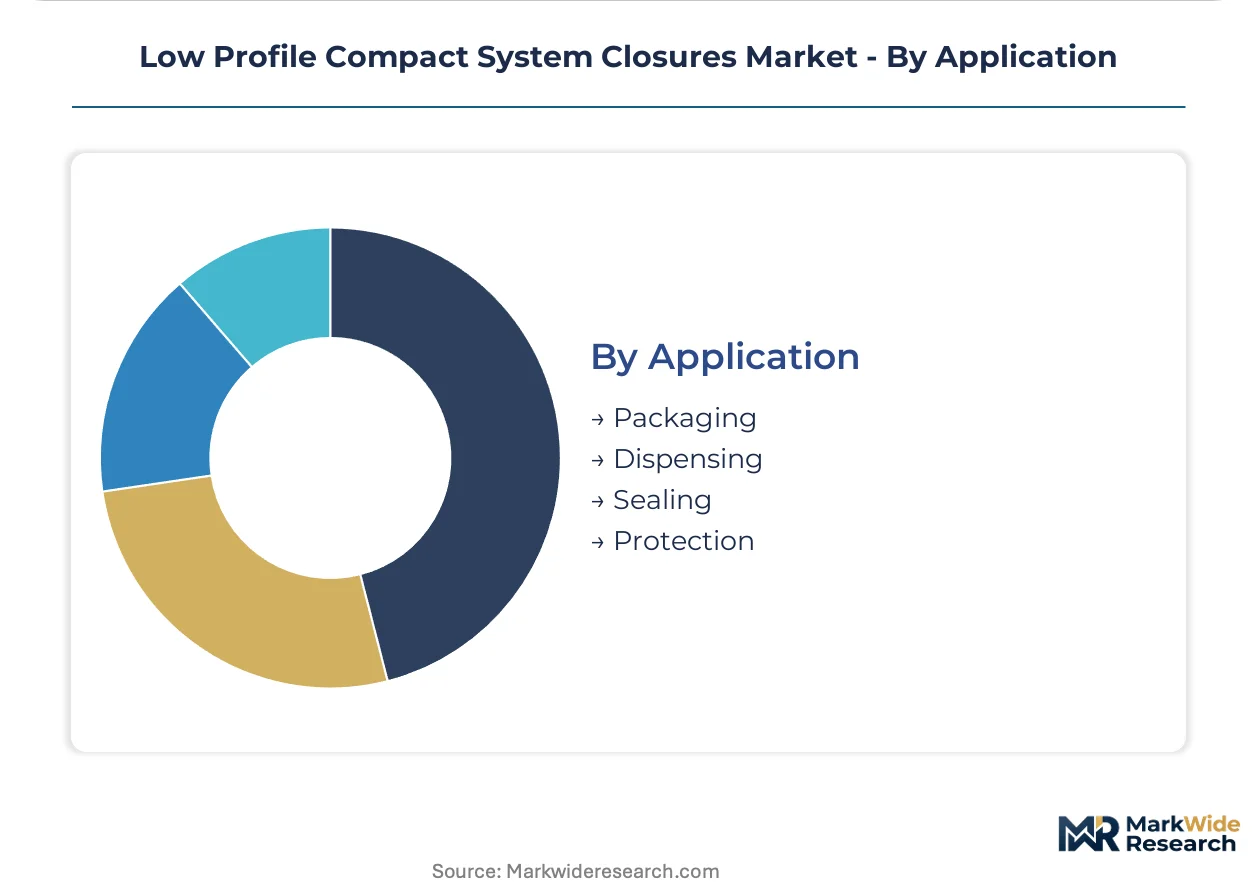
Functional purpose determines performance specification intensity, with sealing and protection roles commanding tighter tolerance bands than basic packaging functions.
- Sealing:Hermetic closure systems with elastomeric liners maintain CO2 retention in carbonated beverages and moisture vapor transmission barriers in pharmaceutical vials. EMA serialization directives and FDA child-resistant mandates converge on this application with the strictest validation protocols.
- Protection:Tamper-evident bands and breakaway rings serve authentication and safety functions across over-the-counter medications and premium spirits. EU MDR medical device regulations extend these requirements to diagnostic reagent closures.
- Packaging:Basic containment functions without active barrier requirements serve commodity dry goods and non-reactive chemicals.
- Dispensing:Controlled-flow orifices and flip-top spouts enable measured dosing in personal care and automotive fluid applications.
Sealing applications concentrate procurement spend while protection functions climb fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision molders capture 15-20% price premiums over Indian contract manufacturers for pharmaceutical-grade closures, while Chinese resin compounders undercut both on commodity beverage formats by 8-12%.
Germany
Baden-Württemberg tooling houses supply 24-cavity hot-runner molds to global pharma brands under compressed qualification timelines. REACH Annex XVII restrictions on phthalate plasticizers force compounders toward bio-based alternatives. Stuttgart precision clusters concentrate technical know-how for child-resistant mechanism validation.
United States
FDA 16 CFR 1700 child-resistant mandates drive replacement cycles across generic drug portfolios. DSCSA serialization directives require laser-etched closure surfaces compatible with track-and-trace infrastructure. Minnesota and Massachusetts medical device contract manufacturers adopt digital twin simulations to accelerate FDA submission packages.
China
NMPA pharmaceutical packaging standards converge with international GMP protocols for export-oriented manufacturers. Dual carbon goals accelerate shifts toward lightweight polymer designs in domestic beverage markets. Yangtze River Delta resin compounders scale nucleated PP copolymer production for carbonated soft drink closures.
India
CDSCO tightening of pharmaceutical packaging norms forces domestic generic manufacturers toward ISO 15378 compliant closure systems. Maharashtra and Gujarat injection molders expand capacity for oral solid dose bottle seals. Gujarat petrochemical corridors supply cost-competitive polypropylene feedstock to regional closure fabricators.
Japan
METI industrial standards for pharmaceutical packaging materials exceed baseline ICH requirements, filtering supplier qualification. PMDA serialization mandates align with FDA and EMA track-and-trace protocols. Kanto region drug delivery device manufacturers specify ceramic-filled polyethylene blends for prefilled syringe luer-lock seals.
Low Profile Compact System Closures Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in resin compounding and precision tooling. The vendor base spans three distinct tiers: integrated resin-to-closure producers with captive compounding, contract molders leveraging asset-light equipment leasing, and regional specialists in regulatory-intensive pharma formats. Strategic differentiation concentrates on backward integration into resin supply, geographic proximity to FDA/EMA inspection zones, and mold-trial-to-production subscription models that compress capital deployment cycles.
Among North American packaging conglomerates, Berry Global exemplifies the integrated archetype through captive resin compounding across multi-material portfolios. Crown Holdings occupies a position anchored in deep metal-forming expertise that competes with plastic alternatives in premium beverage segments. Silgan Holdings sits within the high-volume screw-on closure specialization that dominates food packaging channels. These three represent divergent competitive vectors: material integration, metal-forming heritage, and scale-driven standardization.
| Leading Market Players |
|---|
| Berry Global |
| Crown Holdings |
| Silgan Holdings |
| Closure Systems International |
| AptarGroup |
| OBerk Company |
| Vetroplas Packaging |
| PolyChem Alloy |
| Guala Closures |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese injection molding clusters is compressing spot-market resin pricing and forcing German precision molders toward configured-to-order service bundles that protect margin structures. This utilization asymmetry between Asia-Pacific commodity producers and European specialty manufacturers is bifurcating procurement behavior across pharmaceutical and beverage buyer segments.
Pricing Analysis
The customization-premium spread separates standard screw closures from validated pharmaceutical-grade seals by a factor of three to five, with FDA 16 CFR 1700 certification costs embedded in configured pricing. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade and certification tier differentiation. Price erosion runs through commodity beverage formats as Yangtze River Delta compounders absorb resin volatility to maintain volume share. Generic drug manufacturers exhibit highest price sensitivity due to thin portfolio margins, while biologic drug delivery device makers prioritize barrier performance over unit cost.
Supply Chain Analysis
Export-control regimes limiting multi-cavity hot-runner mold technology flows from Germany and Japan to unlicensed destinations are fragmenting equipment access across emerging manufacturing bases. Supply concentrates in Germany for precision pharma tooling, China for nucleated PP copolymer resin, and India for oral solid dose bottle seal fabrication. Raw material dependencies rest on naphtha-derived polypropylene homopolymer, ethylene vinyl alcohol barrier interlayers, and ceramic-filled polyethylene compounds. Single-source vulnerability concentrates in Stuttgart-area tooling houses with specialized 32-cavity mold maintenance expertise. Distribution runs through direct equipment leasing subscriptions and regional compounder networks serving FDA-inspected pharmaceutical zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against aluminum roll-on closures in premium spirits and wine segments where oxygen scavenging performance resists full polymer conversion. Metal-forming incumbents leverage tactile heft and barrier heritage to slow plastic displacement.
For Market Incumbents: Pre-empt resin price volatility exposure through captive compounding capacity or long-term offtake hedging with Gulf Coast petrochemical producers. Consolidate mold maintenance technician training programs to address aging European specialist scarcity. Defend against asset-light regional molders by embedding digital twin simulation capabilities that compress customer qualification timelines.
For New Entrants and Emerging Players: Build out prefilled syringe luer-lock seal capabilities targeting Japanese and North American biologic drug delivery device manufacturers. Target Maharashtra and Gujarat injection molding corridors where CDSCO compliance investments create qualification barriers for uncommitted competitors. Pursue mold-trial-to-production subscription partnerships with Engel or KraussMaffei to bypass 18-month capital approval cycles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across contract manufacturing segments as equipment leasing models displace owned press fleets. Five-to-ten year viability favors compounders with backward integration into bio-based resin alternatives ahead of REACH Annex XVII hardening. Target acquisition archetype: German precision molders with validated 24-cavity hot-runner pharmaceutical production and embedded FDA inspection relationships. Watch for inflection in EU Packaging and Packaging Waste Regulation extended producer responsibility compliance deadlines as signal for closed-loop recycling design valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Berry Global's captive PP formulation control sustains margin across multi-material portfolios. |
| Digital Twin Platform Adoption | Minnesota medical device contract manufacturers collapse FDA submission timelines from 14 weeks to 6 weeks. |
| Closed-Loop Recycling Design Certification | Mono-material PP closures with detachable liners align with EU Packaging and Packaging Waste Regulation targets. |
| Hot-Runner Mold Leasing Subscriptions | Engel and KraussMaffei subscription models let regional molders scale without capital approval cycles. |
| Ceramic-Filled Polyethylene Reformulation | Japanese drug delivery device manufacturers specify PFAS-free barrier substrates for prefilled syringe seals. |
Study Parameters
Initial hypotheses were tested against primary input from injection molding plant managers, pharmaceutical packaging procurement leads, FDA regulatory affairs specialists, and hot-runner mold maintenance technicians and refined through secondary validation. Primary fieldwork drew from structured interviews across Baden-Württemberg tooling houses, Minnesota medical device contract manufacturers, and Gujarat petrochemical corridor operators. Secondary sources included FDA 16 CFR 1700 protocol documentation, ECHA REACH Annex XVII substance restriction filings, SEC 10-K disclosures from packaging conglomerates, and customs data on polypropylene resin trade flows. Bottom-up unit economics for closure categories were triangulated against top-down market sizing from resin consumption patterns.
Demand-supply-balance framing anchored the forecast framework across the analysis window, modeling volume and value outputs through segmentation dimensions of product architecture, material formulation grade, end-use regulatory intensity, and geographic production cluster. CAGRs were derived from trend extrapolation of replacement cycle dynamics and qualification timeline compression. Industry-specific inputs included pharmaceutical serialization mandate implementation schedules and carbonated beverage lightweighting targets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed resin compounders or German tooling house consolidation would shift outcomes. Material shifts in REACH Annex XVII substance restriction scope or FDA child-resistant packaging protocol revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Saudi Arabia Plastic Caps and Closures Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
China Plastic Caps and Closures Market
Caps and Closures
United States Plastic Caps and Closure Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Gamma Seal Lids Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Dauber Caps Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
Canada Plastic Caps and Closures Market
Caps and Closures
Screw Caps and Closure Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
APAC Plastic Caps and Closures Market