
 Egypt Plastic Caps and Closures Market | 2026-2036
Egypt Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Plastic Caps and Closures Market Insights
Small-batch cosmetic manufacturers is collapsing as a buyer archetype while large-format beverage bottlers consolidate procurement volumes. Bericap Egypt anchors its position through captive technical-service teams stationed at client filling lines. NatPack differentiates via customized color-matching and liner formulations for pharmaceutical clients. El Safa Plast Mold and Plastic Factory competes on rapid tool-turnaround for regional dairy brands needing seasonal cap redesigns.
Plastic caps and closures are injection-molded or compression-molded thermoplastic components, typically manufactured from polypropylene or polyethylene, designed to seal container openings against leakage, contamination, and tampering. Screw caps dominate the product-type landscape due to their resealability and compatibility with automated capping equipment across high-speed beverage lines. Polypropylene leads the material mix because its fatigue resistance supports repeated opening cycles in household chemical applications. Dispensing caps represent the fastest-growing product configuration, driven by viscosity-controlled dosing requirements in personal care and pharmaceutical segments where precision delivery commands margin premiums.
Egypt's Ministry of Trade and Industry enforces EOS quality certifications for food-contact plastics, while the Environmental Affairs Agency advances extended-producer-responsibility frameworks affecting post-consumer cap collection targets. Compliance with these dual regulatory tracks shapes resin selection, recyclability labeling, and supplier qualification protocols for both domestic and import-dependent brands. Stakeholders must monitor how forthcoming packaging-waste regulations redistribute compliance costs between resin suppliers, converters, and downstream brand owners.
Market Dynamics
Egypt's food processing modernization is compressing procurement cycles for tamper-evident closures, forcing converters to align resin grades with tightened EOS food-contact standards while beverage bottlers consolidate volumes around technical-service partnerships.
Growth Catalysts
- Food-contact compliance mandates:EOS tightened material rules are pushing converters toward certified polypropylene and polyethylene grades that meet pharmaceutical and beverage safety thresholds.
- Beverage sector automation:High-speed filling lines across Greater Cairo's industrial corridor are standardizing screw-cap formats compatible with automated capping equipment.
- Dispensing precision requirements:Personal care and pharmaceutical segments are demanding viscosity-controlled dosing caps that command margin premiums through technical differentiation.
Market Restraints
- Resin price volatility:Polypropylene feedstock costs fluctuate with naphtha and propylene monomer pricing, squeezing converter margins on fixed-price annual contracts.
- Tooling concentration risk:Mold fabrication capacity clusters in limited industrial zones, extending lead times for seasonal dairy cap redesigns.
- Collection infrastructure gaps:Extended producer responsibility frameworks lack downstream sorting capacity, limiting post-consumer cap recyclability claims.
Strategic Opportunities
- Pharmaceutical liner specialization:Customized induction-seal formulations for moisture-sensitive drug packaging remain underdeveloped relative to beverage-dominant production.
- Upper Egypt distribution penetration:Dairy and edible oil brands in Sohag and Qena governorates rely on imported closures, creating white space for domestic molding capacity.
- Color-matching service tiers:Cosmetic manufacturers are collapsing as a buyer archetype, but surviving mid-scale players pay premiums for rapid Pantone-matched production runs.
Industry Challenges
- Multi-cavity mold design expertise:Compression molding for high-volume beverage caps requires specialized thermal management knowledge that local toolrooms struggle to retain.
- Dual-track compliance timelines:Simultaneous EOS quality certifications and Environmental Affairs Agency waste-framework adherence create overlapping audit burdens without harmonized documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Plastic Caps and Closures Market |
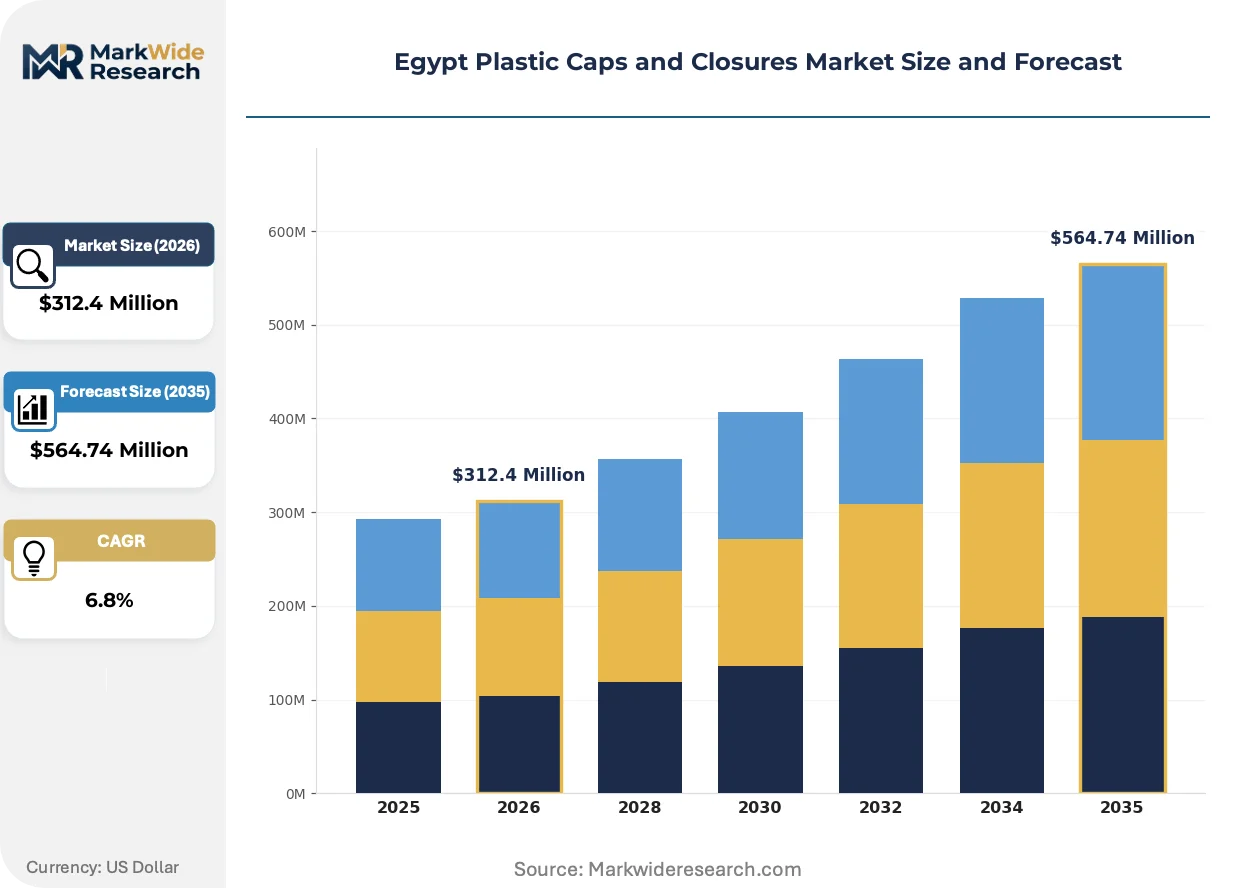
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Caps, Screw Caps, Snap-on Caps, Dispensing Caps Material: Polypropylene, Polyethylene, PET, PVC Application: Beverages, Personal Care, Pharmaceuticals, Household Chemicals End User: Food Industry, Cosmetic Manufacturers, Medical Facilities, Cleaning Sector |
| Companies Covered | Amcor Plc, Tetra Pak International S.A., Bericap Egypt, NatPack, El Safa Plast Mold and Plastic Factory, Delta Egypt Plastic, Aptar Group, Delpack SA, Alpla, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Plastic Caps and Closures Market Trends and Innovations
Tamper-evidence mechanisms and sustainable material formulations are reshaping converter R&D priorities across Egypt's packaging value chain. Technical-service integration at client filling lines is becoming the primary competitive differentiator.
Lightweighting through short-shot compression molding is decomposing the traditional trade-off between material reduction and seal integrity. Beverage bottlers in 6th of October City industrial parks are adopting thinned-wall closures at accelerated trial frequencies. This technology is decomposing legacy injection-molding capacity utilization as converters retool for lower-cycle-time production.
EOS harmonization with Codex Alimentarius standards is tightening migration limit testing for food-contact polyolefins. Converters must now maintain dual laboratory certifications for volatile organic compound and heavy metal screening. Pharmaceutical and infant nutrition segments are absorbing these compliance costs through dedicated production line segregation.
Consolidated procurement by large-format bottlers is compressing supplier rosters from multi-source to single-source technical partnerships. Regional dairy brands in Alexandria and Damietta are losing negotiating leverage as national distributors centralize cap purchasing through Bericap Egypt's embedded service teams. This concentration is most visible in the carbonated soft drink vertical, where annual volume commitments now determine mold investment allocation.
Egypt Plastic Caps and Closures Market Segmentation
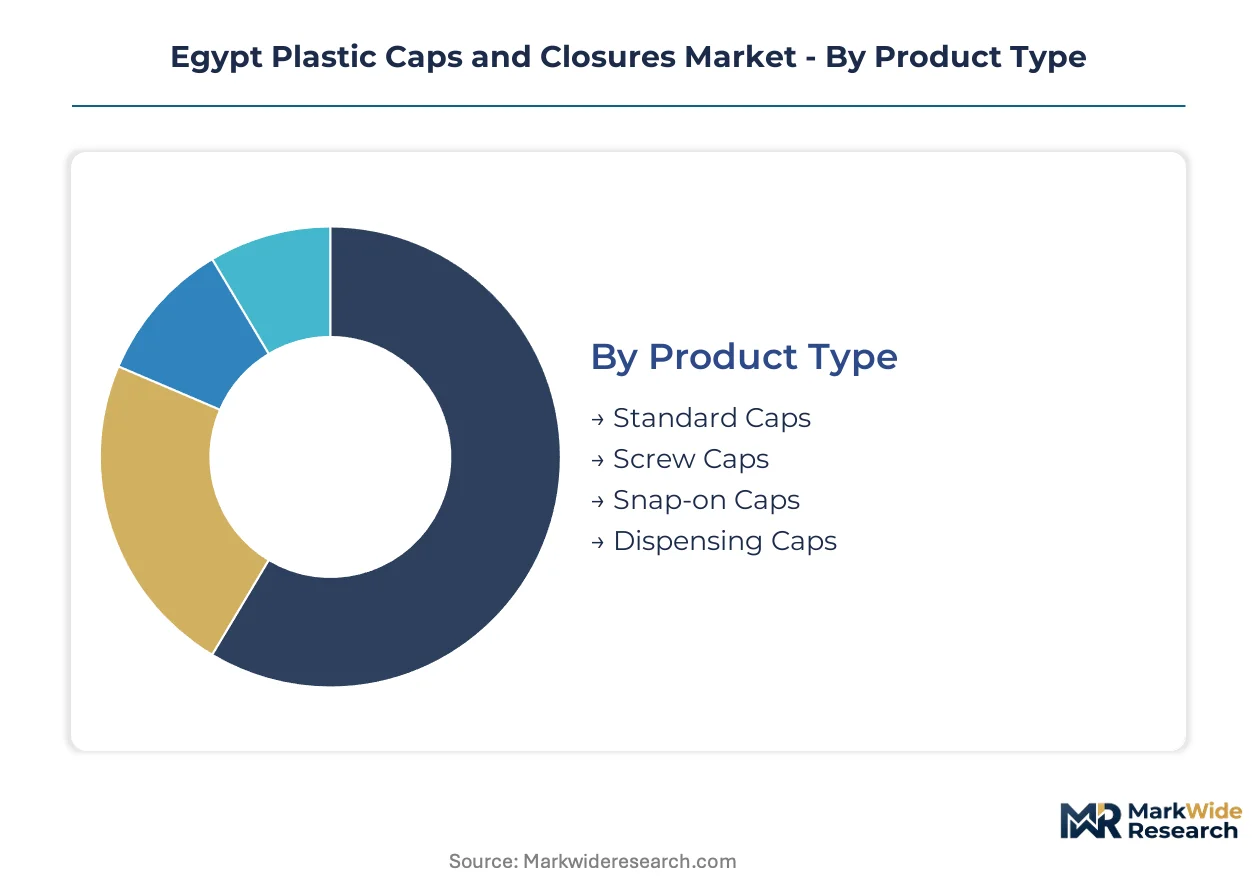
Segmentation in Egypt's plastic caps and closures market reveals how procurement concentration, regulatory compliance tiers, and end-use automation requirements reshape converter capacity allocation across the Greater Cairo industrial corridor and Upper Egypt distribution networks.
Product Type:
Domestic production concentrates on formats serving high-volume beverage bottlers in 6th of October City and 10th of Ramadan industrial zones, while export-oriented specialty configurations cluster around Alexandria's port-accessible molding facilities.
- Screw Caps:Injection-molded polypropylene or polyethylene closures with continuous helical threads enabling repeated opening cycles. Demand clusters around carbonated soft drink and bottled water filling lines across Greater Cairo's automated high-speed corridors, where resealability and capping equipment compatibility drive standardization.
- Dispensing Caps:Viscosity-controlled dosing mechanisms incorporating silicone valves, flip-top actuators, or pump integrations. Personal care and pharmaceutical segments in Alexandria and Damietta absorb these configurations fastest, precision delivery requirements commanding margin premiums through technical differentiation.
- Standard Caps:Basic unlined or foam-lined closures for non-critical sealing applications. Regional dairy brands in Alexandria source these for seasonal product rotations requiring rapid tool turnaround.
- Snap-on Caps:Single-use press-fit closures without threading mechanisms. Edible oil and household chemical producers in Upper Egypt governorates utilize these for cost-sensitive volume applications.
Screw caps command the established base. The steepest expansion runs through dispensing caps.
Material:
Cost tier stratification separates certified food-contact grades absorbing EOS compliance premiums from commodity resins serving price-sensitive regional markets.
- Polypropylene:Semi-crystalline thermoplastic with superior fatigue resistance and chemical inertness. Pharmaceutical and household chemical applications across Greater Cairo dominate procurement, repeated opening cycles and aggressive formulation compatibility requirements favoring homopolymer and random copolymer grades.
- Polyethylene:Lower-density polyolefin offering flexibility and impact resistance. Dairy and edible oil segments in Sohag and Qena governorates drive uptake, moisture barrier properties and induction-seal compatibility supporting regional distribution needs.
- PET:Polyester resin limited to specialty applications requiring transparency or barrier performance. Niche pharmaceutical blister packaging and premium cosmetic presentations utilize these grades.
- PVC:Chlorinated polymer restricted by EOS migration limits for food-contact applications. Industrial chemical and non-consumable sectors retain limited demand.
Polypropylene holds the volume anchor. Polyethylene is climbing the fastest on Upper Egypt penetration.
Application:
Customer type fragmentation separates consolidated national bottlers demanding embedded technical service from fragmented regional players prioritizing mold flexibility and color-matching responsiveness.
- Beverages:Carbonated soft drinks, bottled water, and juice segments requiring tamper-evident banding and high-speed capping compatibility. National distributors centralizing procurement through technical partnerships dominate this vertical.
- Pharmaceuticals:Moisture-sensitive drug packaging with customized induction-seal formulations and child-resistant mechanisms. This segment absorbs compliance costs through dedicated production line segregation and dual laboratory certifications.
- Personal Care:Shampoo, lotion, and cosmetic containers demanding viscosity-matched dispensing precision. Surviving mid-scale cosmetic manufacturers pay premiums for rapid Pantone-matched production runs.
- Household Chemicals:Bleach, detergent, and surface cleaner closures requiring chemical resistance and safety venting. Polypropylene fatigue resistance supports repeated opening cycles in this segment.
Beverages command the established base. Pharmaceuticals is gaining share fastest on liner specialization.
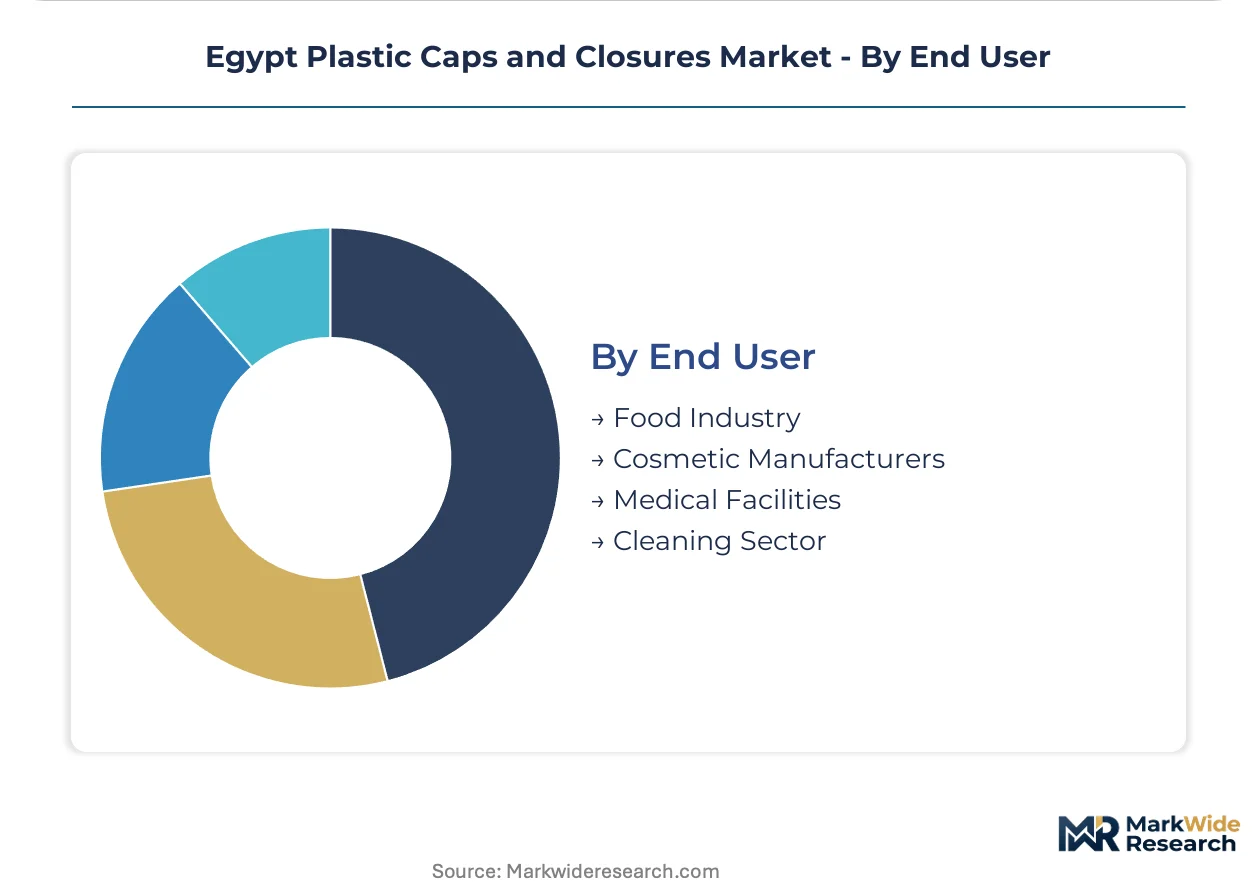
End User:
Supply concentration aligns converter qualification protocols with end-user audit intensity, food and pharmaceutical sectors imposing overlapping EOS quality and Environmental Affairs Agency documentation burdens.
- Food Industry:Processed dairy, edible oil, and condiment producers requiring EOS-certified food-contact materials. Modernization across this sector compresses procurement cycles for tamper-evident closures.
- Medical Facilities:Hospital and clinic supply chains for sterile pharmaceutical packaging. Induction-seal integrity and migration limit compliance dominate resin selection.
- Cosmetic Manufacturers:Mid-scale surviving players in Alexandria and Cairo corridors. Color-matching service tiers differentiate converter offerings as small-batch competitors collapse.
- Cleaning Sector:Industrial and consumer chemical formulators. Chemical resistance and venting specifications drive polypropylene grade selection.
Food industry commands the established base. Medical facilities show the steepest expansion trajectory on compliance-driven segmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's plastic caps and closures sector feeds Gulf and North African distribution networks through Alexandria's port infrastructure, while domestic demand concentrates in Greater Cairo's beverage bottling corridor.
Greater Cairo
Carbonated soft drink and bottled water bottlers in 6th of October City and 10th of Ramadan industrial zones drive procurement volumes for tamper-evident screw caps. The Egyptian Organization for Standardization and Quality enforces tightened food-contact material rules that push converters toward certified polypropylene grades. High-speed filling lines across this corridor standardize formats compatible with automated capping equipment.
Alexandria and Delta Region
Export-oriented molding facilities cluster around Alexandria's port to serve North African and Levantine markets with specialty dispensing configurations. The Environmental Affairs Agency advances extended-producer-responsibility frameworks affecting post-consumer collection targets for converters operating coastal facilities. Dairy brands in Damietta source rapid-tool-turnaround standard caps for seasonal product rotations.
Upper Egypt
Sohag and Qena governorates rely on imported closures for edible oil and dairy distribution, creating white space for domestic capacity expansion. Regional processors absorb higher logistics costs from Cairo-based suppliers due to limited local molding infrastructure. Induction-seal compatible polyethylene caps penetrate these markets through price-sensitive procurement channels.
Suez Canal Zone
Free zone incentives attract foreign converters seeking re-export access to Gulf Cooperation Council markets without customs duty exposure. The Ministry of Trade and Industry qualifies zone operators for export-oriented EOS certifications streamlined for pharmaceutical and food-contact applications. Logistics parks near Port Said handle resin imports for redistribution to Nile Delta processing clusters.
Egypt Plastic Caps and Closures Market Competitive Landscape
Player mix skews toward multinational technical-service specialists and domestic mold-fabrication shops serving fragmented regional dairy brands. Market structure divides into three functional tiers: embedded-service providers anchoring national bottler accounts, rapid-response specialists capturing seasonal redesign cycles, and import-dependent distributors filling Upper Egypt supply gaps. Competitive moves center on technical-staff placement at client filling lines and multi-cavity mold capacity expansion in Greater Cairo industrial zones.
Among multinational-anchored specialists, Bericap Egypt and Aptar Group exemplify the embedded-service archetype through captive technical teams stationed at high-volume beverage operations. NatPack and El Safa Plast Mold and Plastic Factory occupy the domestic responsiveness tier, with the former representing customized formulation capabilities for pharmaceutical compliance and the latter anchoring rapid tool-turnaround services for Alexandria-based dairy brands needing seasonal cap redesigns. Delta Egypt Plastic sits within the regional distribution-focused segment.
| Leading Market Players |
|---|
| Amcor Plc |
| Tetra Pak International S.A. |
| Bericap Egypt |
| NatPack |
| El Safa Plast Mold and Plastic Factory |
| Delta Egypt Plastic |
| Aptar Group |
| Delpack SA |
| Alpla |
| Others |
Pricing and Supply Chain Analysis
High-cavity mold utilization rates above 80% in Greater Cairo's industrial corridor create asymmetric scale advantages that compress price floors for commodity screw caps while elevating premiums for specialized dispensing configurations. This scale polarization concentrates procurement leverage among national beverage bottlers and fragments margin capture for regional dairy brands lacking volume commitments.
Pricing Analysis
Compression-molding technology generation gaps separate pricing tiers: legacy injection-molded caps from prior-generation equipment trade at commodity levels, current-generation short-shot compression commands mid-tier premiums, and next-generation lightweight thinned-wall formats capture peak margins. Pricing stratifies across premium, standard, and economy tiers driven by EOS certification grade and embedded technical-service bundling. Cost compression in the standard tier is intensifying because resin price volatility squeezes converters on fixed-price annual contracts. National beverage bottlers show lowest price sensitivity due to consolidated procurement volumes, while Upper Egypt edible oil processors remain most price-sensitive given logistics cost absorption from Cairo-based suppliers.
Supply Chain Analysis
Saudi Arabia and the United Arab Emirates anchor polypropylene resin supply through petrochemical complexes serving Egyptian converters via Red Sea shipping lanes. Local production draws from naphtha-derived propylene monomer, color masterbatch formulations, and multi-cavity mold tooling. Single-source vulnerability concentrates in mold fabrication capacity clustering in limited industrial zones. Distribution runs through national distributors centralizing procurement for carbonated soft drink bottlers, with secondary channels serving fragmented regional dairy brands through import-dependent distributors in Upper Egypt governorates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's plastic caps and closures market represents an early-cycle expansion story as food processing modernization accelerates tamper-evidence adoption across national beverage bottlers and pharmaceutical compliance investments deepen. This penetration tailwind creates asymmetric opportunity windows before supply-side consolidation hardens competitive barriers.
For Market Incumbents: Compound technical-service differentiation by embedding captive engineering teams at high-volume beverage filling lines and securing exclusive mold investment allocation through annual volume commitments. Defend against emerging rapid-response specialists by accelerating multi-cavity compression capacity expansion in 6th of October City industrial parks. Certification investment in dual EOS and Environmental Affairs Agency compliance documentation creates switching-cost barriers against import-dependent competitors. For New Entrants and Emerging Players: Pharmaceutical liner formulation under-service by beverage-dominant incumbents creates white-space opportunity for specialized induction-seal capabilities targeting moisture-sensitive drug packaging. Upper Egypt's import-dependent edible oil and dairy segments in Sohag and Qena governorates offer the most penetrable geography given limited domestic molding infrastructure. A go-to-market angle anchored in rapid Pantone-matched production runs for surviving mid-scale cosmetic manufacturers commands margin premiums through color-matching responsiveness. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with installed short-shot compression capacity and established EOS dual-certification laboratory infrastructure. Long-term viability over the next decade rests on compliance-driven segmentation deepening as extended producer responsibility frameworks mature. Acquisition targets should display embedded technical-service contracts with national bottlers and mold fabrication capabilities in Greater Cairo industrial zones. The signal to watch is Environmental Affairs Agency packaging-waste regulation enforcement timing, which would redistribute compliance costs and reshape converter margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Cavity Compression Capacity Expansion | Short-shot molding investments in 6th of October City industrial parks capture lightweighting premiums from beverage bottlers. |
| Dual Certification Laboratory Investment | EOS and Environmental Affairs Agency compliance documentation creates switching-cost barriers against import-dependent distributors. |
| Embedded Technical-Service Team Deployment | Captive engineering staff stationed at client filling lines anchor procurement consolidation toward single-source partnerships. |
| Pharmaceutical Liner Specialization | Customized induction-seal formulations for moisture-sensitive drug packaging penetrate underdeveloped compliance-driven segments. |
| Upper Egypt Distribution Infrastructure | Regional molding capacity in Sohag and Qena governorates displaces import-dependent supply chains for edible oil processors. |
Research Methodology
A standing panel of plant managers at PET preform and cap molding facilities, procurement leads at national beverage bottlers, technical R&D directors at resin distributors, and Environmental Affairs Agency compliance officers provided ongoing calibration across primary fieldwork. Secondary validation drew from Egyptian Organization for Standardization and Quality certification databases, Ministry of Trade and Industry customs records, SEC filings of multinational packaging parents, and industrial zone authority capacity registries. Bottom-up segment sizing triangulated against top-down value-chain estimates across product type, material grade, and application verticals.
Consistency checks validated volume and value outputs against external benchmarks including regional polyolefin consumption patterns and beverage industry packaging intensity ratios. The analytical framework modeled segmentation across product configuration, resin certification tier, end-use automation requirement, and geographic procurement cluster throughout the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating beverage sector automation trajectories and pharmaceutical compliance cost absorption rates. Industry-specific forecast inputs included mold cavity count expansion schedules and EOS harmonization timelines with Codex Alimentarius migration limits.
Forecasts assume regulatory continuity in Egyptian Organization for Standardization and Quality food-contact material rules and Environmental Affairs Agency extended producer responsibility frameworks; material policy shifts would require re-modeling resin grade qualification protocols and post-consumer collection target compliance costs. Specific risks that could revise projections include polypropylene feedstock price volatility exceeding historical bands, mold fabrication capacity constraints extending seasonal redesign lead times, and upstream sorting infrastructure gaps limiting recyclability claim verification. Recalibration cycles align with material shifts in packaging-waste regulation enforcement and beverage bottler procurement centralization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Metal Closures Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Reverse Cap Bottles Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Dispensing Caps Market
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Latin America Metal Caps and Closures Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Spouted Dispensing Closures Market