
 Asia Pacific Metal Caps and Closures Market | 2026-2036
Asia Pacific Metal Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Metal Caps and Closures Market Insights
Buyer concentration among Asia Pacific beverage bottlers is shifting as multinational soft-drink and brewing conglomerates consolidate supplier lists while regional craft producers fragment procurement channels. Crown Holdings, Inc. leverages integrated aluminum supply chains to anchor volume contracts with mega-brewers across China and Vietnam. Nippon Closures Co., Ltd. sustains precision-engineering leadership in high-torque screw-cap designs for carbonated drinks. UA Packaging competes on cost-optimized tinplate solutions for mass-market edible oil and sauce segments in India and Indonesia.
Asia Pacific metal caps and closures are threaded or crimped sealing devices fabricated from aluminum, tinplate, or stainless steel, typically specified to 0.15–0.40 mm gauge with internal lacquer coatings and elastomeric liners to prevent gas exchange and corrosion. These components function as barrier systems preserving carbonation, aroma, and shelf stability across liquid consumer goods. Screw caps dominate volume due to resealability and compatibility with automated capping lines in high-speed beverage plants, while roll-on caps retain share in wine and spirits where tamper-evident bands matter. Aluminum material grades are capturing margin pools as brands substitute tinplate for weight reduction and recycling-value claims in premium water and craft beer.
China's SAMR enforces GB standards for food-contact metal packaging, including migration limits and coating integrity tests that shape material selection across domestic suppliers. India's BIS mandates ISI certification for metal closures used in edible oils and processed foods, creating compliance barriers for uncertified imports. Japan's METI promotes JIS-aligned sustainability metrics that reward closures with higher recycled-content ratios. Stakeholders must monitor how divergent national certification timelines affect cross-border tooling investments and regional manufacturing footprint decisions.
Market Dynamics
Aluminum lightweighting mandates from beverage brands are compressing tinplate demand while forcing closure suppliers to retool extrusion and forming lines across China's eastern manufacturing corridor.
Growth Catalysts
- China's dual carbon goals:Carbon intensity reduction targets are accelerating aluminum substitution in beverage closures as brands seek recycling-value credentials.
- Southeast Asian bottling expansion:Vietnam and Thailand beverage plants are scaling automated capping line capacity, driving screw-cap volume procurement.
- BIS certification mandates:India's ISI mark requirements for edible oil closures are formalizing supply relationships with certified domestic metal-forming specialists.
Market Restraints
- Aluminum ingot price volatility:LME aluminum fluctuations compress margin buffers for closure converters locked into annual beverage supply contracts.
- China supply concentration:Eastern province smelter and rolling mill clusters create geographic vulnerability to regional power rationing or environmental shutdowns.
- Technical torque limitations:Ultra-lightweight aluminum gauges below 0.18 mm struggle to maintain seal integrity in high-pressure carbonated applications.
Strategic Opportunities
- Indonesia's underpenetrated edible oil segment:Palm oil processors in Sumatra and Java lack certified metal closure suppliers, opening slots for BIS-compliant entrants.
- Japan's JIS-aligned sustainability metrics:METI recycled-content scoring creates premium positioning for closures with verified post-consumer aluminum ratios.
- Direct-to-brewer digital procurement platforms:Regional craft beer brands in Australia are bypassing traditional distributor networks for specification-matched closure sourcing.
Industry Challenges
- Tooling reconfiguration timelines:GB standard updates from China's SAMR require 12-18 month validation cycles that delay new product launches.
- Lacquer formulation expertise gaps:Food-contact coating chemistry specialization is scarce across Vietnam and Philippines technical workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Metal Caps and Closures Market |
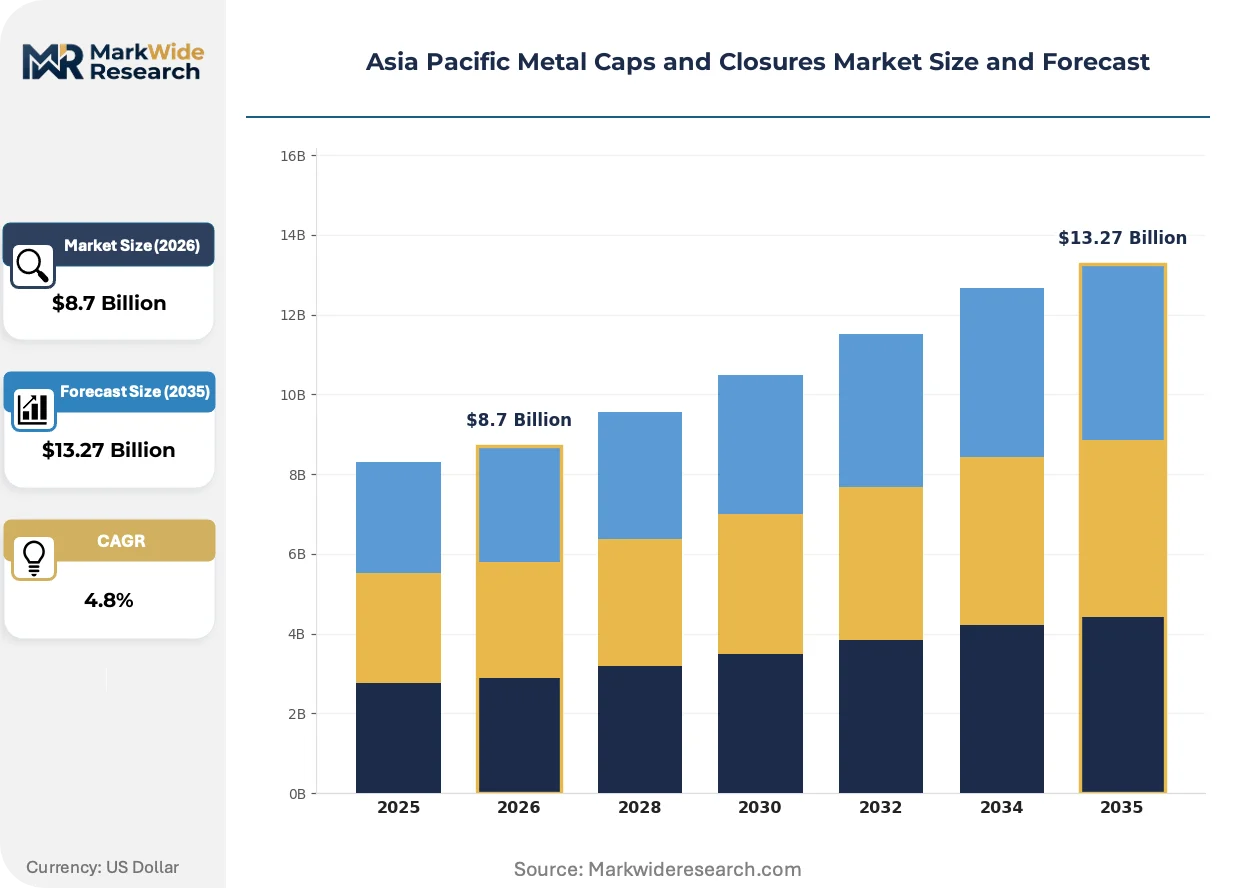
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Spouted Caps, Pull-Tab Caps, Roll-On Caps End User: Beverage, Pharmaceuticals, Personal Care, Food Material: Aluminum, Iron, Tinplate, Stainless Steel Application: Cosmetics, Chemicals, Liquids, Alcoholic Beverages |
| Companies Covered | Crown Holdings, Inc., UA Packaging, Alupac India, Nippon Closures Co., Ltd., ACTEGA, Closure Systems International Inc., Guala Closures Group, Hercules Sdn Bhd, Amcor Plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Metal Caps and Closures Market Trends and Innovations
Active coating technologies and liner material advances are redefining barrier performance expectations, while procurement digitization compresses specification-to-delivery cycles across Asia Pacific beverage supply chains.
Smart closure systems with embedded RFID tags are integrating traceability functions directly into aluminum roll-on caps, enabling brewers in Australia and Japan to authenticate supply chains and manage returnable bottle pools. Premium water brands in South Korea are piloting these tagged closures at scale. The technology is integrating inventory management with consumer engagement platforms, collapsing the traditional separation between packaging hardware and digital infrastructure.
China's SAMR is tightening GB 4806.9 migration limits for heavy metals in food-contact aluminum, forcing domestic coating suppliers to reformulate epoxy-phenolic lacquer systems ahead of 2025 enforcement windows. Closure manufacturers in Zhejiang and Guangdong provinces are accelerating third-party testing investments. The regulation is compressing uncertified competitors from export-oriented supply chains serving ASEAN beverage bottlers.
Consolidated procurement by multinational brewing conglomerates is fragmenting supplier tiers, with mega-contracts concentrating at integrated aluminum specialists while craft producers disaggregate orders across regional metal-forming job shops. Vietnam's emerging craft beer segment exemplifies this bifurcation. The pattern is rotating volume leverage toward buyers with specification standardization capabilities and away from undifferentiated converters.
Asia Pacific Metal Caps and Closures Market Segmentation
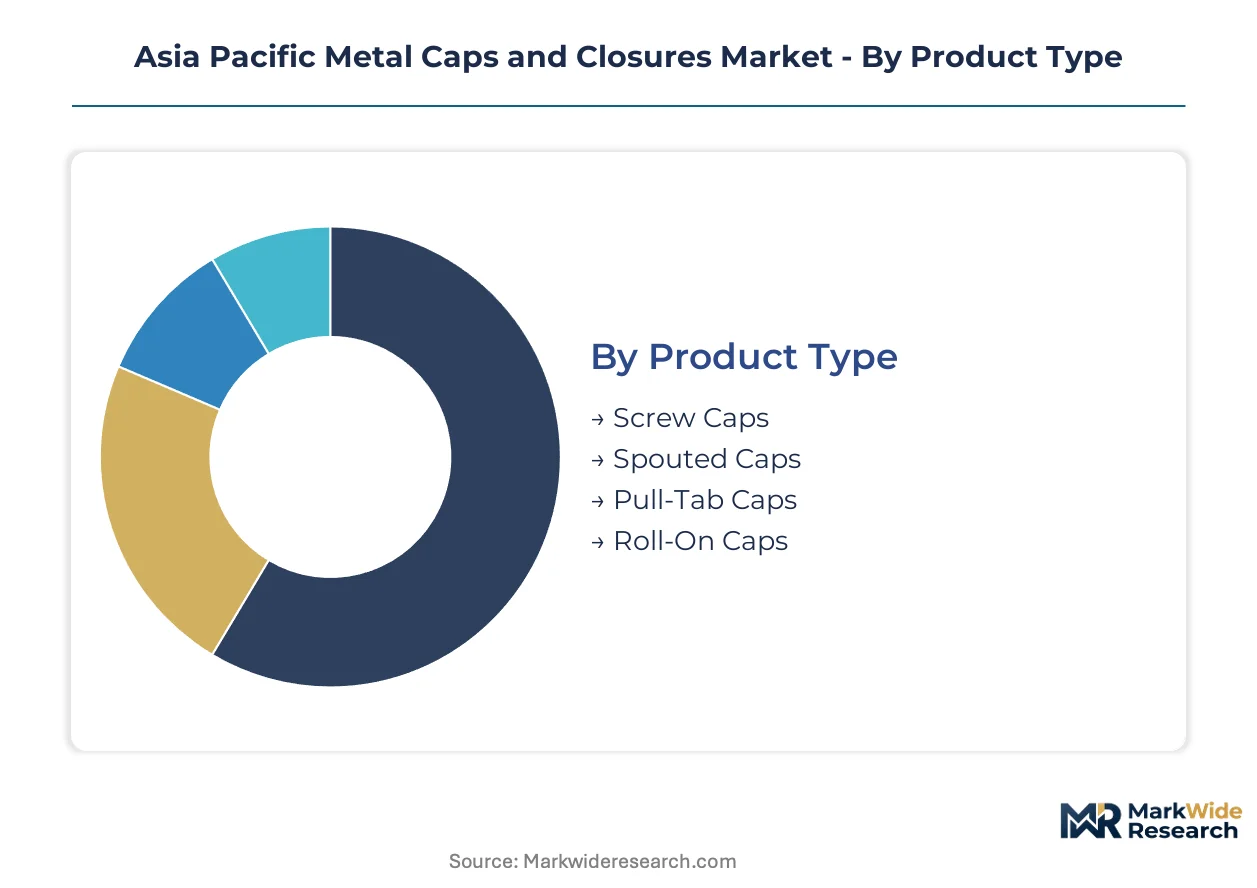
Segmentation in the Asia Pacific metal caps and closures market reveals how specification requirements diverge across beverage carbonation pressures, pharmaceutical sterility standards, and regional regulatory compliance tiers. Buyers select closure architectures based on torque performance, migration limits, and line-speed compatibility rather than commodity pricing alone.
Product Type:
Application torque and resealability requirements separate high-volume beverage bottlers from specialty pharmaceutical and cosmetic packagers across the region.
- Screw Caps:Threaded aluminum designs with elastomeric liners dominate carbonated soft-drink and beer applications. China's eastern manufacturing corridor ships these in billions to automated capping lines serving Tsingtao, Carlsberg China, and regional cola bottlers. The 26mm PCO standard anchors procurement specifications.
- Roll-On Caps:Aluminum shells formed around bottle necks deliver tamper-evident security for wine and spirits. Australia's Treasury Wine Estates and Japan's Suntory specify these for premium positioning and returnable bottle pool management. Pilfer-proof bands satisfy METI traceability guidelines.
- Spouted Caps:Flip-top mechanisms with directional flow control suit edible oil and sauce dispensing in India and Indonesia. FSSAI-compliant designs with venting channels prevent glug and spill.
- Pull-Tab Caps:Integrated ring-tab openings serve single-serve beverage cans and convenience-oriented food tins. Southeast Asian canneries specify these for palm juice and ready-to-drink coffee formats.
Volume sits with screw caps; growth tilts toward roll-on caps.
End User:
Regulatory stringency and procurement scale create distinct buyer tiers with diverging specification complexity and contract duration patterns.
- Beverage:Carbonated and still drink bottlers drive aluminum closure demand through lightweighting mandates and recycling-value claims. Vietnam's Heineken brewery and Thailand's Singha procurement teams specify sub-0.20mm gauges with GB 4806.9-compliant coatings.
- Food:Edible oil processors in Indonesia and sauce manufacturers in India require BIS-certified tinplate closures with oxygen barrier liners. Palm oil supply chains in Sumatra and Java represent underpenetrated procurement channels.
- Pharmaceuticals:Child-resistant and senior-friendly closure standards from CDSCO and TGA shape aluminum and polypropylene composite specifications. Sterility validation extends tooling qualification timelines.
- Personal Care:Cosmetic serum and toner brands in South Korea specify precision-dispensing pumps and screw caps with metallized finishes. Premium positioning drives small-batch procurement fragmentation.
Beverage commands procurement volume; pharmaceutical specifications are climbing fastest.
Material:
Density, recyclability credentials, and coating compatibility determine material selection across price-sensitive and premium positioning strategies.
- Aluminum:1050 and 3104 alloy grades enable 0.15-0.25mm gauges with full recyclability claims. China's dual carbon goals accelerate substitution for tinplate in water and beer closures. Zhejiang and Guangdong rolling mills supply regional converters.
- Tinplate:Electrolytic tin-coated steel retains cost advantage for edible oil and processed food segments in India and Indonesia. BIS ISI certification requirements favor domestic sourcing from Jamshedpur and Pune metal-forming clusters.
- Stainless Steel:304-grade closures serve high-end spirits and pharmaceutical applications requiring corrosion resistance and repeated sterilization cycles.
- Iron:Uncoated and lacquered iron closures occupy economy tiers for industrial chemical and agricultural packaging with limited shelf-life requirements.
Aluminum holds volume leadership; stainless steel specifications are expanding most quickly.
Application:
Pressure differential, chemical compatibility, and consumer interface requirements shape closure architecture selection across liquid product categories.
- Alcoholic Beverages:Crown corks and roll-on caps manage carbonation retention in beer and tamper evidence in spirits. Australia's craft brewers and Japan's sake distillers specify distinct torque and liner profiles.
- Liquids:Broad category spanning water, juice, and functional beverages where screw caps with oxygen scavenging liners extend shelf stability. South Korean premium water brands pilot RFID-embedded smart closures.
- Cosmetics:Airless pump systems and precision-dosing closures protect active ingredients in serum and essence formulations. Seoul-based beauty brands drive metallized and soft-touch surface specifications.
- Chemicals:Venting and child-resistant closures for agrochemical and industrial solvent containers. UN-certified designs for hazardous material transport dominate procurement criteria.
Alcoholic beverages anchor procurement volume; cosmetics applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates along China's eastern manufacturing corridor, where integrated can-and-closure clusters serve domestic brewers and soft-drink brands. India's edible oil processors and Southeast Asia's bottling expansion create secondary demand poles with distinct procurement specifications.
China
Tsingtao and Carlsberg China drive aluminum closure procurement through automated capping line expansions in Shandong and Guangdong provinces. SAMR's GB 4806.9 migration limits for heavy metals are forcing coating reformulations ahead of enforcement windows. Zhejiang and Guangdong rolling mills supply regional converters with 1050 and 3104 alloy grades.
India
Edible oil processors in Maharashtra and Gujarat require BIS ISI-certified tinplate closures for palm oil and mustard oil packaging. FSSAI compliance mandates are formalizing supply relationships with certified domestic metal-forming specialists. Jamshedpur and Pune clusters dominate tinplate sourcing for mass-market sauce and oil segments.
Japan
Suntory and Treasury Wine Estates specify roll-on caps with tamper-evident bands for premium spirits and wine positioning. METI's JIS-aligned sustainability metrics reward closures with verified post-consumer aluminum ratios. Kanto region precision-engineering specialists maintain leadership in high-torque screw-cap designs for carbonated drinks.
Vietnam
Heineken's brewery expansion and emerging craft beer producers fragment procurement between mega-contracts and small-batch orders. Automated capping line capacity scaling drives screw-cap volume procurement from regional suppliers. Ho Chi Minh City and Hanoi bottling corridors concentrate demand for sub-0.20mm aluminum gauges.
Australia
Craft brewers in Victoria and New South Wales pilot RFID-embedded smart closures for supply chain authentication and returnable bottle pool management. TGA pharmaceutical standards shape child-resistant closure specifications for over-the-counter packaging. Direct-to-brewer digital procurement platforms are bypassing traditional distributor networks.
Asia Pacific Metal Caps and Closures Market Competitive Landscape
Chinese producers anchor the volume tier; Japanese and Indian specialists hold premium and cost-optimized niches respectively. The vendor base separates into integrated aluminum converters, precision-engineering houses, and regional tinplate job shops. Three archetypes dominate: mega-scale beverage contractors, certification-compliant domestic formers, and technology-differentiated precision specialists. Competitive moves concentrate on backward integration into aluminum rolling and strategic partnerships with coating chemistry suppliers.
Among integrated aluminum specialists, Crown Holdings, Inc. and Nippon Closures Co., Ltd. occupy positions at opposite ends of the scale-precision spectrum. UA Packaging exemplifies the cost-optimized tinplate tier serving India's edible oil and sauce segments. These three anchors represent how geographic specialization and material focus stratify competitive positioning across the region's divergent regulatory and demand environments.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| UA Packaging |
| Alupac India |
| Nippon Closures Co., Ltd. |
| ACTEGA |
| Closure Systems International Inc. |
| Guala Closures Group |
| Hercules Sdn Bhd |
| Amcor Plc |
| Others |
Pricing and Supply Chain Analysis
Backward integration into aluminum rolling capacity anchors supply positioning and pricing power for beverage closure converters across China's eastern manufacturing corridor. Crown Holdings and Nippon Closures leverage captive 1050 and 3104 alloy supply to defend margin pools against spot-market volatility while regional tinplate job shops absorb cost compression from LME fluctuations.
Pricing Analysis
Volume concentrates in mega-contracts with multinational brewers while margin pools accrue to precision-engineered roll-on caps for premium spirits. Price differentiation rests on GB 4806.9 coating certification tiers and recycled-content verification under METI guidelines. Cost compression in standard screw-cap tiers is intensifying because aluminum ingot volatility compresses converter margins locked into annual beverage supply agreements. Mass-market edible oil processors in India exhibit highest price sensitivity; Japanese premium water brands demonstrate lowest sensitivity due to sustainability credential requirements.
Supply Chain Analysis
Regional distribution centers in Zhejiang and Guangdong provinces feed hub-and-spoke patterns serving ASEAN beverage bottlers. Raw material dependencies center on LME aluminum ingots, electrolytic tinplate from Jamshedpur and Pune clusters, and epoxy-phenolic lacquer formulations. Single-source vulnerability concentrates in eastern province smelter clusters exposed to environmental shutdown mandates. Distribution runs through integrated can-and-closure manufacturing corridors with direct line-feed arrangements to high-speed capping operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over aluminum rolling and coating chemistry supply determines competitive viability. Players pursuing upstream capture of 1050 and 3104 alloy production secure margin defense against raw material volatility.
For Market Incumbents: Anchor volume contracts through specification standardization capabilities that lock mega-brewers into multi-year aluminum closure supply agreements. Defend against emerging precision-engineering houses by accelerating third-party GB 4806.9 testing investments ahead of SAMR enforcement windows. Prioritize backward integration into Zhejiang and Guangdong rolling mill capacity to neutralize LME price volatility exposure. For New Entrants and Emerging Players: BIS ISI certification requirements in India open a window for certified domestic metal-forming specialists to capture palm oil processor contracts in Sumatra and Java. Target Indonesia's underpenetrated edible oil segment with tinplate solutions compliant with FSSAI migration limits. Establish go-to-market presence through direct technical service partnerships with regional sauce manufacturers bypassing traditional distributor markups. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of precision-engineering houses with METI-aligned sustainability verification capabilities and high-torque screw-cap IP. Long-term viability favors converters with verified post-consumer aluminum ratios and coating chemistry partnerships. Watch for inflection in China's dual carbon goal acceleration timelines as signal for aluminum substitution velocity against tinplate.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | Captive 1050 and 3104 alloy supply from Zhejiang mills neutralizes LME volatility exposure for beverage contracts. |
| GB 4806.9 Coating Certification Investment | Third-party testing acceleration ahead of SAMR enforcement compresses uncertified competitors from export supply chains. |
| Direct-to-Brewer Digital Procurement Platform | Australian craft beer pilot programs collapse specification-to-delivery cycles bypassing traditional distributor networks. |
| RFID-Embedded Smart Closure Development | South Korean premium water brand pilots integrate inventory management with consumer engagement infrastructure. |
| BIS ISI Certification Acquisition | Formalized supply relationships with Maharashtra and Gujarat edible oil processors create defensive moat against imports. |
Research Methodology
Independent corroboration across beverage procurement directors, aluminum rolling mill operations managers, and coating chemistry formulators underwrites the qualitative findings. Primary interviews with FSSAI compliance officers, METI sustainability program administrators, and SAMR regulatory affairs specialists combined with secondary validation from customs records, SEC 10-K filings of listed packaging converters, and BIS certification databases. Bottom-up demand modeling across beverage, food, pharmaceutical, and personal care end-uses triangulates against top-down aluminum and tinplate consumption data.
Comparable-period anchoring to historical beverage production volumes and closure-to-container ratios establishes the forecast baseline across the projection horizon. Segmentation dimensions span product architecture, material grade tier, end-use regulatory stringency, and regional manufacturing cluster concentration. CAGRs derive from aluminum substitution elasticity models against tinplate cost curves, with specific inputs including China's dual carbon policy implementation velocity and Southeast Asian bottling capacity expansion pipelines.
The model assumes a particular technology adoption path; alternative pathways for RFID-embedded smart closures or active coating barrier technologies would alter the outlook. Forecasts reflect documented assumptions regarding SAMR enforcement timing and BIS certification penetration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Cover Caps Market
Caps and Closures
India Plastic Caps and Closures Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
Flapper Caps Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Cap Seals Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Heat Shrink Bands Market
Caps and Closures
Drop Sealers Market
Caps and Closures
Brush Caps Market
Caps and Closures
Screw Caps and Closure Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Molded Fiber Pulp Cap Market
Caps and Closures
Fez Caps Market