
 Russia Plastic Caps and Closures Market | 2026-2036
Russia Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Plastic Caps and Closures Market Insights
The capital-intensity divergence between automated high-cavitation molders and labor-dependent regional suppliers is unwinding competitive stability across the Russia plastic caps and closures market. Berry Global Inc. leverages its multinational tooling networks to sustain consistent output of pharmaceutical-grade closures for Russian drug packers. Safe Cap anchors its position through specialized child-resistant and tamper-evident designs that dominate domestic pharmaceutical bottling lines.
Plastic caps and closures are threaded or snap-fit sealing devices manufactured through injection or compression molding from thermoplastic resins, designed to preserve product integrity, enable controlled dispensing, and comply with child-safety standards. Polypropylene dominates material selection for hot-fill beverage and dairy applications due to its thermal stability and chemical resistance, while bioplastics remain nascent but attract pilot interest from personal care brands seeking EAEU-aligned sustainability positioning. Screw caps command the largest volume share across beverage packaging, whereas dispensing caps capture expanding demand from cosmetic containers and household cleaning segments where precision dosing reduces waste.
Russia's Federal Service for Surveillance in Consumer Rights Protection (Rospotrebnadzor) enforces TR TS 005/2011 packaging safety rules, while the Eurasian Economic Commission harmonizes EAEU technical regulations that govern plastic migration limits and recyclability labeling across member states. The country's national standards body, Rosstandart, maintains GOST R certification pathways that overlap with EAEU conformity requirements, creating dual compliance obligations for converters serving both domestic and cross-border customers. Stakeholders must monitor pending amendments to extended producer responsibility frameworks and the pace of domestic rPET and recycled polypropylene infrastructure buildout to anticipate raw material qualification shifts.
Market Dynamics
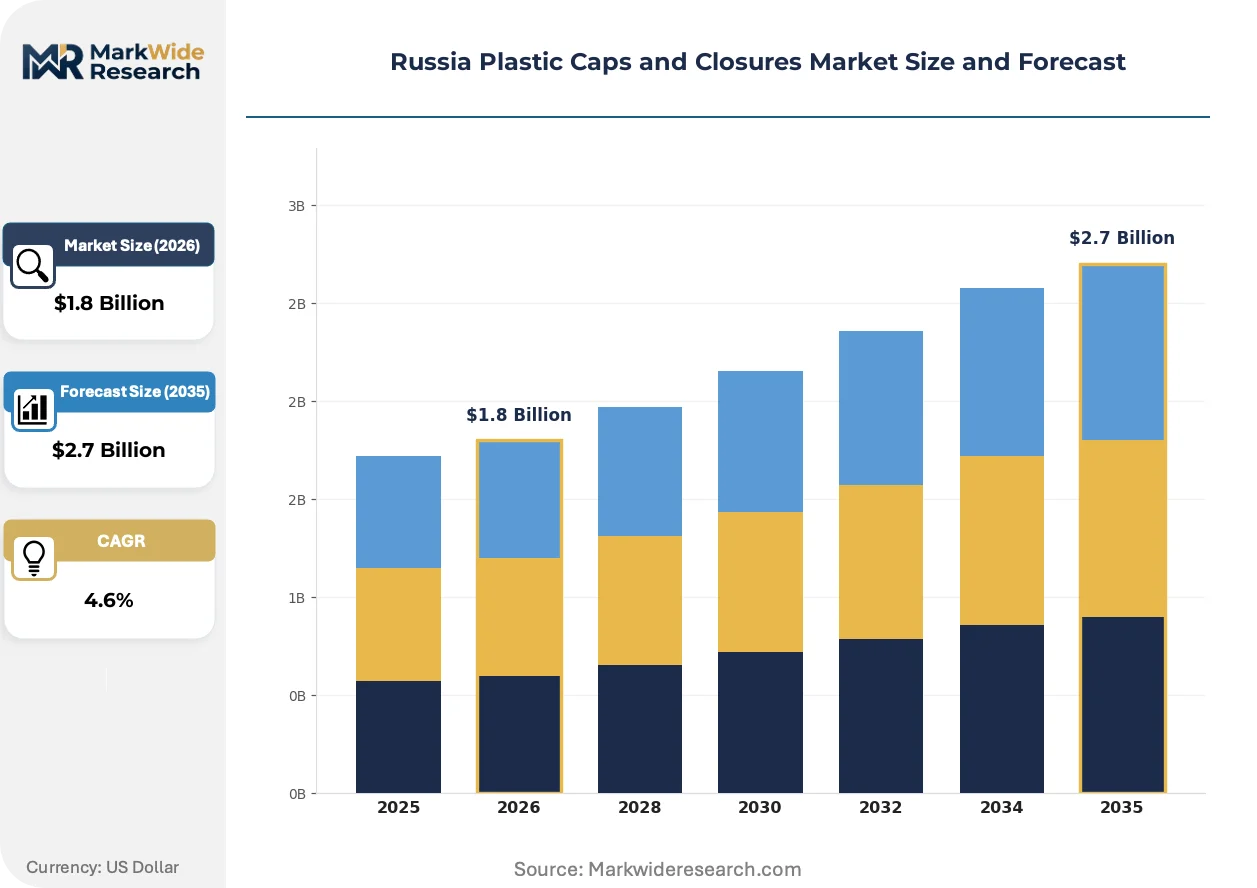
Russia's plastic caps and closures market is undergoing structural recalibration as EAEU migration-limit enforcement tightens material qualification pathways, forcing converters to abandon legacy polyethylene grades in favor of certified polypropylene and compliant resin alternatives.
Growth Catalysts
- TR TS 005/2011 Enforcement:Russia's packaging safety technical regulation mandates stricter substance migration controls, compelling beverage processors to upgrade closure specifications and expand procurement of certified materials.
- Pharmaceutical Bottling Expansion:Moscow-based drug packers are scaling child-resistant closure volumes to meet domestic pharmaceutical output targets and export-readiness requirements for EAEU markets.
- Hot-Fill Compatibility:Polypropylene thermal stability is unlocking dairy and juice processor demand for steam-sterilizable closures that withstand pasteurization without deformation or seal compromise.
Market Restraints
- Feedstock Price Volatility:Naphtha-derived polypropylene resin costs fluctuate with regional refinery output schedules, compressing converter margins and destabilizing annual contract pricing.
- Molding Equipment Concentration:High-cavitation injection systems depend on German and Austrian tooling suppliers, exposing Russian molders to extended lead times and currency-driven capex inflation.
- Recyclate Infrastructure Gap:Limited domestic rPET and recycled polypropylene purification capacity restricts closed-loop material sourcing for EAEU recyclability-label-compliant closures.
Strategic Opportunities
- North Caucasus Processing Hubs:Underdeveloped converter presence in southern federal districts offers first-mover positioning for molders serving emerging mineral water bottlers near Stavropol and Krasnodar.
- Bioplastic Pilot Positioning:Personal care brands are testing polylactic acid closures for premium cosmetic lines, creating early-adoption partnerships ahead of EAEU sustainability framework formalization.
- Dispensing Cap Diversification:Household cleaning and agrochemical packers seek precision-dose closures that reduce over-application waste, opening technical collaboration channels with specialty molders.
Industry Challenges
- Dual Certification Complexity:Converters serving both domestic and cross-border customers must maintain parallel GOST R and EAEU conformity documentation, extending product approval timelines.
- Tooling Technician Scarcity:Advanced hot-runner system maintenance and multi-cavity mold optimization require specialized skills that regional labor markets struggle to supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Plastic Caps and Closures Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-On Caps, Dispensing Caps, Specialty Closures Material: Polypropylene, Polyethylene, PVC, Bioplastics End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Application: Beverage Packaging, Cosmetic Containers, Pharmaceutical Bottles, Household Cleaning |
| Companies Covered | Berry Global Inc., Safe Cap, Erecton LLC, PZPI LLC, Artpack Plastic, Continental Plast LLC, Polymir LLC, Plastmassa, Polymeric Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Plastic Caps and Closures Market Trends and Innovations
Active material substitution and regulatory alignment are compressing product development cycles across Russian closure manufacturing, with technical capabilities separating automated high-volume molders from labor-dependent regional competitors.
High-cavitation hot-runner molding is supplanting cold-runner systems in beverage closure production, eliminating runner waste and reducing cycle times. Moscow-area dairy processors are adopting these systems for 28mm neck finish standardization. The technology is compressing unit economics for mid-volume converters unable to amortize tooling investments.
Rospotrebnadzor is intensifying TR TS 005/2011 surveillance protocols, expanding laboratory testing of aromatic amine and heavy metal migration from colored masterbatch formulations. Pharmaceutical packers face the steepest compliance burden, reformulating closure pigments and accelerating supplier qualification audits. The Central Federal District is witnessing the fastest certification documentation turnover as converters consolidate testing partnerships.
Direct-procurement relationships between food processors and specialized molders are fragmenting traditional distributor channels. Large beverage bottlers in the Moscow region now specify cavity counts, resin grades, and tamper-evident band geometries in direct technical specifications. This pattern is most pronounced in dairy and mineral water segments where packers prioritize supply security over distributor inventory flexibility.
Russia Plastic Caps and Closures Market Segmentation
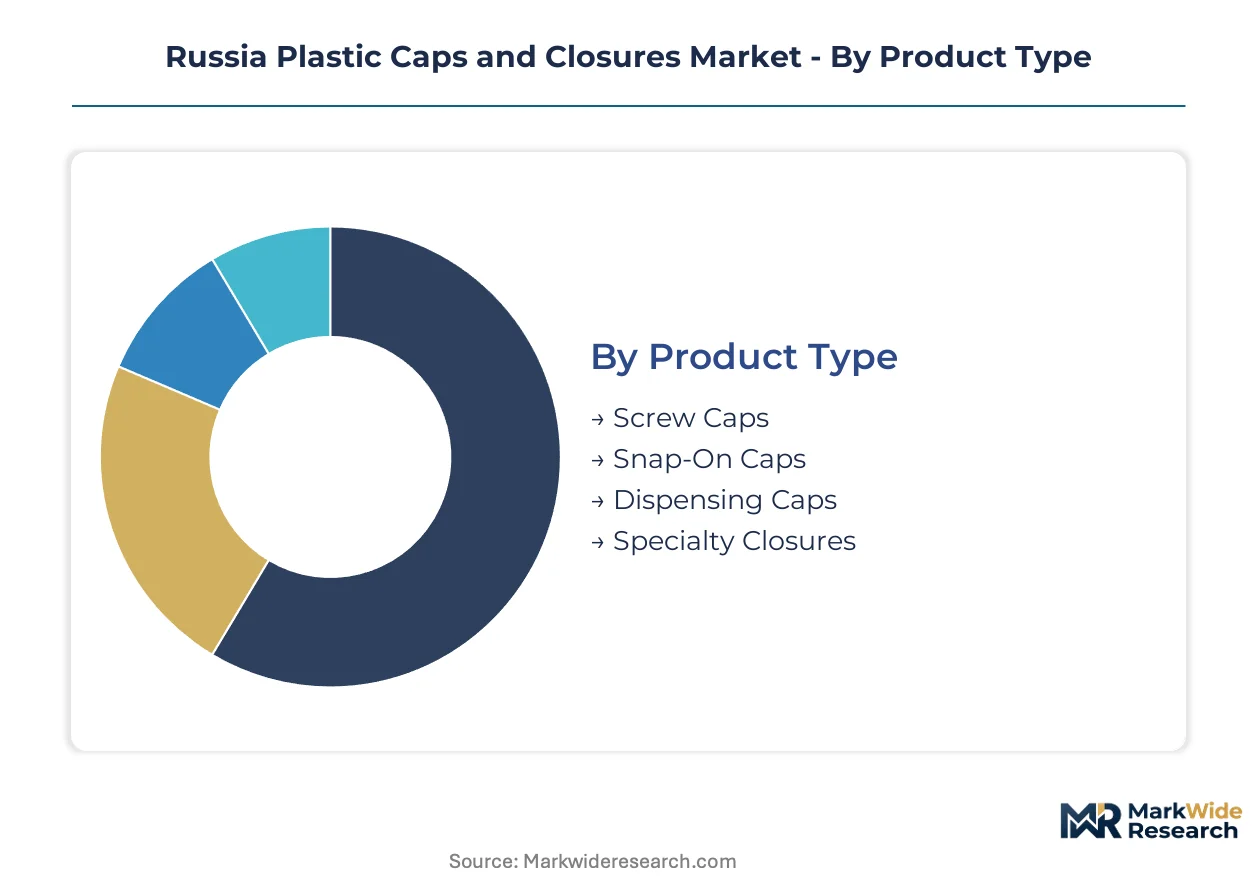
Segmentation reveals how EAEU regulatory pressure and procurement consolidation are reshaping competitive positioning across Russian closure manufacturing. Each dimension exposes different fault lines between certified high-volume molders and regional suppliers struggling with material qualification.
Product Type:
Screw caps dominate domestic beverage procurement, while dispensing variants draw export-led interest from EAEU cosmetic packers.
- Screw Caps:Threaded closures manufactured through high-cavitation injection molding, typically specified with 28mm neck finishes for standardization. Moscow-area dairy processors are consolidating procurement around steam-sterilizable polypropylene screw caps that withstand pasteurization cycles without thread deformation.
- Dispensing Caps:Pump and flip-top mechanisms enabling controlled product release, requiring precision-molded flow channels and gasket integration. Personal care brands in the Central Federal District are expanding dispensing cap specifications for premium cosmetic lines, prioritizing EAEU recyclability-label compliance.
- Snap-On Caps:Press-fit closures with integral tamper-evident rings, common in mineral water and juice segments.
- Specialty Closures:Child-resistant and tamper-evident designs for pharmaceutical compliance.
Screw caps hold the largest share; momentum sits with dispensing caps.
Material:
Cost tier separation is pronounced, with certified polypropylene commanding premium pricing against legacy polyethylene grades facing qualification failure.
- Polypropylene:Thermoplastic resin selected for hot-fill compatibility and chemical resistance, specified in homopolymer and random copolymer grades. Central Federal District converters are prioritizing polypropylene for dairy and pharmaceutical applications where TR TS 005/2011 migration limits disqualify lower-cost alternatives.
- Polyethylene:Linear low-density and high-density grades historically dominant in cold-fill beverage closures. Rospotrebnadzor enforcement of aromatic amine migration limits is forcing reformulation or abandonment of colored polyethylene masterbatches.
- Bioplastics:Polylactic acid and bio-based polypropylene variants attracting pilot interest.
- PVC:Declining specification in food contact due to plasticizer scrutiny.
Polypropylene captures the dominant volume position; bioplastics are climbing the fastest despite nascent infrastructure.
End User:
Application maturity varies sharply, with pharmaceutical packers demanding the most intensive certification documentation.
- Food & Beverage:Dairy processors and mineral water bottlers in Moscow and Tver oblasts driving standardization around 28mm neck finishes. Hot-fill compatibility requirements are filtering supplier bases toward polypropylene-specialized molders with validated sterilization protocols.
- Pharmaceuticals:Moscow-based drug packers scaling child-resistant closure procurement to meet domestic output targets and EAEU export requirements. Dual GOST R and EAEU conformity documentation extends approval timelines for converters serving this segment.
- Personal Care:Premium cosmetic brands testing bioplastic closures for sustainability positioning.
- Household Products:Agrochemical and cleaning packers seeking precision-dose closures.
Food & beverage maintains volume leadership; pharmaceuticals show the steepest expansion trajectory.
Application:
Supply concentration in the Central Federal District shapes procurement patterns, with direct processor-molder relationships displacing distributor channels.
- Beverage Packaging:Dairy and juice segments standardizing on 28mm neck finishes with tamper-evident bands. Direct technical specifications from large bottlers now dictate cavity counts, resin grades, and band geometries.
- Pharmaceutical Bottles:Child-resistant and senior-friendly designs requiring specialized tooling and validation protocols. Safe Cap and multinational suppliers dominate this technically demanding segment.
- Cosmetic Containers:Dispensing cap demand from premium personal care brands.
- Household Cleaning:Precision-dose closures reducing over-application waste.
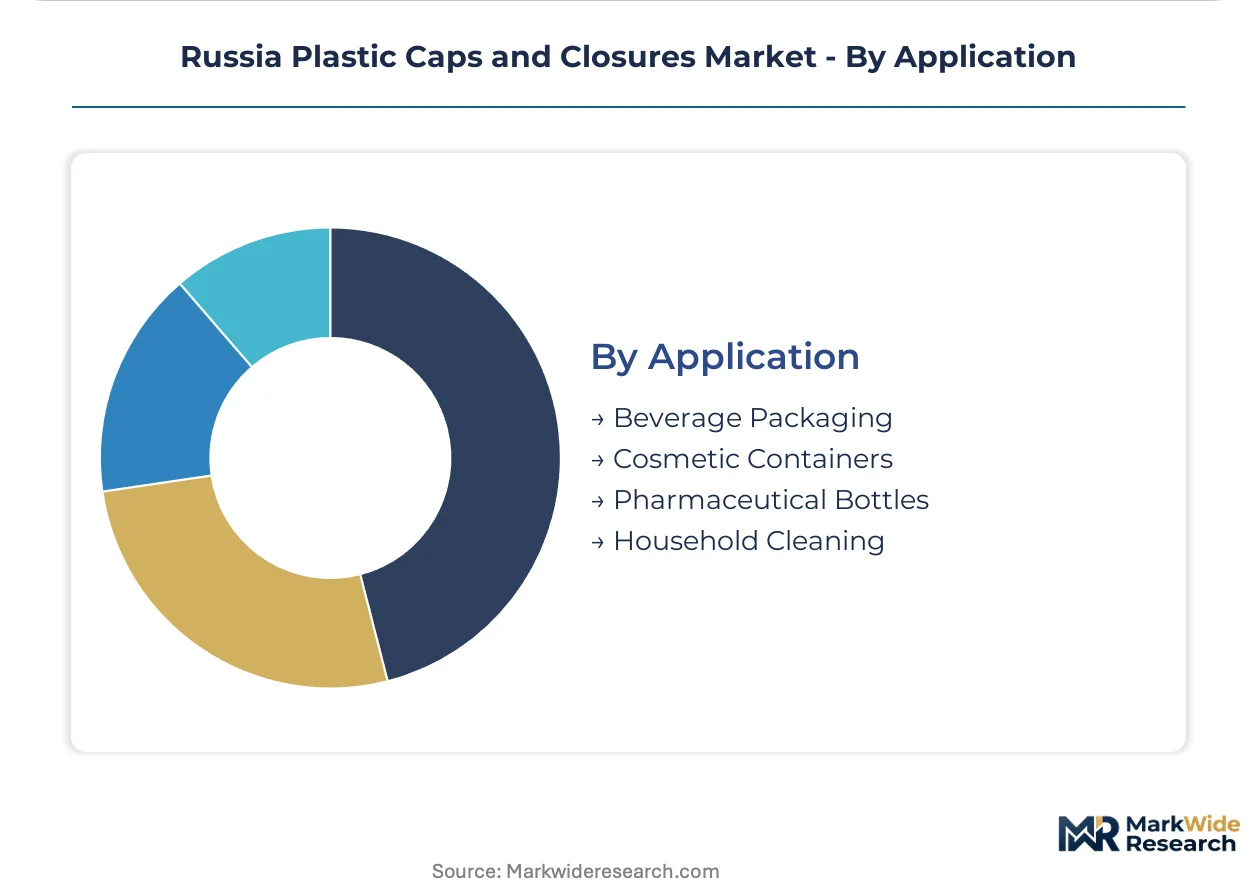
Beverage packaging holds the largest share; pharmaceutical bottles are gaining share fastest on regulatory compliance investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Central Federal District while southern federal districts operate on thinner margins. Moscow-based converters command premium rates for certified polypropylene closures. Regional molders in peripheral districts struggle with material qualification costs.
Central Federal District
Moscow-based dairy processors and pharmaceutical packers drive demand for steam-sterilizable screw caps and child-resistant closures. Rospotrebnadzor maintains its headquarters here, accelerating TR TS 005/2011 compliance documentation turnover. Tver and Moscow oblasts host the densest clustering of high-cavitation molding facilities serving beverage bottlers.
Northwestern Federal District
St. Petersburg's port infrastructure supports closure exporters targeting EAEU markets in Belarus and Kazakhstan. The district's food processors prioritize tamper-evident bands for dairy exports. Kaliningrad's special economic zone attracts molders seeking duty-advantaged resin imports for Baltic market access.
Volga Federal District
Mineral water bottlers in the Caucasus foothills source closures from Kazan and Samara converters. The region's petrochemical feedstock proximity reduces resin logistics costs for mid-volume molders. Nizhny Novgorod's industrial base sustains cold-runner systems for economy-tier beverage applications.
Southern Federal District
Stavropol and Krasnodar krai host emerging mineral water processors underserved by certified closure suppliers. The region's agricultural chemical packers seek precision-dose dispensing caps for fertilizer applications. Rostov-on-Don's converter presence remains thin, creating first-mover gaps for EAEU-compliant molders.
Ural Federal District
Yekaterinburg's machinery builders supply auxiliary equipment to regional molders lacking direct German tooling relationships. The district's pharmaceutical packaging growth lags Moscow but shows rising child-resistant closure procurement. Chelyabinsk's industrial converters face steepest certification delays due to distant testing laboratory access.
Russia Plastic Caps and Closures Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Russian plastic caps and closures market. Multinational suppliers with validated pharmaceutical-grade tooling networks occupy the premium tier, while domestic specialists anchor mid-market positions through regulatory compliance expertise. Regional labor-dependent molders compete on price but face material qualification barriers. Dominant competitive moves include direct-procurement relationship cultivation with large beverage bottlers and specialized tooling partnerships for hot-runner system maintenance.
Among multinational suppliers, Berry Global Inc. exemplifies the technology-leadership archetype through its access to multinational tooling networks. Safe Cap occupies a specialist position within the domestic tier, representing concentrated expertise in child-resistant and tamper-evident designs for pharmaceutical applications. Erecton LLC and PZPI LLC sit within the regional fabricator segment, serving price-sensitive beverage processors with standard screw cap configurations.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Safe Cap |
| Erecton LLC |
| PZPI LLC |
| Artpack Plastic |
| Continental Plast LLC |
| Polymir LLC |
| Plastmassa |
| Polymeric Technologies |
| Others |
Pricing and Supply Chain Analysis
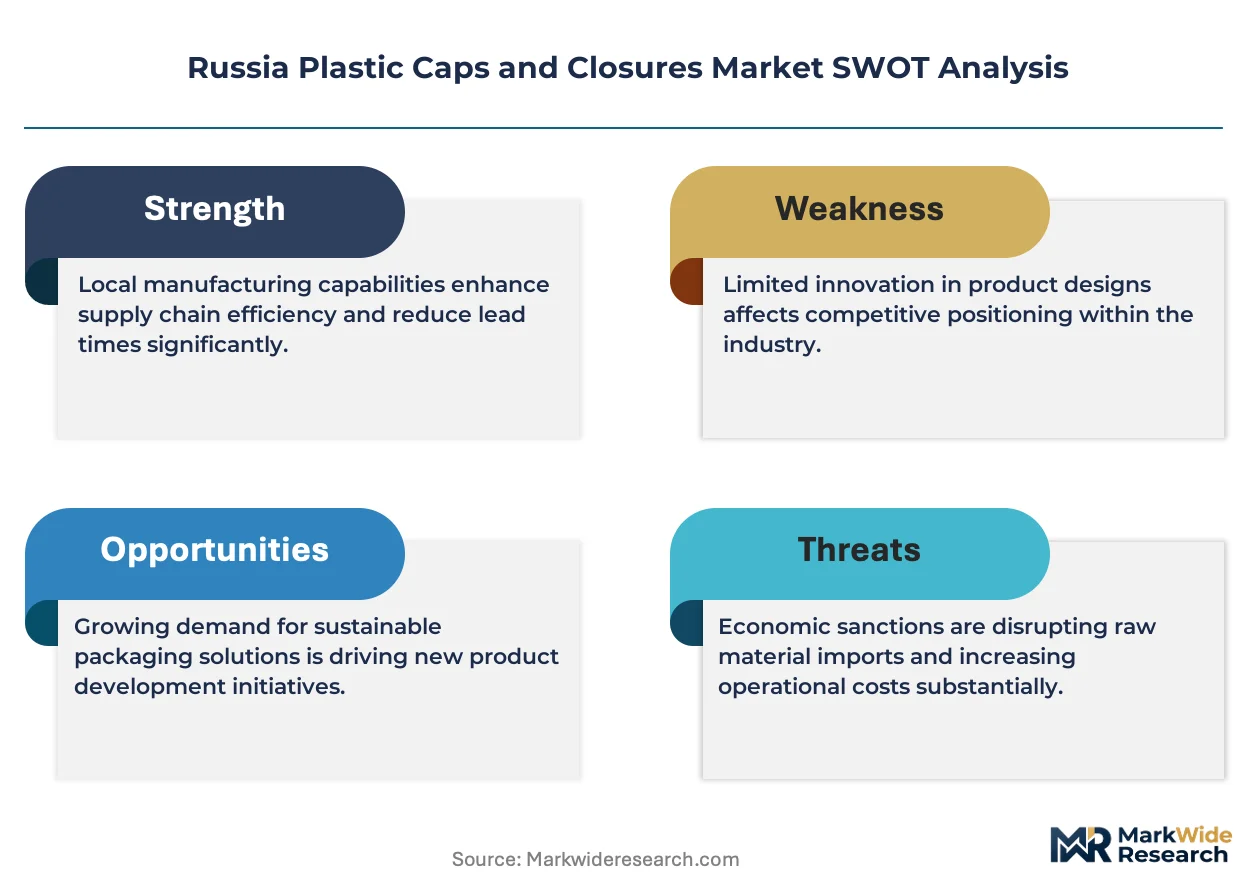
Long-term resin offtake contracts between Central Federal District converters and Kazan-based polypropylene suppliers lock in feedstock access and insulate against naphtha price spikes, while simultaneously compressing margin visibility for regional molders lacking comparable procurement scale. This contract-structure asymmetry concentrates pricing power among Moscow-area high-cavitation operators and fragments cost competitiveness across peripheral federal districts.
Pricing Analysis
Configured-to-order pricing for EAEU-certified child-resistant closures commands a substantial premium over standard 28mm beverage screw caps, with three-tier pricing structure across premium, standard, and economy levels separating pharmaceutical-grade molders from commodity converters. Certification tier and hot-runner tooling amortization represent the primary differentiation drivers, while feedstock volatility stemming from regional refinery output schedules intensifies cost compression in the economy tier. Large beverage bottlers exhibit the lowest price sensitivity due to supply security priorities, whereas agrochemical packers in the Southern Federal District demonstrate acute sensitivity to unit cost fluctuations.
Supply Chain Analysis
Germany and Austria anchor precision hot-runner tooling fabrication, while South Korea and domestic Kazan refineries supply certified polypropylene resin grades. Russian molders draw from German mold-making specialists for high-cavitation injection systems, South Korean petrochemicals for random copolymer feedstock, and Austrian auxiliary equipment for process automation. Single-source vulnerability concentrates in German tooling suppliers, where extended lead times expose converters to currency-driven capex inflation. Distribution runs through direct-procurement channels between large processors and specialized molders, displacing traditional distributor intermediaries in dairy and pharmaceutical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket tooling maintenance contracts and hot-runner system service agreements are expanding faster than hardware sales, transforming the Russia plastic caps and closures market into a service-attach opportunity where recurring technical support revenue stabilizes converter cash flows.
For Market Incumbents: Secure validated supplier status with Rospotrebnadzor by accelerating TR TS 005/2011 migration-limit testing documentation, while simultaneously building backward integration into domestic rPET purification capacity to preempt recyclate infrastructure gaps. Certification investment represents the critical defensive lever against emerging regional molders in the North Caucasus, and channel control through direct-procurement relationships with Moscow-based dairy processors defends margin position against price-competitive imports. For New Entrants and Emerging Players: Lead with precision-dose dispensing cap specialization targeting agrochemical packers in Stavropol and Krasnodar, where certified closure supply remains underdeveloped and technical collaboration appetite runs high. The Southern Federal District offers the most penetrable geography due to converter scarcity near mineral water bottling clusters, and a go-to-market angle anchored on EAEU recyclability-label compliance ahead of framework formalization unlocks early-adoption partnerships with sustainability-positioned personal care brands. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap molders with validated pharmaceutical-grade tooling networks and established Rospotrebnadzor testing partnerships, as these assets command durable pricing power across the analysis window. Acquisition targets should exhibit dual GOST R and EAEU conformity documentation capabilities, with the signal to watch being amendments to extended producer responsibility frameworks that would accelerate domestic recyclate infrastructure buildout and reshape raw material qualification economics.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Runner System Retrofit | Eliminates runner waste and reduces cycle times for Moscow-area dairy processors standardizing on 28mm neck finishes. |
| Backward Integration into rPET Purification | Addresses EAEU recyclability-label compliance gaps by securing closed-loop material sourcing ahead of infrastructure maturation. |
| Pharmaceutical Certification Investment | Accelerates TR TS 005/2011 documentation turnover for child-resistant closure specifications demanded by Moscow drug packers. |
| North Caucasus Geographic Expansion | Captures first-mover positioning among emerging mineral water bottlers in Stavropol and Krasnodar with limited certified supplier access. |
| Direct-Procurement Channel Development | Displaces distributor intermediaries by establishing technical specification relationships with large Central Federal District beverage processors. |
Research Methodology
Cross-validation between converter production data and Rospotrebnadzor certification filings anchors the qualitative findings, combining primary interviews with plant managers at Tver and Moscow oblast molding facilities, procurement leads at Central Federal District dairy processors, pharmaceutical packaging engineers, and distribution channel partners with secondary validation through customs records, Rosstandart GOST R documentation, and Eurasian Economic Commission regulatory harmonization protocols. Bottom-up capacity assessments and top-down demand aggregation from beverage bottler procurement specifications complete the triangulation.
Sensitivity analysis across resin price scenarios, tooling lead time variations, and regulatory enforcement intensity levels informs the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, material grade tier, end-use industry, application format, and federal district production cluster. CAGRs derive from compound growth trajectory analysis applied to baseline procurement volumes, with industry-specific forecast inputs incorporating hot-fill compatibility adoption curves and pharmaceutical bottling capacity expansion schedules.
Forecasts assume regulatory continuity in TR TS 005/2011 enforcement and EAEU technical regulation harmonization; material policy shifts involving extended producer responsibility framework acceleration or aromatic amine migration limit tightening would require re-modeling. Specific risk factors include feedstock price volatility from regional refinery disruptions, German tooling supplier lead time extensions, and recyclate infrastructure buildout delays. Recalibration cycles align with material shifts in Rospotrebnadzor surveillance protocols and domestic rPET purification capacity commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
PCR Closures Market
Caps and Closures
Latin America Plastic Caps and Closure Market
Caps and Closures
Dispensing Spouts Market
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
United Arab Emirates Plastic Caps and Closures Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Dauber Caps Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Case Closures and Sealers Market
Caps and Closures
China Plastic Caps and Closures Market