
 Smart Fitness Trackers Market | 2026-2036
Smart Fitness Trackers Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fitness Trackers Market Insights
GDPR's health-data portability mandates in Europe is repositioning compliance spending toward encryption and consent-management infrastructure. Apple Inc. leverages its vertically integrated ecosystem to control premium pricing and data lock-in. Garmin Ltd. anchors its position in GPS-differentiated outdoor and aviation-adjacent fitness segments. Xiaomi Corporation competes on manufacturing scale to occupy entry-level price bands across Asia and Africa.
Smart fitness trackers are wearable electronic devices incorporating accelerometers, optical heart-rate sensors, galvanic skin response electrodes, and low-power Bluetooth chipsets to capture, process, and transmit physiological and kinematic data to companion applications. Their primary commercial purpose is to enable continuous, non-invasive biometric monitoring for health optimization, athletic performance management, and clinical remote patient surveillance. Wristbands and watches together dominate hardware shipment volumes, though smart clothing represents the fastest-growing product type as textile-integrated sensor manufacturing matures. Health monitoring applications command the highest margin pools due to subscription-linked revenue models, while sports tracking remains the most penetrated application among casual users.
The FDA in the United States, the EU's Medical Device Regulation (MDR) and GDPR, and China's NMPA collectively shape market access by classifying certain predictive algorithms as regulated medical software, mandating clinical validation, and restricting cross-border health-data flows. These frameworks inflate R&D costs for entrants but protect incumbents with established quality-management systems and regulatory affairs capabilities. Stakeholders must monitor evolving software-as-medical-device classifications to determine which algorithmic features trigger premarket submission requirements versus general wellness exemptions.
Market Dynamics
Software-as-medical-device reclassification by the FDA, EMA, and NMPA is forcing manufacturers to rebuild algorithmic validation pipelines from general wellness claims toward clinical-grade evidence standards. This regulatory compression is redistributing R&D budgets toward quality-management infrastructure and away from hardware iteration cycles.
Growth Catalysts
- Corporate wellness procurement:Enterprise human-resources departments in the United States and Germany now mandate wrist-worn biometric monitoring as a condition of group health-insurance premium reductions. This institutional demand stream stabilizes volume forecasts for device OEMs.
- GDPR health-data portability:The European Union's portability mandates compel manufacturers to invest in interoperable data architectures. Compliance spending on encryption and consent-management infrastructure creates competitive moats for vendors with established European operations.
- Textile-integrated sensor maturation:Advances in conductive yarn manufacturing and washable electrode fabrication are enabling smart clothing product categories. Athletic-apparel brands in South Korea and Japan are integrating galvanic skin response and electromyography sensors directly into compression garments.
Market Restraints
- Optical sensor supply concentration:Precision photoplethysmography modules depend on a narrow base of Taiwanese and Japanese optical-component foundries. Geopolitical friction or foundry-capacity constraints transmit directly into OEM production schedules.
- Premarket submission cost inflation:FDA 510(k) and EU MDR clinical-validation requirements for arrhythmia-detection algorithms add twelve-to-eighteen-month delays and seven-figure documentation costs. This structural barrier protects incumbent quality-system investments while excluding capital-constrained entrants.
- Smartphone substitution threat:Accelerometer and gyroscope capabilities in flagship handsets now satisfy casual step-counting and basic activity-tracking use cases. Price-sensitive consumer segments in Southeast Asia and Latin America are deferring dedicated wearable purchases.
Strategic Opportunities
- Remote patient monitoring reimbursement:United States Medicare CPT codes now reimburse clinicians for continuous glucose and cardiac-rhythm data review. Algorithmic-feature roadmaps are pivoting toward diagnostic-grade outputs that qualify for these reimbursement streams.
- India's PLI scheme for electronics manufacturing:Production-linked incentive structures for wearable device assembly are attracting component suppliers to Gujarat and Tamil Nadu. Domestic brands can exploit tariff advantages and shortened logistics loops against imported competition.
- SpO2 and respiratory-rate convergence:The integration of pulse-oximetry and acoustic breathing-pattern analysis is converging with post-acute care discharge protocols. Hospital-at-home programs in Germany and the Netherlands are specifying these combined sensor stacks in procurement tenders.
Industry Challenges
- Algorithmic-bias validation:Skin-tone-dependent accuracy variation in optical heart-rate measurement requires expanded dermatological diversity in clinical-trial cohorts. Manufacturers must rebuild training datasets and statistical-analysis plans to satisfy FDA and EMA equity-review criteria.
- Cross-border data-sovereignty compliance:China's Personal Information Protection Law and the EU's GDPR impose conflicting residency and processing restrictions on physiological data. Cloud-architecture teams must engineer region-segregated storage and federated analytics pipelines.
- Battery-chemistry certification timelines:Solid-state and silicon-anode cell formats promise energy-density gains for multi-day wearables. Aviation-safety certification by the International Air Transport Association and national civil-aviation authorities delays product launches by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fitness Trackers Market |
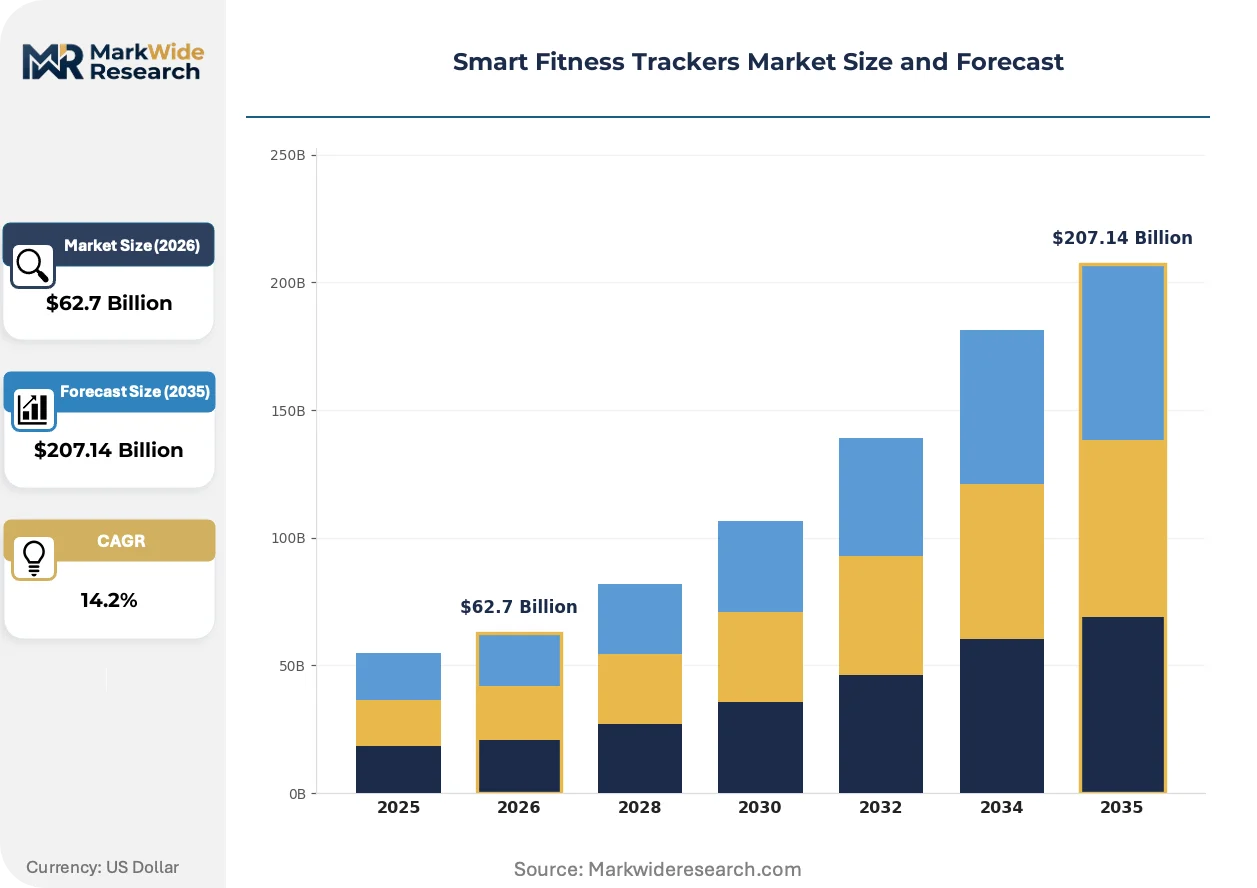
| Market Size in 2026 | $62.7 Billion |
| Market Size in 2035 | $207.14 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wristbands, Watches, Smart Clothing, Accessories Connectivity: Bluetooth, Wi-Fi, NFC, Cellular Target User: Athletes, Casual Users, Health Enthusiasts, Rehab Patients Application: Sports Tracking, Health Monitoring, Sleep Analysis, Activity Tracking |
| Companies Covered | Apple Inc., Google (Fitbit), Garmin Ltd., Samsung Electronics, Huawei Technologies, Fossil Group, Xiaomi Corporation, WHOOP, Polar Electro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fitness Trackers Market Trends and Innovations
Sensor fusion and edge-AI inference are compressing the latency between physiological signal capture and actionable health insight. These capabilities are repositioning fitness trackers from passive data loggers toward real-time clinical-decision support tools.
Photoplethysmography is converging with machine-learning arrhythmia classification to enable continuous atrial-fibrillation screening without external electrodes. Cardiology departments in the United Kingdom and Australia are piloting prescription-based device distribution for post-stroke monitoring populations. This convergence is compressing the boundary between consumer wellness and diagnostic-cardiology service lines.
The EU Medical Device Regulation's 2024 software-guidance updates are reclassifying predictive algorithms for sleep-apnea risk and hypertension estimation as Class IIa medical devices. Manufacturers must submit clinical-performance data and post-market surveillance protocols to notified bodies in Germany, the Netherlands, or Ireland. Wearables with cleared diagnostic features command reimbursement eligibility in France and Belgium that uncertified competitors cannot access.
Employer-sponsored wellness programs are consolidating procurement authority under benefits-administration platforms rather than individual HR departments. Large self-insured employers in the United States are negotiating enterprise licenses directly with device OEMs and data-analytics intermediaries. This channel compression is most visible in Fortune 500 manufacturing and technology sectors where annual biometric-screening mandates drive volume commitments.
Smart Fitness Trackers Market Segmentation
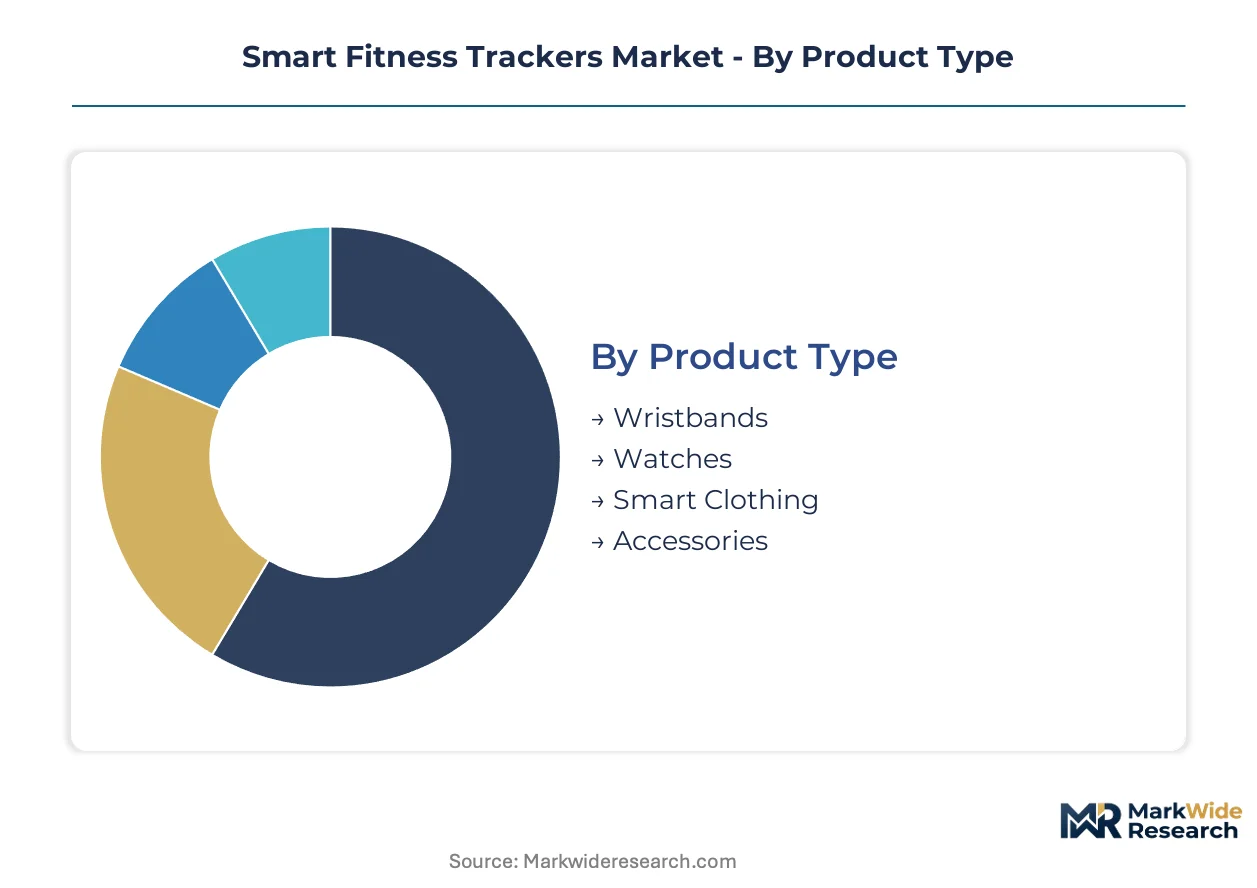
Segmentation in smart fitness trackers reflects divergent technical architectures, user sophistication levels, and reimbursement pathways. Product form factors determine sensor payload capacity and battery constraints. Connectivity specifications shape real-time clinical utility versus offline consumer convenience.
Product Type:
Standardization dominates wrist-worn formats while textile integration demands bespoke manufacturing partnerships with apparel OEMs.
- Wristbands:Slim polymer housings with single-point optical sensors and seven-day battery life. Mass-market volume concentrates in China and India where sub-$50 price points drive replacement cycles every eighteen months.
- Watches:Multi-sensor arrays combining photoplethysmography, accelerometry, and galvanic skin response in machined aluminum or composite cases. Premium procurement by corporate wellness programs in Germany and the United States favors diagnostic-grade algorithm stacks.
- Smart Clothing:Conductive yarn-integrated garments with distributed electromyography and respiratory sensors. South Korean athletic-apparel manufacturers pilot washable electrode durability above fifty cycles.
- Accessories:Chest straps, clip-on pods, and shoe-mounted kinematic sensors serving niche cycling and swimming segments. Garmin and Polar retain loyalist bases in triathlon training cohorts.
Leading the category by volume: Wristbands. Expanding most quickly: Smart Clothing.
Connectivity:
Hardware BOM cost scales directly with radio complexity, creating four distinct procurement tiers across consumer and clinical channels.
- Bluetooth:Low-energy 5.3 chipsets enabling smartphone-tethered data sync with sub-10mW power draw. Casual users in Southeast Asia and Latin America accept this dependency to avoid subscription fees.
- Wi-Fi:Direct cloud upload capability for overnight sleep-data transmission without phone proximity. Health enthusiasts in suburban United States markets favor this for uninterrupted biometric logging.
- NFC:Contactless payment and access-control integration in enterprise wellness deployments. German automotive manufacturers specify NFC for plant-floor security compliance.
- Cellular:Independent LTE-M or NB-IoT radios enabling remote patient monitoring without smartphone intermediation. Medicare-reimbursed cardiac-rhythm surveillance in the United States mandates this architecture for elderly populations.
Dominant by shipment share: Bluetooth. Steepest expansion trajectory: Cellular.
Target User:
User sophistication determines algorithm accuracy requirements, subscription willingness, and regulatory classification thresholds.
- Athletes:Power-output, lactate-threshold, and recovery-score metrics demanding medical-grade heart-rate variability precision. Triathlon and ultramarathon segments in Australia and Switzerland drive premium pricing tolerance above $400.
- Casual Users:Step-counting and calorie-estimation functions served by basic accelerometry. Price-sensitive segments in Indonesia and Nigeria defer purchase when smartphone sensors suffice.
- Health Enthusiasts:Sleep-stage scoring, stress-index tracking, and Vo2 max estimation with FDA-cleared algorithm preferences. Self-quantification communities in the Netherlands and Denmark sustain subscription attach rates above 40%.
- Rehab Patients:Post-acute care discharge monitoring with prescribed adherence protocols. Hospital-at-home programs in Germany and the Netherlands specify SpO2 and respiratory-rate convergence in procurement tenders.
Largest installed base: Casual Users. Fastest-growing reimbursement eligibility: Rehab Patients.
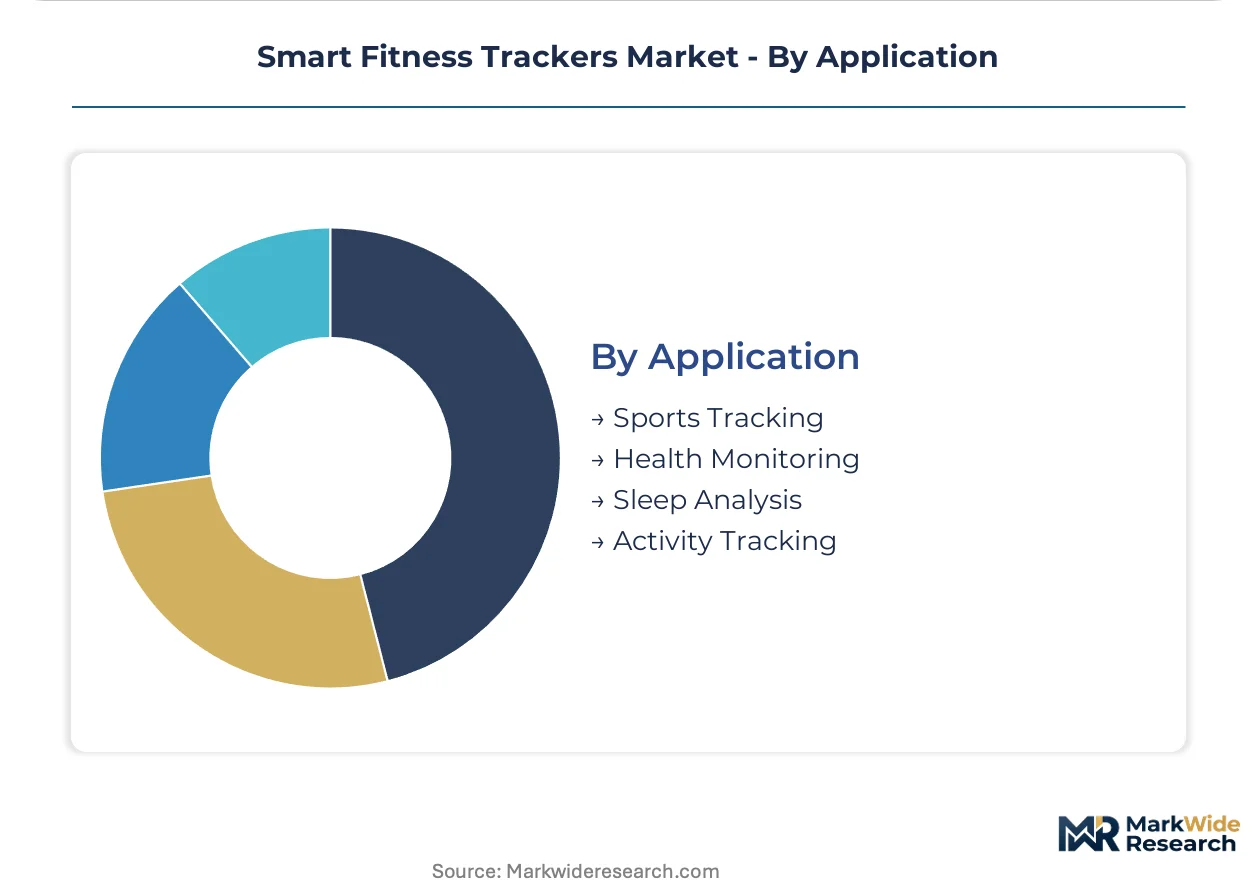
Application:
Margin pools diverge sharply between one-time hardware sales and recurring subscription revenue tied to clinical-grade outputs.
- Sports Tracking:GPS-differentiated route mapping, pace analytics, and segment benchmarking for running and cycling. Garmin anchors this segment with aviation-hardened positioning accuracy.
- Health Monitoring:Continuous glucose, blood-pressure estimation, and atrial-fibrillation screening triggering software-as-medical-device classification. FDA 510(k) clearance in the United States unlocks Medicare CPT code reimbursement.
- Sleep Analysis:Actigraphy-based stage scoring and apnea-risk flagging reclassified as Class IIa medical devices under EU MDR 2024 guidance. French and Belgian reimbursement eligibility now requires notified-body certification.
- Activity Tracking:Basal step-counting and sedentary-alert functions commoditized by smartphone sensor convergence. Southeast Asian and Latin American volume is compressing as handset capabilities improve.
Highest penetration: Activity Tracking. Greatest margin expansion: Health Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates mass-market procurement volume through domestic brands exploiting manufacturing scale and price-performance ratios. Enterprise wellness mandates in Germany and reimbursement pathways in the United States reshape demand geography.
China
Domestic OEMs capture replacement cycles through sub-$50 wristbands targeting price-sensitive consumers in tier-two and tier-three cities. NMPA software-as-medical-device guidance compels algorithm revalidation for predictive health features. Shenzhen and Dongguan clusters host vertically integrated optical sensor and Bluetooth chipset assembly operations serving export markets.
United States
Medicare CPT code reimbursement for remote cardiac-rhythm monitoring drives cellular-enabled device procurement for elderly populations. FDA 510(k) premarket submissions impose twelve-to-eighteen-month delays and seven-figure documentation costs on arrhythmia-detection algorithms. Austin and Boston corridors concentrate digital-health startups engineering diagnostic-grade sensor fusion.
Germany
Automotive and manufacturing sectors mandate NFC-integrated wearables for plant-floor security compliance within corporate wellness frameworks. EU MDR 2024 software guidance reclassifies sleep-apnea risk algorithms as Class IIa medical devices requiring notified-body certification. Bavaria and Baden-Württemberg host precision-optics suppliers feeding photoplethysmography module production.
India
Production-linked incentive schemes for electronics assembly attract component suppliers to Gujarat and Tamil Nadu manufacturing zones. BIS certification requirements and tariff structures favor domestic brands against imported competition. Bangalore and Hyderabad clusters incubate wearable-software startups targeting health-insurance partnerships.
South Korea
Athletic-apparel manufacturers pilot textile-integrated electromyography sensors in compression garments for fifty-plus wash cycles. MFDS medical-device classification for predictive algorithms aligns with EU MDR standards, streamlining export compliance. Seoul-Incheon corridor anchors conductive-yarn R&D partnerships between textile mills and sensor foundries.
Smart Fitness Trackers Market Competitive Landscape
United States and Chinese producers anchor the premium and mass-market tiers respectively; European specialists hold differentiated outdoor and clinical segments. The vendor base stratifies across three archetypes: vertically integrated ecosystem operators, GPS-differentiated performance specialists, and manufacturing-scale value players. Dominant competitive moves include algorithmic validation pipeline investments for software-as-medical-device clearance and textile-integration partnerships with athletic-apparel OEMs.
Within the premium ecosystem tier, Apple Inc. exemplifies vertical control over hardware-software-data integration. Garmin Ltd. and Polar Electro occupy positions among GPS-differentiated specialists serving athletic and aviation-adjacent segments. Xiaomi Corporation anchors the manufacturing-scale archetype competing on cost structure across Asia and Africa.
| Leading Market Players |
|---|
| Apple Inc. |
| Google (Fitbit) |
| Garmin Ltd. |
| Samsung Electronics |
| Huawei Technologies |
| Fossil Group |
| Xiaomi Corporation |
| WHOOP |
| Polar Electro |
| Others |
Pricing and Supply Chain Analysis
Corporate wellness procurement mandates in Germany and the United States are compressing supplier margins by demanding diagnostic-grade algorithm stacks at volume-contract pricing, forcing OEMs to absorb FDA validation costs while maintaining sub-$200 unit economics for enterprise tenders.
Pricing Analysis
Volume-mass wristbands in China and India trade at sub-$50 price points with replacement cycles every eighteen months, while premium watches with FDA-cleared arrhythmia detection command three-to-four-fold premiums through Medicare reimbursement eligibility in the United States. Certification tier serves as the primary price differentiation driver, separating uncertified wellness devices from Class IIa medical devices under EU MDR guidance. Pricing pressure stems from smartphone sensor convergence displacing casual activity-tracking purchases in Southeast Asia and Latin America. Casual users in Indonesia and Nigeria exhibit extreme price sensitivity, deferring dedicated wearable purchases when handset accelerometers suffice, whereas health enthusiasts in the Netherlands and Denmark sustain subscription attach rates above 40% with minimal elasticity.
Supply Chain Analysis
Photoplethysmography module supply rests on Taiwanese and Japanese optical-component foundries, with precision sensor manufacturing concentrated in Hsinchu Science Park and Kyoto precision-optics clusters. Raw material dependencies span gallium arsenide wafers, specialized polymer housings, and low-power Bluetooth chipsets. Single-source vulnerability in Taiwanese foundry capacity transmits directly into OEM production schedules during geopolitical friction or capacity constraints. Distribution runs through enterprise benefits-administration platforms in the United States, direct-to-consumer e-commerce channels in China, and carrier retail partnerships for cellular-enabled devices targeting Medicare populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photoplethysmography foundry capacity constraints in Taiwan and Japan are propping hardware pricing, creating a supply-constrained market where algorithmic validation capabilities determine procurement access more than manufacturing scale alone.
For Market Incumbents: To counter smartphone sensor substitution in Southeast Asian and Latin American casual segments, anchor defensive positioning through backward integration into optical sensor design and exclusive enterprise wellness platform partnerships. Prioritize FDA 510(k) pipeline investments for arrhythmia-detection features that unlock Medicare reimbursement eligibility, creating contractual switching costs against lower-tier competitors lacking quality-system infrastructure. For New Entrants and Emerging Players: Hospital-at-home procurement channels in Germany and the Netherlands offer the most penetrable entry vector, targeting SpO2 and respiratory-rate convergence specifications in post-acute care tenders. India's PLI scheme for electronics assembly enables tariff-advantaged domestic production against imported competition. Pursue white-label partnerships with South Korean textile manufacturers to accelerate smart clothing commercialization without captive sensor foundry investments. For Investors and Strategic Acquirers: The window for entry favors algorithmic-validation specialists with cleared diagnostic pipelines over hardware-assemblers facing commoditization pressure. Long-term viability centers on software-as-medical-device clearance portfolios rather than unit shipment volumes. Watch FDA software guidance expansion beyond arrhythmia to sleep-apnea and hypertension estimation as the inflection signal for reimbursement pathway widening.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Unlocks Medicare CPT code reimbursement for continuous cardiac-rhythm monitoring in elderly populations. |
| EU MDR Class IIa Certification | Enables French and Belgian reimbursement eligibility for sleep-apnea risk algorithms under notified-body oversight. |
| Textile-Integration Partnership | Positions wearable OEMs within South Korean athletic-apparel supply chains for washable electrode durability. |
| Enterprise Wellness Platform Integration | Consolidates procurement authority under benefits-administration intermediaries in Fortune 500 manufacturing sectors. |
| Cellular-Enabled Architecture Deployment | Satisfies Medicare mandates for independent remote patient monitoring without smartphone intermediation. |
Research Methodology
Multi-period observation of FDA 510(k) submission volumes, EU MDR notified-body certification timelines, and enterprise wellness procurement contract awards anchored the trend analysis, supplemented by interviews with digital-health regulatory affairs directors, biomedical engineering leads at hospital systems, optical sensor foundry operations managers, and benefits-administration platform procurement officers. Secondary validation drew from FDA 510(k) databases, EU MDR notified-body registers, CMS Medicare reimbursement code filings, and customs trade records for photoplethysmography module shipments. Bottom-up shipment estimates by product form factor triangulated against top-down value projections across connectivity tiers and target user segments.
Segment-weighting approaches modeled wristbands, watches, smart clothing, and accessories separately by sensor payload capacity and battery constraints, with connectivity specifications treated as distinct procurement tiers reflecting radio complexity BOM costs. Geographic clusters were weighted by reimbursement pathway maturity and manufacturing incentive structures. CAGRs were derived from regression analysis of historical shipment trajectories against regulatory event timing and enterprise procurement cycle data, incorporating algorithmic revalidation cost inflation and textile-integration yield improvement assumptions.
Several conditions sit outside the modeled scope, including geopolitical disruption of Taiwanese foundry operations, aviation-safety certification delays for solid-state battery formats, and unannounced FDA software-as-medical-device reclassifications. Forecasts reflect documented assumptions regarding reimbursement code expansion timelines and PLI scheme continuity in India. A small set of named triggers warrants ongoing watch: FDA guidance updates on hypertension estimation algorithms, EU MDR 2024 sleep-apnea classification enforcement patterns, and NMPA cross-border data-sovereignty rulings affecting cloud architecture requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
Breathing Wear Market
Wearable Fitness Technology
Wearable Devices Market
Wearable Fitness Technology
Smart Wearable Gloves Market
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Sports Headbands Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market
Wearable Fitness Technology
Wearable Sensors Market
Wearable Fitness Technology
Wearable Motion Sensors Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Australia Wearables Market